
 Foot Care Products Market | 2026-2036
Foot Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Foot Care Products Market Analysis
China is tilting toward expanded domestic manufacturing of silicone-based insoles and exfoliating foot creams for regional export. Johnson & Johnson leverages its pharmaceutical heritage to sustain credibility in medicated foot care formulations across North American pharmacy channels. GlaxoSmithKline plc anchors its position through specialty dermatology R&D pipelines that address fungal and cracked-heel indications. Reckitt Benckiser Group Plc competes aggressively in mass-market hygiene segments with broad retail distribution networks.
Foot care products encompass topical formulations, mechanical supports, and electronic devices engineered to maintain epidermal integrity, redistribute plantar pressure, or alleviate musculoskeletal discomfort. Silicone gel insoles typically incorporate viscoelastic polymers with shore hardness between 15 and 30 A, molded to custom arch profiles via CAD-CAM orthotic workflows. Orthotic Devices command the deepest margin pools due to prescription-grade customization and podiatrist-channel gatekeeping, while Online Retail represents the fastest-growing distribution vector as telehealth referrals and direct-to-consumer brands bypass traditional pharmacy intermediaries. Foot Creams remain the most mature product category, with formulation innovation now concentrating on urea concentrations and ceramide complexes for diabetic skin.
FDA 510(k) pathways govern medical-grade insoles and orthotic devices in the United States, requiring biomechanical efficacy documentation that elevates barriers for unvalidated imports. The EU Medical Device Regulation (MDR) reclassifies certain active foot-care electronics, compelling manufacturers to renew technical files and clinical evidence under stricter notified body oversight. REACH compliance constrains preservative and fragrance chemistries in European topical formulations, redirecting R&D toward biobased emollients. Stakeholders must monitor evolving reimbursement codes for preventive podiatry, as coverage expansion would restructure volume toward clinical channels and away from purely cosmetic positioning.
Market Dynamics
Podiatrists integrating therapeutic insoles into diabetic treatment protocols are restructuring channel economics, compressing retail margins while elevating prescription-grade orthotics to gatekept medical devices requiring clinical validation.
Growth Catalysts
- Germany's Statutory Health Insurance Reimbursement:Custom orthotics coverage mandates drive consistent prescription volume, anchoring manufacturer investment in CAD-CAM production workflows.
- FDA 510(k) Streamlining:Class I medical device clearance pathways reduce time-to-market for biomechanical insoles, accelerating commercialization of pressure-redistribution technologies in the United States.
- Silicone Gel Viscoelastic Polymers:Shore hardness tunability between 15 and 30 A enables mass-customization of arch profiles, matching individualized plantar pressure mapping outputs.
Market Restraints
- EU MDR Reclassification Friction:Active foot-care electronics now require renewed technical files and stricter notified body oversight, extending compliance timelines and elevating documentation costs.
- REACH Preservative Constraints:European fragrance and biocide restrictions redirect R&D toward unproven biobased emollients, destabilizing established formulation supply chains.
- Import Validation Barriers:Unvalidated offshore insoles face elevated FDA biomechanical efficacy documentation requirements, limiting price-competitive Asian manufacturing penetration.
Strategic Opportunities
- Telehealth Referral Channels:Direct-to-consumer brands bypassing pharmacy intermediaries capture diabetic patient segments previously gatekept by podiatrist offices, restructuring last-mile distribution.
- China Domestic Manufacturing Expansion:Silicone-based insole and exfoliating cream production for regional export concentrates supply chain control within Asia-Pacific manufacturing clusters.
- Ceramide Complex Formulation Innovation:Urea concentration advances in diabetic skin creams address underpenetrated preventive care segments, opening reimbursement-adjacent positioning.
Industry Challenges
- Biomechanical Efficacy Documentation Talent Scarcity:Clinical validation expertise for FDA 510(k) submissions concentrates in specialized CROs, elongating hiring cycles for in-house regulatory functions.
- CAD-CAM Workflow Integration Complexity:Legacy orthotic laboratories face capex intensity in digitizing plaster-cast workflows, compressing margins during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot Care Products Market |
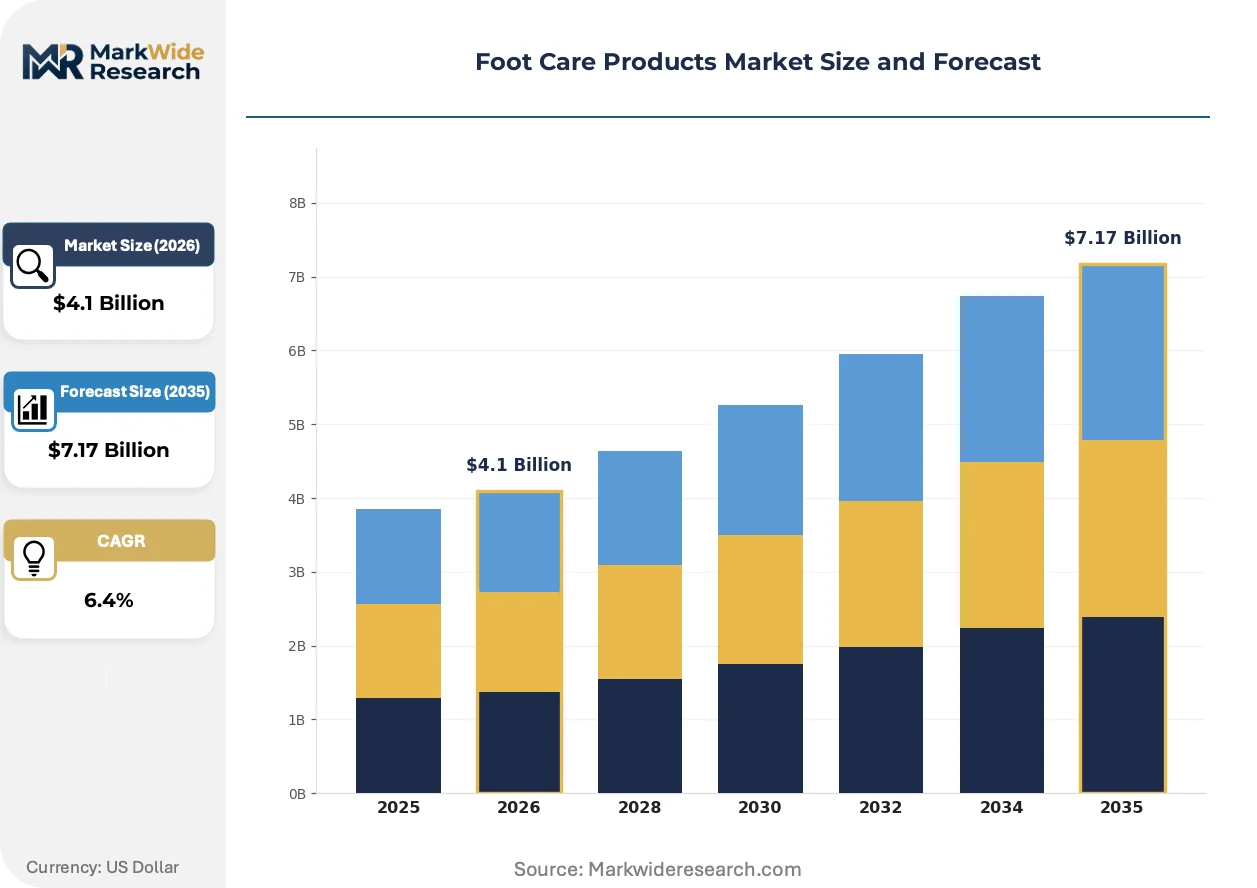
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foot Creams, Insoles, Orthotic Devices, Sprays End User: Retail Consumers, Healthcare Providers, Athletes, Elderly Application: Moisturizing, Pain Relief, Prevention, Hygiene Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | GlaxoSmithKline plc, Aetrex Worldwide Inc., Johnson & Johnson, PediFix Inc., Alva-Amco Pharmacal Companies, Inc., Reckitt Benckiser Group Plc, Scholl's Wellness Co., HoMedics USA LLC, Revlon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot Care Products Market Emerging Trajectories
Convergence between pressure-sensing electronics and viscoelastic materials is redefining product boundaries, while regulatory reclassification and channel disintermediation simultaneously compress traditional competitive moats.
Smart insole technology is hybridizing capacitive pressure mapping with thermoplastic polyurethane substrates to enable real-time gait analysis. Podiatry clinics and sports medicine practices are piloting these systems for diabetic ulcer prevention and athletic biomechanical optimization. The technology is hybridizing hardware and service revenue models, forcing legacy insole manufacturers to develop software competencies or cede high-margin segments to digital-native entrants.
REACH compliance is constraining preservative chemistries in European topical foot care, compelling manufacturers to reformulate around biobased emollients and natural antimicrobial agents. Industrial consequence includes extended stability testing timelines and supplier qualification burdens for fragrance houses. Foot cream manufacturers serving Germany and France are responding by vertically integrating emollient sourcing to secure supply chain predictability.
Buyer concentration among telehealth-enabled diabetic patients is fragmenting traditional pharmacy channel control over foot care product access. Direct-to-consumer brands leveraging podiatrist video consultations are displacing retail shelf-space dependence with subscription-based orthotic replenishment. This pattern is most visible in the United States, where high-deductible health plans accelerate price-transparent purchasing decisions outside insurance networks.
Foot Care Products Market Segmentation
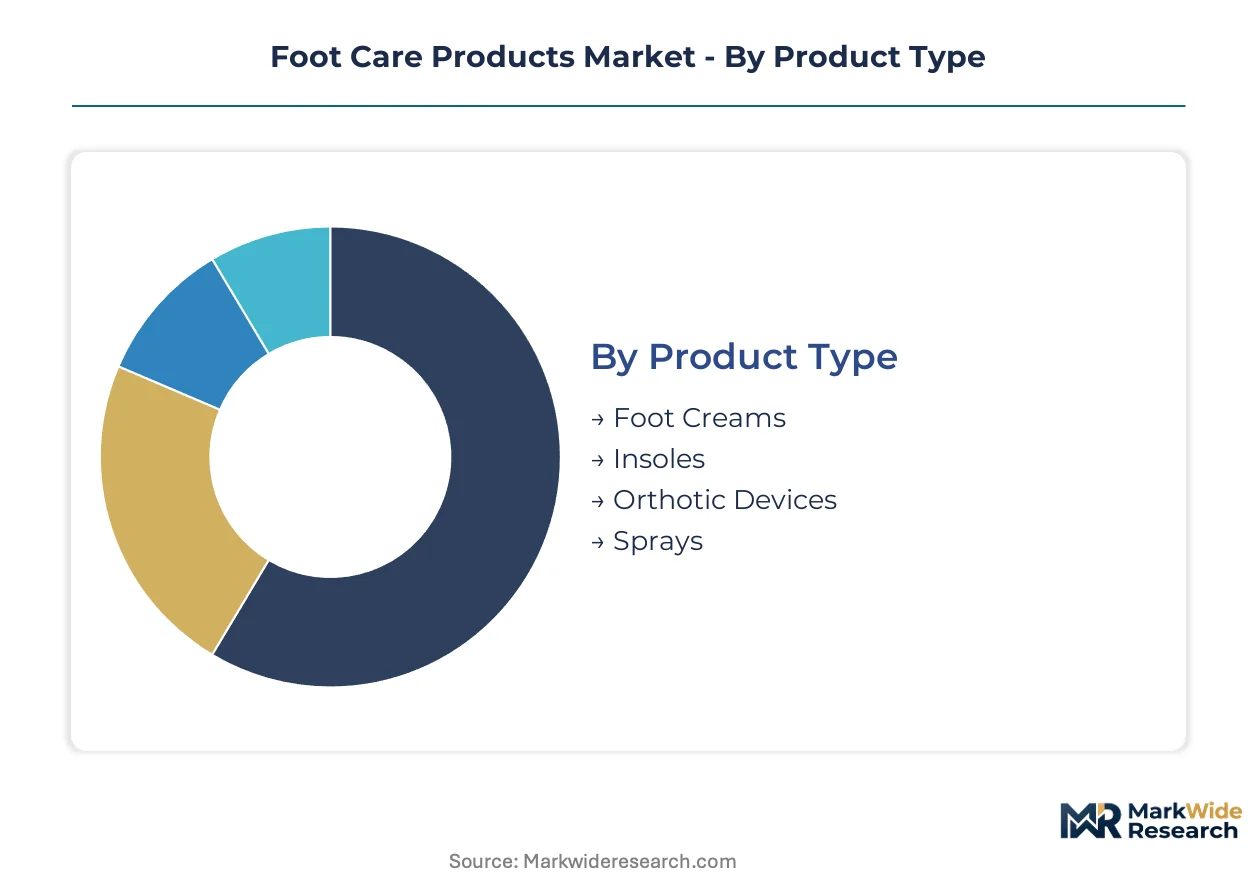
Product differentiation in foot care spans therapeutic efficacy tiers, channel gatekeeping intensity, and reimbursement eligibility. Segmentation reveals where margin pools concentrate versus where volume scales fastest.
Product Type:
Mature categories dominate shelf space while emerging technologies capture premium positioning.
- Orthotic Devices:CAD-CAM manufactured supports with shore hardness between 15 and 30 A redistribute plantar pressure for diabetic patients. Germany's statutory health insurance reimbursement anchors prescription volume, compressing retail-accessible alternatives.
- Foot Creams:Urea and ceramide complex formulations address epidermal integrity in diabetic skin. REACH compliance in Europe redirects R&D toward biobased emollients, destabilizing legacy preservative supply chains.
- Insoles:Silicone gel viscoelastic polymers enable mass-customization through pressure mapping workflows.
- Sprays:Antifungal and deodorizing formulations compete in hygiene segments with lower clinical validation barriers.
Foot Creams retain volume leadership; Orthotic Devices hold the steepest expansion curve.
End User:
Customer type determines channel economics and price transparency expectations.
- Healthcare Providers:Podiatrists gatekeep prescription-grade orthotics through biomechanical assessment protocols. FDA 510(k) documentation requirements elevate barriers for unvalidated device imports.
- Elderly:Diabetic patient segments drive preventive foot care adoption as Medicare Advantage plans expand podiatry coverage.
- Retail Consumers:High-deductible health plan holders accelerate price-transparent purchasing outside insurance networks.
- Athletes:Sports medicine practices pilot pressure-sensing insoles for biomechanical optimization.
Healthcare Providers command premium pricing power; Elderly segments gain share fastest through reimbursement expansion.
Application:
Functional positioning separates cosmetic from reimbursable product categories.
- Prevention:Diabetic ulcer prevention protocols integrate therapeutic insoles as standard care, restructuring volume toward clinical channels.
- Pain Relief:Viscoelastic materials address musculoskeletal discomfort through pressure redistribution mechanics.
- Moisturizing:Urea concentration advances target diabetic skin pathologies.
- Hygiene:Mass-market deodorizing and antifungal applications compete on retail shelf space and brand recognition.
Prevention commands the deepest margins; Pain Relief applications scale fastest through sports medicine adoption.
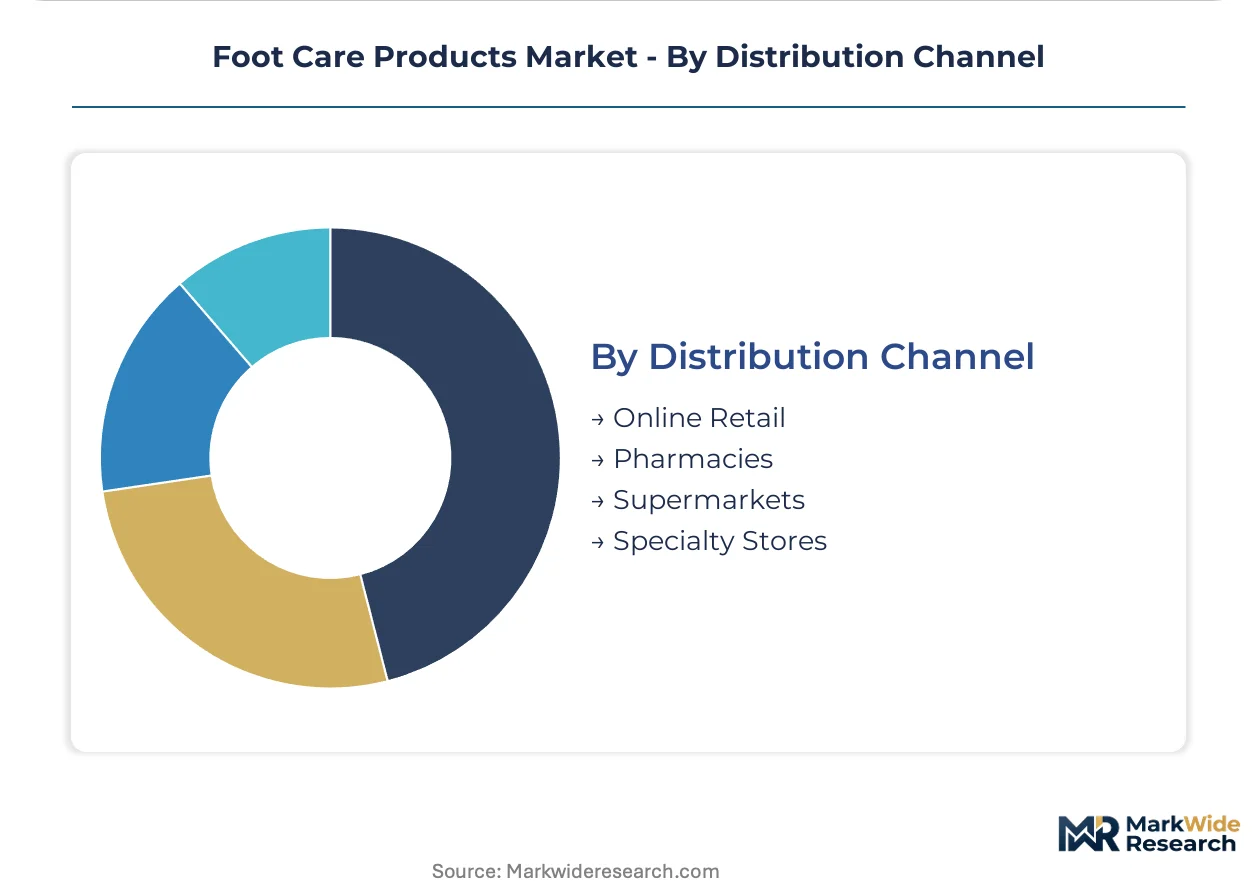
Distribution Channel:
Channel selection determines customer acquisition cost and subscription revenue potential.
- Online Retail:Telehealth referrals and direct-to-consumer brands bypass pharmacy intermediaries with subscription-based orthotic replenishment.
- Pharmacies:Medicated foot care formulations leverage Johnson & Johnson's credibility in North American pharmacy channels.
- Specialty Stores:Custom fitting services for athletic and medical-grade products concentrate in urban podiatry clusters.
- Supermarkets:Mass-market hygiene products compete on price and impulse placement.
Pharmacies retain volume leadership; Online Retail climbs the fastest through telehealth integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor commercialization velocity in the United States, while Germany's statutory health insurance reimbursement and China's manufacturing expansion reshape regional competitive positioning across the forecast window.
United States
Podiatrist-channel gatekeeping of prescription-grade orthotics and Medicare Advantage diabetic coverage expansion concentrate demand in clinical settings. FDA 510(k) documentation requirements for Class I medical devices elevate barriers for unvalidated imports. Boston and Minneapolis medical device clusters host CAD-CAM orthotic laboratories digitizing plaster-cast workflows.
Germany
Statutory health insurance reimbursement mandates for custom orthotics drive consistent prescription volume through podiatry clinics. EU MDR reclassification of active foot-care electronics compels manufacturers to renew technical files under stricter notified body oversight. The Ruhr Valley and Bavaria host precision polymer processing facilities supplying silicone gel viscoelastic components.
China
Domestic manufacturing of silicone-based insoles and exfoliating foot creams accelerates for regional export concentration. NMPA medical device registration requirements apply to pressure-sensing orthotic electronics entering clinical channels. The Yangtze River Delta manufacturing belt concentrates injection-molding capacity for shore-hardness-tuned polymer substrates.
United Kingdom
NHS podiatry referral pathways and high-deductible health plan penetration fragment channel control between clinical and direct-to-consumer vectors. REACH compliance constrains preservative chemistries in topical formulations, redirecting R&D toward biobased emollients. London and Manchester house formulation laboratories serving diabetic skin care segments.
Japan
Aging demographics and diabetic patient preventive care protocols expand therapeutic insole adoption through podiatry clinics. PMDA medical device classification governs pressure-redistribution orthotics requiring biomechanical efficacy documentation. The Kanto region around Tokyo concentrates sports medicine practices piloting pressure-sensing insole systems for gait analysis.
Foot Care Products Market Vendor Landscape
Pharmaceutical heritage players and consumer health specialists split the market across prescription-grade and mass-access channels. Consolidation concentrates around podiatrist-gatekept orthotics with steep documentation barriers, while mass-market hygiene segments fragment across retail shelf-space competitors. Three archetypes dominate: legacy pharmaceutical formulators leveraging dermatology R&D credibility, direct-to-consumer digital natives bypassing pharmacy intermediaries, and precision polymer processors with CAD-CAM customization capabilities. Competitive moves center on telehealth referral channel construction and backward integration into emollient supply chains.
Within the pharmaceutical heritage tier, GlaxoSmithKline plc and Johnson & Johnson occupy positions anchored by dermatology R&D pipelines and North American pharmacy channel credibility. Reckitt Benckiser Group Plc exemplifies the mass-market hygiene specialist archetype with broad retail distribution networks. These three entities represent contrasting strategic vectors: prescription-adjacent clinical validation, pharmacy-channel medicated formulations, and mass-market brand recognition competing on shelf-space velocity rather than podiatrist gatekeeping.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Aetrex Worldwide Inc. |
| Johnson & Johnson |
| PediFix Inc. |
| Alva-Amco Pharmacal Companies, Inc. |
| Reckitt Benckiser Group Plc |
| Scholl's Wellness Co. |
| HoMedics USA LLC |
| Revlon Inc. |
| Others |
Supply Flow & Price Mechanics
Germany's statutory health insurance reimbursement mandates anchor premium pricing for prescription-grade orthotics, while Asian manufacturing clusters compete on cost for retail-accessible silicone gel insoles. CAD-CAM production workflows concentrate margin capture with podiatrist-gatekept medical devices, leaving mass-market hygiene products to absorb commodity polymer pricing volatility.
Pricing Analysis
Geographic price spreads separate German reimbursement-backed custom orthotics from direct-to-consumer Asian imports. Three-tier pricing structure across prescription-grade, pharmacy-channel, and mass-retail levels reflects certification intensity and clinical validation depth. Pricing pressure stems from telehealth brands bypassing traditional pharmacy intermediaries with subscription models. Retail consumers under high-deductible health plans exhibit highest price sensitivity; podiatry clinics show lowest sensitivity due to insurance coverage anchoring.
Supply Chain Analysis
Contract manufacturing for silicone gel viscoelastic polymers concentrates in China's Yangtze River Delta and Germany's Ruhr Valley polymer processing facilities. Raw material dependencies include medical-grade silicone elastomers, thermoplastic polyurethane substrates, and biobased emollient feedstocks. Single-source vulnerability runs through specialized CAD-CAM software licensors controlling orthotic design workflows. Distribution runs through podiatry clinics for prescription devices, pharmacy chains for medicated formulations, and direct-to-consumer platforms for replenishment subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as telehealth referrals disintermediate traditional pharmacy gatekeepers and split demand across clinical, retail, and direct-to-consumer channels.
For Market Incumbents: Pre-empt digital-native entrants by acquiring telehealth referral platform capabilities or building proprietary podiatrist video consultation networks. Backward integration into medical-grade silicone polymer sourcing secures supply predictability against REACH-driven emollient reformulation disruptions. Priority defensive moves center on CAD-CAM workflow patent thickets and exclusive GPO contracts with hospital systems. For New Entrants and Emerging Players: Build out ceramic-complex foot cream formulations targeting diabetic skin segments adjacent to reimbursable podiatry protocols. White-space concentration sits with pressure-sensing insole electronics hybridizing hardware and software revenue models. Go-to-market leverage comes through sports medicine practice partnerships piloting real-time gait analysis systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision polymer processors possessing CAD-CAM customization infrastructure but lacking telehealth channel integration. Long-term viability favors targets bridging clinical validation expertise with direct-to-consumer subscription mechanics. Watch FDA 510(k) clearance velocity for active foot-care electronics as inflection signal for reimbursement code expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Podiatrist video consultations bypass pharmacy intermediaries and capture diabetic patient segments. |
| Backward Integration into Silicone Supply | Captive polymer sourcing insulates against REACH preservative constraints and biobased emollient volatility. |
| Pressure-Sensing Hardware Development | Capacitive gait analysis systems open service revenue streams beyond commoditized insole units. |
| CAD-CAM Workflow Digitization | Legacy orthotic laboratories reduce plaster-cast labor intensity and compress production cycle times. |
| Ceramide Complex R&D Investment | Urea concentration advances address underpenetrated diabetic skin care adjacent to clinical channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with podiatrists, biomedical engineers, pharmacy category buyers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and customs trade records. Bottom-up triangulation across product-level volume estimates and top-down macroeconomic anchoring ensured convergence.
Forecast inputs span product type segmentation across orthotic devices, foot creams, insoles, and sprays; end-user stratification between healthcare providers, elderly diabetic patients, retail consumers, and athletes; and distribution channel dynamics spanning online retail, pharmacies, specialty stores, and supermarkets. CAGRs were derived from regression analysis against diabetic population growth curves, reimbursement code expansion patterns, and telehealth adoption trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native direct-to-consumer brands or rapid FDA clearance acceleration for active electronics would shift outcomes. Quarterly review of telehealth referral volume, 510(k) submission velocity, and statutory insurance reimbursement code updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Personal Lubricants Market