
 Personal Lubricants Market | 2026-2036
Personal Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Lubricants Market Intelligence
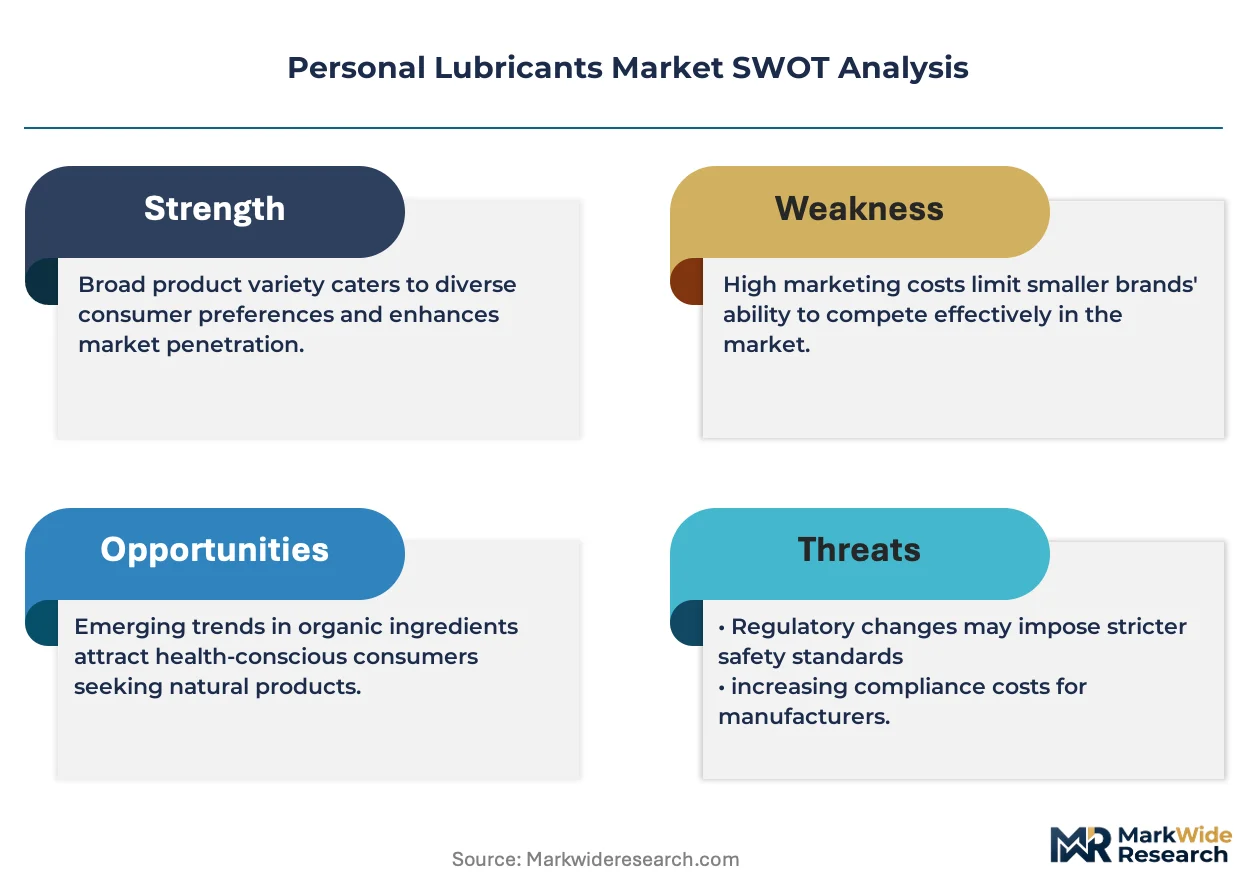
A widening capital-intensity gap between formulation-heavy innovators and packaging-focused assemblers is reorganizing competitive tiers in personal lubricants. BioFilm Inc. leverages its manufacturing scale to sustain cost advantages across water-based production lines. Reckitt Benckiser Group plc anchors its position through brand strength and pharmacy channel control in developed markets. Church & Dwight Co., Inc. differentiates via R&D intensity in pH-balanced and sensitive-skin formulations.
Personal lubricants comprise viscous gel or liquid preparations formulated with water, silicone, or oil bases to reduce friction during intimate contact or clinical procedures, with osmolality and pH specifications typically engineered between 3.8 and 4.5 to maintain mucosal compatibility. Water-based formulations dominate volume due to broad compatibility with latex barriers and easy cleanup, while silicone-based variants command premium positioning for extended-duration applications. The organic formulation segment is attracting reformulation investment as clean-label procurement shifts among sexual wellness retailers, and clinical-use applications are expanding through urology and gynecology practice integrations.
The FDA regulates personal lubricants as Class II medical devices in the United States, requiring 510(k) clearance for clinical claims, while the EU Medical Device Regulation imposes biocompatibility testing standards through notified body oversight. Health Canada and the TGA enforce comparable pre-market safety frameworks, creating compliance complexity for multi-territory launches. Stakeholders must monitor evolving classification debates between cosmetic and medical device designations, as regulatory reclassification would fundamentally reshape testing burdens and market access timelines.
Market Dynamics
Clean-label procurement standards are forcing a bifurcation between formulation-heavy innovators capable of organic certification and commodity assemblers dependent on synthetic bases. This structural tension is compressing margins for mid-tier producers while concentrating volume among vertically integrated compounders.
Growth Catalysts
- FDA 510(k) pathway expansion:Streamlined medical device clearance for clinical-grade lubricants is opening urology and gynecology practice channels in the United States, creating institutional procurement pipelines distinct from retail.
- Japan METI wellness initiative:Government-backed sexual health destigmatization campaigns are normalizing lubricant retail placement in pharmacies and convenience stores, broadening demographic access beyond traditional specialty outlets.
- Plant-derived hyaluronic acid:Biotechnology advances in fermentation-based humectant production are enabling organic formulations with performance parity to synthetic glycerin bases, satisfying clean-label requirements without efficacy trade-offs.
Market Restraints
- Silicone feedstock concentration:Dimethicone and cyclomethanol supply chains cluster in Chinese and German chemical manufacturing hubs, exposing premium lubricant producers to input volatility from energy price shocks.
- EU MDR testing burdens:Biocompatibility and cytotoxicity validation requirements for medical device classification impose six-to-eighteen month pre-market timelines that cosmetic-classified competitors bypass entirely.
- Natural oil substitution threat:Coconut and almond oil household products compete directly with commercial lubricants in price-sensitive segments, particularly where latex compatibility concerns remain undereducated.
Strategic Opportunities
- German pharmacy channel integration:Apotheken networks remain underpenetrated for sexual wellness relative to other personal care categories, presenting first-mover advantages for clinical-positioned brands with BfArM-compliant documentation.
- Telehealth prescription bundling:Direct-to-patient platforms for menopause and erectile dysfunction management are creating embedded lubricant distribution opportunities through integrated treatment protocols.
- pH-matched prebiotic formulations:Convergence of microbiome science and intimate care is enabling differentiated positioning around vaginal flora preservation, commanding premium pricing in sensitive-skin segments.
Industry Challenges
- Cosmetic-chemical regulatory ambiguity:Divergent classification interpretations between FDA district offices and EU notified bodies create compliance planning uncertainty for multi-territory launches, requiring parallel dossier preparation.
- Formulation chemist scarcity:Specialized expertise in osmolality engineering and mucosal compatibility testing concentrates among legacy medical device firms, constraining R&D scaling for newer market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Lubricants Market |
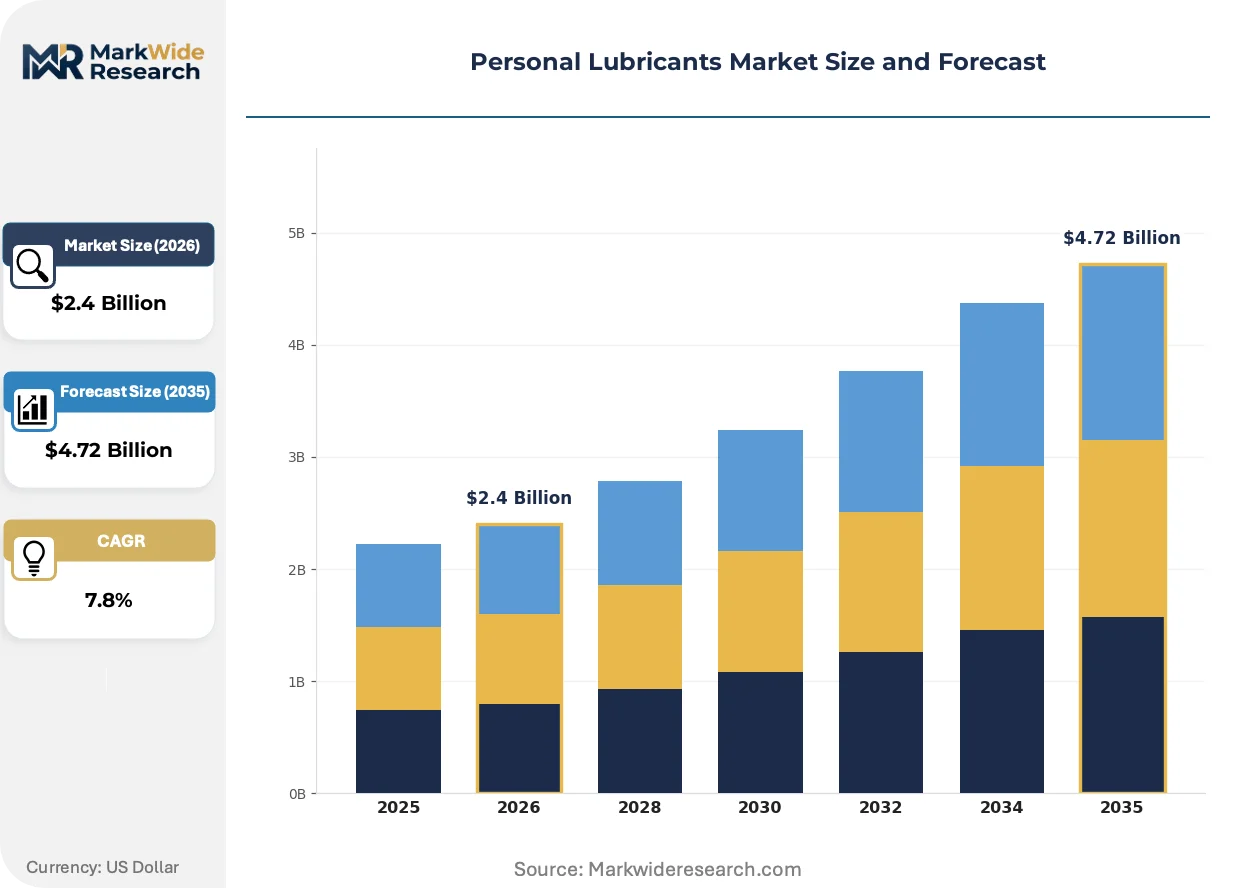
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Silicone-Based, Oil-Based, Hybrid Formulation: Organic, Synthetic, Non-Toxic, Flavored Application: Personal Use, Clinical Use, Sexual Wellness, Massage Packaging Type: Tube, Bottle, Sachet, Jar |
| Companies Covered | BioFilm Inc., Ansell Limited, Reckitt Benckiser Group plc, Lovehoney Group Ltd., Mayer Laboratories, Inc., Church & Dwight Co., Inc., Trigg Laboratories, Inc., Sliquid LLC, LifeStyles Healthcare Pte Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Lubricants Market Strategic Shifts & Innovations
Biotechnology-enabled ingredient substitution and channel disintermediation through telehealth integration are compressing traditional value chain structures while elevating formulation transparency as a purchase determinant.
Plant-derived hyaluronic acid produced via microbial fermentation is displacing petrochemical glycerin as the dominant humectant in premium water-based formulations. Sexual wellness retailers and clean-label distributors are accelerating adoption, with organic-certified SKUs expanding shelf space at double the rate of conventional alternatives. This displacement is compressing synthetic base producers into commodity pricing tiers while rewarding compounders with captive biotechnology partnerships.
The EU Medical Device Regulation's 2021 implementation tightened biocompatibility testing mandates for lubricants claiming clinical or therapeutic utility. Manufacturers must now submit cytotoxicity, sensitization, and irritation data through notified body review, extending time-to-market by twelve to eighteen months for medical-grade positioning. German and French producers with established BfArM and ANSM relationships are capturing disproportionate share of institutional procurement contracts as compliance barriers rise.
Subscription-based replenishment models are displacing episodic pharmacy and specialty store purchases among recurring-use consumers. Direct-to-consumer platforms capture purchase history data to personalize formulation recommendations, bypassing traditional retail intermediaries. This channel shift concentrates most visibly in United States metropolitan markets where telehealth-integrated sexual wellness services have achieved mainstream penetration.
Personal Lubricants Market Segmentation
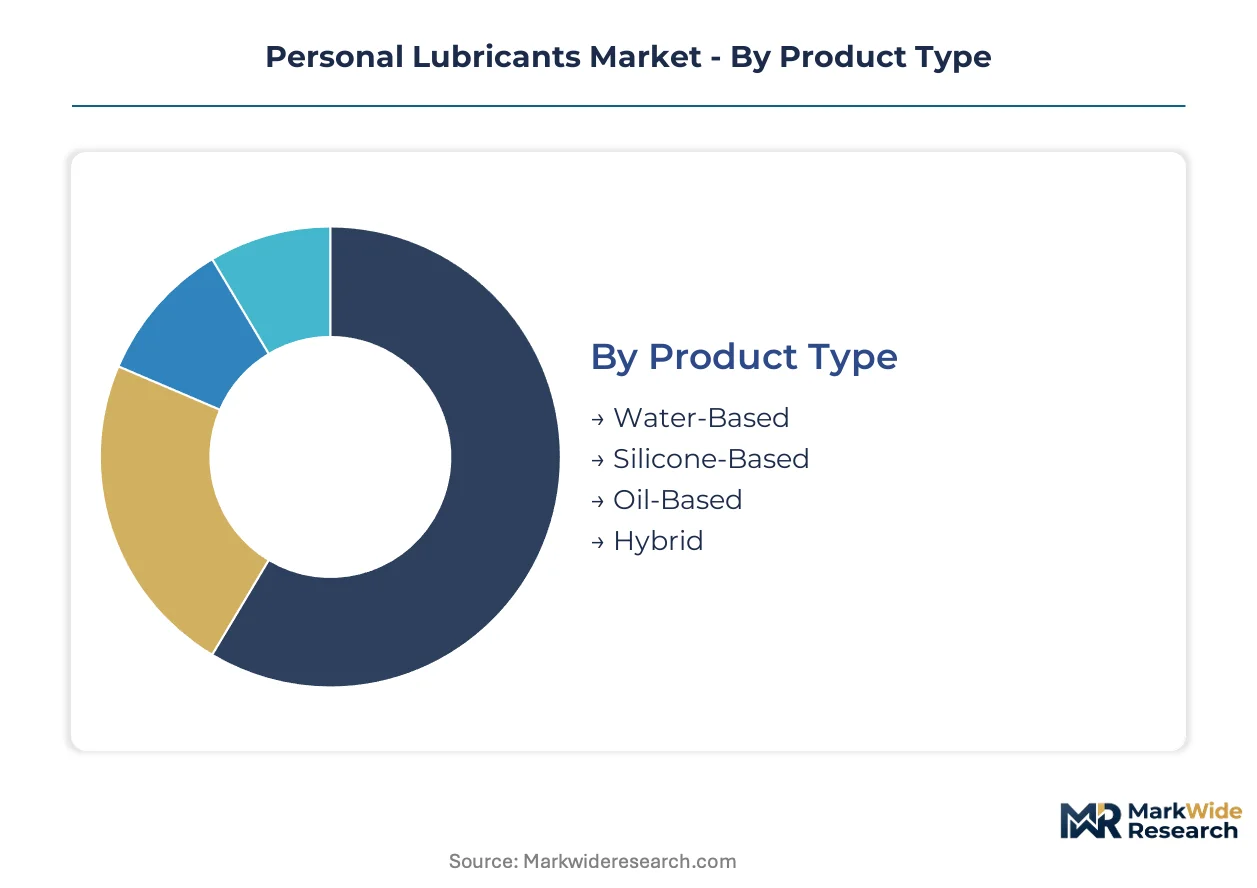
Personal lubricant purchasing patterns diverge sharply across formulation chemistry, end-use context, and distribution channel. Segmentation reveals where margin pools concentrate and which product architectures command sustainable price premiums.
Product Type:
Water-based variants dominate domestic consumption in the United States, Germany, and Japan, while silicone-based exports flow to emerging markets seeking clinical-grade positioning.
- Water-Based:Formulated with purified water, glycerin or plant-derived hyaluronic acid, and cellulose thickeners engineered to 200-400 mOsm/kg osmolality. Demand concentrates in United States retail pharmacy chains where FDA 510(k) clearance enables insurance reimbursement for vaginal dryness treatment. Compatibility with latex barriers and easy cleanup sustain volume leadership despite shorter duration performance.
- Silicone-Based:Dimethicone and cyclopentasiloxane bases deliver extended lubricity without reapplication. Export-led demand from Japanese and German manufacturers supplies urology clinics across Asia-Pacific and Middle Eastern markets where clinical-grade positioning commands 3-4x retail price multiples. Energy price volatility in Chinese and German chemical hubs constrains margin stability.
- Oil-Based:Natural oil formulations from coconut and almond sources compete in price-sensitive segments, particularly where latex compatibility education remains underdeveloped.
- Hybrid:Water-silicone emulsions blend cleanup convenience with extended performance, gaining placement in premium sexual wellness retail.
Water-Based holds the largest share; momentum sits with Silicone-Based as clinical procurement pipelines expand.
Formulation:
Cost tier stratification separates certified organic compounders from synthetic commodity producers, with mid-tier non-toxic positioning squeezed between them.
- Organic:Plant-derived humectants and fermentation-based hyaluronic acid satisfy clean-label procurement standards at sexual wellness retailers. United States and German consumers drive premium pricing for USDA Organic and EU Organic certified SKUs.
- Synthetic:Petrochemical glycerin and propylene glycol bases dominate volume manufacturing through BioFilm Inc. and legacy medical device compounders. Cost advantages concentrate production in United States and Chinese contract manufacturing facilities.
- Non-Toxic:Paraben-free and glycerin-free positioning targets sensitive-skin segments without full organic certification overhead.
- Flavored:Edible formulations with food-grade flavoring systems expand demographic access beyond therapeutic use cases.
Synthetic formulations retain volume dominance; organic certification claims the steepest expansion trajectory as clean-label procurement hardens.
Application:
Customer type bifurcation separates recurring retail consumers from institutional procurement committees with divergent specification requirements.
- Personal Use:Direct-to-consumer subscription models displace episodic pharmacy purchases in United States metropolitan markets. Telehealth-integrated sexual wellness platforms capture purchase history for personalized formulation recommendations.
- Clinical Use:Urology and gynecology practice integration demands FDA 510(k) or EU MDR compliance. German Apotheken networks and Japanese hospital procurement systems concentrate institutional volume.
- Sexual Wellness:Specialty retail and e-commerce platforms normalize lubricant placement alongside contraception and intimacy products.
- Massage:Cross-category positioning in spa and wellness channels leverages formulation overlap with body care products.
Personal use commands current revenue concentration; clinical use is climbing fastest as regulatory clearance opens reimbursement pathways.
Packaging Type:
Volume scale and margin structure vary with packaging format, from high-frequency sachet consumption to premium jar positioning.
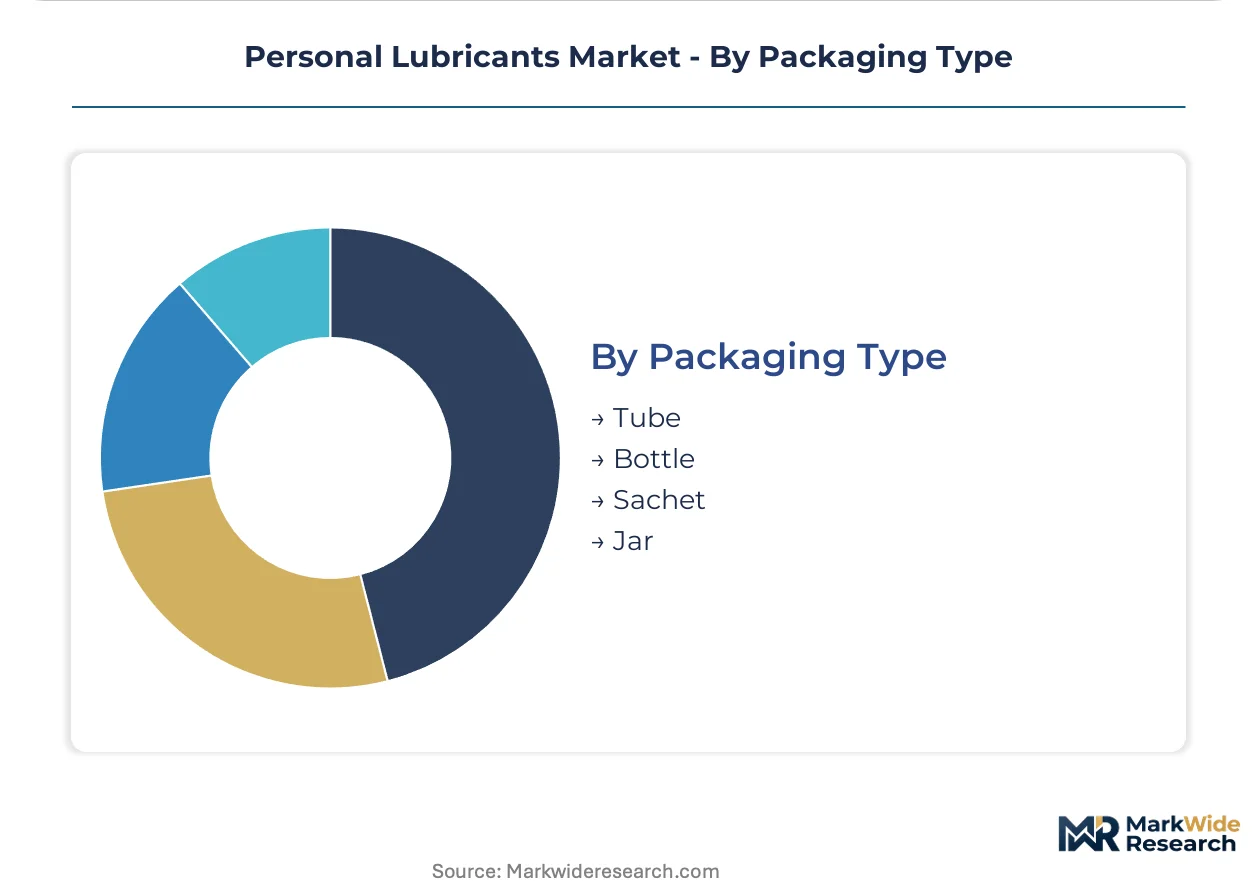
- Tube:Collapsible aluminum and laminate tubes dominate pharmacy and retail shelf placement across United States and European markets.
- Bottle:Pump and flip-top dispensers serve recurring-use households with cost-per-ounce efficiency.
- Sachet:Single-use foil packets drive trial conversion and travel segment penetration in Japanese convenience store channels.
- Jar:Wide-mouth glass and premium plastic containers command sexual wellness boutique placement with aesthetic differentiation.
Tube packaging holds the largest share; sachet formats gain share fastest through METI-backed pharmacy normalization in Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands a premium multiple over German pharmacy channels, while Japanese normalization campaigns compress retail margins through volume expansion. This asymmetry shapes where formulation-heavy innovators versus packaging-focused assemblers concentrate investment.
United States
FDA 510(k) clearance pathways for clinical-grade lubricants drive institutional procurement through urology and gynecology practices. The agency's Class II medical device classification enables insurance reimbursement for vaginal dryness treatment, concentrating volume in retail pharmacy chains. Greater Boston and the Pacific Northwest host biotechnology partnerships advancing plant-derived hyaluronic acid fermentation.
Germany
EU Medical Device Regulation biocompatibility testing mandates extend time-to-market for clinical-positioned brands, favoring established BfArM relationships. The Apotheken pharmacy network remains underpenetrated for sexual wellness relative to other personal care categories. Bavaria and North Rhine-Westphalia concentrate notified body expertise and contract manufacturing infrastructure.
Japan
METI wellness initiatives destigmatize sexual health products, normalizing lubricant placement in convenience stores and pharmacies. Government-backed campaigns broaden demographic access beyond traditional specialty outlets. The Kanto region around Tokyo anchors domestic manufacturing scale for water-based formulations.
United Kingdom
Telehealth-integrated sexual wellness platforms accelerate subscription-based replenishment models in metropolitan markets. MHRA regulatory alignment with EU MDR frameworks preserves testing burdens for clinical claims. London and the Southeast concentrate direct-to-consumer platform development and clean-label retailer headquarters.
Australia
TGA pre-market safety frameworks for therapeutic goods create compliance parity with FDA and EU standards, enabling multi-territory launch strategies. Pharmacy channel consolidation limits shelf access for new entrants without established wholesaler relationships. New South Wales and Victoria host distribution infrastructure serving Asia-Pacific export demand.
Personal Lubricants Market Key Industry Players
Concentration sits with vertically integrated compounders capable of organic certification and medical device compliance. Mid-tier assemblers dependent on synthetic bases face margin compression as clean-label procurement hardens. Three archetypes dominate: biotechnology-enabled formulators, pharmacy-channel incumbents, and direct-to-consumer platform operators. Competitive moves center on M&A for fermentation technology access and strategic partnerships with telehealth platforms for embedded distribution.
Among North American specialists, BioFilm Inc. and Church & Dwight Co., Inc. exemplify divergent scale strategies. BioFilm Inc. anchors cost advantages through manufacturing scale across water-based production lines. Church & Dwight Co., Inc. occupies a position emphasizing R&D intensity in pH-balanced formulations. Reckitt Benckiser Group plc represents pharmacy-channel control through brand strength in developed markets. These three illustrate how regulatory clearance capabilities separate sustainable premium positioning from commodity exposure.
| Leading Market Players |
|---|
| BioFilm Inc. |
| Ansell Limited |
| Reckitt Benckiser Group plc |
| Lovehoney Group Ltd. |
| Mayer Laboratories, Inc. |
| Church & Dwight Co., Inc. |
| Trigg Laboratories, Inc. |
| Sliquid LLC |
| LifeStyles Healthcare Pte Ltd. |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance requirements gate both supply qualification and price differentiation, concentrating premium pricing power among compounders with medical device compliance capabilities while synthetic-base assemblers compete on cost in unregulated retail tiers.
Pricing Analysis
Configured-to-order pricing for clinical-grade formulations commands multiples over standard retail SKUs, with FDA-cleared and EU MDR-compliant products securing insurance reimbursement pathways that commodity alternatives cannot access. Price differentiation rests on certification grade and osmolality engineering precision, not brand alone. Cost compression in synthetic water-based tiers is intensifying as clean-label procurement hardens at sexual wellness retailers. Price-sensitive consumers in emerging markets gravitate toward household oil substitutes, while least-sensitive buyers in German Apotheken and US urology practices prioritize biocompatibility documentation over unit cost.
Supply Chain Analysis
Dimethicone and cyclomethanol feedstock concentration in Chinese and German chemical hubs creates a chokepoint exposing premium silicone-based producers to energy price volatility and input disruption. Manufacturing scale for water-based formulations concentrates in United States contract facilities, Japanese Kanto-region plants, and North Rhine-Westphalia compounding centers. Raw material dependencies include fermentation-derived hyaluronic acid, pharmaceutical-grade glycerin, and medical-device-certified packaging polymers. Single-source vulnerability in silicone precursor supply chains elevates risk profiles for clinical-grade positioning. Distribution runs through pharmacy chains in developed markets, direct-to-consumer platforms in US metropolitan areas, and convenience store networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement committees in urology and gynecology practices, fragmenting demand away from episodic retail purchasers and rewarding suppliers with regulatory dossier capabilities.
For Market Incumbents: Fortify certification moats through parallel FDA 510(k) and EU MDR dossier maintenance, locking in reimbursement pathways that emerging competitors cannot replicate. Deepen backward integration into fermentation-based hyaluronic acid production to secure organic formulation supply against biotechnology partnership scarcity. Channel control in German Apotheken networks and US retail pharmacy chains remains the critical defensive lever against direct-to-consumer platform disintermediation. For New Entrants and Emerging Players: Telehealth-integrated prescription bundling represents a service-layer gap where incumbents under-serve, offering embedded distribution through menopause and erectile dysfunction management platforms. Target Australian pharmacy consolidation as the most penetrable geography, where TGA compliance parity with FDA and EU standards enables multi-territory launch strategies without redundant testing. A subscription-based replenishment go-to-market angle bypasses wholesale relationship barriers that constrain shelf access. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward compounders with established notified body relationships and biocompatibility testing infrastructure. Long-term viability over a multi-year horizon favors biotechnology-enabled formulators with captive fermentation partnerships over packaging-focused assemblers facing margin compression. The signal to watch is regulatory reclassification debates between cosmetic and medical device designations, which would fundamentally alter testing burden economics and target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Partnership Formation | Fermentation-based hyaluronic acid access secures organic formulation supply chains against petrochemical glycerin displacement. |
| Regulatory Dossier Parallel Preparation | Simultaneous FDA 510(k) and EU MDR submissions compress multi-territory launch timelines for clinical-grade positioning. |
| Telehealth Platform Integration | Embedded distribution through menopause and erectile dysfunction protocols captures recurring-use consumers via prescription bundling. |
| Apotheken Channel Penetration | BfArM-compliant documentation unlocks underpenetrated German pharmacy networks for sexual wellness category expansion. |
| Subscription Replenishment Model | Direct-to-consumer platforms capture purchase history data for personalized formulation recommendations, bypassing retail intermediaries. |
Research Approach
The analysis maps water-based, silicone-based, oil-based, and hybrid formulation sub-sectors, each validated through formulation chemists, sexual wellness retail buyers, urology practice procurement managers, and pharmacy chain category directors. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, METI wellness initiative publications, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs for consistency.
Outputs were validated against external benchmarks including sexual wellness retailer SKU expansion rates, pharmacy chain reimbursement code adoption, and biotechnology partnership announcement frequencies. Segmentation dimensions across the modeling period include formulation chemistry, certification tier, end-use context, and distribution channel. CAGRs were derived from regression analysis of historical volume trajectories and regulatory pathway expansion timelines, with osmolality engineering capability and clean-label procurement intensity as industry-specific forecast inputs.
Underlying assumptions cover sustained FDA medical device classification, EU MDR enforcement continuity, and METI campaign normalization trajectories, with deviation risk concentrated in regulatory reclassification debates and silicone feedstock energy price shocks. Practitioners should keep alternative scenarios live as cosmetic-chemical classification ambiguity and biotechnology scale-up timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Global Canes and Walking Sticks Market