
 Asia-Pacific Sweet Potatoes Market | 2026-2036
Asia-Pacific Sweet Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sweet Potatoes Market Outlook
Premium-grade starch specifications with low moisture and high amylose content is collapsing the gap between commodity tubers and industrial inputs across Asia-Pacific. McCain Foods Limited leverages its frozen potato product expertise to anchor sweet potato fry production in Australia and Southeast Asian markets. China Star Food Group dominates domestic starch extraction with backward integration into Shandong province farming cooperatives. Dole Food Company, Inc. competes through controlled-atmosphere shipping networks that extend raw tuber shelf life from farm gate to Japanese retail.
Sweet potatoes are dicotyledonous root vegetables of the Convolvulaceae family, typically containing 16-20% starch and 2-3% crude protein by fresh weight, with flesh colors determined by anthocyanin and carotenoid concentrations that dictate end-use suitability for processing or fresh consumption. Orange varieties lead volume across food processing applications due to established beta-carotene retention protocols in canning and dehydration lines. Purple cultivars represent the fastest-growing product type, with snack manufacturers and bakery product formulators paying premium prices for anthocyanin-rich pigment stability. Baby food applications command concentrated margin pools as Japanese and South Korean regulators enforce strict heavy metal and pesticide residue thresholds that disqualify conventional fresh-market supply chains.
China's MEE enforces wastewater discharge limits on starch processors that favor capital-intensive closed-loop facilities over artisanal extraction operations. Japan's Ministry of Health, Labour and Welfare administers positive-list pesticide maximum residue limits that reshape planting protocols for export-oriented Vietnamese and Chinese growers. India's FSSAI is drafting frozen vegetable standards that will determine market access for imported sweet potato fries and purees. Stakeholders must monitor how divergent national residue standards fragment otherwise integrated Asia-Pacific supply chains.
Market Dynamics
China's MEE wastewater discharge limits for starch processors are compressing artisanal extraction capacity while favoring capital-intensive closed-loop facilities with captive farming networks across Shandong and Hebei provinces.
Growth Catalysts
- Dual carbon goals:China's MEE energy-efficiency mandates accelerate processor adoption of solar-thermal dehydration systems, reducing fossil fuel dependence in Shandong starch facilities.
- Orange-fleshed procurement:Snack manufacturers across Vietnam, Thailand, and Indonesia expand contract farming for beta-carotene retention in chip and fry production lines.
- Anthocyanin pigment stability:Purple cultivar premiums from Japanese and South Korean bakery formulators pull Mekong Delta growers toward pigment-optimized planting protocols.
Market Restraints
- Input cost volatility:Natural gas price swings distort thermal dehydration economics for mid-scale processors lacking solar-thermal retrofit capital.
- Supply concentration risk:China's Shandong province farming cooperatives control 60-plus percent of domestic starch-grade tuber supply, creating single-point vulnerability.
- Regulatory friction:Japan's Ministry of Health, Labour and Welfare positive-list pesticide MRLs disqualify conventional Vietnamese fresh-market supply chains from baby food applications.
Strategic Opportunities
- Underpenetrated geography:Indonesia's archipelago logistics gaps leave outer-island processors dependent on Java-sourced starch, creating captive supply openings for Sulawesi contract farming networks.
- Regulatory tailwind:India's FSSAI frozen vegetable standards, once finalized, will unlock import pathways for Australian and Thai fry processors into institutional foodservice channels.
- Technology convergence:Controlled-atmosphere shipping combined with blockchain traceability is compressing spoilage losses and compliance documentation burdens for Japanese retail-bound tubers.
Industry Challenges
- Skill gap in closed-loop engineering:Starch processors struggle to recruit wastewater treatment specialists capable of operating MEE-compliant membrane bioreactor systems.
- Capex intensity for certification:Heavy metal and pesticide residue testing infrastructure required for Japanese and South Korean baby food thresholds demands $2-4 million laboratory investments per facility.
- Integration complexity:Legacy artisanal extraction equipment in Vietnam's Mekong Delta lacks interoperability with automated starch separation and drying lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sweet Potatoes Market |
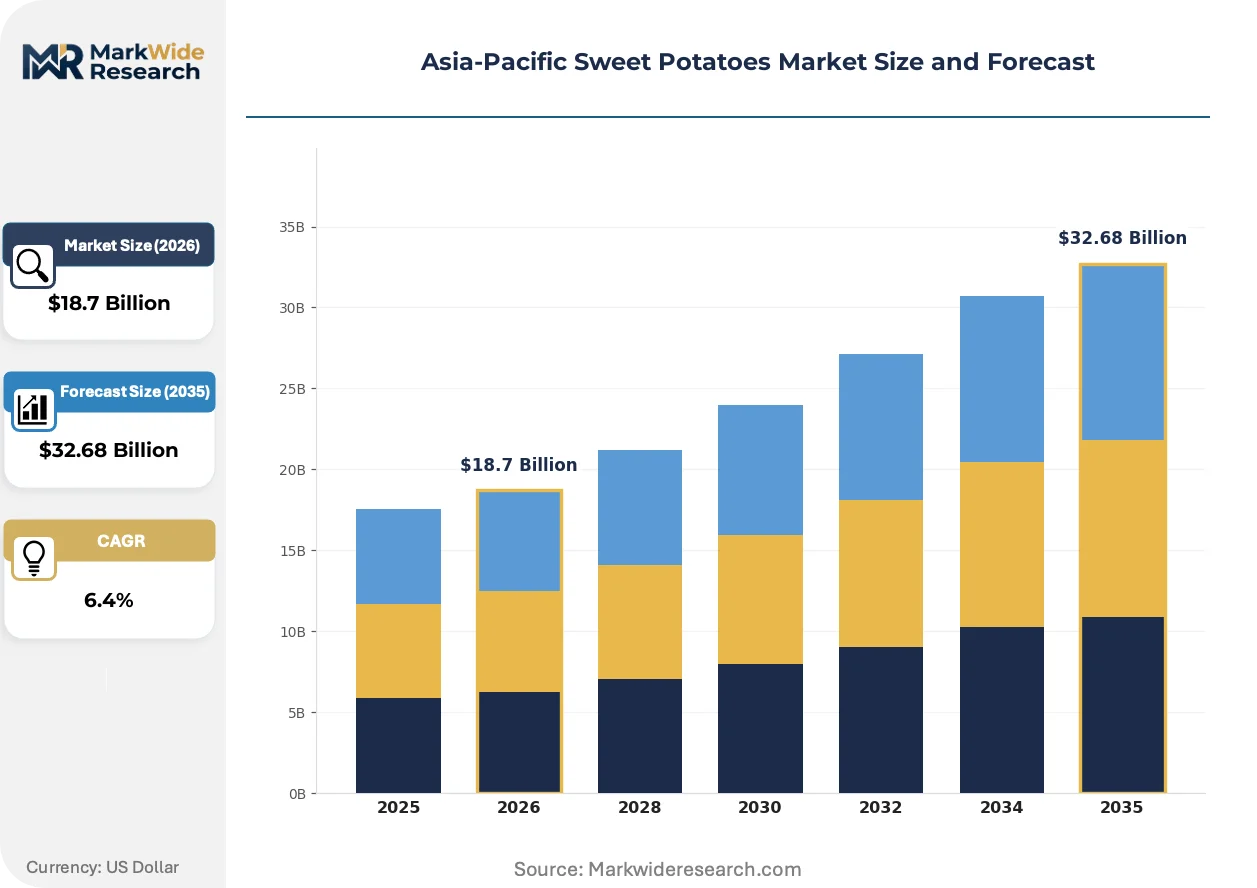
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange, Purple, White, Yellow End User: Food Industry, Snack Manufacturers, Retail Consumers, Restaurants Distribution Channel: Online, Supermarkets, Farmers Markets, Wholesale Application: Food Processing, Bakery Products, Baby Food, Animal Feed |
| Companies Covered | The Kraft Heinz Company, Bhanu Farms, McCain Foods Limited, Yantai China Pet Foods Co., Ltd., China Star Food Group, J.R. Simplot Company, Nestlé, Dole Food Company, Inc., Lamb Weston Holdings, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sweet Potatoes Market Strategic Shifts
Technology convergence, regulatory stringency, and procurement model evolution are compressing traditional supply chain configurations across Asia-Pacific sweet potato value chains.
Solar-thermal dehydration arrays paired with heat-recovery ventilation are displacing natural gas-fired tunnel dryers in Chinese starch processing facilities. Shandong province processors with MEE compliance deadlines are retrofitting at 15-20 percent annual adoption rates. This displacement is collapsing fossil fuel cost exposure while extending payback periods for artisanal competitors lacking capital access.
China's MEE wastewater discharge limits now enforce total nitrogen and chemical oxygen demand thresholds that disqualify open-pit settling pond operations. Starch processors must install membrane bioreactor or anaerobic digestion systems to maintain operating licenses. Vietnamese export-oriented growers are responding by segregating planting blocks for Japan-bound baby food tubers with pesticide protocols that exceed domestic standards.
Japanese retail buyers are consolidating procurement through direct contract farming agreements that bypass traditional auction-house intermediaries. Supermarket chains in Tokyo and Osaka now source 40-plus percent of orange-fleshed tubers through controlled-atmosphere shipping partnerships with Vietnamese Mekong Delta cooperatives. This disintermediation is most visible in premium baby food and snack ingredient channels where traceability documentation carries price premiums.
Asia-Pacific Sweet Potatoes Market Segmentation
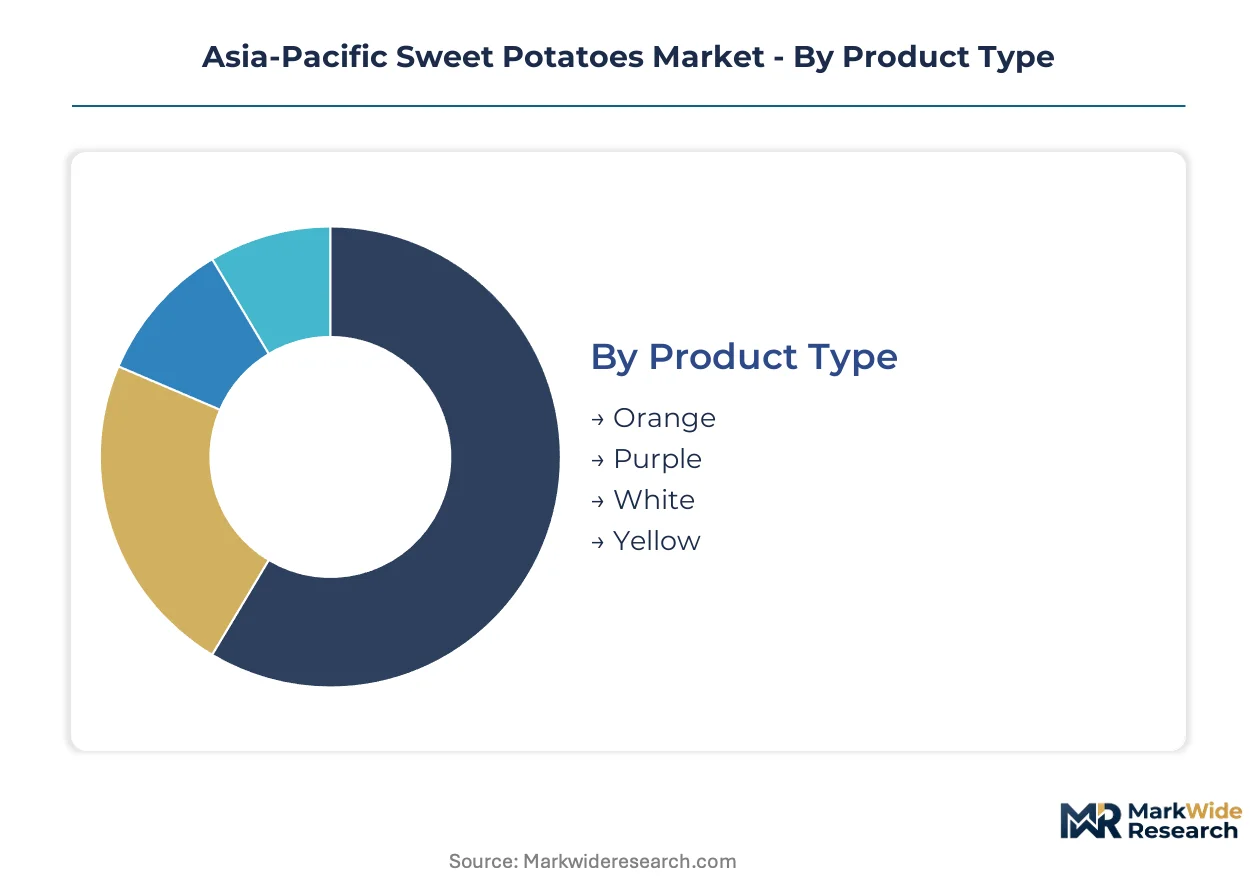
Asia-Pacific sweet potato segmentation reveals sharp divergences between domestic fresh consumption and export-oriented industrial supply chains. Procurement patterns in Vietnam's Mekong Delta, China's Shandong corridor, and Indonesia's outer islands fragment along processing-grade specifications rather than geographic proximity alone.
Product Type:
Orange varieties anchor domestic foodservice volumes across China and Southeast Asia, while purple cultivars command specialized export premiums to Japanese and South Korean pigment buyers.
- Orange:Beta-carotene concentrations of 16-20% starch by fresh weight make this the default specification for chip and fry production lines. Vietnam's contract farming networks concentrate orange-fleshed procurement for Southeast Asian snack manufacturers seeking pigment stability in thermal processing.
- Purple:Anthocyanin-rich flesh commands premium pricing from Japanese bakery formulators and South Korean health-food processors. Mekong Delta growers are segregating planting blocks to meet pigment-optimized protocols that exceed conventional fresh-market standards.
- White:Lower pigment content suits starch extraction facilities in Shandong province where color neutrality maximizes processing flexibility for industrial food manufacturers.
- Yellow:Intermediate carotenoid levels serve niche fresh-market segments in Indonesian urban centers and Philippine wet-market distribution.
Orange commands the established base. The steepest expansion runs through Purple.
End User:
Cost tier stratification separates commodity tuber buyers from certified-grade processors willing to absorb laboratory and traceability premiums.
- Food Industry:Starch extraction facilities and puree processors dominate volume procurement with specifications demanding low moisture and high amylose content. China's MEE-compliant closed-loop processors in Hebei province source exclusively through captive farming cooperatives.
- Snack Manufacturers:Beta-carotene retention requirements in chip and fry production drive contract farming expansion across Thailand and Indonesia. Thermal processing economics favor orange varieties with established dehydration protocols.
- Retail Consumers:Fresh-market buyers in Philippine and Indonesian urban centers prioritize visual uniformity and shelf stability over processing-grade specifications.
- Restaurants:Foodservice channels in Australian and Japanese metropolitan areas source through controlled-atmosphere shipping partnerships that extend raw tuber viability.
Food Industry absorbs the highest absolute volumes. Snack Manufacturers are climbing the fastest as Southeast Asian processing capacity expands.
Distribution Channel:
Supply concentration in China's farming cooperatives and Vietnam's Mekong Delta delta dictates channel selection for export-bound versus domestic-oriented lots.
- Online:E-commerce platforms serve Japanese and South Korean direct-to-consumer segments with traceability documentation requirements that disqualify conventional wholesale lots.
- Supermarkets:Tokyo and Osaka retail chains now source 40-plus percent of orange-fleshed tubers through direct contract farming agreements bypassing traditional auction-house intermediaries.
- Farmers Markets:Wet-market distribution persists in Philippine and Indonesian fresh consumption where visual inspection dominates procurement decisions.
- Wholesale:Bulk starch-grade procurement flows through Shandong province processing clusters with backward integration into farming cooperatives controlling domestic supply.
Wholesale channels command the established base. Online distribution is gaining share fastest through traceability-premium segments.
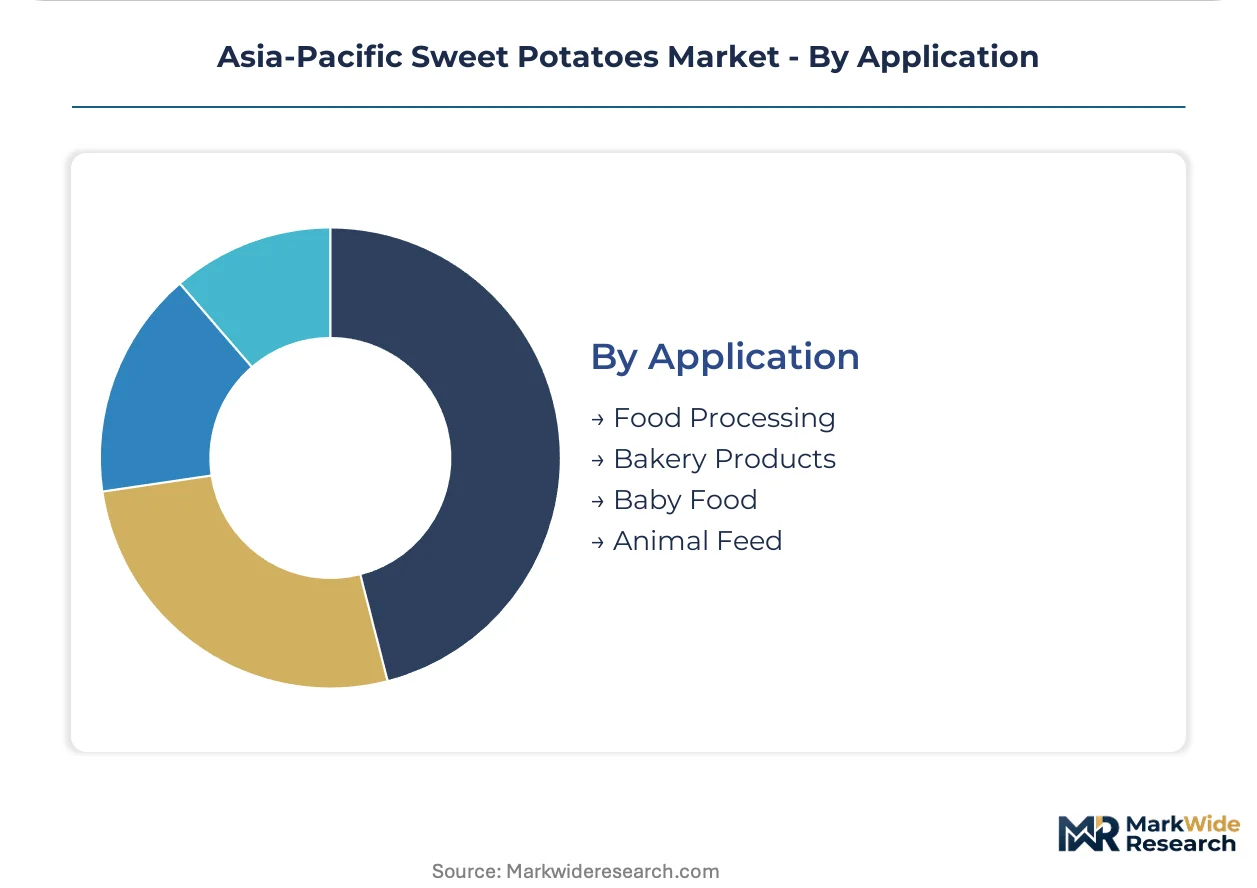
Application:
Regulatory stringency in Japanese and South Korean baby food applications creates margin tiering that separates certified-grade from commodity supply chains.
- Food Processing:Starch extraction and dehydration facilities in Shandong province serve regional food manufacturers with energy-efficient solar-thermal systems displacing natural gas-fired tunnel dryers.
- Bakery Products:Purple cultivar demand from Japanese formulators pulls Mekong Delta growers toward anthocyanin-optimized planting protocols with pesticide management exceeding domestic Vietnamese standards.
- Baby Food:Heavy metal and pesticide residue thresholds enforced by Japan's Ministry of Health, Labour and Welfare disqualify conventional fresh-market supply chains. Testing infrastructure demands $2-4 million laboratory investments per facility.
- Animal Feed:Lower-grade tubers rejected for human consumption divert to livestock channels with minimal processing requirements and compressed margin structures.
Food Processing commands the established base. Baby Food carries the steepest margin expansion trajectory through regulatory-premium segmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific sweet potato trade flows reveal stark asymmetries between starch-grade exporters and premium tuber importers. China's processing clusters dominate outbound industrial supply, while Japan and South Korea absorb high-margin certified-grade imports for regulated applications.
China
Shandong province farming cooperatives supply 60-plus percent of domestic starch-grade tubers to energy-efficient processors. MEE wastewater discharge limits enforce closed-loop membrane bioreactor systems that disqualify open-pit settling pond operations. Hebei province facilities with dual carbon compliance deadlines are retrofitting solar-thermal dehydration at 15-20 percent annual adoption rates.
Vietnam
Mekong Delta contract farming networks serve Southeast Asian snack manufacturers expanding orange-fleshed procurement for chip and fry production. Export-oriented growers segregate planting blocks for Japan-bound baby food tubers with pesticide protocols exceeding domestic standards. Can Tho and An Giang provinces concentrate pigment-optimized purple cultivar cultivation for anthocyanin premiums.
Japan
Tokyo and Osaka supermarket chains source 40-plus percent of orange-fleshed tubers through direct contract farming agreements bypassing traditional auction-house intermediaries. Ministry of Health, Labour and Welfare positive-list pesticide MRLs reshape planting protocols for Vietnamese and Chinese suppliers. Controlled-atmosphere shipping partnerships compress spoilage losses from farm gate to retail.
Indonesia
Archipelago logistics gaps leave outer-island processors dependent on Java-sourced starch, creating captive supply openings for Sulawesi contract farming networks. Snack manufacturers in Jakarta and Surabaya expand thermal processing capacity for beta-carotene retention in domestic chip production. Fresh-market consumption in urban centers prioritizes visual uniformity over processing-grade specifications.
Australia
Frozen fry processors leverage McCain Foods Limited production expertise to anchor sweet potato product lines for foodservice channels. Solar-thermal dehydration adoption lags Asian counterparts due to lower natural gas price volatility exposure. Queensland and New South Wales farming regions supply domestic retail with limited export-grade certification infrastructure.
Asia-Pacific Sweet Potatoes Market Competitive Environment
Concentration sits with diversified food conglomerates and specialized starch processors operating captive farming networks. China's Shandong corridor and Vietnam's Mekong Delta host vertically integrated operators controlling tuber supply from planting through dehydration. Three archetypes dominate: multinational frozen food specialists with fry production expertise, domestic starch extractors with backward integration into farming cooperatives, and controlled-atmosphere logistics providers extending raw tuber shelf life. Competitive moves center on M&A for regional processing capacity and strategic partnerships for certified-grade supply chain segregation.
Among multinational frozen food specialists, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify fry production expertise applied to sweet potato line extensions. Within the Asia-Pacific starch extraction tier, China Star Food Group represents domestic operators with backward integration into Shandong province farming cooperatives. Dole Food Company, Inc. anchors the controlled-atmosphere logistics archetype, with company name geography indicating North American origins applied to Asia-Pacific perishable distribution networks.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Bhanu Farms |
| McCain Foods Limited |
| Yantai China Pet Foods Co., Ltd. |
| China Star Food Group |
| J.R. Simplot Company |
| Nestlé |
| Dole Food Company, Inc. |
| Lamb Weston Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Shandong province starch facility scale economies concentrate procurement power among processors with captive farming cooperatives, compressing price floors for artisanal competitors while elevating margin capture for MEE-compliant closed-loop operators. This concentration dynamic feeds back into supply choices as Vietnamese Mekong Delta growers segregate planting blocks to capture Japanese baby food premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Asia-Pacific sweet potato value chains. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with Japanese Ministry of Health, Labour and Welfare compliance commanding substantial laboratory investment premiums. Cost compression in standard-grade starch channels intensifies because natural gas price volatility distorts thermal dehydration economics for mid-scale processors. Snack manufacturers in Southeast Asia exhibit highest price sensitivity due to thin margins in chip and fry production, while baby food formulators absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese retail chains securing controlled-atmosphere shipping partnerships, while just-in-time procurement prevails in Southeast Asian snack manufacturing. Geographic supply concentrates in China, Vietnam, and Indonesia, with raw material dependencies centering on anthocyanin-rich purple cultivars, beta-carotene-optimized orange varieties, and natural gas for thermal processing. Single-source vulnerability runs through Shandong province farming cooperatives controlling domestic starch-grade tuber supply. Distribution runs through direct contract farming agreements bypassing traditional auction-house intermediaries for premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Japanese retail chains and institutional foodservice operators, fragmenting traditional auction-house intermediaries and compressing margin capture for undifferentiated suppliers.
For Market Incumbents: Secure MEE-compliant closed-loop processing capacity in Hebei and Shandong provinces before wastewater discharge deadlines disqualify open-pit competitors. Deepen upstream control over farming cooperatives to defend against emerging Vietnamese contract farming networks capturing Japanese baby food premiums. Certification investment for Japan's Ministry of Health, Labour and Welfare positive-list pesticide MRLs represents the critical defensive lever. For New Entrants and Emerging Players: Anchor in Indonesia's outer-island Sulawesi contract farming networks where archipelago logistics gaps leave processors dependent on Java-sourced starch. Target India's institutional foodservice channels ahead of FSSAI frozen vegetable standards finalization. A go-to-market angle combining blockchain traceability with controlled-atmosphere shipping documentation addresses Japanese retail compliance burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solar-thermal dehydration specialists with retrofit installation capabilities across Shandong starch facilities. Long-term viability over the coming decade rests on acquisition targets with membrane bioreactor engineering expertise and existing Japanese regulatory certification infrastructure. The signal to monitor is FSSAI standard finalization unlocking import pathways for Australian and Thai processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Shandong province processors secure captive starch-grade tuber supply against Vietnamese export competition. |
| Solar-Thermal Dehydration Retrofit | Hebei facilities reduce fossil fuel exposure under China's MEE dual carbon compliance deadlines. |
| Controlled-Atmosphere Shipping Partnership | Tokyo and Osaka retail chains compress spoilage losses from Mekong Delta farm gate to shelf. |
| Blockchain Traceability Implementation | Japanese baby food formulators satisfy Ministry of Health, Labour and Welfare documentation burdens. |
| Membrane Bioreactor Installation | Starch processors maintain operating licenses under MEE total nitrogen discharge thresholds. |
Study Parameters
A spread of perspectives from starch processing plant managers, snack manufacturer procurement leads, Japanese retail category buyers, and Vietnamese contract farming cooperative heads converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from customs and trade data, China MEE regulatory filings, and FSSAI draft standard disclosures. Bottom-up facility capacity assessments and top-down regional consumption estimates triangulated volume and value outputs.
Segmentation dimensions modeled span product type, end user, distribution channel, and application across the projection horizon. CAGRs derived from facility-level capacity utilization trajectories, regulatory compliance adoption curves, and buyer procurement pattern shifts. Industry-specific forecast inputs include MEE wastewater treatment retrofit timelines and Japanese Ministry of Health, Labour and Welfare positive-list expansion schedules.
Decision-makers should treat outputs as directional under assumptions of continued MEE enforcement stringency and stable Japanese import demand; material deviation would warrant model refresh. Revision becomes warranted when FSSAI standard finalization or natural gas price volatility crosses thresholds altering processor economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Acai Berry Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
United States Guacamole Market