
 Global Blockchain in Healthcare Market | 2026-2036
Global Blockchain in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Healthcare Market Analysis
Project finance for blockchain infrastructure is tilting competitive advantage toward consortium operators with balance-sheet depth. IBM leverages its Hyperledger Fabric deployments across multi-hospital networks to sustain recurring revenue from node management services. Microsoft anchors enterprise demand through Azure Blockchain Workbench integrations with existing cloud contracts. Patientory competes on consumer-facing health record portability, differentiating its tokenized incentive model from institutional-focused rivals.
Blockchain in healthcare denotes distributed ledger architectures using cryptographic hashing, consensus mechanisms, and smart contracts to create tamper-evident records across untrusted parties. These systems execute automated compliance checks and immutable audit trails, primarily serving pharmaceutical supply chains and clinical data exchanges where provenance verification reduces counterfeiting and accelerates regulatory submissions. Private blockchain deployments dominate current enterprise procurement, capturing the majority of margin pools through customized permissioning and integration fees. Supply chain transparency applications are expanding fastest as pharmaceutical firms face DSCSA serialization deadlines. Cloud-based deployment models lead volume adoption by eliminating capital expenditure barriers for mid-sized hospital systems.
The FDA enforces drug traceability standards under DSCSA that mandate interoperable electronic systems, directly stimulating demand for verified ledger infrastructure. HIPAA privacy rules shape product architecture by requiring granular access controls and encrypted patient identifiers on any network handling protected health information. The EU's EMA and GDPR frameworks impose cross-border data residency constraints that favor geographically distributed node configurations. Stakeholders must monitor how harmonization between FDA and EMA pilot programs affects interoperability standards and procurement specifications.
Market Dynamics
Immutable ledger mandates from pharmaceutical regulators are compressing deployment timelines across hospital networks and drug manufacturers, forcing infrastructure decisions before interoperability standards fully crystallize.
Growth Catalysts
- DSCSA serialization deadlines:The FDA's enforcement timeline for electronic track-and-trace systems compels US pharmaceutical distributors to procure verified ledger infrastructure ahead of compliance windows.
- Clinical trial documentation pilots:Germany's BfArM and the EMA joint programs create procurement urgency among European contract research organizations seeking tamper-evident audit trails.
- Cloud-based deployment models:Elimination of capital expenditure barriers accelerates adoption among mid-sized hospital systems previously priced out of private blockchain implementations.
Market Restraints
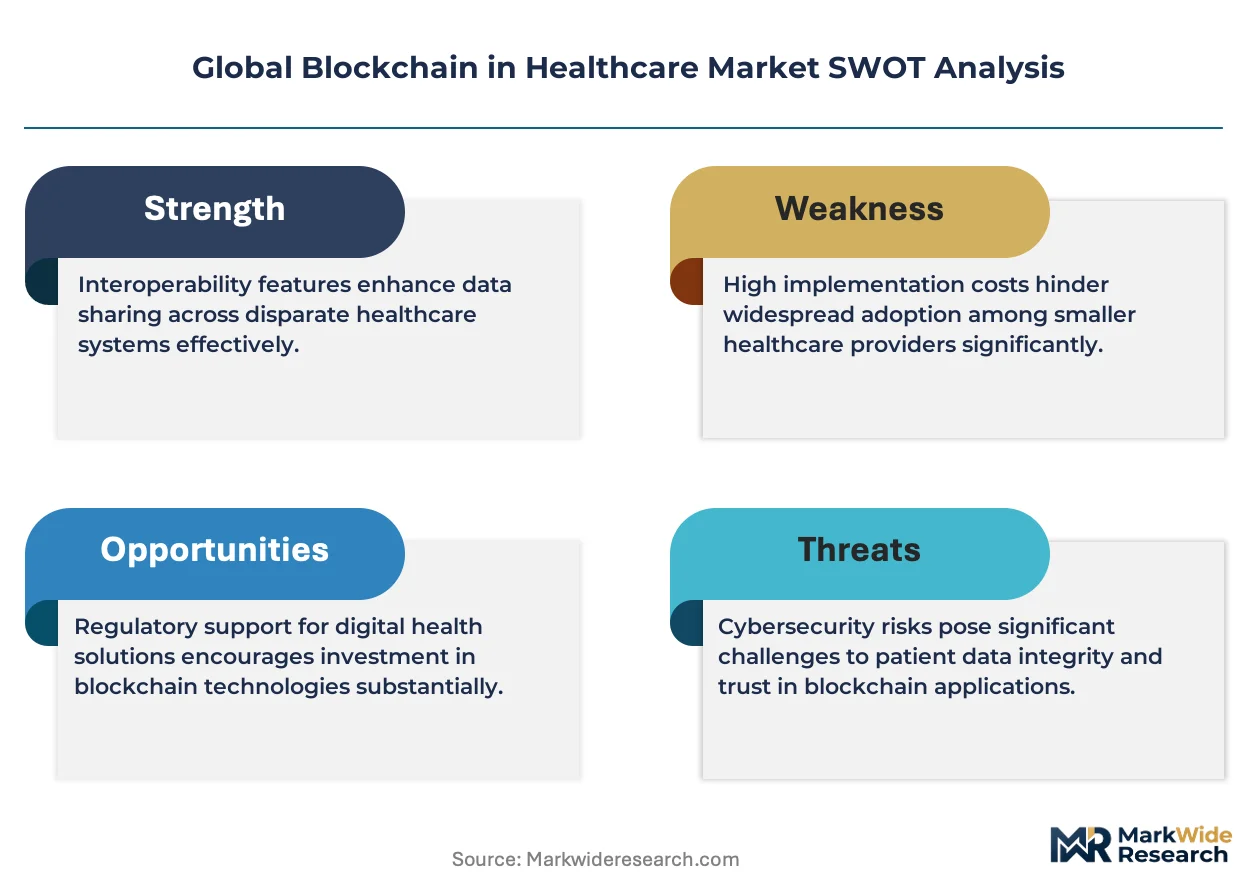
- GDPR cross-border data residency constraints:The EU's framework imposes geographic node distribution requirements that inflate infrastructure costs for multinational health networks.
- Specialized cryptographic talent scarcity:Shortage of engineers proficient in zero-knowledge proofs and permissioned consensus mechanisms constrains deployment velocity.
- Legacy EHR integration friction:Proprietary data formats in incumbent hospital information systems resist standardized API connectivity, extending implementation timelines.
Strategic Opportunities
- Tokenized patient incentive models:Consumer-facing health record portability platforms in the United States reward data sharing through cryptographic token economics, opening direct-to-patient revenue streams distinct from institutional contracts.
- AI-blockchain convergence:Machine learning models trained on federated ledgers enable predictive supply chain analytics without centralizing sensitive manufacturing data.
- Indian pharmaceutical export compliance:CDSCO alignment with international traceability standards creates demand for ledger infrastructure among generic drug manufacturers serving regulated markets.
Industry Challenges
- HIPAA technical safeguard implementation:Granular access controls and encrypted patient identifiers require architectural redesign of permissioning layers, extending development cycles.
- Consensus mechanism latency:Proof-of-authority validation speeds in clinical settings lag real-time patient monitoring requirements, limiting acute care applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Healthcare Market |
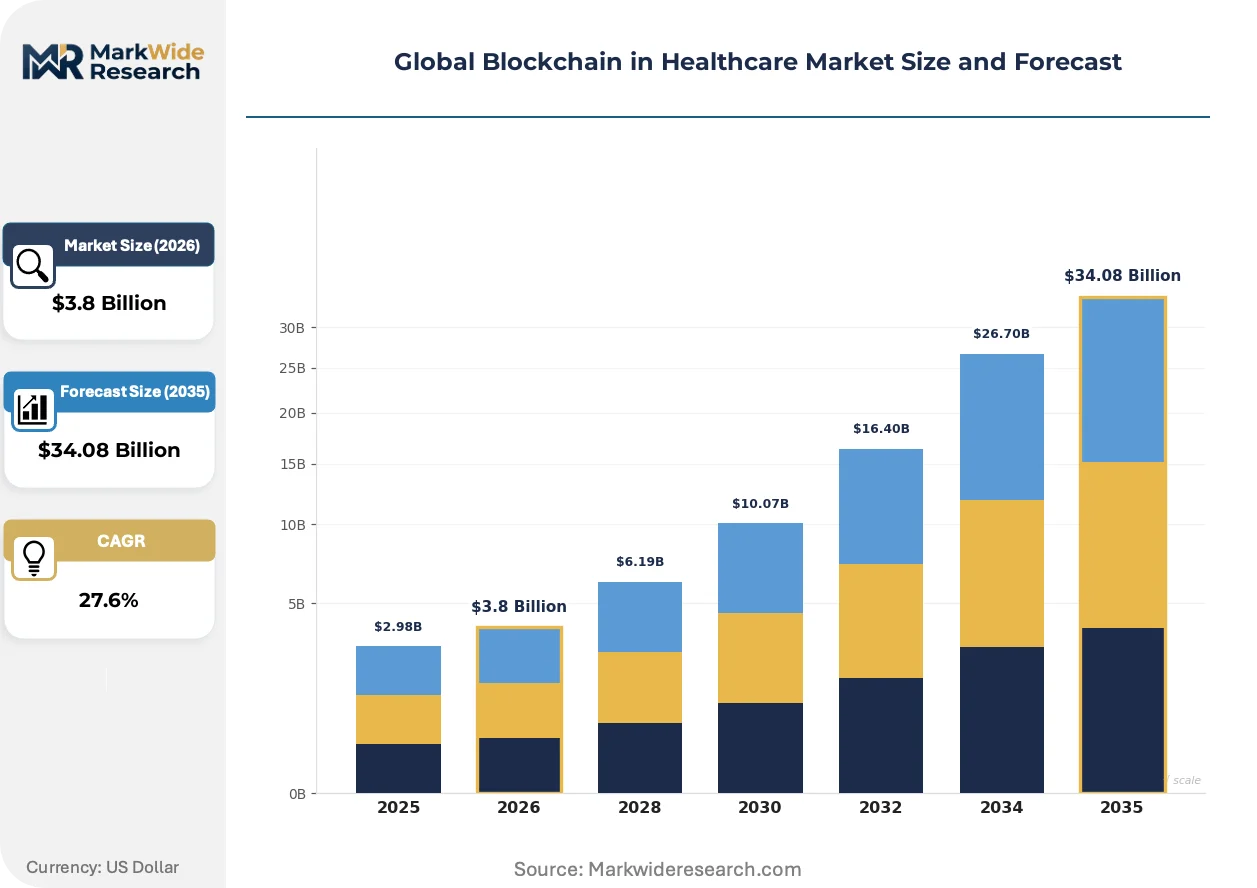
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $34.08 Billion |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Application: Patient Data Management, Supply Chain Transparency, Drug Traceability, Clinical Trials Management End User: Hospitals, Insurance Companies, Pharmaceutical Firms, Research Institutions Deployment: Cloud-Based, On-Premise, Hybrid, Mobile-Based |
| Companies Covered | IBM, Microsoft, Patientory, Hashed Health, BurstIQ, Akiri, Guardtime, Avaneer Health, Chronicled, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Healthcare Market Emerging Trajectories
Healthcare blockchain architectures are pivoting from experimental pilots toward production-grade deployments as regulatory deadlines harden and cloud-native tooling matures. This transition is compressing vendor selection cycles and elevating interoperability standards.
Zero-knowledge proof implementations are migrating from research environments into live pharmaceutical supply chain verification. Drug manufacturers in Germany and Switzerland deploy zk-SNARK protocols to validate batch provenance without exposing competitive sourcing data. This migration from transparent ledgers to privacy-preserving architectures protects commercial confidentiality while satisfying EMA documentation requirements.
The EU AI Act's risk classification framework imposes algorithmic audit obligations on clinical decision-support systems that leverage distributed data pools. Healthcare AI developers must now document training data lineage on immutable ledgers to demonstrate compliance with high-risk system standards. European hospital procurement committees increasingly require such documentation in vendor evaluation scorecards.
Subscription-based node management services displace perpetual license models as the dominant procurement structure for hospital consortiums. Multi-hospital networks in the United States favor operational expenditure arrangements that bundle infrastructure maintenance with regulatory update guarantees. This shift concentrates purchasing power among cloud hyperscalers offering integrated compliance tooling alongside compute resources.
Global Blockchain in Healthcare Market Segmentation
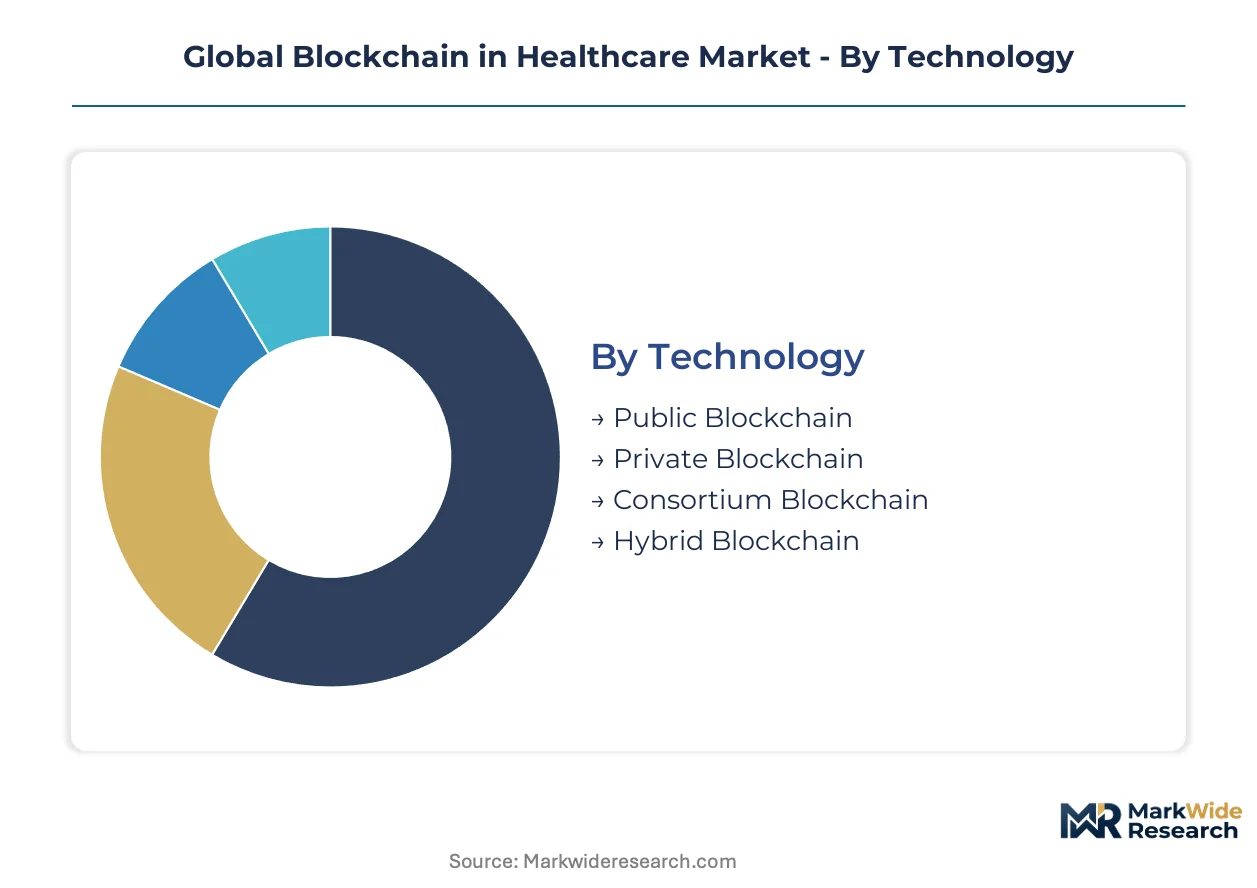
Blockchain architectures in healthcare serve distinct risk-reward profiles across institutional workflows. Technology choices determine regulatory compliance pathways, while deployment models shape capital commitment structures for buyers.
Technology:
The use-case spectrum spans fully decentralized verification to tightly controlled permissioned networks.
- Private Blockchain:Permissioned architectures restrict node participation to vetted institutional members, enabling granular access controls required under HIPAA technical safeguards. Pharmaceutical manufacturers in the United States deploy these systems for DSCSA-compliant drug serialization, with procurement concentrated among FDA-regulated distributors facing enforcement deadlines.
- Consortium Blockchain:Multi-stakeholder governance distributes infrastructure costs across hospital networks and pharmaceutical partners while maintaining collective control over consensus rules. Germany's BfArM pilot programs for clinical trial documentation are accelerating adoption among European contract research organizations seeking tamper-evident audit trails without single-vendor dependency.
- Public Blockchain:Open verification networks offer cryptographic immutability without infrastructure ownership, though HIPAA compliance constraints limit PHI handling.
- Hybrid Blockchain:Segmented architectures isolate sensitive patient data on private subnets while leveraging public chains for non-confidential verification anchors.
Established volume favors private deployments; emerging adoption favors consortium structures.
Application:
Functional priorities diverge between operational efficiency and regulatory risk mitigation.
- Supply Chain Transparency:End-to-end serialization tracks pharmaceutical batches from active ingredient sourcing through dispensing, creating cryptographic provenance records that satisfy FDA DSCSA and EMA documentation requirements. Demand clusters among generic drug manufacturers in India seeking CDSCO alignment with export market standards.
- Drug Traceability:Unit-level verification systems authenticate medication legitimacy at point of care, with hospital pharmacies deploying these solutions to intercept counterfeit products before patient administration.
- Patient Data Management:Tokenized health record portability enables consumer-controlled sharing across provider networks, with United States platforms experimenting with cryptographic incentive models.
- Clinical Trials Management:Immutable consent documentation and automated protocol compliance reduce regulatory submission timelines for research institutions participating in EMA pilot programs.
Supply chain applications command current procurement budgets; patient-facing platforms are gaining share fastest.
End User:
Buyer sophistication ranges from compliance-driven procurement to experimental innovation budgets.
- Pharmaceutical Firms:Serialization mandates and anti-counterfeiting investments drive the largest contract values, with United States distributors upgrading infrastructure ahead of FDA enforcement windows.
- Hospitals:Mid-sized health systems favor cloud-based deployments to avoid capital expenditure, while academic medical centers pilot zero-knowledge proof integrations for research data sharing.
- Insurance Companies:Claims verification and fraud prevention applications leverage smart contract automation for prior authorization workflows.
- Research Institutions:Clinical data exchange requirements under EU AI Act documentation rules are elevating ledger infrastructure in vendor scorecards.
Pharmaceutical procurement dominates contract value; hospital adoption is expanding most quickly.
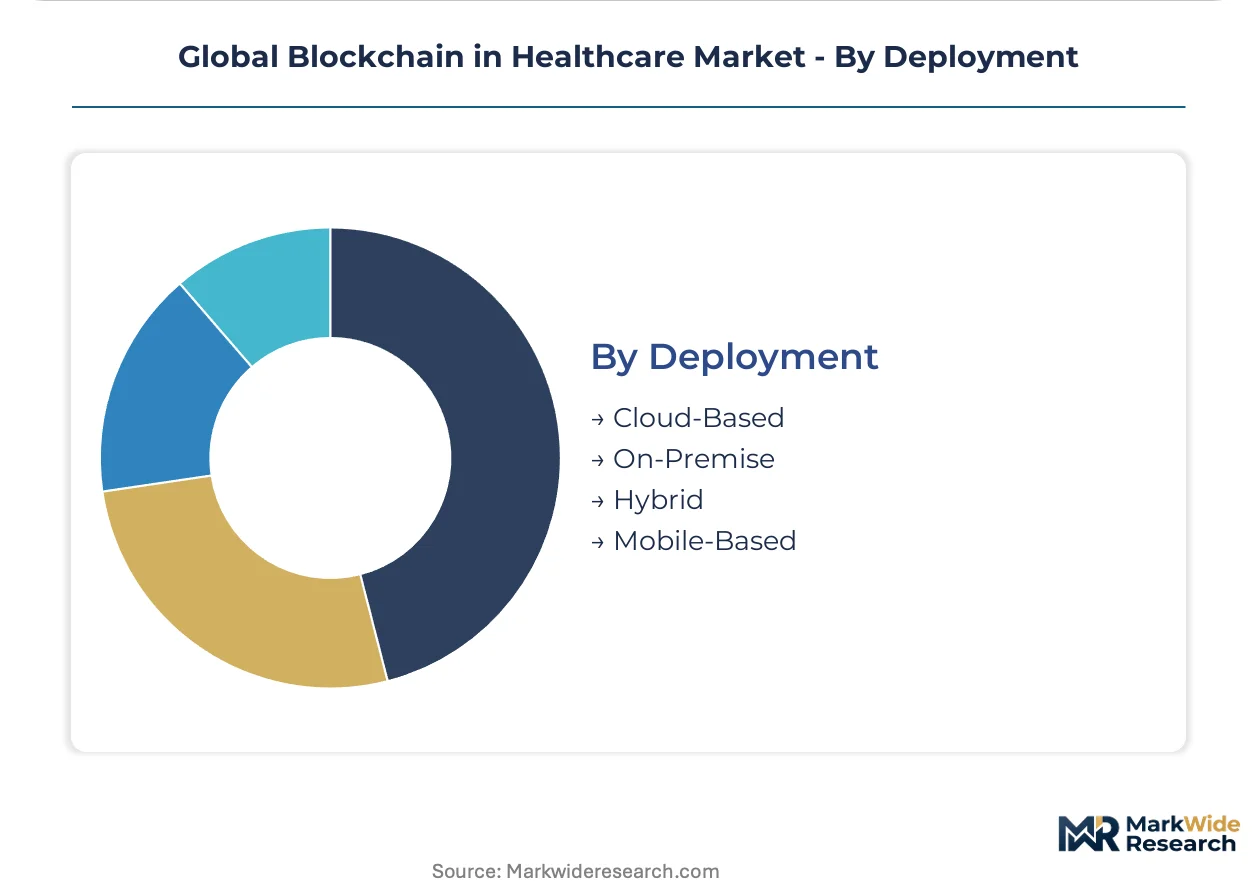
Deployment:
Infrastructure economics separate buyers by balance-sheet capacity and regulatory risk tolerance.
- Cloud-Based:Subscription node management eliminates upfront infrastructure investment, enabling mid-sized hospital systems and European contract research organizations to deploy compliant architectures without dedicated IT staff. Microsoft and IBM bundle regulatory update guarantees with compute resources, concentrating purchasing power among hyperscalers.
- On-Premise:Self-hosted infrastructure satisfies data residency constraints under GDPR cross-border restrictions, though specialized cryptographic talent scarcity extends implementation timelines.
- Hybrid:Segmented deployments isolate PHI on private infrastructure while leveraging cloud resources for non-sensitive verification workloads.
- Mobile-Based:Lightweight client applications enable patient-facing record access and tokenized incentive participation through smartphone interfaces.
Cloud arrangements capture procurement volume; on-premise deployments retain preference where data residency constraints apply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in blockchain healthcare infrastructure tilt toward jurisdictions with stringent serialization mandates and advanced cloud ecosystems. Net exporters of ledger technology concentrate in economies with hyperscaler headquarters and pharmaceutical regulatory leadership.
United States
FDA DSCSA enforcement deadlines and HIPAA technical safeguard requirements drive procurement among pharmaceutical distributors and hospital networks. The regulatory timeline compresses vendor selection cycles, with November compliance windows forcing infrastructure commitments. Greater Boston hosts concentrated blockchain health startups alongside academic medical centers piloting zero-knowledge proof integrations.
Germany
BfArM and EMA joint pilot programs for clinical trial documentation create urgent demand among contract research organizations. GDPR cross-border data residency constraints favor geographically distributed node configurations that inflate infrastructure costs. The Rhine-Ruhr metropolitan region anchors European pharmaceutical manufacturing, with serialization investments flowing to ledger providers serving export markets.
India
CDSCO alignment with international traceability standards stimulates adoption among generic drug manufacturers serving regulated export markets. The country's pharmaceutical export dependency creates compliance-driven procurement urgency. Hyderabad and Ahmedabad clusters concentrate active ingredient production where batch provenance systems satisfy foreign regulator documentation requirements.
Switzerland
Swissmedic oversight of pharmaceutical quality combines with banking secrecy culture to favor privacy-preserving ledger architectures. The regulatory environment supports zk-SNARK deployments that validate supply chain data without exposing competitive sourcing information. Basel's pharmaceutical headquarters density drives enterprise blockchain spending for cross-border clinical data exchange.
United Kingdom
NHS digital transformation targets and post-Brexit regulatory autonomy shape procurement distinct from EU harmonization paths. MHRA divergence from EMA frameworks creates interoperability complexity for multinational health networks. London's fintech and health tech convergence supports pilot programs for tokenized patient incentive models distinct from continental European approaches.
Global Blockchain in Healthcare Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cryptographic tooling and consensus mechanism design. Market structure concentrates around cloud hyperscalers with regulatory compliance bundling capabilities and boutique health ledger specialists with clinical workflow expertise. Two strategic archetypes dominate: enterprise infrastructure providers leveraging existing cloud contracts, and vertical specialists offering tokenized patient-facing platforms. Competitive moves center on subscription model displacement of perpetual licenses and zero-knowledge proof capability acquisition.
Within the enterprise infrastructure tier, IBM and Microsoft exemplify divergent approaches to healthcare blockchain deployment. IBM leverages Hyperledger Fabric deployments across multi-hospital networks to sustain recurring revenue from node management services. Microsoft anchors enterprise demand through Azure Blockchain Workbench integrations with existing cloud contracts. Patientory occupies a distinct position among consumer-facing health record portability platforms, differentiating its tokenized incentive model from institutional-focused rivals.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Patientory |
| Hashed Health |
| BurstIQ |
| Akiri |
| Guardtime |
| Avaneer Health |
| Chronicled |
| Others |
Supply Flow & Price Mechanics
The transatlantic fiber corridor connecting Frankfurt to Ashburn anchors infrastructure cost dynamics for blockchain healthcare deployments, concentrating pricing power among cloud hyperscalers while forcing mid-sized hospital systems toward subscription models that absorb capital expenditure volatility.
Pricing Analysis
Industrial OEM buyers anchor subscription-based node management as the dominant pricing structure, with pharmaceutical distributors facing FDA DSCSA deadlines accepting premium tiers bundling regulatory update guarantees. Price differentiation rests on HIPAA certification grade and geographic node distribution requirements under GDPR cross-border constraints. Cost compression in mid-market cloud tiers is intensifying because hyperscalers leverage existing compute contracts to undercut specialized ledger vendors. Generic drug manufacturers in India exhibit highest price sensitivity, while academic medical centers piloting zero-knowledge proof integrations show lowest sensitivity due to research grant funding.
Supply Chain Analysis
Extended payment terms from cloud hyperscalers to cryptographic hardware suppliers have restructured working capital requirements across the vendor base. Geographic supply concentrates in the United States, Germany, and India, with node infrastructure drawing from specialized semiconductor foundries in Taiwan and cryptographic security module manufacturers in Switzerland. Raw material dependencies span high-performance computing chips, quantum-resistant encryption hardware, and fiber optic transmission equipment. Single-source vulnerability in zero-knowledge proof implementation talent constrains deployment velocity. Distribution runs through direct enterprise sales teams for pharmaceutical clients and channel partners for mid-sized hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain healthcare infrastructure operates as a defensive-moat market where regulatory entrenchment creates switching costs that protect incumbent positions against specialized challengers.
For Market Incumbents: Harden compliance bundling capabilities by embedding FDA DSCSA and EMA documentation rules directly into automated node management services, neutralizing emerging competition from pure-play cryptographic specialists. Pursue backward integration into zero-knowledge proof research through captive academic partnerships, securing talent pipelines that constrain rival deployment velocity. Vertical capacity expansion in Germany's Rhine-Ruhr corridor captures BfArM pilot program procurement before interoperability standards crystallize. For New Entrants and Emerging Players: Establish a beachhead in tokenized patient incentive models for United States consumer-facing platforms, where institutional rivals underinvest due to enterprise contract concentration. Target mid-sized European contract research organizations seeking consortium blockchain alternatives to IBM and Microsoft dependency. Deploy open-source tooling with regulatory compliance wrappers as the primary go-to-market angle, converting experimental budgets into production commitments. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical manufacturers spinning out internal blockchain units as compliance mandates mature and capital allocation priorities shift. Long-term viability hinges on regulatory entrenchment depth rather than technical differentiation alone. Monitor EMA-FDA harmonization progress as the critical inflection signal for interoperability standard consolidation and vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Capability Acquisition | Swiss pharmaceutical headquarters demand privacy-preserving batch verification without competitive data exposure. |
| Subscription Model Migration | Multi-hospital United States networks favor operational expenditure arrangements with bundled regulatory guarantees. |
| Consortium Governance Structuring | Germany's BfArM pilots accelerate European contract research organization adoption without single-vendor lock-in. |
| HIPAA Technical Safeguard Certification | FDA-regulated distributors require granular access controls as table stakes for pharmaceutical procurement. |
| Cloud-Native Compliance Tooling Integration | Microsoft and IBM leverage existing enterprise contracts to capture mid-sized hospital system volume. |
Methodological Framework
The analysis maps private blockchain deployments, consortium governance structures, and tokenized patient platforms, each validated through pharmaceutical supply chain executives, hospital IT procurement officers, and regulatory affairs specialists at contract research organizations. Primary interviews with cloud infrastructure architects and cryptographic security engineers combined with secondary validation from FDA DSCSA guidance documents, EMA pilot program disclosures, and hospital procurement database records. Bottom-up deployment estimates triangulate against top-down pharmaceutical compliance spending projections.
Analytical assumptions held regulatory enforcement timelines and cloud hyperscaler pricing structures fixed across the modeling period, while varying adoption curves by hospital system size and geographic regulatory cluster. Segmentation dimensions modeled include technology architecture, application workflow, end-user sophistication, and deployment model complexity. CAGRs derive from regression analysis of historical compliance-driven procurement cycles and cloud infrastructure penetration patterns. Forecast inputs incorporate pharmaceutical serialization mandate deadlines and GDPR cross-border data residency enforcement intensity.
Sensitivities concentrate around EMA-FDA harmonization progress, zero-knowledge proof standardization velocity, and cloud hyperscaler competitive pricing aggression. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cryptographic talent supply elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Blockchain in Aviation Market