
 Blockchain in Pharmaceutics Market | 2026-2036
Blockchain in Pharmaceutics Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Pharmaceutics Market Insights
Market Context
Multi-source vendor arrangements for blockchain infrastructure is consolidating around a smaller set of platform providers with proven pharmaceutical deployments. IBM leverages its Hyperledger Fabric deployments to anchor enterprise-grade supply chain networks for major drug manufacturers. Microsoft competes through Azure Blockchain Workbench integrations that extend cloud-native compliance tooling to contract research organizations. Guardtime differentiates with its KSI blockchain technology, which specializes in data integrity verification for clinical trial documentation across European health systems.
Technical Definition and Segment Structure
Blockchain in pharmaceutics denotes immutable distributed ledger systems that cryptographically timestamp and link transactional records across decentralized nodes, typically employing consensus mechanisms such as proof-of-authority or Byzantine fault tolerance to ensure data integrity without single-point vulnerabilities. These systems serve primarily to eliminate information asymmetries in multi-party pharmaceutical workflows, from active ingredient sourcing through patient dispensing. Supply chain management applications currently dominate deployment value, as private blockchain configurations capture the largest margin pools by offering permissioned access controls that satisfy pharmaceutical companies' confidentiality requirements. Drug traceability represents the fastest-growing application segment, driven by regulatory serialization mandates that demand interoperable verification layers across national borders.
Regulatory Framework
The FDA, EMA, and EU Falsified Medicines Directive collectively shape demand by mandating unit-level traceability and verification infrastructure that only blockchain-native architectures can cost-effectively deliver at scale. HIPAA in the United States and GDPR in Europe impose additional data governance constraints that favor permissioned ledger designs with granular access controls and audit trails. Stakeholders must monitor evolving interoperability standards between national drug verification systems, as regulatory divergence threatens to fragment platform architectures and inflate compliance costs for multinational pharmaceutical operations.
Market Dynamics
Serialization mandates from the FDA Drug Supply Chain Security Act and the EU Falsified Medicines Directive are forcing pharmaceutical manufacturers to replace paper-based pedigree systems with cryptographically verifiable distributed ledgers, compressing deployment timelines across wholesale distribution networks.
Growth Catalysts
- Regulatory Compliance Deadlines:The FDA Drug Supply Chain Security Act mandates unit-level traceability by 2023 for manufacturers, with dispensers following by 2025, creating irreversible procurement pressure.
- Cold-Chain Integrity Requirements:Temperature-sensitive biologics demand immutable temperature logging across multi-party handoffs, driving adoption in mRNA vaccine distribution networks.
- Active Ingredient Sourcing Complexity:Indian and Chinese API suppliers face heightened scrutiny from European and American drug makers seeking cryptographic provenance verification.
Market Restraints
- Interoperability Fragmentation:Divergent national verification system architectures between the United States and European Union threaten to inflate compliance costs for multinational operations.
- Technical Talent Scarcity:Blockchain-savvy engineers with pharmaceutical domain expertise command premium compensation, constraining deployment velocity for mid-tier manufacturers.
- Legacy System Integration Burden:Enterprise resource planning systems from SAP and Oracle require expensive middleware development to interface with distributed ledger networks.
Strategic Opportunities
- Clinical Trial Documentation:Regulatory bodies in Germany and Estonia are piloting KSI-based integrity verification for electronic health records, opening new application vectors beyond supply chain.
- Patient-Centric Data Monetization:Permissioned ledger designs with granular consent management enable direct-to-patient compensation models for real-world evidence contributions.
- Generics Manufacturer Compliance:Indian contract manufacturers serving export markets represent an underpenetrated segment facing imminent serialization deadlines for EU and US shipments.
Industry Challenges
- Cross-Chain Communication Standards:Absence of unified protocols between Hyperledger Fabric, R3 Corda, and Ethereum enterprise implementations complicates multi-vendor network participation.
- Validation Timeline Compression:Pharmaceutical IT departments must complete computer systems validation for novel distributed architectures within compressed regulatory windows, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Pharmaceutics Market |
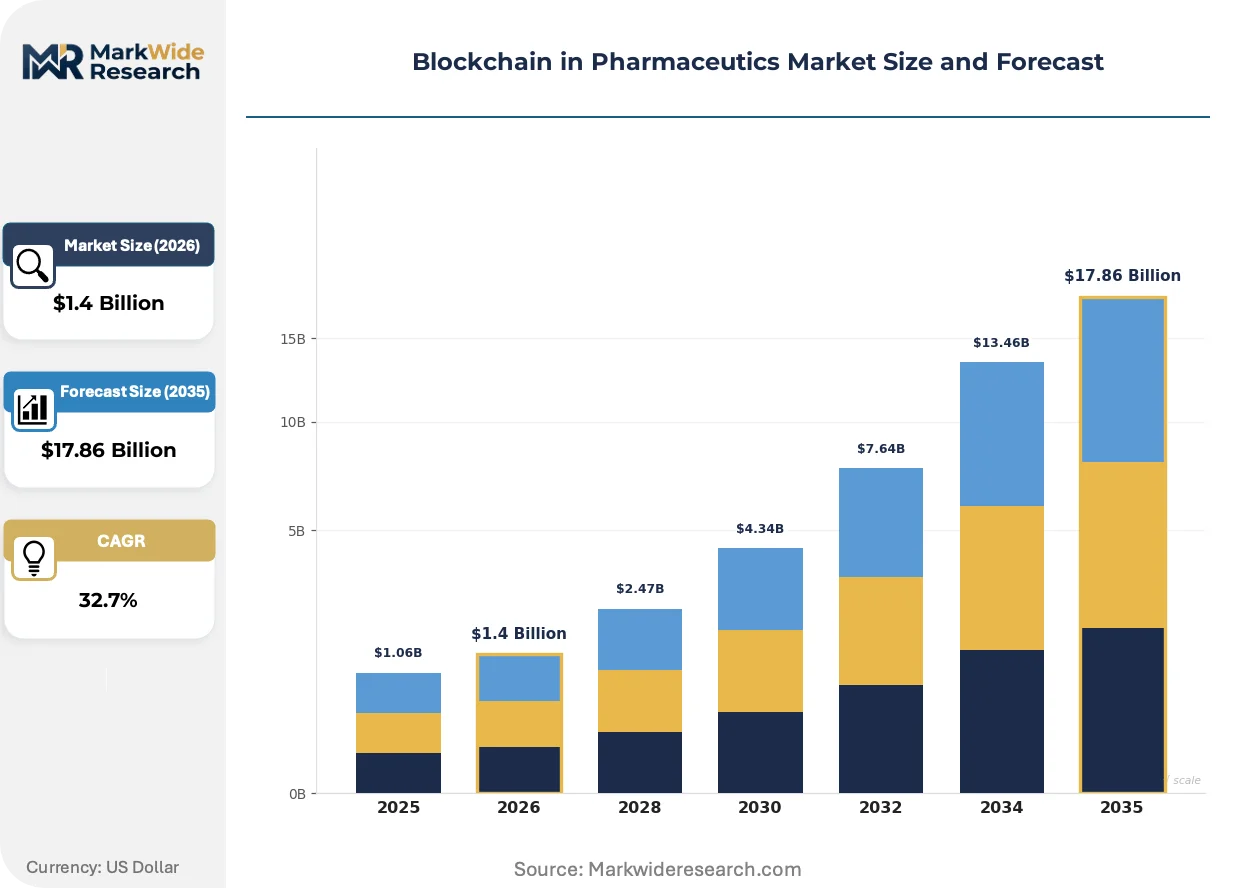
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $17.86 Billion |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Drug Traceability, Clinical Trials, Regulatory Compliance Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain End User: Pharmaceutical Companies, Contract Research Organizations, Distributors, Regulatory Authorities Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | IBM, Microsoft, Oracle, Guardtime, BurstIQ, PharmaLedger, MediLedger, PharmaTrust, Blockpharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Pharmaceutics Market Trends and Innovations
Distributed ledger architectures are fragmenting into specialized configurations optimized for distinct pharmaceutical workflows, with consensus mechanisms and access controls diverging sharply between supply chain and clinical applications.
Zero-knowledge proof implementations are modularizing how pharmaceutical companies share sensitive batch records with regulators without exposing competitive formulation data. Large molecule manufacturers in Switzerland and Massachusetts are piloting these privacy-preserving verification methods for biologics license applications. The structural consequence is modularizing compliance data exchange into discrete, auditable cryptographic attestations rather than document-heavy submissions.
The EU Falsified Medicines Directive's delegated regulation on safety features mandates interoperable verification across national systems, forcing platform providers to adopt common data formats and API specifications. This harmonization is compressing deployment timelines for cross-border European distribution networks. Generic drug manufacturers in Eastern Europe are accelerating platform procurement to meet the February 2019 enforcement deadline for prescription medicines.
Hospital pharmacy buyers are consolidating vendor relationships around integrated serialization-and-verification platforms, displacing point solutions that handled only one compliance function. This concentration is reshaping procurement evaluation criteria toward end-to-end network coverage rather than modular capability. The shift is most visible in American health systems operating centralized specialty pharmacies for oncology and rare disease therapies.
Blockchain in Pharmaceutics Market Segmentation
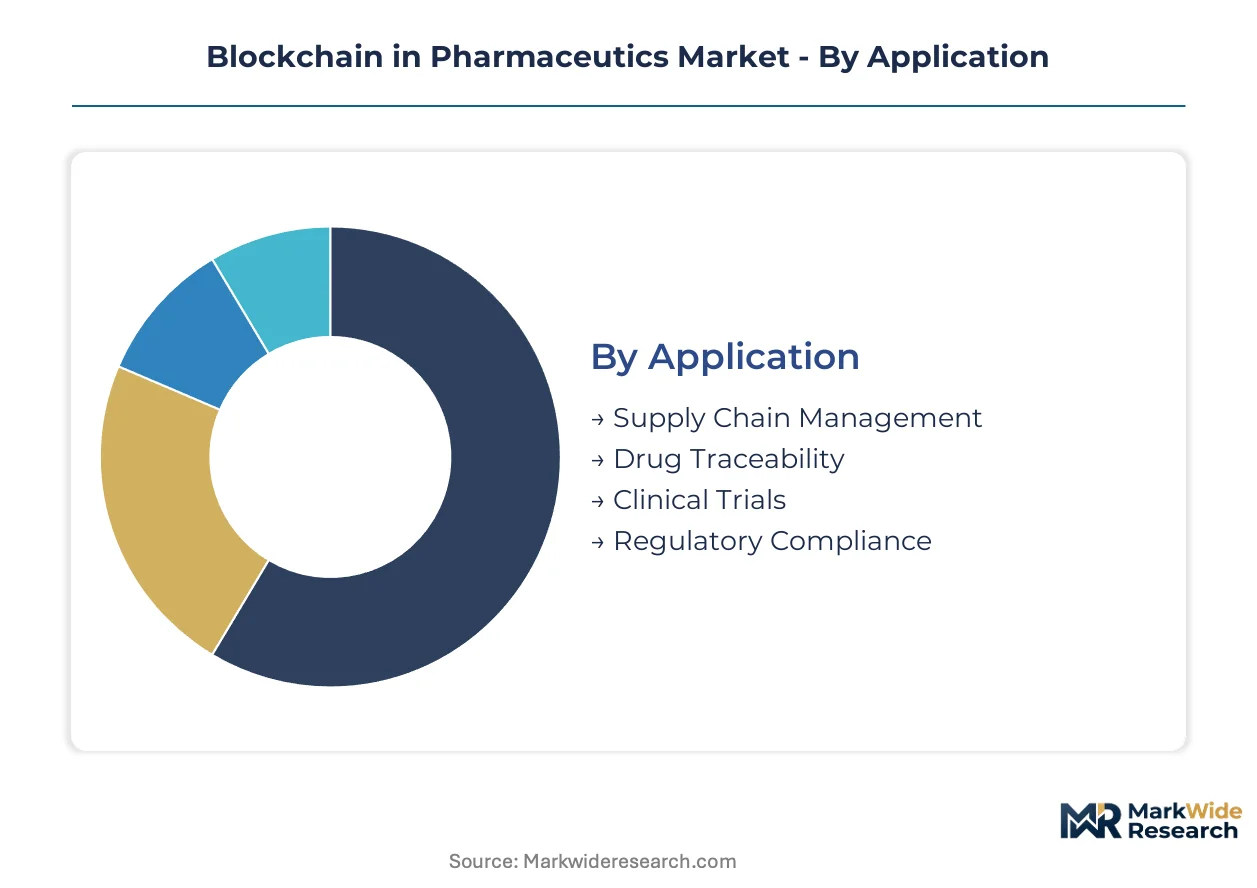
Blockchain deployments in pharmaceutics fragment across technical architectures, regulatory use cases, and operational models. Each segmentation axis carries distinct margin profiles and compliance implications that shape procurement decisions across drug manufacturers and health systems.
Application:
Permissioned ledger configurations dominate where data confidentiality intersects with multi-party verification requirements.
- Supply Chain Management:Private blockchain networks with Byzantine fault tolerance secure cold-chain handoffs from API sourcing through wholesale distribution. Temperature-sensitive biologics and mRNA vaccines drive concentrated demand from manufacturers in Switzerland and Massachusetts.
- Drug Traceability:Immutable batch serialization creates interoperable verification layers across national borders. FDA Drug Supply Chain Security Act mandates and EU Falsified Medicines Directive deadlines are compressing deployment timelines for unit-level tracking systems.
- Clinical Trials:KSI-based integrity verification protects electronic health record documentation against tampering.
- Regulatory Compliance:Automated audit trails streamline submissions to EMA and national pharmaceutical regulators.
Supply chain management leads on scale; drug traceability leads on momentum.
Technology:
Consensus mechanism selection directly determines access control granularity and transaction throughput for pharmaceutical workloads.
- Private Blockchain:Proof-of-authority protocols with permissioned node membership satisfy HIPAA and GDPR constraints on patient data exposure. Large drug manufacturers deploy these configurations for internal batch record management and supplier qualification workflows.
- Consortium Blockchain:Multi-party governance structures distribute infrastructure costs across competing manufacturers within the same therapeutic category. European wholesale distributors favor this model for cross-border verification networks under the EU Falsified Medicines Directive.
- Public Blockchain:Open consensus layers remain rare in pharmaceutical applications due to confidentiality requirements.
- Hybrid Blockchain:Selective disclosure architectures anchor sensitive data on private ledgers while publishing verification hashes to public chains.
Private blockchain captures the dominant share; consortium blockchain is climbing the fastest as multi-stakeholder networks mature.
End User:
Procurement authority concentrates with entities bearing direct regulatory liability for serialization and traceability compliance.
- Pharmaceutical Companies:Brand-name manufacturers with complex global supply chains invest in end-to-end provenance infrastructure. These organizations face the steepest penalties under the FDA Drug Supply Chain Security Act for non-compliant unit-level tracking.
- Contract Research Organizations:Clinical trial administrators adopt blockchain for patient consent management and data integrity verification. Estonia and Germany are piloting KSI-based electronic health record systems that extend procurement timelines for CROs serving European sponsors.
- Distributors:Wholesale networks require interoperable verification nodes to satisfy dispenser-level traceability mandates.
- Regulatory Authorities:Government agencies deploy permissioned observer nodes to automate compliance monitoring without accessing proprietary formulation data.
Pharmaceutical companies anchor investment volume; contract research organizations show the steepest expansion trajectory as clinical applications diversify.
Deployment:
Infrastructure location decisions trade data sovereignty against operational flexibility and total cost of ownership.
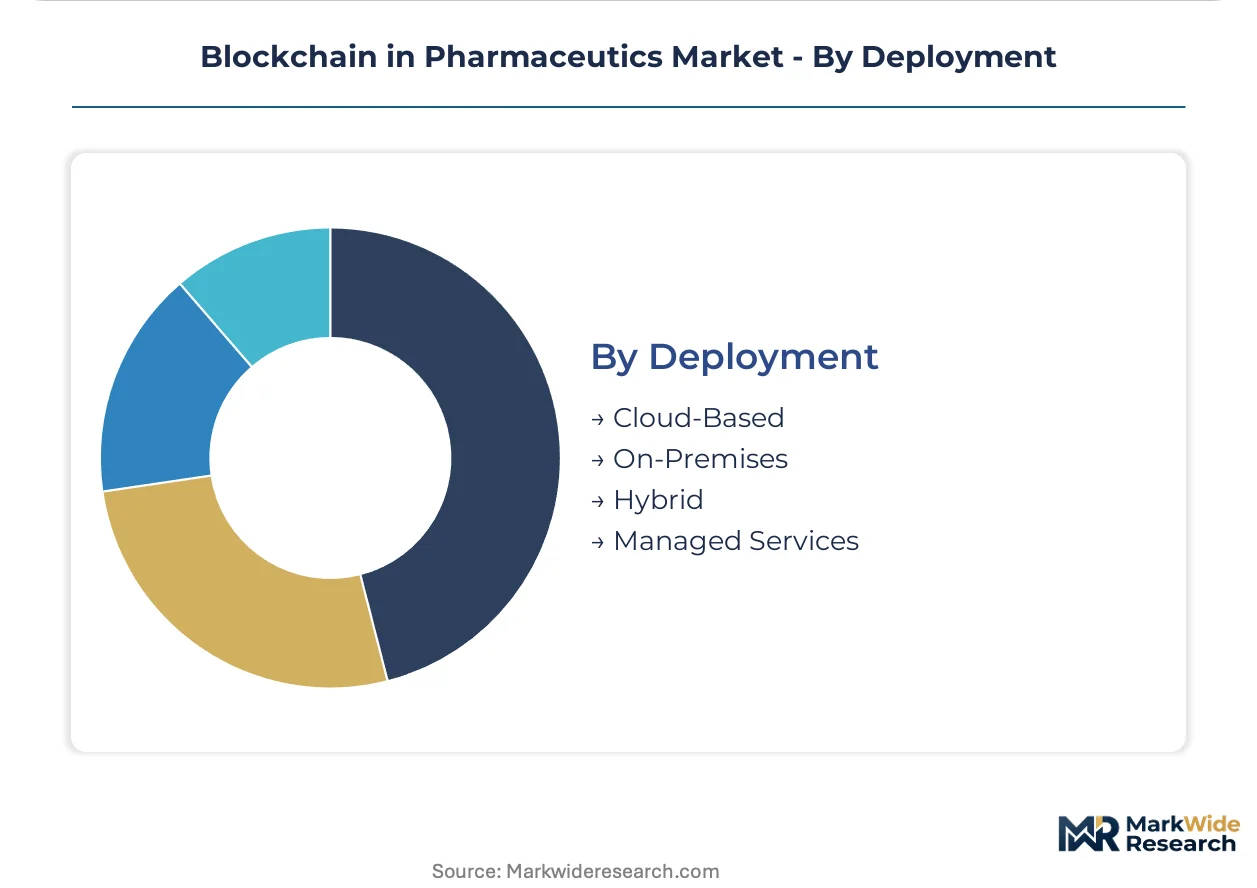
- Cloud-Based:Hyperscaler-hosted ledger nodes reduce capital expenditure for mid-tier generic manufacturers facing compressed compliance deadlines. Azure Blockchain Workbench and Hyperledger Fabric on IBM Cloud dominate procurement evaluations for their pre-validated compliance tooling.
- On-Premises:Captive data centers satisfy strictest interpretations of data residency requirements under GDPR and national pharmaceutical regulations. Swiss and German manufacturers favor this model for biologics license applications involving trade-secret formulation data.
- Hybrid:Split architectures anchor sensitive records on-premises while leveraging cloud nodes for cross-border verification.
- Managed Services:Third-party operators handle node maintenance and software updates for organizations lacking blockchain engineering capacity.
Cloud-based deployment leads on adoption breadth; on-premises leads on contract value per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping blockchain deployment patterns as pharmaceutical manufacturers migrate compliance infrastructure toward jurisdictions with harmonized serialization standards and lower cost-of-compliance thresholds. The United States and European Union maintain the steepest mandates, while India and Switzerland emerge as alternative operational bases for firms seeking streamlined verification architectures.
United States
FDA Drug Supply Chain Security Act deadlines compress procurement timelines for unit-level traceability systems. Massachusetts and New Jersey pharmaceutical clusters drive concentrated demand for Hyperledger Fabric deployments among large molecule manufacturers. Hospital pharmacy buyers in these states consolidate vendor relationships around integrated serialization platforms.
Germany
EU Falsified Medicines Directive enforcement accelerates platform procurement across wholesale distribution networks. The country's national pharmaceutical regulator mandates interoperable verification nodes for cross-border European shipments. Bavaria-based generic manufacturers accelerate cloud-based ledger adoption to meet compressed compliance windows.
Switzerland
Swissmedic biologics licensing requirements favor on-premises blockchain configurations for trade-secret formulation data. Basel and Zurich pharmaceutical clusters pilot zero-knowledge proof implementations for regulatory submissions. Temperature-sensitive biologics distribution drives private ledger investment across Alpine logistics corridors.
India
CDSCO export compliance deadlines for EU and US shipments force contract manufacturers toward cryptographic provenance verification. Maharashtra and Gujarat API suppliers face heightened scrutiny from European and American drug makers. Hyderabad and Ahmedabad clusters represent underpenetrated segments facing imminent serialization mandates.
United Kingdom
Post-Brexit divergence from EU verification systems threatens interoperability costs for multinational operations. The Medicines and Healthcare products Regulatory Agency maintains alignment with EMA traceability standards while developing independent infrastructure. London-based contract research organizations pilot KSI-based integrity verification for clinical trial documentation.
Blockchain in Pharmaceutics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clinical trial and patient-centric data applications beyond core supply chain verification. The vendor base stratifies across three functional layers: hyperscaler-hosted platform providers, specialized blockchain infrastructure firms, and consortium-governed industry utilities. Dominant competitive moves include strategic partnerships between ledger technology vendors and pharmaceutical ERP system integrators, plus geographic expansion into Indian and Chinese contract manufacturing markets facing export compliance deadlines.
Within the enterprise platform tier, IBM and Microsoft exemplify divergent architectural approaches to pharmaceutical compliance workloads. IBM leverages its Hyperledger Fabric deployments to anchor permissioned supply chain networks for major drug manufacturers. Microsoft competes through Azure Blockchain Workbench integrations that extend cloud-native tooling to mid-tier generic producers. Guardtime occupies a specialized position with KSI blockchain technology for clinical trial documentation integrity across European health systems.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| Guardtime |
| BurstIQ |
| PharmaLedger |
| MediLedger |
| PharmaTrust |
| Blockpharma |
| Others |
Pricing and Supply Chain Analysis
Large drug manufacturers with complex global supply chains command the dominant pricing power in blockchain procurement, forcing platform vendors toward subscription-based SaaS tiers with volume-scaled discounts rather than perpetual licensing models.
Pricing Analysis
Distributor margin compression shapes the dominant pricing structure. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity and validation requirements. Price differentiation hinges on certification grade (FDA-validated versus non-validated configurations) and customization depth. Pricing pressure stems from mid-tier generic manufacturers demanding pre-validated cloud templates. Hospital pharmacy buyers show the highest price sensitivity; Swiss biologics manufacturers the lowest.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive hardware components complicates on-premises deployment economics. Supply concentrates in the United States, Germany, and Switzerland for enterprise-grade ledger infrastructure. Component sourcing draws from Taiwanese semiconductor foundries, German industrial server manufacturers, and Indian software engineering centers. Single-source vulnerability around Hyperledger Fabric-certified hardware modules threatens network expansion timelines. Distribution runs through hyperscaler marketplaces and specialized pharmaceutical IT integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain in pharmaceutics functions as a stable compounder, with regulatory serialization mandates creating irreversible procurement cycles that insulate revenue streams from cyclical pharmaceutical R&D spending.
For Market Incumbents: Hedge against interoperability fragmentation by anchoring multi-protocol integration capabilities into core platform architectures. Deepen backward integration into FDA-validated hardware supply chains to secure deployment timelines. Prioritize certification investment for EU Falsified Medicines Directive compliance modules. For New Entrants and Emerging Players: Begin with Indian contract manufacturers facing imminent CDSCO export compliance deadlines as the most penetrable segment. Target cloud-native managed service offerings for mid-tier generic producers lacking blockchain engineering capacity. Lead with pre-validated compliance templates that compress procurement cycles. For Investors and Strategic Acquirers: Pharmaceutical ERP system integrators are the most active acquirer in this space, seeking ledger capabilities to bundle with existing SAP and Oracle deployment practices. Five-to-ten-year viability rests on regulatory mandate durability rather than technology differentiation. Monitor FDA enforcement action intensity as the critical inflection signal for platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Module Development | FDA-validated configurations capture premium pricing from Massachusetts biologics manufacturers. |
| Multi-Protocol Integration Investment | Hyperledger Fabric and R3 Corda interoperability addresses EU-US verification divergence. |
| Cloud-Native Managed Service Launch | Azure and IBM Cloud partnerships reduce capital barriers for Indian generic exporters. |
| Clinical Trial Documentation Expansion | KSI-based integrity verification opens Estonian and German health system procurement channels. |
| Zero-Knowledge Proof Pilot Programs | Swissmedic submissions for biologics licensing establish privacy-preserving verification standards. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical IT directors, regulatory affairs leads, and hospital pharmacy procurement managers; secondary analysis of FDA DSCS guidance documents, EMA traceability specifications, and ClinicalTrials.gov integrity pilot records; plus customs data on blockchain hardware imports — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include application type, consensus mechanism architecture, end-user category, and regional regulatory cluster. CAGRs were derived from deployment velocity curves weighted against compliance deadline proximity. Forecast inputs incorporated FDA enforcement calendar phasing and EU member state verification system interoperability progress.
Caveats apply where regulatory deadline extensions, cross-chain standardization breakthroughs, or hyperscaler platform discontinuations could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain Messaging Apps Market