
 North America Sports Training Market | 2026-2036
North America Sports Training Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Training Market Analytics
Modular subscription bundling of virtual coaching with wearable-linked performance analytics is recalibrating buyer choice across the North America sports training landscape. Kitman Labs Inc. leverages biometric data integration to anchor its position in athlete management platforms. Strava competes through community-driven endurance tracking that extends its reach beyond competitive athletes into recreational fitness networks. TOCA Football Inc. specializes in automated ball-delivery systems that differentiate its technical skill-development offering from generalized coaching services.
North America sports training encompasses structured physical and technical development programs delivered through in-person instruction, digital platforms, and sensor-augmented feedback systems, typically incorporating heart-rate variability monitoring, motion-capture biomechanics, and periodized load management to optimize athletic output and reduce injury incidence. Personal training and virtual coaching command premium pricing due to customization intensity, while group sessions sustain volume throughput across youth and amateur segments. Performance analysis is accelerating fastest as colleges and professional organizations integrate real-time tracking into roster decisions, and recovery programs represent an emerging margin pool as load-management science matures.
The NCAA governs collegiate athlete training protocols and compensation-linked commercial activity, while state-level high school athletic associations in Texas and California set participation and safety standards that shape program design. The FDA regulates wearable medical claims and recovery-device classifications, constraining how performance technology vendors market physiological benefits. Stakeholders must monitor how NIL rule evolution and state concussion-legislation divergence alter facility-investment priorities and liability exposure across jurisdictions.
Market Dynamics
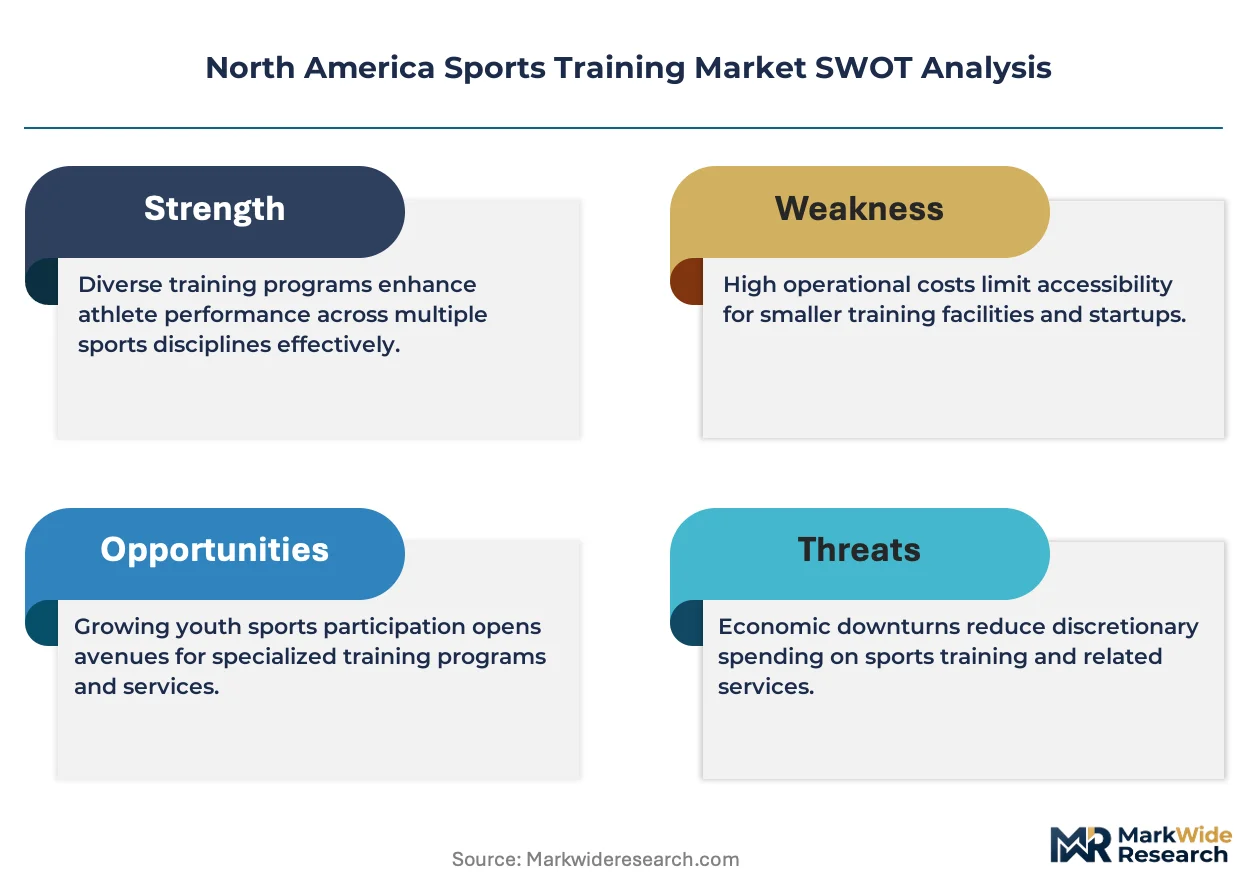
The NCAA's evolving name-image-likeness framework is redirecting capital flows toward structured training ecosystems, compelling private academies and collegiate programs to upgrade biometric monitoring infrastructure and athlete management platforms to retain competitive talent pipelines.
Growth Catalysts
- Biometric Data Integration:Wearable-linked performance analytics are creating subscription bundling opportunities across youth and amateur segments, with heart-rate variability monitoring and motion-capture biomechanics becoming standard equipment in Texas and Florida training facilities.
- NIL Commercialization:The NCAA's compensation-linked framework is accelerating investment in professional-grade training infrastructure as collegiate athletes monetize their brand value, driving demand for periodized load management and recovery programs.
- Concussion Legislation:State-level safety mandates in California and Texas are mandating sensor-augmented feedback systems for contact sports participation, expanding the addressable market for real-time impact monitoring technology.
Market Restraints
- Capital Intensity:Automated ball-delivery systems and motion-capture installations require substantial upfront facility investment, limiting expansion beyond established metropolitan training clusters in Dallas and Miami.
- Regulatory Fragmentation:Divergent state concussion protocols between Texas and California create compliance complexity for multi-location academy operators, inflating legal and operational overhead.
- Technical Limitations:Current wearable battery life and signal reliability constraints restrict continuous load monitoring during extended outdoor endurance sessions, compressing actionable data windows.
Strategic Opportunities
- Underpenetrated Markets:Secondary metropolitan areas in the US Southeast lack density of automated technical skill development, presenting first-mover potential for standardized academy franchising models.
- Recovery Science Maturation:Load-management science is creating premium service tiers around cryotherapy, compression therapy, and sleep optimization that command recurring revenue streams beyond traditional coaching.
- Virtual-Physical Convergence:Blended delivery models combining in-person biomechanical assessment with remote coaching platforms are opening rural and exurban markets previously excluded from elite training access.
Industry Challenges
- Specialized Coaching Talent Scarcity:Certified performance analysts and biomechanics specialists command premium compensation, constraining scalable service delivery across expanding academy networks.
- Technology Integration Complexity:Legacy facility management systems resist seamless API connections with emerging athlete management platforms, fragmenting data workflows and degrading coaching decision velocity.
- Certification Timeline Compression:Rapid evolution of FDA device classifications for recovery equipment creates regulatory uncertainty, delaying product commercialization and inflating compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Training Market |
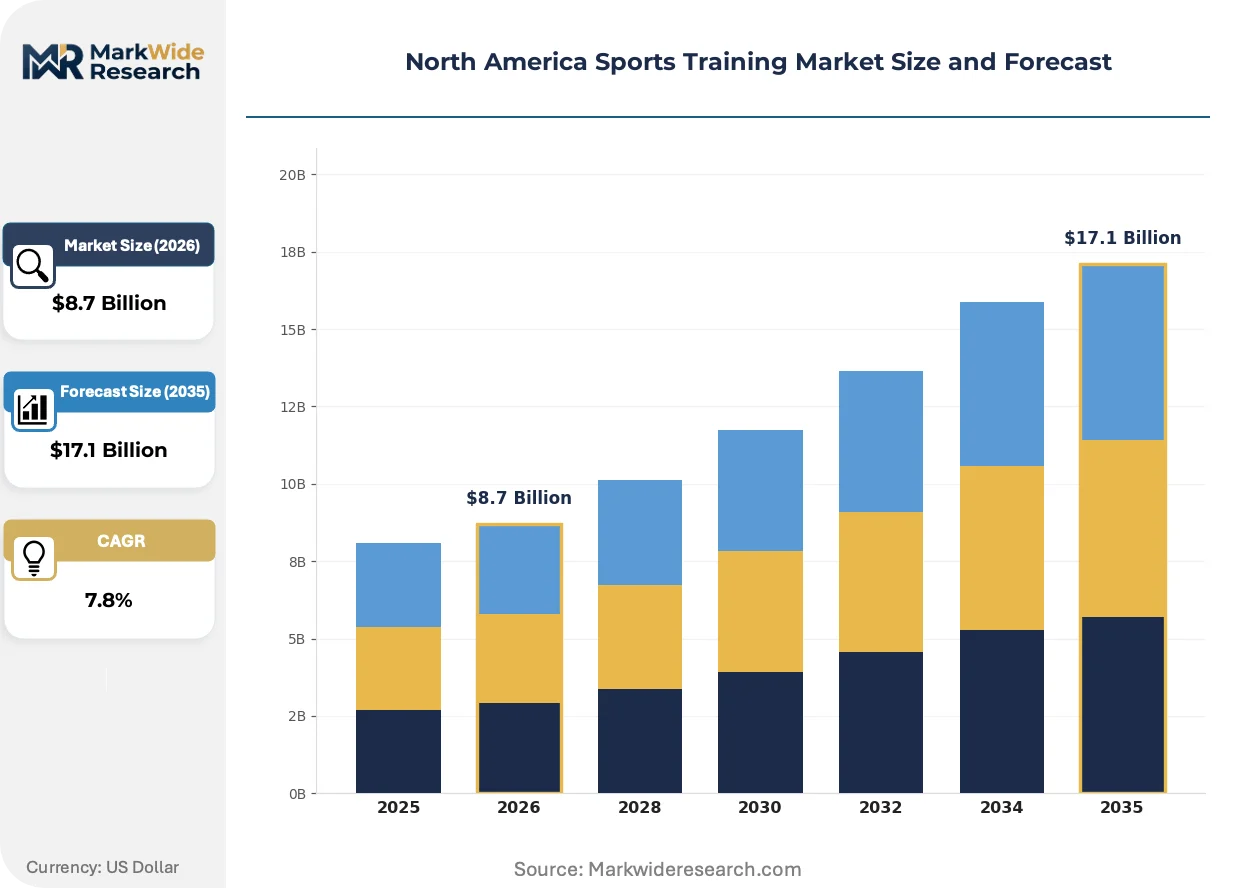
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Training, Group Sessions, Virtual Coaching, Performance Analysis End User: Athletes, Coaches, Fitness Enthusiasts, Schools Training Method: Strength Training, Endurance Training, Skill Development, Recovery Programs Equipment Type: Weights, Cardio Machines, Resistance Bands, Training Aids |
| Companies Covered | Strava, WaveOn Health, Inc, i9 Sports Corporation, X3 Sports, Brodie Sports Group, Kitman Labs Inc., GameChanger, Dynamic Sports Training, TOCA Football Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Training Market Evolving Landscape
Sensor-augmented feedback systems are compressing the coaching feedback loop from days to seconds, while regulatory pressure on athlete safety and shifting compensation models reshape how training value is captured and delivered across the North American landscape.
Motion-capture biomechanics platforms are unifying technical skill assessment with injury-risk prediction. Collegiate athletic departments and professional organizations are adopting these systems at accelerated procurement cycles. This convergence is unifying previously siloed coaching, medical, and strength-conditioning departments into integrated athlete performance units that share real-time data streams.
State concussion legislation in Texas and California is mandating baseline cognitive testing and return-to-play protocols for high school contact sports. These requirements are forcing training facilities to employ certified athletic trainers and invest in impact-sensor inventory. The scholastic segment is responding by outsourcing compliance management to specialized third-party providers rather than building in-house expertise.
Subscription bundling is displacing à-la-carte service purchasing across youth and recreational segments. Parents and amateur athletes are consolidating virtual coaching, wearable analytics, and facility access into single recurring payments. This shift is most visible in Florida's dense private academy networks, where membership retention now depends on demonstrating measurable performance improvement rather than facility amenities alone.
North America Sports Training Market Segmentation
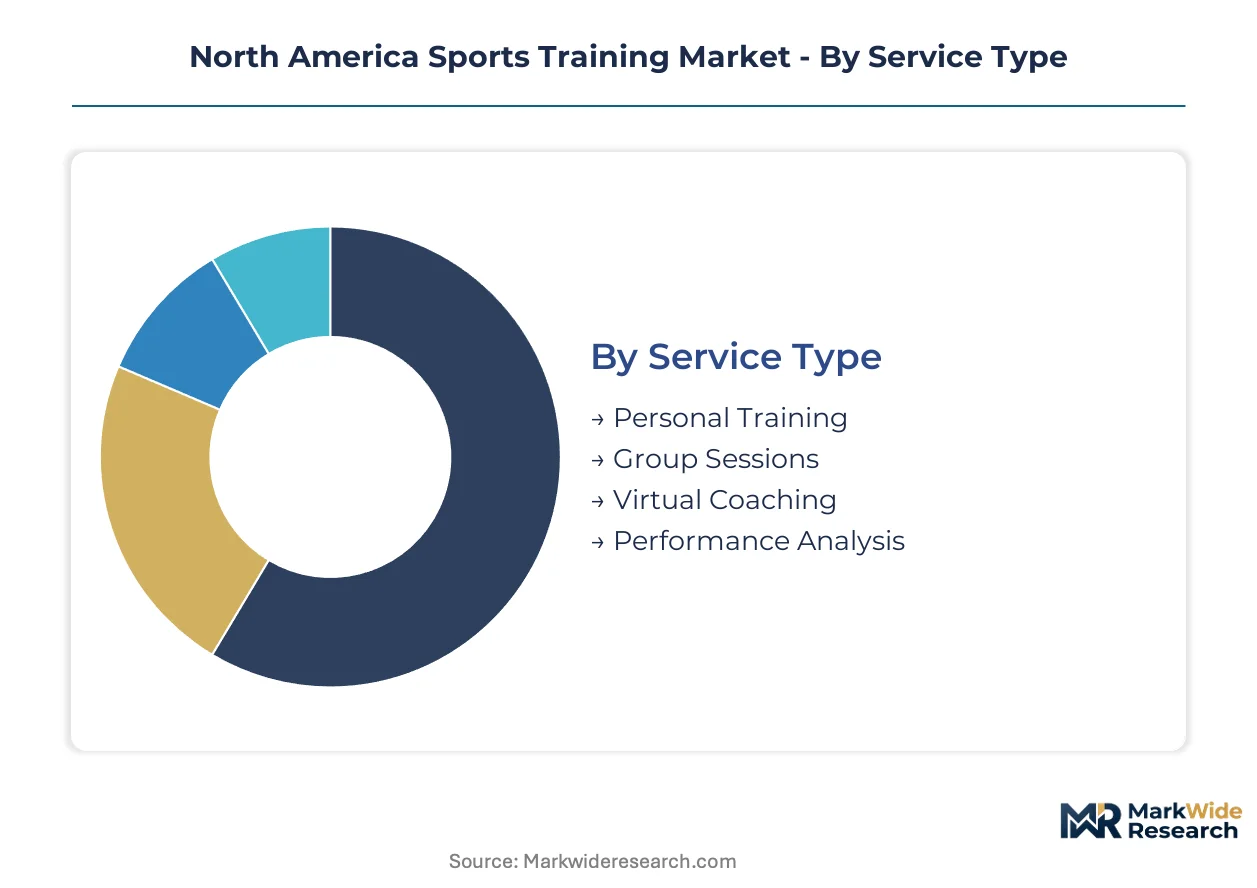
Segmentation in sports training reveals how value pools split between premium customization and volume throughput. Each dimension exposes distinct margin structures and capital intensity requirements across the North American landscape.
Service Type:
Volume throughput concentrates in standardized delivery formats, while premium tiers anchor on biometric personalization and one-to-one instruction intensity.
- Personal Training:One-to-one instruction protocols incorporating heart-rate variability monitoring and periodized load management command the highest per-session rates. Demand clusters in Texas and Florida private academies where NIL commercialization drives investment in professional-grade individual development.
- Group Sessions:Standardized curriculum delivered to cohorts of 8-20 participants sustains facility utilization rates and amortizes coaching costs across youth and amateur segments. Volume leadership sits with suburban Dallas and Miami metropolitan clusters where population density supports recurring enrollment.
- Virtual Coaching:Remote instruction platforms with wearable-linked feedback loops reduce geographic barriers to elite programming access.
- Performance Analysis:Biomechanical assessment and motion-capture diagnostics are gaining share fastest as collegiate programs integrate real-time tracking into roster decisions.
Mature deployment sits with Group Sessions. Newer deployment is concentrated in Performance Analysis.
End User:
Commercial significance tracks compensation-linked commercial activity and institutional procurement scale rather than individual purchasing frequency.
- Athletes:Collegiate and professional competitors with monetizable brand value under NIL frameworks drive demand for integrated athlete management platforms. Texas and Florida training facilities report the densest concentration of this segment.
- Schools:High school athletic departments in California and Texas face state-mandated concussion compliance requirements that expand procurement of sensor-augmented feedback systems and certified athletic trainer services.
- Coaches:Performance analysts and technical specialists require continuing education and platform certification to maintain employment eligibility.
- Fitness Enthusiasts:Recreational participants consolidate virtual coaching, wearable analytics, and facility access into subscription bundles.
Procurement scale favors Schools. Margin expansion concentrates with Athletes.
Training Method:
Application intensity varies by injury-risk profile and load-management science maturity across contact and non-contact disciplines.
- Recovery Programs:Cryotherapy, compression therapy, and sleep optimization services command recurring revenue streams beyond traditional coaching engagement. Demand is climbing the fastest as load-management science matures and professional organizations prioritize athlete longevity.
- Skill Development:Automated ball-delivery systems and motion-capture biomechanics differentiate technical training from generalized conditioning services. TOCA Football's specialized infrastructure exemplifies capital intensity in this segment.
- Strength Training:Resistance-based protocols remain foundational across collegiate and professional programs with established equipment depreciation cycles.
- Endurance Training:Community-driven tracking platforms extend reach into recreational fitness networks beyond competitive athlete populations.
Equipment standardization dominates Strength Training. Service innovation clusters in Recovery Programs.
Equipment Type:
Supply concentration and margin structure follow manufacturing scale and connected-device integration complexity.
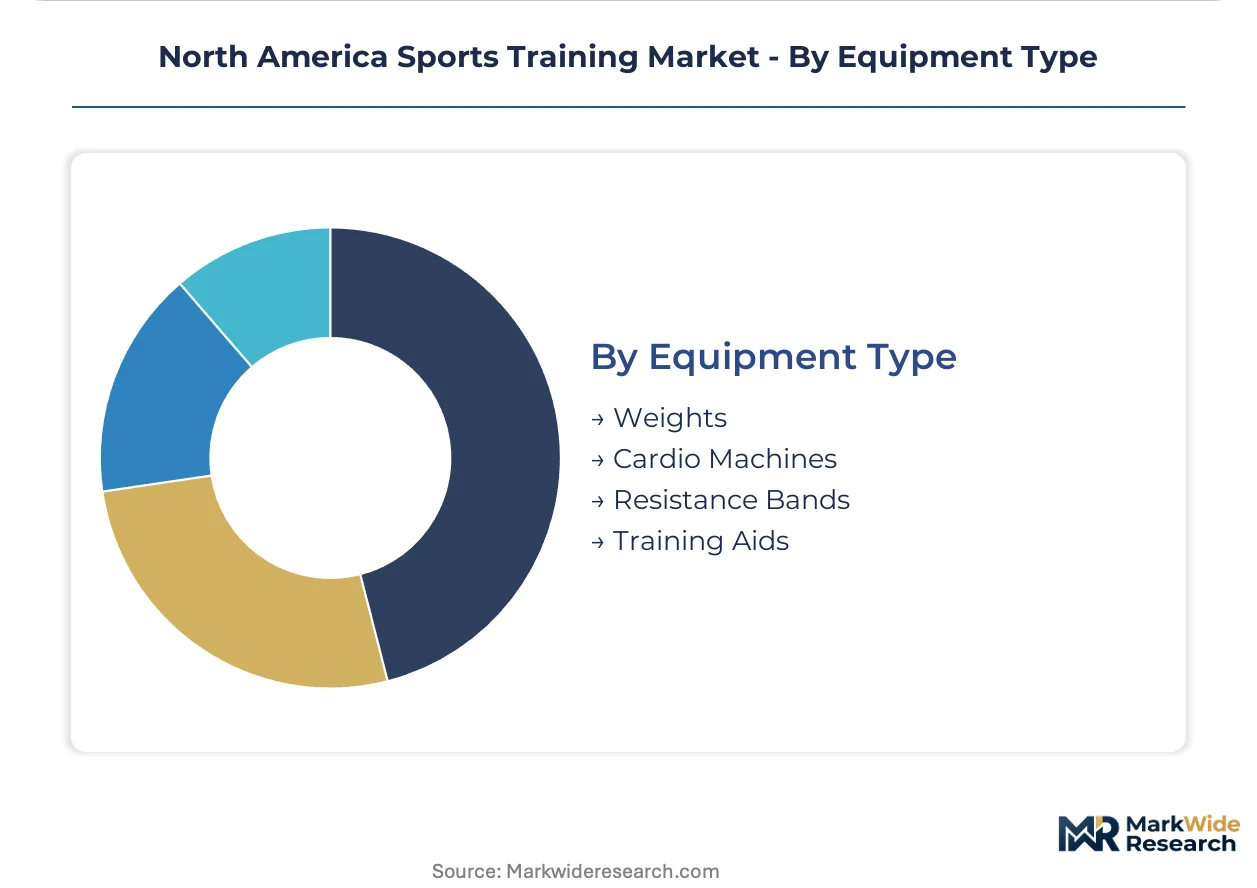
- Cardio Machines:Treadmills, rowers, and cycling equipment with embedded biometric sensors capture recurring subscription revenue through platform-linked analytics. FDA device classification constraints apply to medical claims on physiological benefit marketing.
- Training Aids:Automated delivery systems and sensor-augmented feedback devices require substantial upfront facility investment, limiting deployment to established metropolitan training clusters.
- Weights:Free-weight and plate-loaded equipment represent mature procurement categories with compressed margin profiles.
- Resistance Bands:Portable elastic training tools serve travel-competitive athletes and home-based rehabilitation protocols.
Technology integration is deepest in Cardio Machines. Price competition is most severe in Weights.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of sports training services while Canada and Mexico develop specialized export-oriented programming. Production of elite coaching talent and technology infrastructure concentrates in Texas, Florida, and California metropolitan clusters.
United States
Texas and Florida drive demand through dense collegiate athletic infrastructure and private academy networks. The NCAA's evolving NIL framework redirects capital toward biometric monitoring and athlete management platforms. Dallas and Miami metropolitan areas anchor facility investment for automated technical skill development systems.
California
State-mandated concussion legislation expands procurement of sensor-augmented feedback systems for high school contact sports. The California Interscholastic Federation enforces baseline cognitive testing and return-to-play protocols. Los Angeles and San Francisco Bay Area training facilities employ certified athletic trainers to manage compliance outsourcing demand.
Canada
Health Canada regulates wearable medical claims and recovery-device classifications, constraining physiological benefit marketing. Toronto and Vancouver metropolitan clusters concentrate hockey-specific technical skill development and motion-capture biomechanics investment. Provincial athletic associations in Ontario and British Columbia shape participation standards for youth segments.
Mexico
Federal consumer protection standards and state-level sports development programs guide facility licensing in Mexico City and Guadalajara metropolitan zones. The National Commission of Physical Culture and Sport promotes athlete development initiatives that expand access to structured training ecosystems. Northern border states leverage cross-border athletic exchange programs with Texas academies.
Southeastern United States
Secondary metropolitan areas in Georgia and North Carolina present first-mover potential for standardized academy franchising models. State high school athletic associations mandate safety equipment standards that expand addressable markets for impact-monitoring technology. Atlanta and Charlotte clusters attract investment in recovery program infrastructure as load-management science matures.
North America Sports Training Market Competitive Landscape
The competitive structure tilts toward technology-integrated platform providers over traditional facility-based operators. Market participants fragment across three tiers: biometric data specialists, automated equipment fabricators, and community-driven endurance platforms. Consolidation pressure concentrates among athlete management software vendors and wearable analytics providers. Dominant competitive moves include strategic partnerships with collegiate athletic departments and geographic expansion through standardized franchising protocols.
Within the technology-integrated tier, Kitman Labs Inc. and TOCA Football Inc. exemplify divergent specialization strategies. Kitman Labs Inc. anchors the athlete management platform archetype through biometric data integration. TOCA Football Inc. occupies a position among automated technical skill development specialists. Strava represents the community-driven endurance tracking archetype that extends reach beyond competitive athletes into recreational fitness networks. WaveOn Health, Inc. and i9 Sports Corporation sit within the youth and amateur segment service providers.
| Leading Market Players |
|---|
| Strava |
| WaveOn Health, Inc |
| i9 Sports Corporation |
| X3 Sports |
| Brodie Sports Group |
| Kitman Labs Inc. |
| GameChanger |
| Dynamic Sports Training |
| TOCA Football Inc. |
| Others |
Value Network & Pricing Analysis
Biometric sensor integration into cardio machines and training aids is compressing manufacturing cost curves while concentrating component sourcing among semiconductor fabricators in Taiwan and South Korea. This technology shift simultaneously enables subscription-linked revenue models for equipment vendors and reshapes procurement economics for facility operators across Texas, Florida, and California metropolitan clusters.
Pricing Analysis
Margin tightening in personal training and virtual coaching tiers reflects the premium commanded by heart-rate variability monitoring and motion-capture biomechanics customization. Three-tier pricing structure across premium, standard, and economy levels separates NIL-linked collegiate athlete programs from youth group sessions and recreational fitness subscriptions. Cost-down pressure on automated ball-delivery systems accelerates because capital intensity limits deployment beyond Dallas and Miami established clusters. Schools and amateur fitness enthusiasts exhibit highest price sensitivity, while professional athletes and collegiate programs with monetizable brand value demonstrate lowest sensitivity to per-session rates.
Supply Chain Analysis
Domestic-content mandates in US federal procurement guidelines are reshaping sourcing patterns for sensor-augmented feedback systems deployed in scholastic facilities. Manufacturing concentrates in China for consumer-grade wearables, Taiwan for semiconductor components, and Germany for precision motion-capture optics. Raw material dependencies include lithium-ion battery cells, optical sensors, and medical-grade elastomers for compression therapy devices. Single-source vulnerability sits with Taiwan-based foundries supplying performance analytics chipsets. Distribution runs through specialized athletic equipment distributors serving collegiate procurement departments and direct-to-facility relationships with private academy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-augmented feedback systems are displacing legacy coaching judgment across North American sports training, compressing feedback loops from days to seconds and recalibrating how value is captured and delivered.
For Market Incumbents: Anticipate regulatory fragmentation between Texas and California concussion protocols by investing in certified athletic trainer networks and compliance management platforms that standardize multi-jurisdiction operations. Vertical integration into athlete management software development protects margin pools as biometric data integration becomes table stakes for collegiate program retention. Defend position against community-driven endurance platforms by embedding social features into proprietary coaching ecosystems. For New Entrants and Emerging Players: Direct-to-consumer virtual coaching platforms with wearable-linked analytics offer the most penetrable route into rural and exurban markets previously excluded from elite training access. Secondary metropolitan areas in Georgia and North Carolina present first-mover potential for standardized academy franchising models with lower capital intensity than Texas and Florida saturation zones. Recovery program specialization—cryotherapy, compression therapy, sleep optimization—commands recurring revenue streams with less coaching talent dependency than technical skill development. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by collegiate athletic department technology vendors and private equity rollup of fragmented regional academy networks. Long-term viability favors platforms with FDA-cleared device classifications and established API integrations with legacy facility management systems. Watch for inflection signals in state NIL rule harmonization that would accelerate capital deployment into biometric monitoring infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Data Platform Integration | Kitman Labs Inc. and similar vendors anchor athlete management ecosystems through API standardization with collegiate procurement systems. |
| Automated Technical Skill Infrastructure | TOCA Football Inc.'s ball-delivery systems differentiate capital-intensive facilities from generalized coaching services in Dallas and Miami clusters. |
| Recovery Science Service Tiering | Cryotherapy and compression therapy offerings command recurring revenue beyond traditional coaching engagement as load-management science matures. |
| Virtual-Physical Delivery Convergence | Remote coaching platforms with wearable feedback loops reduce geographic barriers to elite programming access in underpenetrated Southeast markets. |
| Concussion Compliance Outsourcing | California and Texas state mandates expand third-party certified athletic trainer services as scholastic programs avoid in-house expertise buildup. |
Research Methodology
SEC filings from publicly traded fitness technology vendors, FDA device classification databases, and NCAA governance documentation formed the secondary backbone of this analysis. Primary interviews with collegiate athletic department technology procurement officers, private academy network operators, certified performance analysts, and biomechanics platform engineers validated demand-side assumptions. Bottom-up facility investment tracking across Texas, Florida, and California metropolitan clusters was triangulated against top-down collegiate sports expenditure surveys.
Historical trendline analysis of training facility capital deployment and wearable technology adoption patterns informed projection modeling across the analysis window. Segmentation dimensions included service type intensity, end-user procurement scale, training method application, and equipment technology integration depth. CAGRs were derived from regression analysis of biometric sensor penetration rates and NIL-linked infrastructure investment flows. Forecast inputs incorporated state concussion legislation implementation timelines and FDA recovery-device classification evolution.
Inputs from collegiate athletic associations and private academy financial disclosures were available through the study window; gaps in early-stage virtual coaching platform unit economics introduce uncertainty bands around subscriber lifetime value assumptions. Forecasts reflect documented assumptions regarding NIL framework stability and state regulatory harmonization. Sensor battery life constraints and coaching certification timeline compression represent specific risk factors that could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Golf Ball Market
Sports & Fitness
Hydration Belt Market
Sports & Fitness
Sports Eyewear Market
Sports & Fitness
Global Ski Poles Market
Sports & Fitness
Licensed Sports Merchandise Market
Sports & Fitness
Fat Bike Market
Sports & Fitness
Soccer Gear Market
Sports & Fitness
Flexible Wearable Device Market
Sports & Fitness
Sports Technology Market
Sports & Fitness
Ice Cleat Market
Sports & Fitness
Smart Boxing Gear Market
Sports & Fitness
Global Pickleball Equipment Market
Sports & Fitness
Europe Running Gear Market
Sports & Fitness
Knee Pads Market
Sports & Fitness
Recreational Sports Activities Market
Sports & Fitness
Global Sports Sunglasses Market