
 Sports Mouthguard Market | 2026-2036
Sports Mouthguard Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Mouthguard Market Analytics
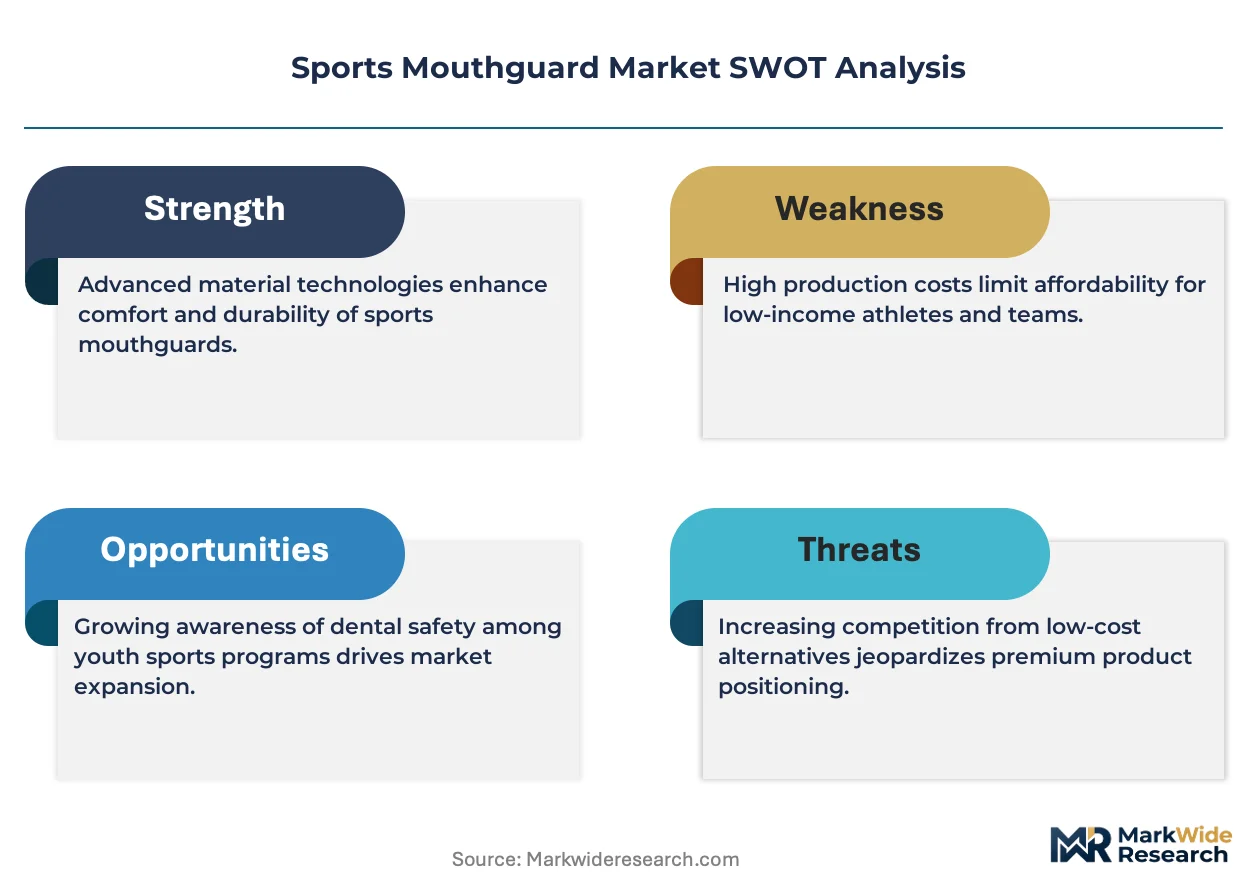
Capital-intensity divergence between custom-fabrication laboratories and mass-mold producers is bifurcating competitive dynamics. Opro leverages dental-lab partnerships to dominate precision-fit segments. Shock Doctor Inc. sustains boil-and-bite volume through pharmacy and sporting-goods channel control. Decathlon SA anchors mass-market accessibility across European retail footprints.
A sports mouthguard is a removable oral protective device fabricated from thermoplastic elastomers or ethylene-vinyl acetate copolymers, engineered to absorb and dissipate impact forces transmitted during athletic collision events. Its primary commercial purpose is preventing dental trauma, jaw fracture, and concussive injury in contact and collision sports. Custom-fitted variants command premium positioning due to dental-impression accuracy and clinician involvement, while boil-and-bite products occupy the high-velocity replacement cycle segment driven by adolescent athlete turnover. TPU formulations represent the fastest-growing material category as manufacturers balance resilience against fabrication complexity.
ASTM International publishes F2967 standards governing impact-attenuation testing protocols, while the FDA regulates mouthguards marketed with medical claims through 510(k) clearance pathways. NCAA and NFHS equipment mandates across U.S. collegiate and secondary athletics directly translate regulatory compliance into procurement requirements for schools and clubs. Stakeholders must monitor evolving state-level scholastic mandates and biomaterial certification shifts to align production capacity with compliance-driven demand inflections.
Market Dynamics
Scholastic mandate expansion across U.S. states is compressing replacement cycles and forcing manufacturers to align production with institutional procurement calendars rather than retail seasonality.
Growth Catalysts
- ASTM F2967 Compliance:Impact-attenuation testing protocols now required by NCAA and NFHS equipment rules drive bulk institutional purchases ahead of athletic seasons.
- TPU Material Advances:Thermoplastic polyurethane formulations deliver superior resilience-to-weight ratios, attracting performance-focused collegiate programs seeking competitive differentiation.
- Youth Football Concussion Protocols:State-level scholastic athletic associations mandate mouthguard use in contact drills, creating captive demand among adolescent athletes.
Market Restraints
- EVA Price Volatility:Ethylene-vinyl acetate copolymer feedstock costs fluctuate with petrochemical indices, squeezing margins for boil-and-bite mass producers.
- Dental Lab Bottleneck:Custom-fabrication capacity concentrates in licensed orthodontic laboratories, limiting precision-fit segment scalability.
- DIY Substitution Risk:Unregulated online molding kits bypass professional fitting entirely, capturing price-sensitive recreational athletes.
Strategic Opportunities
- E-Mandate States:Texas and Florida legislative sessions are advancing scholastic mouthguard requirements, opening institutional procurement pipelines.
- Direct-to-Club Distribution:Subscription models for team replenishment bypass sporting-goods retail markups and capture recurring revenue.
- Wearable Convergence:Embedded pressure-sensor integration with concussion-monitoring systems creates premium positioning for technology-forward products.
Industry Challenges
- Biocompatibility Certification Lag:FDA 510(k) clearance timelines for novel elastomer formulations extend 18-24 months, delaying product launches.
- Orthodontic Technician Scarcity:Precision-fit segment expansion requires skilled dental-laboratory technicians, a workforce with limited training pipeline capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Mouthguard Market |
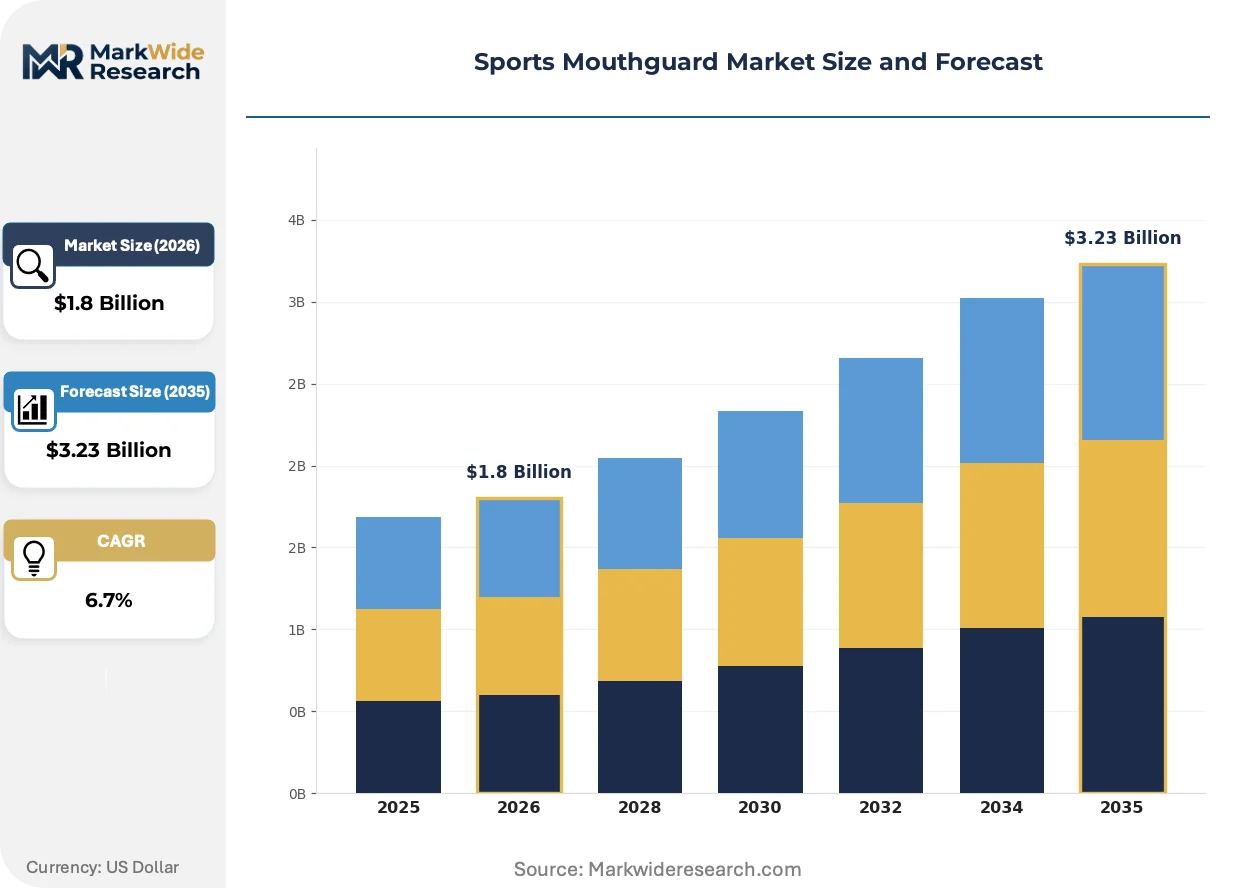
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom-Fitted, Boil and Bite, Stock, Ultra-High Performance Material: EVA, Polypropylene, Silicone, TPU End User: Athletes, Coaches, Schools, Clubs Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Shops, Pharmacies |
| Companies Covered | Opro, Brain Pad Inc., Shock Doctor Inc., Decathlon SA, Mueller Sports Medicine Inc., Nike Inc., Venum, Battle Sports Science LLC, Under Armour Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Mouthguard Market Evolving Landscape
Material science breakthroughs and regulatory harmonization are compressing product development cycles while fragmenting competitive positioning between performance tiers.
3D-printed lattice structures are fragmenting traditional thermoforming dominance. Dental laboratories and direct-to-consumer brands adopt selective laser sintering for custom-fit production at reduced per-unit labor. The technology is fragmenting manufacturing scale assumptions, enabling micro-batch production runs that match boil-and-bite price points at premium fit quality.
ASTM International is harmonizing F2967 with ISO 10268 impact-testing protocols. Multinational manufacturers now design single SKUs satisfying both U.S. scholastic and European club-sport requirements. Dual-certification products command shelf-space priority in cross-border retail channels, particularly among Canadian sporting-goods distributors serving both markets.
Club procurement officers now mandate bulk preseason purchases with mid-season replenishment clauses. Traditional retail stocking models lose ground to institutional contracts with guaranteed volume commitments. This pattern concentrates most visible in southeastern U.S. states where scholastic athletic budgets centralize equipment decisions at district rather than school level.
Sports Mouthguard Market Segmentation
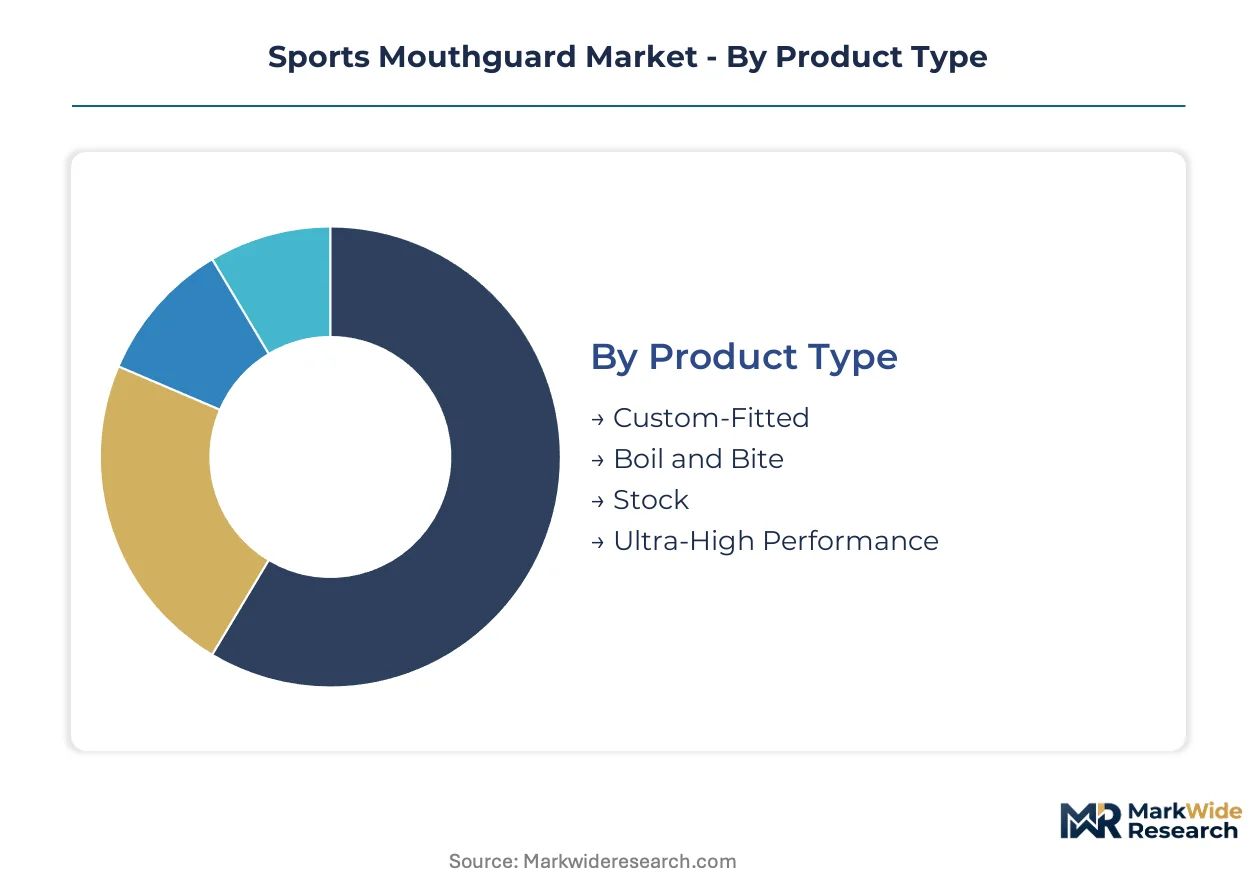
Mouthguard procurement patterns diverge sharply across product tiers and institutional channels. Segment boundaries reflect fabrication complexity, regulatory certification requirements, and the concentration of scholastic athletic mandates in specific jurisdictions.
Product Type:
Custom-fitted variants dominate export flows to markets with established dental-laboratory infrastructure, while boil-and-bite products serve high-velocity domestic replacement cycles in scholastic athletics.
- Custom-Fitted:Fabricated from dental impressions using pressure-laminated EVA or TPU composites with clinician-directed thickness gradients. Demand concentrates in NCAA Division I programs and Texas scholastic districts with centralized procurement budgets.
- Boil and Bite:Thermoformed by end-users from single-density EVA blanks, occupying the adolescent athlete segment where NFHS compliance mandates drive seasonal bulk purchases ahead of football practice windows.
- Stock:Pre-formed single-size units distributed through emergency retail channels for immediate same-day use.
- Ultra-High Performance:Multi-layer TPU laminates with embedded impact sensors targeting professional and elite collegiate programs.
Custom-fitted commands the established base. The steepest expansion runs through ultra-high performance.
Material:
Cost tier stratification separates commodity feedstocks from performance-engineered elastomers, with margin compression most severe in EVA-dependent mass production.
- EVA:Ethylene-vinyl acetate copolymers remain the volume backbone for boil-and-bite fabrication, though petrochemical price volatility squeezes producer margins.
- TPU:Thermoplastic polyurethane formulations deliver superior resilience-to-weight ratios and faster energy return, attracting Florida and California scholastic programs seeking competitive differentiation through equipment procurement.
- Polypropylene:Rigid shell components in hybrid guard designs for hockey and lacrosse facial protection systems.
- Silicone:Medical-grade formulations for orthodontic patients requiring compliance-friendly remoldability.
EVA anchors current volume. TPU is climbing the fastest on material science advances.
End User:
Customer type determines procurement rhythm, with institutional buyers compressing replacement cycles through mandated preseason purchasing windows.
- Athletes:Individual purchasers driving retail replacement through seasonal wear and loss, concentrated in contact sport participants aged 12-18.
- Schools:District-level procurement officers in Texas, Florida, and California mandating bulk purchases with mid-season replenishment clauses tied to NFHS equipment rules.
- Clubs:Independent youth leagues with decentralized purchasing authority and higher price sensitivity than scholastic systems.
- Coaches:Equipment managers influencing brand selection through team-level recommendations rather than direct procurement authority.
Schools command the established base. The steepest expansion runs through clubs adopting subscription replenishment models.
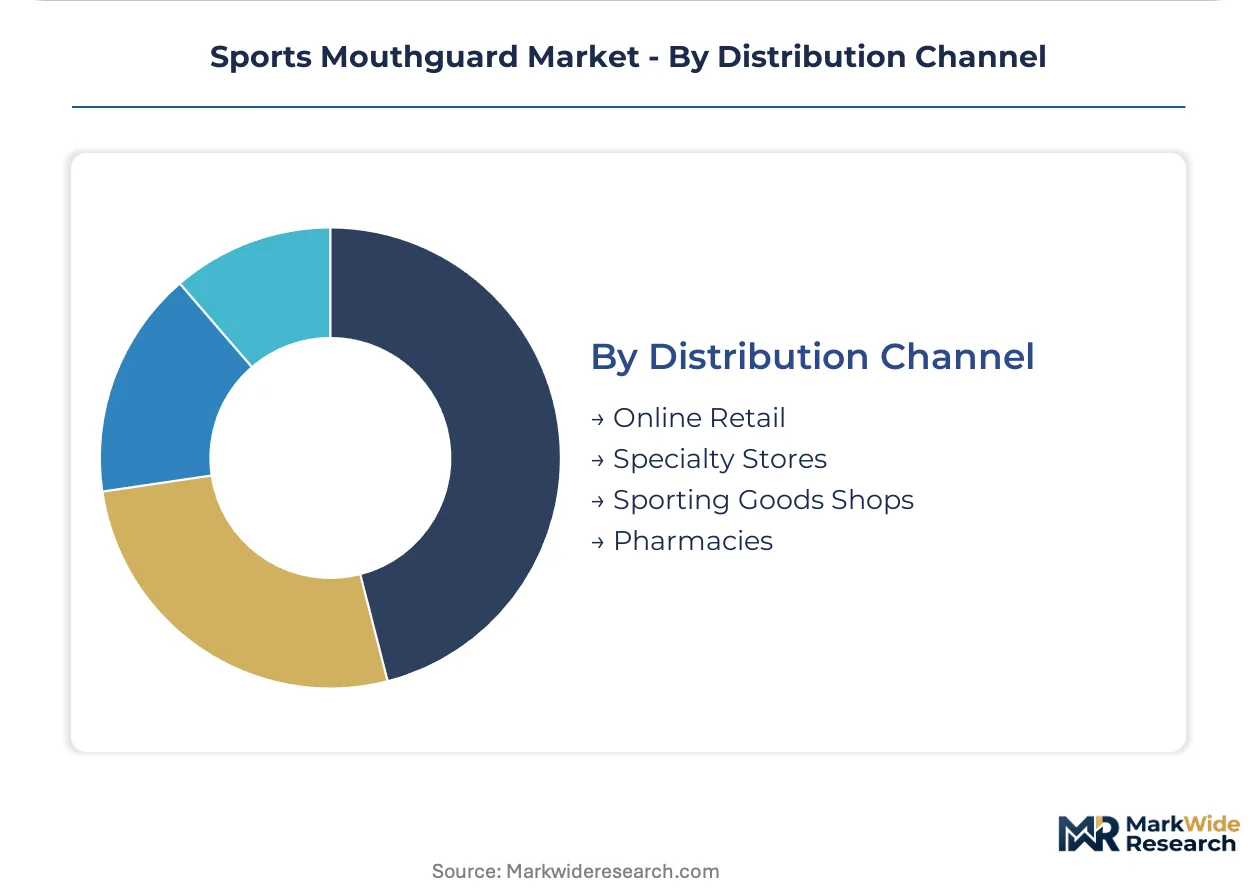
Distribution Channel:
Supply concentration in institutional procurement is displacing traditional retail seasonality, with channel control determining margin capture.
- Specialty Stores:Custom-fitting services with dental technician partnerships, concentrated in metropolitan markets with NCAA program proximity.
- Online Retail:Direct-to-consumer and direct-to-club platforms bypassing retail markups, capturing recurring revenue through team replenishment subscriptions.
- Sporting Goods Shops:Boil-and-bite volume through seasonal stocking aligned with football and hockey calendar peaks.
- Pharmacies:Emergency replacement and parental convenience purchasing with limited product assortment depth.
Specialty stores command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where scholastic mandates institutionalize procurement, while European markets fragment across club-sport retail channels with compressed margins.
United States
Texas and Florida legislative sessions are advancing statewide scholastic mouthguard requirements, opening institutional procurement pipelines. The FDA regulates medical-claim mouthguards through 510(k) clearance pathways. Dallas-Fort Worth athletic districts centralize equipment budgets at the district level, mandating bulk preseason purchases with mid-season replenishment clauses.
Germany
Club-based sports culture drives demand through decentralized hockey and handball associations. ECHA REACH compliance governs elastomer material certification for intra-EU trade. Munich and Cologne dental laboratories serve precision-fit segments for Bundesliga feeder programs.
Canada
Hockey participation rates sustain replacement-cycle volume across youth leagues. Health Canada medical device regulations align with FDA pathways for cross-border product registration. Toronto and Calgary sporting-goods distributors stock dual-certified SKUs satisfying both ASTM F2967 and ISO 10268 protocols.
Australia
Rugby and Australian rules football codes mandate mouthguard use at the state level. The TGA oversees therapeutic claims for concussion-reduction marketing. Melbourne dental technicians fabricate custom guards for AFL academy programs.
Japan
Baseball and rugby school clubs drive boil-and-bite volume through seasonal replacement cycles. METI industrial standards and JIS certification requirements shape product specifications for domestic distribution. Osaka manufacturing clusters produce EVA blanks for Southeast Asian export markets.
Sports Mouthguard Market Competitive Landscape
Concentration sits with dental-laboratory partnerships and mass-retail channel controllers. The market structures around three strategic archetypes: precision-fit specialists leveraging clinical relationships, boil-and-bit volume players capturing pharmacy and sporting-goods distribution, and mass-market retailers anchoring price-accessible segments. Competitive moves center on direct-to-club subscription models and embedded sensor technology partnerships for concussion-monitoring convergence.
Within the precision-fit tier, Opro exemplifies dental-laboratory partnership strategies. Shock Doctor Inc. and Decathlon SA occupy distinct volume positions—one through pharmacy and sporting-goods channel control, the other through European retail footprint density. These three represent the archetypal split between clinical precision, institutional procurement capture, and mass-market accessibility.
| Leading Market Players |
|---|
| Opro |
| Brain Pad Inc. |
| Shock Doctor Inc. |
| Decathlon SA |
| Mueller Sports Medicine Inc. |
| Nike Inc. |
| Venum |
| Battle Sports Science LLC |
| Under Armour Inc. |
| Others |
Value Network & Pricing Analysis
TPU displacement of EVA in performance tiers simultaneously relocates manufacturing toward German and Japanese polymer compounders and widens margin spreads between boil-and-bite commodity production and precision-fit premium fabrication. This substitution dynamic concentrates pricing power with dental laboratories capable of TPU lamination while mass producers absorb petrochemical volatility in single-density EVA blanks.
Pricing Analysis
The customization-premium spread separates dental-impression custom guards from boil-and-bite retail units by a factor reflecting clinician labor and ASTM F2967 certification tier. Pricing stratifies across premium custom-laminated TPU, standard boil-and-bite EVA, and economy stock units with minimal fit adjustment. Cost compression in EVA-dependent mass tiers intensifies because feedstock indices track volatile petrochemical benchmarks. Adolescent athletes and recreational club players exhibit highest price sensitivity, while NCAA Division I equipment managers prioritize impact-attenuation performance over unit cost.
Supply Chain Analysis
Dental-laboratory capacity bottlenecks in Texas and Florida constrain precision-fit segment expansion despite scholastic mandate demand surges. Raw material flows draw from Saudi ethylene crackers for EVA feedstock, German TPU compounders for performance elastomers, and Chinese silicone processors for orthodontic-grade formulations. Single-source vulnerability concentrates in licensed orthodontic technician pools with limited training pipeline capacity. Distribution runs through institutional procurement officers at district level rather than traditional sporting-goods retail seasonality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to scholastic athletic budget cycles, with Texas and Florida legislative sessions opening institutional procurement pipelines ahead of football preseason windows.
For Market Incumbents: Secure exclusive dental-laboratory partnerships in Texas and Florida before legislative mandates activate district-level procurement centralization. Deepen backward integration into TPU compounding to insulate margin structures from petrochemical index volatility. Channel control through direct-to-club subscription platforms defends against DIY molding kit substitution threatening boil-and-bite retail volumes. For New Entrants and Emerging Players: Team replenishment subscription services represent the most penetrable white-space where Shock Doctor and Decathlon maintain only transactional retail presence. Target independent youth football leagues in southeastern states with decentralized purchasing authority and limited compliance enforcement resources. Deploy 3D-printed lattice production to match boil-and-bite price points at custom-fit quality tiers without dental-laboratory dependency. For Investors and Strategic Acquirers: Secondary-cycle assets sit with boil-and-bite volume players facing margin compression from EVA feedstock volatility and DIY kit substitution. Five-to-ten-year viability favors precision-fit specialists with locked dental-laboratory capacity and embedded sensor technology partnerships. Monitor Texas Education Agency rulemaking timelines as the critical inflection signal for institutional procurement volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dental-Laboratory Partnership Lock-Up | Exclusive TPU lamination agreements in Texas and Florida preempt competitor access to scholastic procurement pipelines. |
| Direct-to-Club Subscription Launch | Recurring revenue models bypass sporting-goods retail markups and capture team replenishment cycles. |
| TPU Backward Integration | In-house compounding insulates margin structures from Saudi ethylene price volatility. |
| Embedded Sensor Integration | Pressure-sensor convergence with concussion-monitoring systems commands premium positioning in NCAA programs. |
| 3D-Printed Lattice Production Scale-Up | Selective laser sintering micro-batches match boil-and-bite economics at custom-fit quality tiers. |
Research Methodology
Cross-validation between primary interviews with dental laboratory technicians, scholastic athletic directors, and equipment procurement officers anchors the qualitative findings against secondary validation from FDA 510(k) filings, ASTM F2967 test protocol documentation, and NFHS equipment rule publications. Bottom-up demand modeling triangulates district-level procurement data with top-down market sizing across custom-fitted, boil-and-bite, stock, and ultra-high performance product tiers.
Sensitivity analysis around TPU adoption rates, scholastic mandate expansion timelines, and dental-laboratory capacity constraints shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, material formulation, end-user archetype, and distribution channel with regional regulatory cluster differentiation. CAGRs derive from fitted growth curves applied to institutional procurement volume data and replacement cycle compression patterns. Industry-specific forecast inputs incorporate ASTM-ISO harmonization progress and state-level legislative session calendars.
Underlying assumptions cover stable petrochemical feedstock availability, continued NCAA and NFHS equipment rule enforcement, and dental-laboratory technician training pipeline expansion, with deviation risk concentrated in FDA 510(k) clearance delays for novel elastomer formulations and unregulated DIY molding kit market capture. Practitioners should keep alternative scenarios live as Texas and Florida legislative outcomes and TPU material cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Soccer Cleats Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Padel Balls Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Sports Devices Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Gym Shoes Market