
 Ice Hockey Apparel Market | 2026-2036
Ice Hockey Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Hockey Apparel Market Analysis
Asset-light licensing and royalty-based manufacturing partnerships is rewriting competitive economics in ice hockey apparel. Bauer Hockey leverages captive R&D facilities in Canada to sustain proprietary fit systems across its protective lines. CCM Hockey anchors North American distribution through controlled specialty retail networks. True Temper Sports differentiates via vertical integration into composite material science originally developed for hockey stick shafts.
Ice hockey apparel encompasses protective and performance garments engineered for collision sport mechanics, integrating impact-resistant padding with breathable moisture-management textiles typically rated to 300-500 gsm fabric weight and seam-taped construction for thermal regulation during intermittent high-intensity skating. The primary commercial purpose is to reduce injury incidence while maintaining mobility and thermoregulation across game and practice contexts. Jerseys and compression fabric categories capture the strongest margin pools as teams and leagues enforce standardized kit protocols with shorter replacement cycles. Helmets represent the most technically concentrated segment given multi-density foam liner requirements and certification testing overhead. Pants sustain steady volume through integrated girdle systems that bundle protective elements into single-SKU purchases.
Health Canada and the Consumer Product Safety Commission in the US govern impact protection standards for hockey helmets and protective equipment, while ISO 10256 governs international testing protocols for head and face protection gear. These frameworks elevate compliance costs for new entrants but reinforce incumbent brand loyalty among safety-conscious amateur leagues and parental buyers. Stakeholders must monitor how state-level youth sports concussion protocols in the US and provincial safety mandates in Canada reshape mandatory equipment specifications ahead of purchasing cycles.
Market Dynamics
Amateur league kit refresh compression is the dominant structural force reshaping ice hockey apparel economics. Youth enrollment surges in Canada and the northern United States are compressing replacement cycles from seasonal to calendar-year intervals.
Growth Catalysts
- ISO 10256 certification mandates:International testing protocols for head and face protection gear are elevating baseline safety specifications across amateur leagues. Parental buyers now treat certified equipment as non-negotiable, locking in replacement demand.
- Moisture-wicking compression fabrics:US and Canadian textile suppliers are displacing cotton base layers with engineered synthetics rated to 300-500 gsm. Teams mandate these fabrics for thermal regulation during high-intensity skating intervals.
- Provincial safety mandates in Canada:Ontario and Quebec youth hockey associations enforce mandatory equipment audits before season registration. These audits accelerate protective gear turnover regardless of visible wear.
Market Restraints
- Composite material cost volatility:Carbon fiber and multi-density foam inputs face petrochemical price swings. True Temper Sports and similar vertically integrated manufacturers absorb margin compression when resin prices spike.
- Specialty retail concentration:North American distribution runs through controlled networks of hockey-specific retailers. New entrants face slotting fee barriers and exclusivity agreements with incumbent brands.
- Multi-density foam liner technical limits:Current helmet liners balance impact absorption against weight and breathability tradeoffs. Further safety gains require breakthroughs in aerogel or shear-thickening fluid integration.
Strategic Opportunities
- Underpenetrated US Sun Belt markets:Texas, Florida, and Arizona youth hockey enrollment is climbing from low bases. Rink construction booms in Dallas and Phoenix create first-mover advantages for regional distribution partnerships.
- State-level concussion protocol expansion:California and New York are drafting mandatory baseline testing and equipment upgrade schedules. Apparel manufacturers can embed sensor-ready padding to capture this specification shift.
- Direct-to-team e-commerce platforms:League administrators are consolidating bulk orders through digital portals. This channel innovation bypasses retail markup and captures kit standardization contracts.
Industry Challenges
- Certification timeline compression:Health Canada and the Consumer Product Safety Commission are accelerating review cycles for new helmet designs. Engineering teams must parallel-track testing protocols across jurisdictions.
- Seam-taped construction skill scarcity:Thermal regulation performance depends on specialized sewing technicians. Apprenticeship pipelines in Montreal and Toronto manufacturing clusters are insufficient to meet demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Hockey Apparel Market |
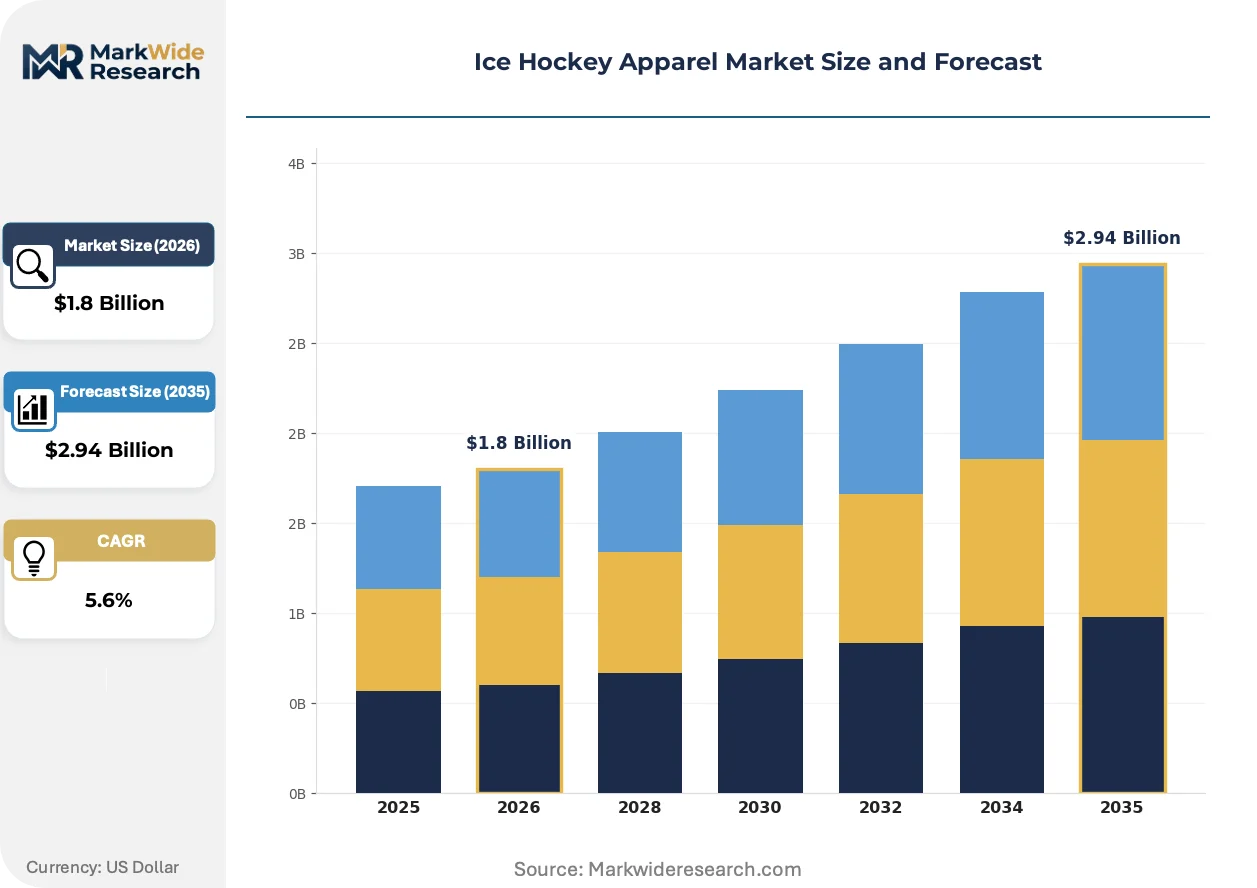
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jerseys, Pants, Socks, Helmets End User: Professional Players, Amateur Players, Coaches, Fans Distribution Channel: Specialty Stores, Online Retail, Department Stores, Event Sales Material: Polyester, Nylon, Cotton, Compression Fabric |
| Companies Covered | True Temper Sports, Easton Hockey, Bauer Hockey, New Balance, Graf Skates, CCM Hockey, Sherwood Hockey, Franklin Sports, Warrior Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Hockey Apparel Market Emerging Trajectories
Material science convergence and regulatory specification tightening are rewriting product development priorities. Manufacturers must now engineer for simultaneous impact resistance, thermal management, and connected-sensor compatibility.
Antimicrobial silver-ion treatments are migrating from medical textiles into hockey base layers and glove linings. Canadian youth leagues are adopting these fabrics fastest due to parental hygiene concerns. This migration is compressing margins for untreated cotton suppliers while opening premium pricing tiers for certified antimicrobial SKUs.
REACH chemical restrictions in the European Union are forcing reformulation of flame-retardant and water-repellent coatings used on hockey bags and outer shells. Manufacturers serving export markets must maintain dual inventory streams. The protective equipment segment faces the steepest compliance costs as padding adhesives fall under substance-of-very-high-concern scrutiny.
Team administrators are consolidating purchasing through league-level kit contracts rather than individual player retail. This aggregation shifts volume toward manufacturers with configurable bulk-order platforms. The Canadian minor hockey system exhibits this pattern most acutely, with provincial associations negotiating exclusive supplier arrangements.
Ice Hockey Apparel Market Segmentation
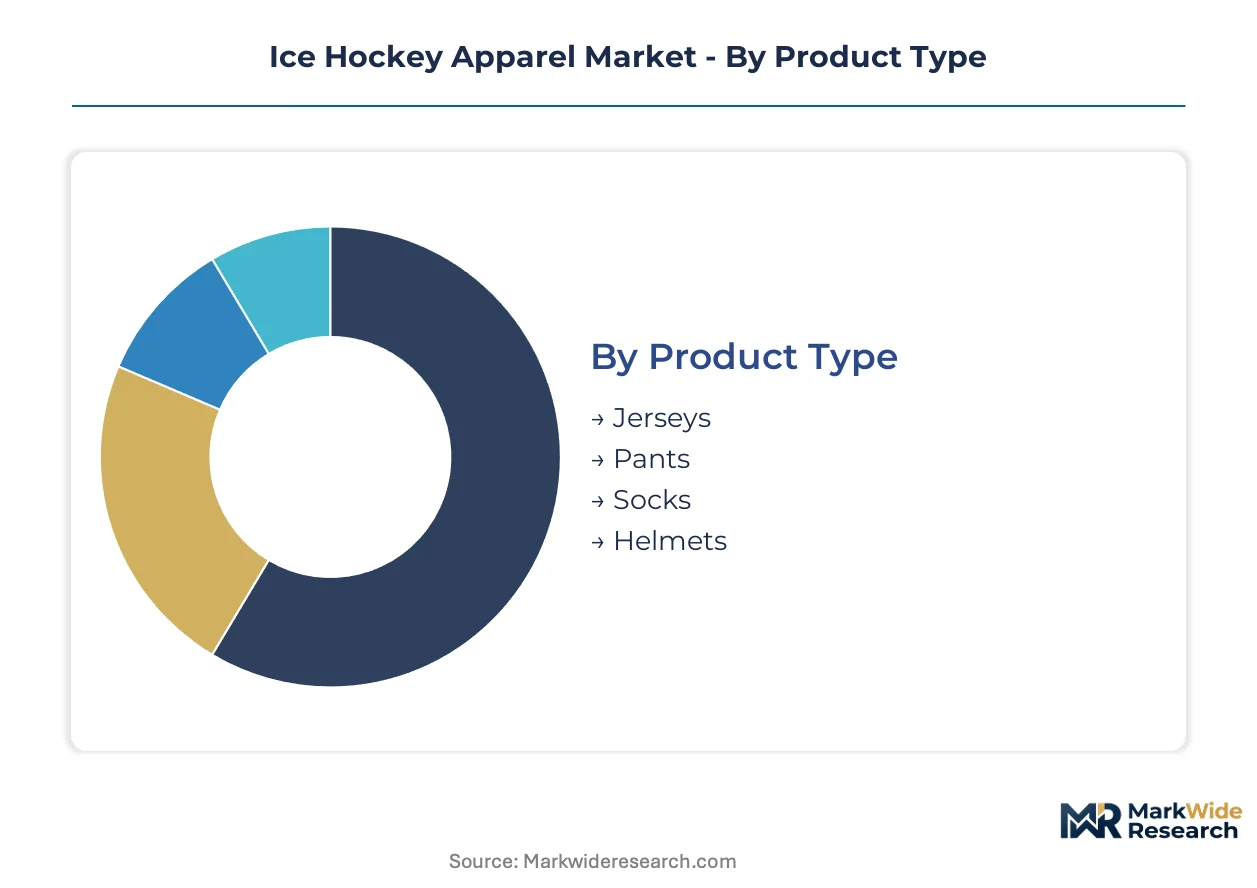
Product architecture in ice hockey apparel varies sharply by replacement cycle intensity and post-purchase service requirements. Teams and leagues enforce kit standardization protocols that compress purchasing decisions into synchronized bulk orders, reshaping how manufacturers configure SKU portfolios across protective and performance categories.
Product Type:
After-sales service intensity runs highest in protective equipment requiring recertification and liner replacement, while performance garments demand less intervention but faster refresh cycles.
- Jerseys:Engineered from 300-500 gsm polyester blends with sublimated graphics and reinforced shoulder panels for contact durability. Canadian youth leagues drive volume through mandatory league-wide kit standardization programs that force annual replacement regardless of wear condition.
- Helmets:Multi-density foam liner systems integrated with polycarbonate shells require ISO 10256 certification maintenance and periodic component replacement. Health Canada and the US Consumer Product Safety Commission govern recertification timelines, creating sustained aftermarket revenue streams for incumbent manufacturers.
- Pants:Integrated girdle systems bundling hip, thigh, and tailbone protection into single-SKU purchases. Demand concentrates in North American amateur leagues seeking simplified protective compliance.
- Socks:Knitted acrylic or moisture-wicking synthetic tubes with reinforced heel and toe sections. Lower price points drive volume through multi-pair team packs.
By volume, jerseys lead. By growth pace, helmets are ahead.
End User:
Cost tier stratification separates premium professional-grade specifications from mass-market amateur compliance requirements.
- Amateur Players:Youth and adult recreational leagues in Canada and the northern United States constitute the volume base. Provincial safety mandates in Ontario and Quebec enforce mandatory equipment audits that accelerate protective gear turnover.
- Professional Players:NHL and minor league athletes demand custom-fit protective systems with sponsor-integrated jersey specifications. Bauer Hockey and CCM Hockey dominate this tier through captive R&D facilities and direct team relationships.
- Coaches:Bench personnel require distinct thermal regulation profiles for stationary observation during games. Moisture-wicking compression base layers from US and Canadian textile suppliers displace cotton in this segment.
- Fans:Replica jersey purchases track team performance and playoff exposure. Event sales channels capture impulse volume during tournament weekends.
Amateur players dominate unit volume. Professional players command the steepest expansion trajectory in average revenue per user.
Distribution Channel:
Geography of demand concentration shapes channel investment, with Canadian population centers sustaining specialty retail density while Sun Belt expansion favors digital penetration.
- Specialty Stores:Hockey-specific retailers in Toronto, Montreal, and Minneapolis-St. Paul provide custom fitting services and equipment recertification. CCM Hockey anchors North American distribution through controlled exclusivity agreements with these networks.
- Online Retail:Direct-to-team e-commerce portals are consolidating bulk orders from league administrators. This channel innovation bypasses retail markup and captures kit standardization contracts.
- Department Stores:Mass-market fan merchandise and entry-level protective sets for casual participants. Limited technical service capability restricts protective equipment penetration.
- Event Sales:Tournament weekend pop-up operations capturing impulse purchases and emergency replacements. Seasonal revenue concentration requires flexible inventory positioning.
Specialty stores retain the highest margin per transaction. Online retail is gaining share fastest.
Material:
Supply concentration in US and Canadian textile manufacturing clusters favors regional sourcing for moisture-management fabrics, while commodity inputs face broader import exposure.
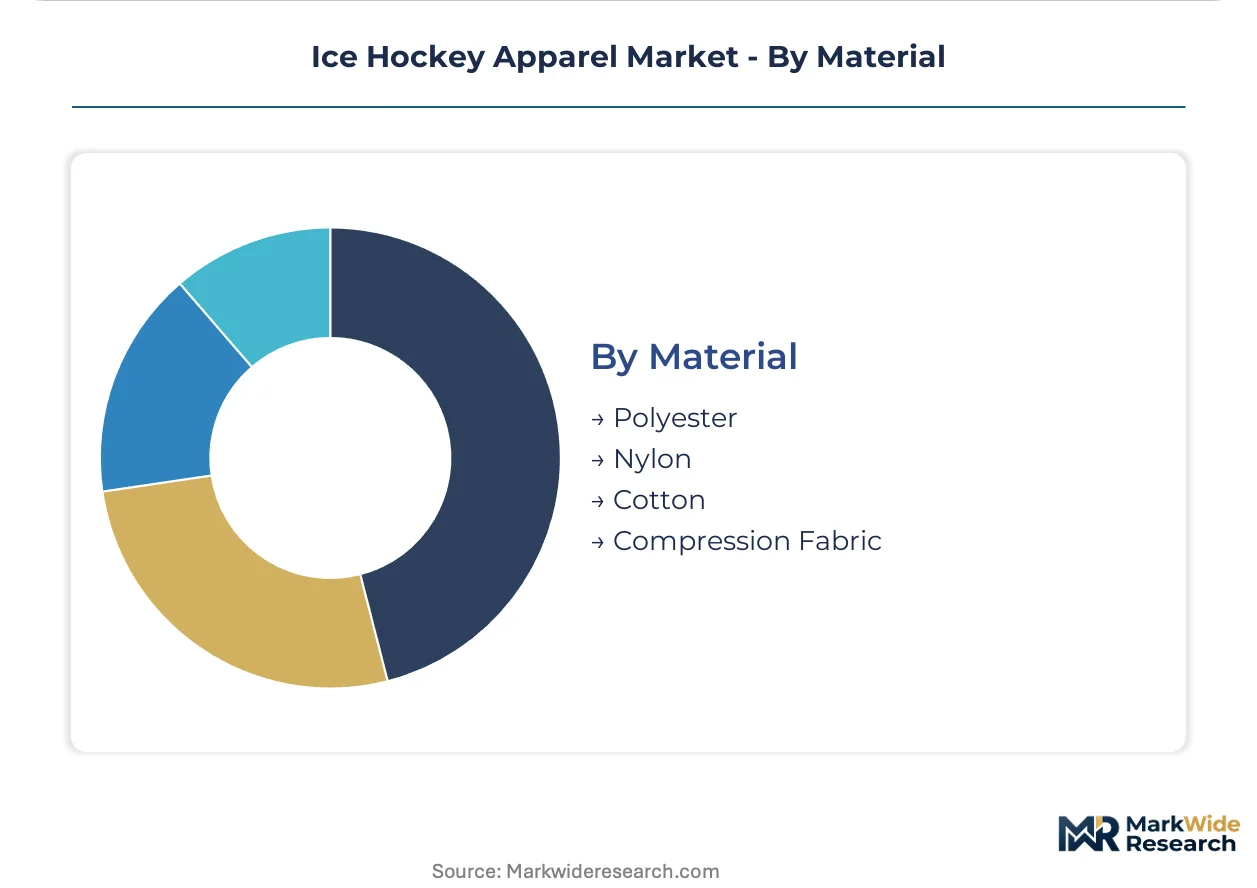
- Compression Fabric:Engineered synthetics rated to 300-500 gsm with silver-ion antimicrobial treatments. Teams mandate these fabrics for thermal regulation during high-intensity skating intervals.
- Polyester:Sublimation-ready filament yarns for jersey bodies and outer shells. REACH chemical restrictions in the European Union force dual inventory streams for export markets.
- Nylon:High-tenacity fibers for abrasion-resistant pant overlays and bag construction. Petrochemical price volatility elevates working capital requirements.
- Cotton:Traditional base layer material now displaced by synthetic alternatives in competitive settings. Survives in fan merchandise and practice-wear price tiers.
Polyester dominates current volume. Compression fabric is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial safety mandates in Canada and state-level concussion protocols across the United States are compressing equipment replacement cycles and reshaping import demand patterns. These regulatory frameworks concentrate procurement authority with league administrators rather than individual consumers. Regional manufacturing clusters in Montreal and Toronto supply moisture-wicking compression fabrics to North American teams.
Canada
Ontario and Quebec youth hockey associations enforce mandatory equipment audits before season registration, accelerating protective gear turnover. Health Canada governs impact protection standards for helmets through accelerated review cycles. Montreal manufacturing clusters supply seam-taped compression fabrics rated to 300-500 gsm for thermal regulation during high-intensity skating.
United States
Texas, Florida, and Arizona youth hockey enrollment climbs from low bases as rink construction booms in Dallas and Phoenix. State-level concussion protocols in California and New York draft mandatory baseline testing and equipment upgrade schedules. Minneapolis-St. Paul specialty retail networks provide custom fitting services and equipment recertification for amateur leagues.
Sweden
Stockholm and Gothenburg amateur leagues adopt ISO 10256 certification mandates for head and face protection gear ahead of seasonal registration. The Swedish Sports Confederation coordinates equipment standardization with neighboring Nordic markets. Textile suppliers in the Borås region engineer antimicrobial silver-ion treatments for hockey base layers.
Finland
Helsinki youth hockey systems mandate moisture-wicking synthetic base layers displacing traditional cotton in competitive settings. The Finnish Ice Hockey Association audits protective equipment compliance through digital registration portals. Tampere manufacturing facilities produce sublimation-ready polyester filament yarns for jersey bodies and outer shells.
Czech Republic
Prague and Brno amateur leagues compress kit refresh cycles as participation rates climb in regional youth divisions. The Czech Ice Hockey Association aligns equipment specifications with EU REACH chemical restrictions on flame-retardant coatings. Ostrava textile clusters supply reinforced shoulder panel fabrics for contact durability in collision sport mechanics.
Ice Hockey Apparel Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specialty retail networks and direct-to-team e-commerce portals. The vendor base concentrates around captive R&D facilities in Canada and controlled distribution agreements with hockey-specific retailers. Two strategic archetypes dominate: vertically integrated material science developers and asset-light licensing operators pursuing royalty-based manufacturing partnerships. Capacity expansion in composite material inputs and strategic partnerships for sensor-ready padding integration represent the dominant competitive moves.
Within the integrated manufacturing tier, True Temper Sports exemplifies upstream control over composite material science originally developed for hockey stick shafts. Bauer Hockey and CCM Hockey occupy positions as channel-anchoring specialists with captive R&D facilities and controlled specialty retail networks across North America. These three companies represent the core competitive set shaping proprietary fit systems and league-level kit standardization contracts.
| Leading Market Players |
|---|
| True Temper Sports |
| Easton Hockey |
| Bauer Hockey |
| New Balance |
| Graf Skates |
| CCM Hockey |
| Sherwood Hockey |
| Franklin Sports |
| Warrior Sports |
| Others |
Supply Flow & Price Mechanics
Montreal manufacturing clusters anchor North American compression fabric supply, and their capacity utilization rates directly determine pricing power for moisture-wicking base layers across amateur league procurement cycles. When seam-taped construction skill scarcity tightens output, incumbent suppliers capture premium pricing tiers while new entrants face margin compression.
Pricing Analysis
Certification level creates the primary spread between amateur and professional-grade protective equipment. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10256 compliance status, brand heritage, and after-sales service bundling. Cost compression in economy-tier helmets is intensifying because Health Canada accelerated recertification timelines. Parental buyers in Canadian youth leagues show lowest price sensitivity for certified head protection, while Sun Belt expansion markets exhibit highest sensitivity.
Supply Chain Analysis
Tariff exposure between US and Chinese petrochemical feedstock suppliers dominates raw material cost volatility for multi-density foam liner inputs. Manufacturing concentration rests on Canada, the United States, and Finland for textile finishing and protective equipment assembly. Carbon fiber prepreg, antimicrobial silver-ion treatments, and polycarbonate shell resins constitute critical dependencies. Single-source vulnerability in Montreal sewing technician apprenticeships threatens seam-taped construction throughput. Distribution runs through hockey-specific specialty retailers with controlled exclusivity agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment recertification services and liner replacement programs expand faster than hardware sales, creating a service-attach opportunity that restructures manufacturer economics toward recurring revenue streams.
For Market Incumbents: Harden proprietary fit systems through captive R&D facility investment in Canada and accelerate certification pipeline parallel-tracking across Health Canada and CPSC jurisdictions. Consolidate specialty retail exclusivity agreements to block emerging direct-to-team e-commerce platforms from capturing kit standardization contracts. Threat substitution from sensor-ready padding specifications requires preemptive engineering integration. For New Entrants and Emerging Players: Texas and Arizona youth hockey enrollment growth from low bases represents the most penetrable entry point for regional distribution partnerships bypassing incumbent-controlled retail networks. Direct-to-team e-commerce portals for bulk league orders offer a go-to-market angle that circumvents slotting fee barriers and captures kit standardization contracts before specialty retail incumbents adapt. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified sporting goods parents with underoptimized hockey apparel divisions lacking captive R&D infrastructure. Long-term viability favors asset-light licensing operators with royalty-based manufacturing partnerships over capital-intensive vertical integration. Watch state-level concussion protocol adoption rates as the signal indicating mandatory equipment upgrade schedule inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Ready Padding Integration | California and New York concussion protocols mandate embedded sensor compatibility for compliance. |
| Direct-to-Team E-Commerce Platform Launch | League administrators in Canada consolidate bulk orders through digital portals bypassing retail markup. |
| Antimicrobial Silver-Ion Treatment Certification | Health Canada guidelines accelerate parental demand for hygiene-validated base layer fabrics. |
| Specialty Retail Exclusivity Expansion | Toronto and Minneapolis-St. Paul networks provide custom fitting services locking in replacement demand. |
| Montreal Sewing Technician Apprenticeship Pipeline | Seam-taped construction skill scarcity threatens thermal regulation performance and output capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from equipment procurement managers at Canadian provincial hockey associations, protective gear R&D directors, specialty retail buyers in Toronto and Minneapolis-St. Paul, and league administrator panels overseeing kit standardization programs, then refined against secondary validation from Health Canada certification databases, CPSC recall filings, ISO 10256 testing protocol documentation, and customs trade records for textile inputs. Bottom-up volume triangulation across amateur enrollment data and top-down value estimation from manufacturer revenue disclosures were cross-checked for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user tier, distribution channel, and material specification grade. CAGRs were derived from replacement cycle compression rates and enrollment growth trajectories. Industry-specific forecast inputs incorporated provincial safety mandate adoption timelines and state-level concussion protocol legislative status.
Macroeconomic conditions sit as an overlay; deviation in petrochemical resin prices or youth sports participation funding would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and specialty retail channel persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Apparel Re-Commerce Market
Apparel & Footwear
Asia-Pacific Lingerie Market
Apparel & Footwear
Mister Cap Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Gym Apparel Market
Apparel & Footwear
Electric Heated Shoes Market
Apparel & Footwear
Bra Cups Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Europe Jeans Market
Apparel & Footwear
India Denim Jeans Market