
 Golf Outfit Market | 2026-2036
Golf Outfit Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Outfit Market Foresight
Vietnam is tilting toward apparel manufacturing scale for performance sportswear, drawing cut-make-trim capacity from legacy textile hubs. Nike leverages vertical integration in synthetic fiber innovation to sustain margin control across its golf lines. Adidas AG anchors European demand through technical partnerships with tour professionals. FootJoy dominates leather-grade glove and shoe craftsmanship, a specialization that insulates its premium positioning.
A golf outfit encompasses performance-engineered apparel designed for swing mobility, moisture management, and UV protection during play, typically constructed from blended fabrics with four-way stretch and breathability ratings exceeding standard casual wear. The primary purpose is to maintain thermoregulation and unrestricted biomechanics across eighteen holes in variable weather. Shirts and pants command the largest revenue pools, though spandex blends in compression base layers represent the fastest-expanding material category as players seek muscle support and recovery benefits. Women's skirts and jackets are gaining shelf space at green-grass pro shops, reflecting demographic diversification in club memberships.
REACH in Europe restricts perfluorinated chemical treatments used in water-repellent finishes, compelling reformulation of rainwear coatings across supply chains. The EPA monitors textile dye discharge from offshore finishing facilities, raising compliance costs for brands sourcing from concentrated Asian wet-processing zones. Stakeholders must monitor how California's SB 657 transparency mandates and emerging extended producer responsibility frameworks reshape sourcing disclosures and consumer-facing sustainability claims.
Market Dynamics
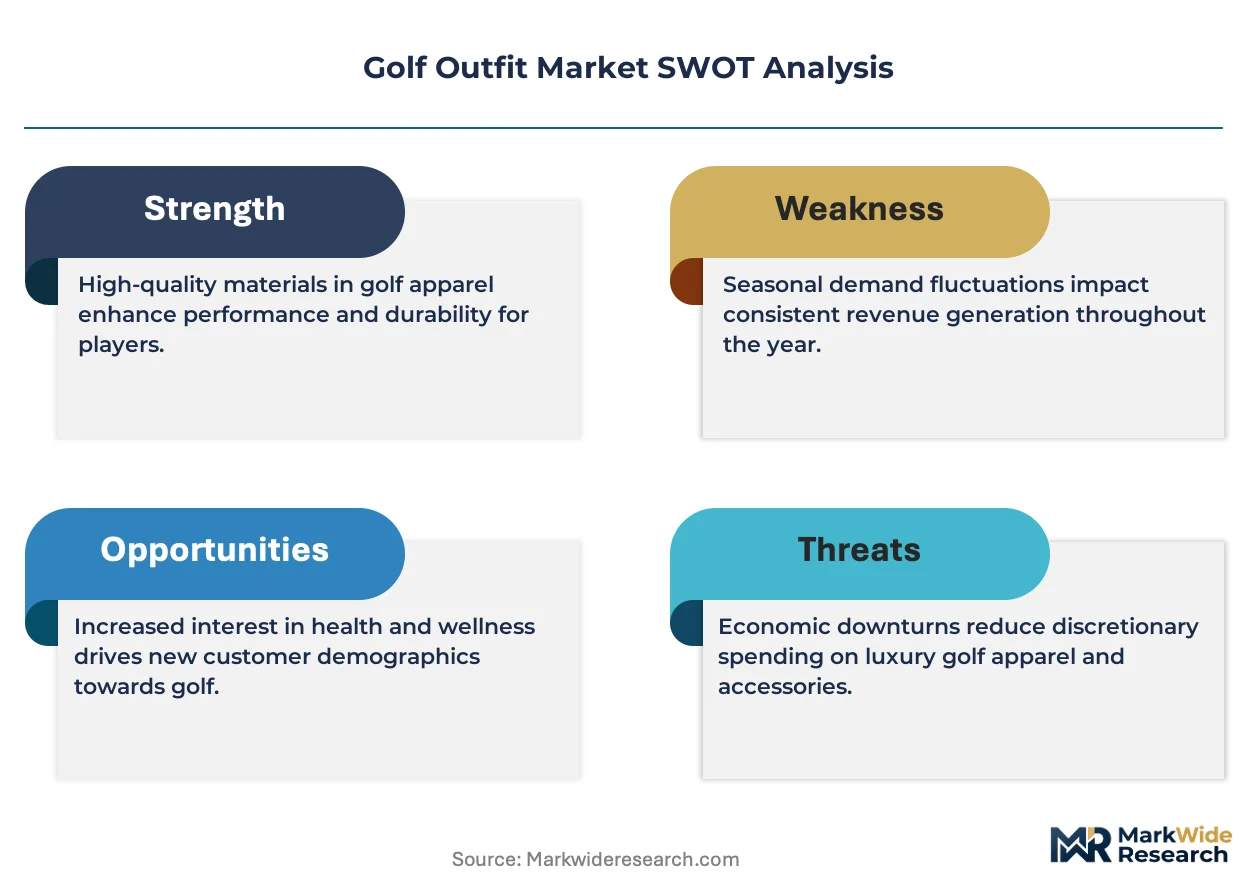
The EU Green Deal's textile sustainability requirements are compressing supplier margins and forcing material reformulation across synthetic fiber supply chains, redrawing competitive positioning in performance golf apparel.
Growth Catalysts
- Recreational golfer expansion:Municipal and resort courses in Sun Belt states are registering elevated tee-time demand from casual players seeking outdoor recreation alternatives.
- REACH chemical reformulation:European water-repellent coating restrictions are accelerating adoption of fluorine-free durable water-repellent finishes across rainwear manufacturing.
- Spandex blend innovation:Compression base layers with four-way stretch recovery properties are capturing shelf space from traditional cotton undergarments in pro shop assortments.
Market Restraints
- Petrochemical input volatility:Recycled polyester feedstock costs fluctuate with crude oil derivatives and post-consumer bottle collection rates in Asian recycling clusters.
- Wet-processing concentration:Textile dye discharge compliance costs are rising at offshore finishing facilities monitored by the EPA, squeezing brands dependent on Vietnamese cut-make-trim capacity.
- Perfluorinated compound substitution:Water-repellent performance gaps between legacy PFAS treatments and compliant alternatives limit product efficacy in heavy-rain competitive play.
Strategic Opportunities
- Women's demographic underpenetration:Skirts and jackets are gaining shelf space at green-grass pro shops as club memberships diversify beyond traditional male segments.
- California SB 657 transparency:Supply chain disclosure mandates are creating first-mover advantages for brands with traceable organic cotton sourcing and verified recycled content claims.
- Direct-to-consumer channel bypass:Technical partnerships with tour professionals are enabling bypass of wholesale markups through authenticated athlete storefronts.
Industry Challenges
- Biomechanical engineering talent scarcity:Apparel designers with swing-motion analysis capabilities and fabric stretch-recovery expertise command premium compensation in competitive labor markets.
- Extended producer responsibility compliance:Emerging take-back program mandates require reverse logistics infrastructure that conflicts with lean inventory models optimized for seasonal collection turnover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Outfit Market |
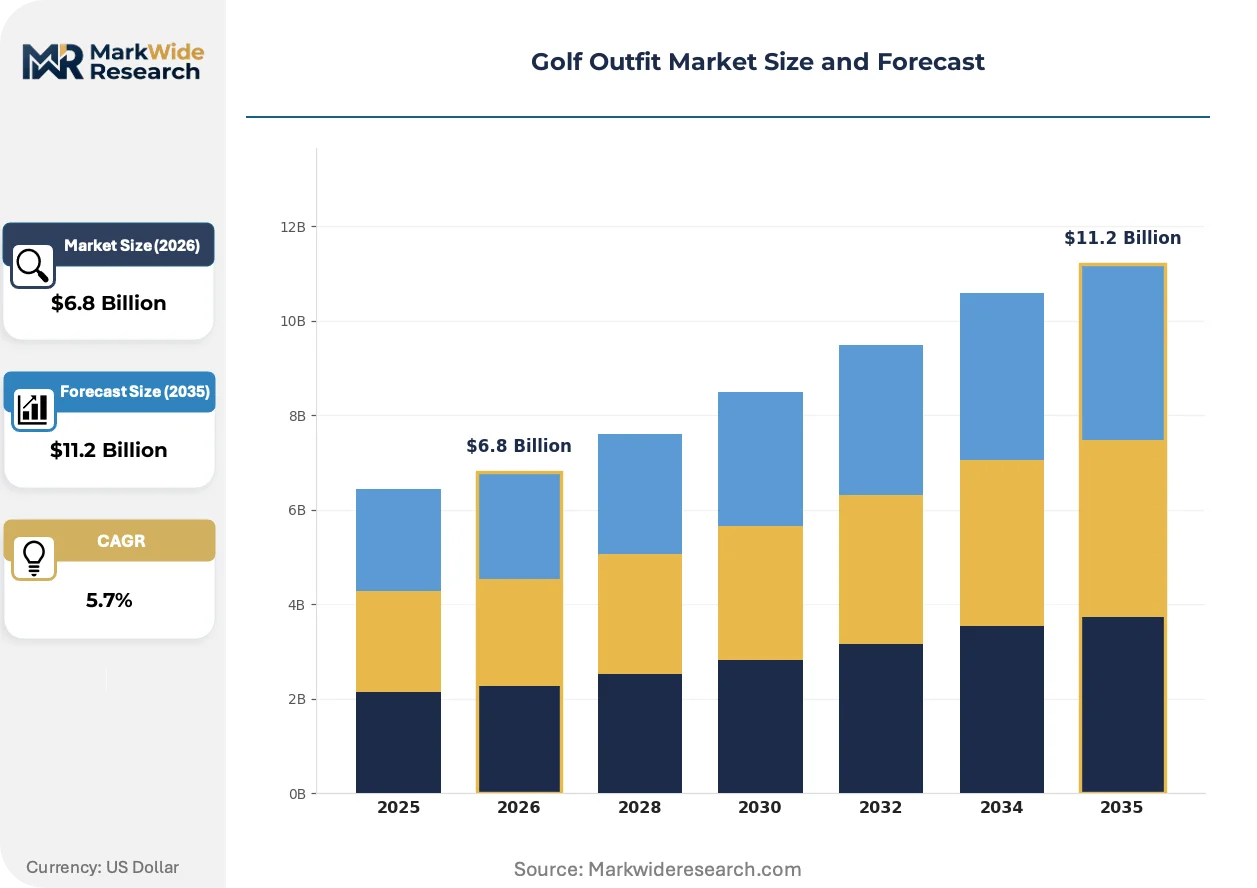
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pants, Shirts, Skirts, Jackets Material: Cotton, Polyester, Spandex, Nylon Gender: Men, Women, Unisex, Kids Size: Small, Medium, Large, Extra Large |
| Companies Covered | Under Armour Inc., Topgolf Callaway Brands Corp., Nike Inc., FootJoy, TravisMathew, Adidas AG, Ralph Lauren Corp., Malbon Golf, Puma SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Outfit Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry bans are collapsing traditional performance-apparel specifications, compressing product development cycles from seasonal to continuous release models.
Seamless knitting technology is collapsing the distinction between base-layer compression and outerwear construction, enabling single-garment thermoregulation across temperature swings. Recreational golfers in Arizona and Florida are adopting these hybrid pieces at accelerating rates. The structural consequence is collapsing inventory SKU counts as multi-functional garments displace specialized layering systems.
REACH restrictions on perfluorinated chemicals are eliminating legacy water-repellent finishes from European-sold rainwear, compelling reformulation of durable water-repellent coatings. Brands sourcing from Vietnamese wet-processing facilities face elevated compliance documentation burdens. The tour-player segment is most affected, demanding performance parity in sponsored competitive gear despite chemistry constraints.
Green-grass pro shops are unbundling after-sales fitting services from product margins, shifting toward appointment-based custom club-fitting studios with attached apparel retail. Municipal course operators in Texas and California are piloting this model to capture higher per-visit spend. The behavioral shift is most visible in Sun Belt states where year-round playability sustains consistent foot traffic.
Golf Outfit Market Segmentation
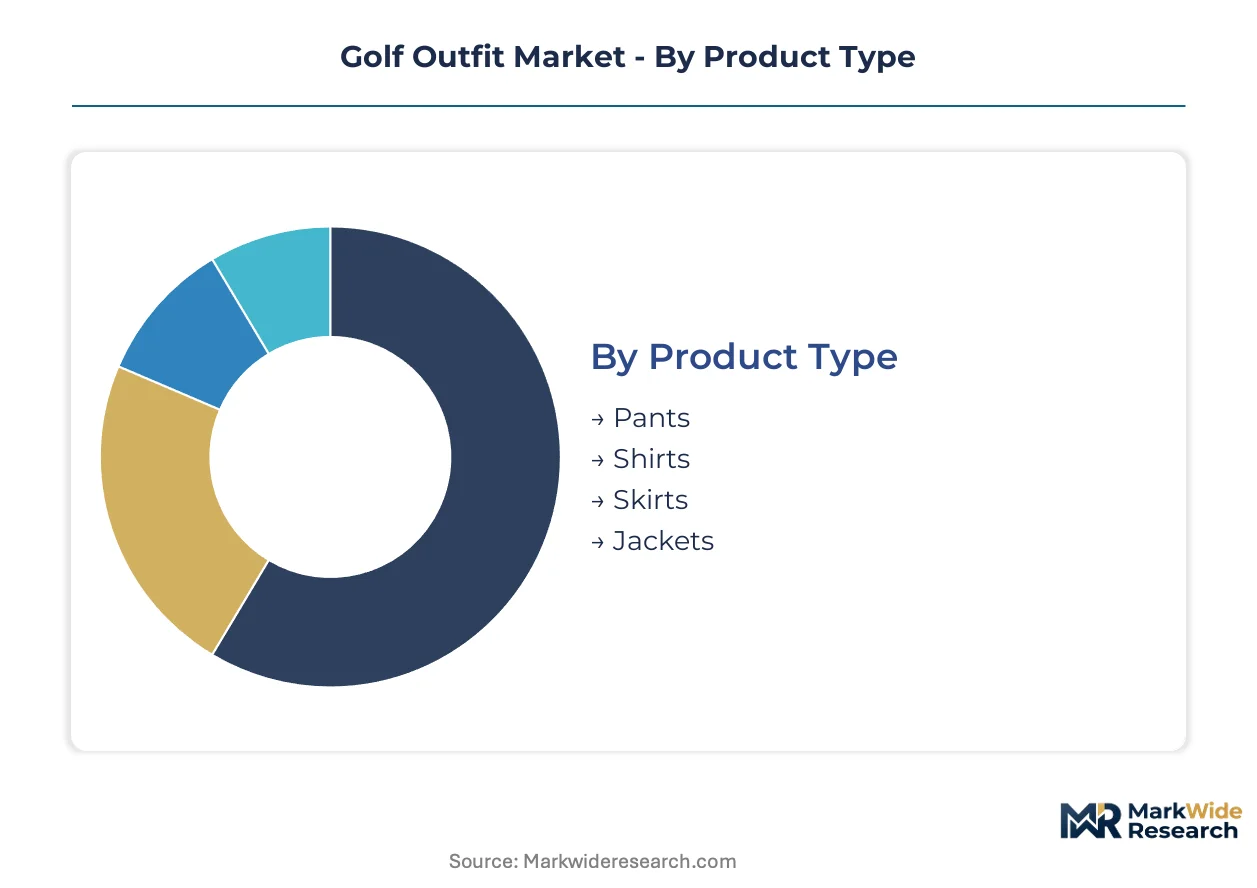
Golf outfit segmentation reveals how material innovation and demographic expansion are fragmenting traditional category boundaries. Manufacturers now engineer distinct product architectures for swing biomechanics, climate adaptability, and generational purchasing preferences.
Product Type:
Mature staples dominate revenue pools while emerging silhouettes capture shelf space from legacy layering systems.
- Pants:Four-way stretch constructions with moisture-wicking liners command the largest revenue share in men's assortments. Sun Belt municipal courses in Texas and Florida drive replacement demand as recreational golfers prioritize unrestricted hip rotation during drives.
- Shirts:Performance-engineered polos with UV protection ratings and breathable mesh panels anchor pro shop inventories. Arizona and California green-grass retailers stock these as year-round staples given sustained tee-time volume.
- Skirts:Pleated designs with built-in compression shorts are gaining placement in women's sections.
- Jackets:Lightweight rain shells with packable construction address unpredictable morning conditions.
Pants and shirts handle the majority of throughput; skirts are expanding most quickly on share as club memberships diversify.
Material:
Cost tier stratification separates commodity inputs from technical fiber investments with measurable performance premiums.
- Polyester:Recycled variants from post-consumer bottle feedstock dominate mid-market price positioning. EU Green Deal compliance costs are compressing margins for brands sourcing from Vietnamese wet-processing clusters.
- Spandex:Four-way stretch recovery fibers enable compression base layers that displace cotton undergarments. Recreational golfers in Florida and Arizona adopt these for muscle support during extended rounds.
- Cotton:Organic certification commands price premiums in European markets.
- Nylon:Ripstop weaves provide abrasion resistance for outerwear applications.
Polyester moves the highest volume; spandex is climbing the fastest as functional benefits penetrate casual player segments.
Gender:
Customer type concentration in traditional male segments is fragmenting as facility operators target underpenetrated demographics.
- Men:Established demand concentration in standard-fit polos and flat-front trousers sustains inventory depth. Municipal course operators in Texas and California maintain broad size runs given consistent foot traffic.
- Women:Skirt-jacket combinations and tailored silhouettes are capturing expanded shelf space. Green-grass pro shops in Sun Belt states are reconfiguring floor plans to accommodate rising female membership rates.
- Unisex:Simplified sizing architectures reduce SKU complexity for direct-to-consumer channels.
- Kids:Junior programs at resort courses drive seasonal demand spikes.
Men's lines absorb the bulk of production capacity; women's is gaining share fastest as demographic targeting intensifies.
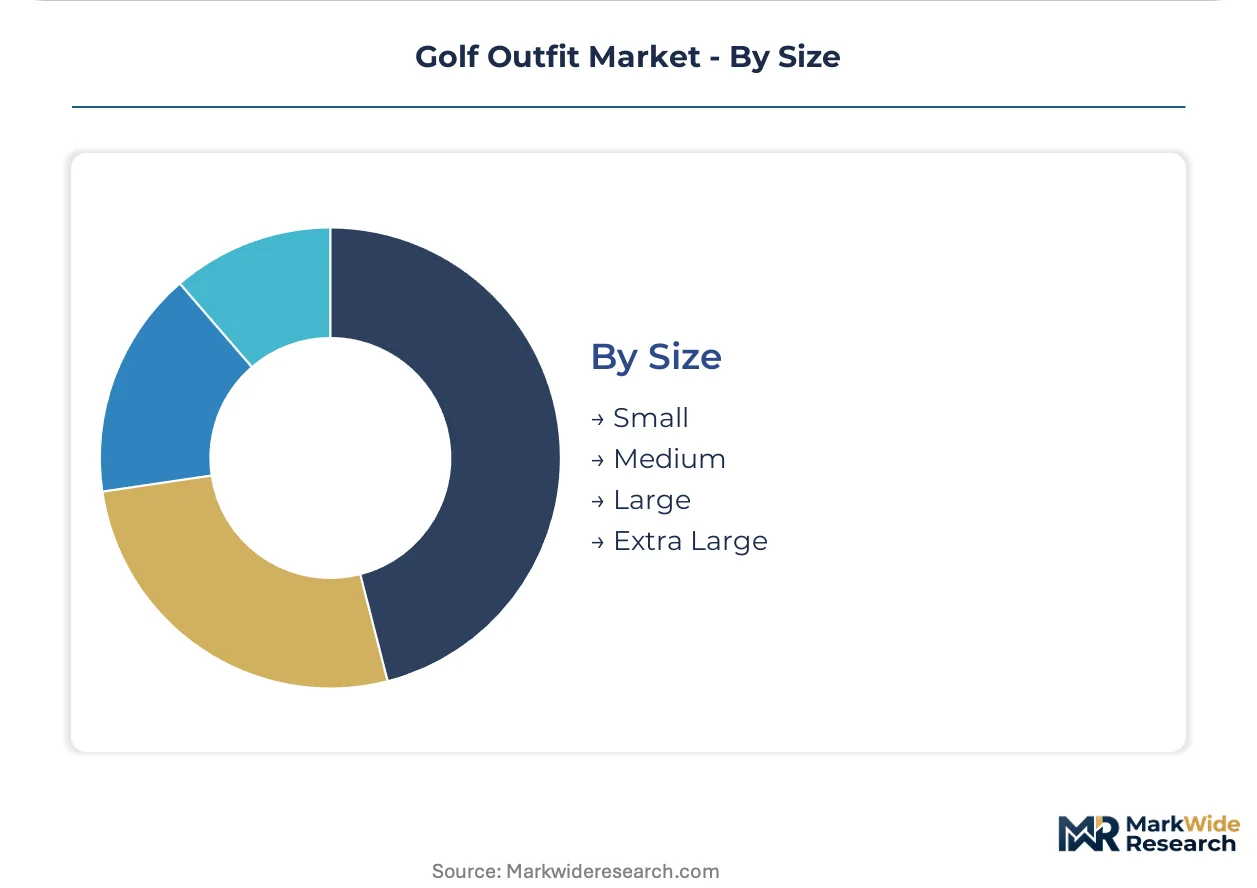
Size:
Volume concentration in core sizing creates inventory risk for extended size ranges with less predictable turnover.
- Medium:The most stocked size across pro shop assortments reflects average male golfer anthropometrics. Arizona and Florida retailers optimize replenishment algorithms around this tier given year-round playability.
- Large:Secondary volume concentration supports breadth in pant waist and shirt chest measurements. Texas municipal operators maintain deeper runs here to capture recreational golfer traffic.
- Small:Women's and junior categories concentrate demand in this tier.
- Extra Large:Extended sizing requires specialized pattern grading and carries higher return rates.
Medium and Large carry the inventory burden; Small is expanding most quickly as women's participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States golfers favor year-round playability in Sun Belt states, while European players prioritize weather-adaptive layering systems under stricter chemical regulations. Asian markets concentrate manufacturing capacity rather than consumption, creating a supply-demand asymmetry across hemispheres.
United States
Sun Belt states including Arizona, Florida, and Texas register sustained tee-time volume from recreational golfers seeking outdoor recreation alternatives. EPA monitoring of textile dye discharge from offshore finishing facilities elevates compliance documentation burdens for brands importing Vietnamese-manufactured goods. Dallas-Fort Worth municipal course operators pilot appointment-based custom fitting studios to capture higher per-visit apparel spend.
Germany
REACH restrictions on perfluorinated chemicals in water-repellent finishes compel reformulation of rainwear coatings for European tournament play. The EU Green Deal's textile sustainability requirements compress margins for brands sourcing recycled polyester feedstock. Bavarian green-grass pro shops expand women's skirt-jacket combinations as club memberships diversify beyond traditional demographics.
Japan
METI standards for textile labeling and fiber content disclosure shape premium positioning strategies for domestic and imported golf apparel. Compression base layers with four-way stretch recovery capture shelf space from cotton undergarments in Tokyo metropolitan pro shops. Osaka-based retailers optimize inventory around medium sizing given average male golfer anthropometrics.
Vietnam
Cut-make-trim capacity expansion draws wet-processing volume from legacy textile hubs in China and Bangladesh. The country's concentrated finishing facilities face elevated EPA scrutiny over dye discharge compliance costs. Ho Chi Minh City industrial zones specialize in spandex blend innovation for compression garment exports to North American and European markets.
United Kingdom
Scotland's links courses sustain demand for packable rain shells addressing unpredictable morning conditions. CSRD disclosure requirements pressure brands toward traceable organic cotton sourcing and verified recycled content claims. London metropolitan retailers stock UV-protected performance polos as year-round staples despite seasonal playability constraints.
Golf Outfit Market Competitive Landscape
Capability concentration sits with specialized leather-grade craftsmen; scale advantage sits with synthetic fiber innovators with captive supply chains. The market structures around three tiers: vertically integrated sportswear giants controlling polymer innovation, heritage specialists defending premium positioning through material craftsmanship, and lifestyle-oriented entrants capturing casual golfer segments. Dominant competitive moves include technical partnerships with tour professionals for authenticated distribution and backward integration into recycled fiber feedstock to manage input cost volatility.
Within the heritage craftsmanship tier, FootJoy exemplifies premium positioning through specialized glove and shoe manufacturing. Among vertically integrated sportswear architects, Nike Inc. and Adidas AG occupy positions sustained by in-house synthetic fiber development and tour player endorsement networks. These three anchors represent divergent strategic paths: material specialization versus polymer innovation scale versus athlete-centric technical partnerships.
| Leading Market Players |
|---|
| Under Armour Inc. |
| Topgolf Callaway Brands Corp. |
| Nike Inc. |
| FootJoy |
| TravisMathew |
| Adidas AG |
| Ralph Lauren Corp. |
| Malbon Golf |
| Puma SE |
| Others |
Supply & Pricing Matrix
REACH chemical reformulation mandates determine both tiered pricing spreads across European and North American markets and the geographic redistribution of wet-processing capacity away from legacy Asian hubs. Brands absorbing fluorine-free durable water-repellent coating costs face margin compression that widens the gap between premium tour-grade assortments and municipal course entry-level lines.
Pricing Analysis
Geographic price spreads between Sun Belt pro shops and European green-grass retailers reflect divergent compliance cost burdens and seasonal demand concentration. Three-tier pricing structure across premium, standard, and economy levels separates tour-authenticated performance gear from recreational cotton-blend basics, with certification grade and after-sales fitting service bundling as the primary differentiation levers. Pricing pressure stems from recycled polyester feedstock volatility tied to crude oil derivatives and Asian bottle collection rates. Municipal course operators in Texas and Florida exhibit highest price sensitivity, while country club members in Arizona show lowest sensitivity to premium positioning.
Supply Chain Analysis
Extended payment terms from Vietnamese cut-make-trim facilities to North American brands are compressing supplier working capital and accelerating supply-chain finance facility adoption. Manufacturing concentrates in Vietnam, China, and Bangladesh, with raw material dependencies spanning petroleum-derived synthetic fibers, organic cotton certification chains, and fluorine-free chemical treatments. Tariff exposure on Vietnamese wet-processed goods creates structural vulnerability for brands dependent on EPA-monitored dye discharge compliance. Distribution runs through green-grass pro shops, direct-to-consumer authenticated athlete storefronts, and municipal course fitting studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated municipal course operators and resort chains, fragmenting the fragmented country club segment and forcing brands toward volume-tier pricing negotiations.
For Market Incumbents: Entrench technical partnerships with tour professionals to maintain authenticated distribution channels against direct-to-consumer entrants. Deepen backward integration into recycled fiber feedstock to manage petrochemical input volatility and sustain margin control. Prioritize certification investment in fluorine-free water-repellent finishes to defend European market access under REACH evolution. For New Entrants and Emerging Players: Women's skirt-jacket combinations in Sun Belt green-grass pro shops represent the most penetrable entry point given demographic diversification and underdeveloped brand loyalty. Compression base layers for recreational golfers in Arizona and Florida offer secondary white-space capture as functional benefits displace cotton undergarments. Pursue appointment-based custom fitting studio partnerships as the go-to-market angle to bypass wholesale markup structures. For Investors and Strategic Acquirers: Extended producer responsibility framework maturation reshapes the acquisition landscape toward targets with reverse logistics infrastructure and traceable organic cotton sourcing capabilities. Long-term viability favors vertically integrated mid-cap specialists with captive polymer innovation and verified sustainability claims. Monitor California SB 657 transparency mandate enforcement as the signal for first-mover advantage crystallization in supply chain disclosure.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Reformulation | REACH compliance secures European market access for rainwear manufacturers. |
| Recycled Polyester Feedstock Integration | Backward integration insulates margin control from petrochemical volatility. |
| Direct-to-Consumer Athlete Storefront | Tour professional partnerships bypass wholesale markups and capture authenticated demand. |
| Women's Assortment Expansion | Skirt-jacket combinations address underpenetrated demographic diversification in club memberships. |
| Custom Fitting Studio Partnership | Appointment-based services elevate per-visit spend at municipal course operators. |
Research Methodology
A standing panel of apparel procurement directors, green-grass pro shop buyers, textile chemical compliance officers, and tour equipment managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA textile dye discharge monitoring reports, EU ECHA REACH substance restriction updates, and customs trade data on Vietnamese apparel exports. Bottom-up triangulation across material cost structures and top-down reconciliation against aggregate retail audit data anchored volume estimates.
Scenario-bracketing around regulatory enforcement intensity and recycled feedstock availability shaped projections across the analysis window. Segmentation dimensions modeled include product type, material composition, gender category, and geographic demand cluster. CAGRs were derived from fitted trend extrapolation against historical replacement cycle data and tee-time volume correlations in Sun Belt states. Swing biomechanics engineering talent scarcity and extended producer responsibility compliance timelines served as industry-specific forecast modifiers.
Practitioners should monitor REACH perfluorinated compound restriction expansion and California transparency mandate enforcement for early signals of supply chain restructuring. Forecasts reflect assumptions regarding sustained recreational golfer participation rates and municipal course investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Thermal Underwear Market
Apparel & Footwear
Women's Trousers Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Intimate Lingerie Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Women Apparel Market
Apparel & Footwear
Sequins Apparels Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Womens Swimwear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Multiple Toe Socks Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
Innerwear Market