
 India Denim Jeans Market | 2026-2036
India Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
India Denim Jeans Market Insights
Tier-two city consumers and college students are redrawing demand patterns across India's denim ecosystem. Arvind Limited leverages vertical integration from cotton to finished garments across its Gujarat operations. Raymond UCO sustains premium positioning through selvedge and specialty denim production. Nandan Denim anchors bulk fabric supply to both domestic brands and export-oriented manufacturers.
Denim jeans constitute twill-woven cotton garments with indigo-dyed warp threads, typically constructed from 10 to 14 ounce per square yard fabric weight, designed for durable casual and semi-formal wear. Slim fit and skinny variants dominate volume sales among youth and college students, while stretch denim technology captures expanding share as comfort preferences intensify. E-commerce platforms represent the fastest-growing distribution channel, though exclusive brand outlets retain higher margin extraction per unit sold.
BIS fabric standards, Ministry of Textiles water-efficiency guidelines, and state-level pollution control mandates govern manufacturing compliance across denim-producing clusters. These frameworks elevate capital requirements for wet-processing facilities and favor organized producers with effluent treatment investments. Stakeholders must monitor enforcement intensity in Surat, Ahmedabad, and Mumbai textile belts where regulatory scrutiny tightens most acutely.
Market Dynamics
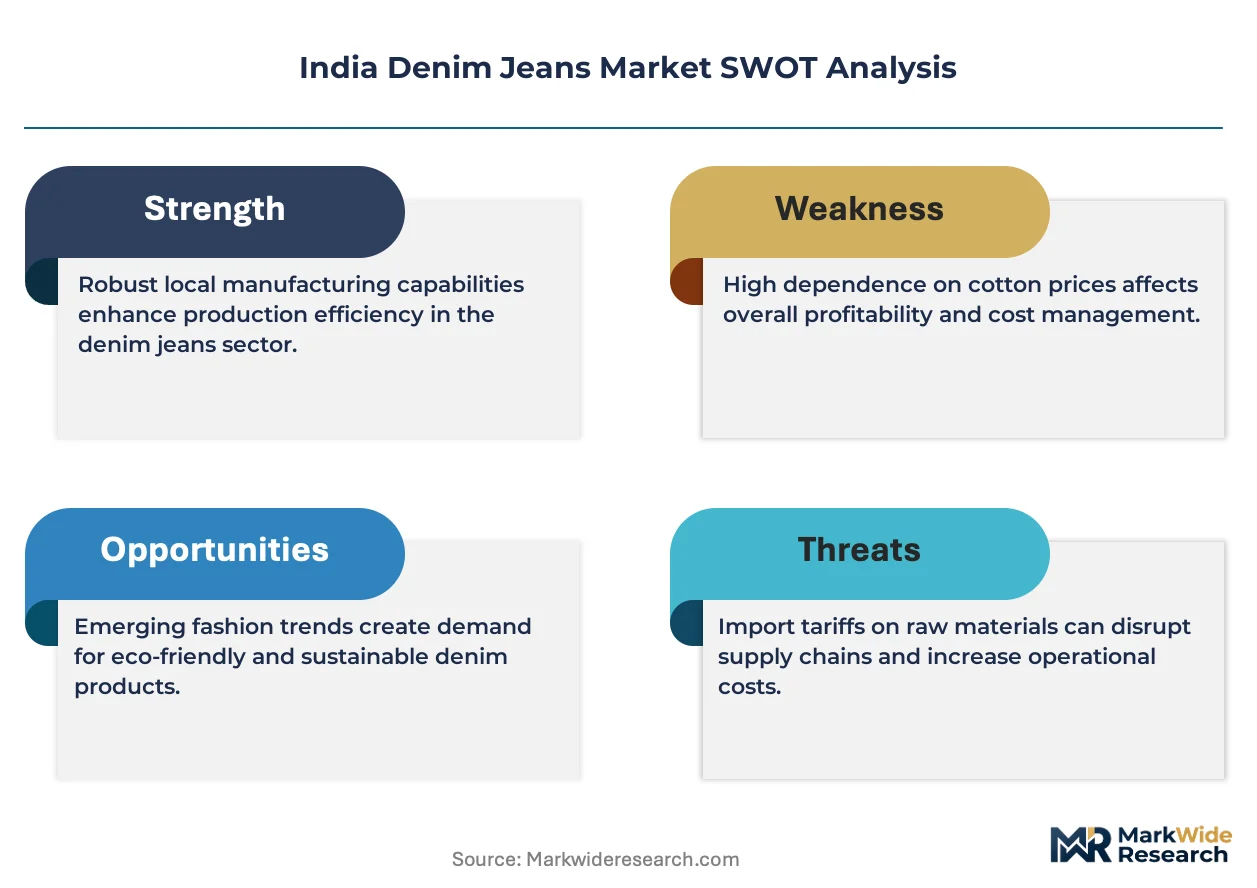
Water-efficiency mandates from the Ministry of Textiles are compressing margins for wet-processing units while favoring Gujarat-based integrated mills with captive effluent treatment infrastructure. This regulatory pressure is redrawing competitive boundaries between organized producers and unorganized clusters across Maharashtra, Karnataka, and Tamil Nadu denim belts.
Growth Catalysts
- E-commerce channel expansion:Tier-two city consumers and college students in Indore, Lucknow, and Jaipur now complete denim purchases through mobile-first platforms, bypassing traditional multi-brand retail intermediaries entirely.
- BIS textile quality mandate:Standardized fabric testing protocols under Bureau of Indian Standards certification are elevating quality consistency across domestic supply chains, reducing import dependency for premium raw materials.
- Stretch denim technology:Lycra and elastane integration into cotton-dominant weaves is capturing preference shifts among young professionals seeking work-appropriate casual wear with extended mobility.
Market Restraints
- Cotton price volatility:Input cost fluctuations for 10-14 ounce per square yard fabric weights compress margin predictability for mid-scale cut-make-trim operators lacking forward contracting with ginneries.
- Surat-Ahmedabad supply concentration:Wet-processing capacity clustering in Gujarat creates geographic vulnerability to monsoon-disrupted effluent discharge and state pollution control board enforcement intensity.
- Technical limitation in waterless dyeing:Laser and ozone finishing technologies remain capital-prohibitive for small-batch producers, constraining adoption of sustainable production methods below certain volume thresholds.
Strategic Opportunities
- Direct-to-consumer channel innovation:Exclusive brand outlets and owned e-commerce storefronts enable margin capture previously surrendered to multi-brand retailers, particularly in Bengaluru and Hyderabad.
- PLI scheme textile incentives:Production-linked incentive allocations for man-made fiber apparel create subsidy tailwinds for denim producers investing in polyester-cotton blend capacity expansion.
- Underpenetrated northeast geography:Assam and Meghalaya markets show latent denim demand with limited organized retail presence, offering first-mover positioning for logistics-integrated brands.
Industry Challenges
- Skill scarcity in sustainable finishing:Operators trained in conventional indigo rope dyeing require re-certification for closed-loop water systems and laser surface treatment equipment.
- Capex intensity for ZLD compliance:Zero liquid discharge mandates from state pollution control boards in Maharashtra and Gujarat demand seven-figure rupee investments in multi-effect evaporators and reverse osmosis recovery.
- Legacy sizing standardization:Inconsistent fit specifications between export-oriented and domestic-market production lines create inventory fragmentation and return-rate elevation for e-commerce fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Denim Jeans Market |
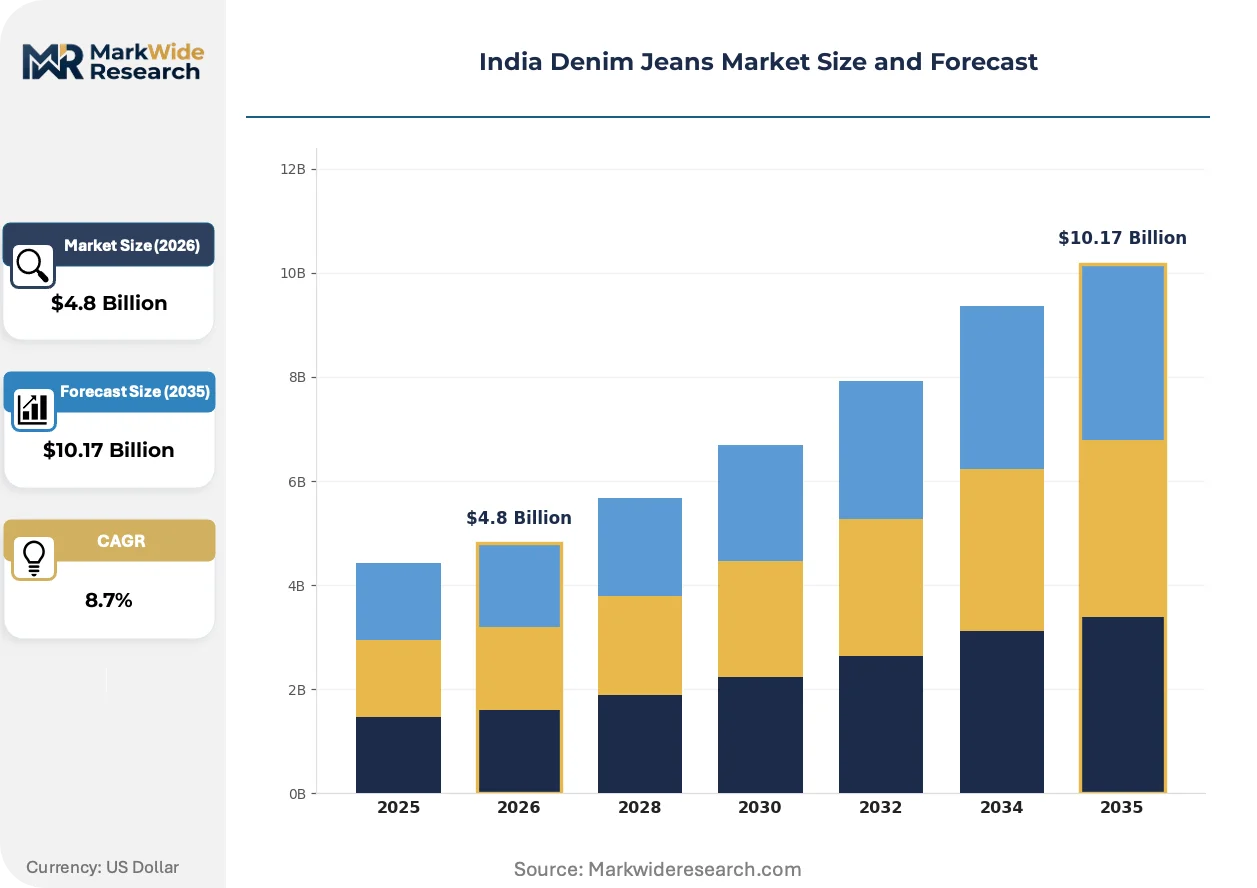
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slim Fit, Regular Fit, Skinny, Bootcut, Relaxed Fit, Straight Leg Fabric Technology: Stretch Denim, Organic Cotton Denim, Stonewashed, Indigo Dyed, Selvedge, Reinforced Denim End User: Youth, Working Professionals, College Students, Casual Wearers, Athleisure Enthusiasts Distribution Channel: Exclusive Brand Outlets, E-Commerce Platforms, Multi-Brand Retailers, Departmental Stores, Specialty Stores |
| Companies Covered | Jindal Worldwide, Sesha Jeans, Arvind Mills, Arvind Limited, DiZNEW, Raymond UCO, Denim Vistara Global, Bellary Jeans Manufacturers, Nandan Denim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Denim Jeans Market Trends and Innovations
Active transformation across India's denim value chain centers on sustainable chemistry adoption, regulatory compliance automation, and channel-specific product architecture. These movements are compressing traditional production timelines while fragmenting quality tiers.
Stretch-recovery denim formulations incorporating dual-core spun yarns is bifurcating the market between premium comfort-positioned brands and commodity rigid-denim suppliers. Young professionals in Pune and Hyderabad are adopting these fabrics for semi-formal workplace contexts at accelerating velocity. This technology is compressing volume share for traditional all-cotton constructions while expanding addressable occasion-wear occasions.
Water-efficiency norms under the Ministry of Textiles are mandating specific liter-per-garment consumption ceilings for licensed manufacturing facilities. Wet-processing units in Surat and Ahmedabad are retrofitting membrane bioreactor systems and counter-current rinsing loops to achieve compliance. Small-scale laundries in the Mumbai textile belt face consolidation pressure from capital requirements and enforcement intensity.
College students and first-job entrants are abandoning multi-brand retail discovery in favor of algorithm-curated mobile commerce with virtual try-on overlays. Myntra and Nykaa Fashion are displacing department store denim floors in tier-two cities like Coimbatore and Nagpur. This behavioral pivot is most visible among 18-25 year demographics in Karnataka and Tamil Nadu where smartphone penetration exceeds national averages.
India Denim Jeans Market Segmentation
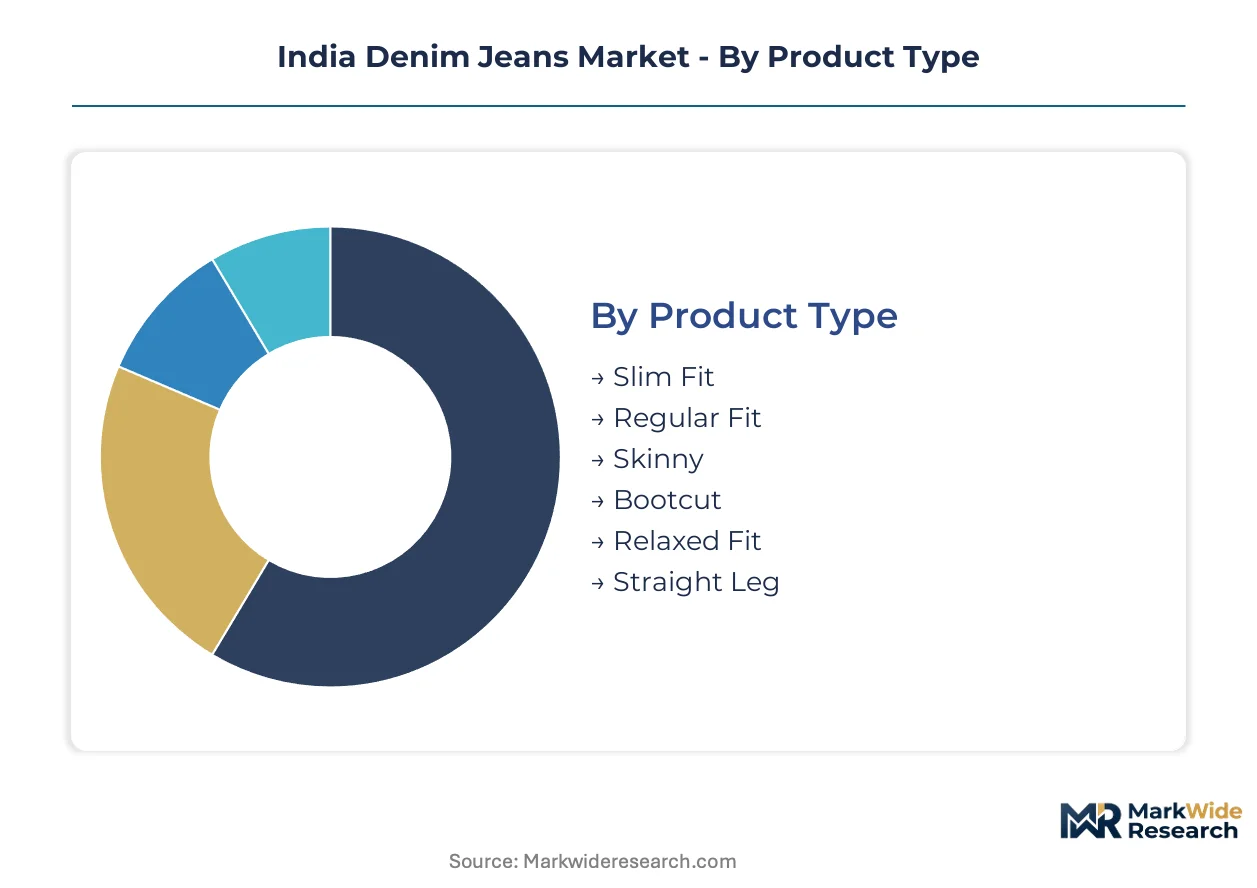
India's denim jeans market fragments across four structural dimensions that determine margin capture and channel economics. Product architecture and fabric technology choices shape manufacturing complexity, while end-user targeting and distribution channel selection dictate customer acquisition costs across tier-one versus tier-two city deployment.
Product Type:
Slim fit and skinny variants flow disproportionately through e-commerce platforms targeting college students in tier-two cities, while regular and relaxed fits sustain multi-brand retail presence in Maharashtra and Gujarat.
- Slim Fit:Tapered leg construction with reduced thigh circumference, typically 10-12 ounce fabric weight. Demand concentrates among working professionals in Bengaluru and Hyderabad seeking semi-formal workplace compatibility with stretch technology integration driving preference.
- Skinny:Second-skin silhouette with highest elastane content requirements, 2-4% Lycra typical. College students in Indore, Lucknow, and Jaipur accelerate purchases through Myntra and Nykaa Fashion, bypassing traditional retail discovery entirely.
- Regular Fit:Classic straight-thigh cut with consistent leg width, 12-14 ounce rigid denim common. Mature consumer base in Ahmedabad and Surat sustains volume through departmental store channels.
- Bootcut:Flared leg opening designed for boot accommodation, heavier fabric weights preferred. Niche positioning in specialty stores serving western-wear enthusiasts in Mumbai and Delhi.
- Relaxed Fit:Generous thigh and seat dimensions prioritizing comfort over silhouette. Casual wearers in tier-three markets drive residual demand through value-oriented multi-brand retailers.
- Straight Leg:Uniform width from hip to ankle, traditional construction methods. Export-oriented production lines in Tamil Nadu favor this specification for standardized sizing.
Slim fit dominates installed base. Skinny is where expansion concentrates.
Fabric Technology:
Cost tier stratification separates premium-positioned selvedge and organic cotton from volume-scale stretch and stonewashed production, with capital requirements for sustainable chemistry widening the gap between organized mills and unorganized laundries.
- Stretch Denim:Dual-core spun yarns integrating cotton with elastane filaments, 15-25% stretch recovery specification. Young professionals in Pune and Hyderabad adopt for extended mobility in workplace contexts, compressing share for rigid constructions.
- Organic Cotton Denim:GOTS-certified fiber with restricted chemical inputs, premium pricing 40-60% above conventional. Bengaluru and Mumbai exclusive brand outlets capture margin from sustainability-positioned consumers.
- Stonewashed:Pumice stone or enzymatic abrasion creating worn surface effect. Surat-Ahmedabad wet-processing clusters face water-efficiency compliance pressure from Ministry of Textiles mandates.
- Indigo Dyed:Traditional rope-dyeing with 6-12 dip cycles for depth of color. Gujarat integrated mills with captive dyehouses maintain cost advantage over merchant processors.
- Selvedge:Shuttle-loom construction with self-finished edge, narrow fabric width. Raymond UCO and premium domestic brands command price premiums through specialty store distribution.
- Reinforced Denim:Kevlar or Cordura fiber integration for abrasion resistance. Motorcycle apparel applications in Delhi and Chandigarh sustain niche demand through dedicated retailers.
Stretch denim dominates installed base. Organic cotton is climbing the fastest.
End User:
Customer type determines product development priorities, with youth and college students driving slim-skinny silhouette innovation while working professionals expand addressable occasions through comfort-technology adoption.
- Youth:16-24 demographic prioritizing trend responsiveness and price accessibility. Algorithm-curated mobile commerce with virtual try-on overlays displaces department store discovery in Karnataka and Tamil Nadu.
- Working Professionals:25-35 segment seeking work-appropriate casual wear. Stretch-recovery formulations capture preference as semi-formal dress codes relax in Pune and Hyderabad corporate environments.
- College Students:First-job entrants with disposable income inflection. Tier-two city e-commerce penetration exceeds national averages for this cohort in Indore, Lucknow, and Jaipur.
- Casual Wearers:Comfort-prioritized consumers across age segments. Regular and relaxed fits sustain multi-brand retail presence in Maharashtra and Gujarat traditional markets.
- Athleisure Enthusiasts:Performance-hybrid expectations migrating from activewear. Jogger-style denim constructions with drawstring waists emerge through specialty athletic retailers in Bengaluru.
Youth dominates installed base. Working professionals show steepest expansion trajectory.
Distribution Channel:
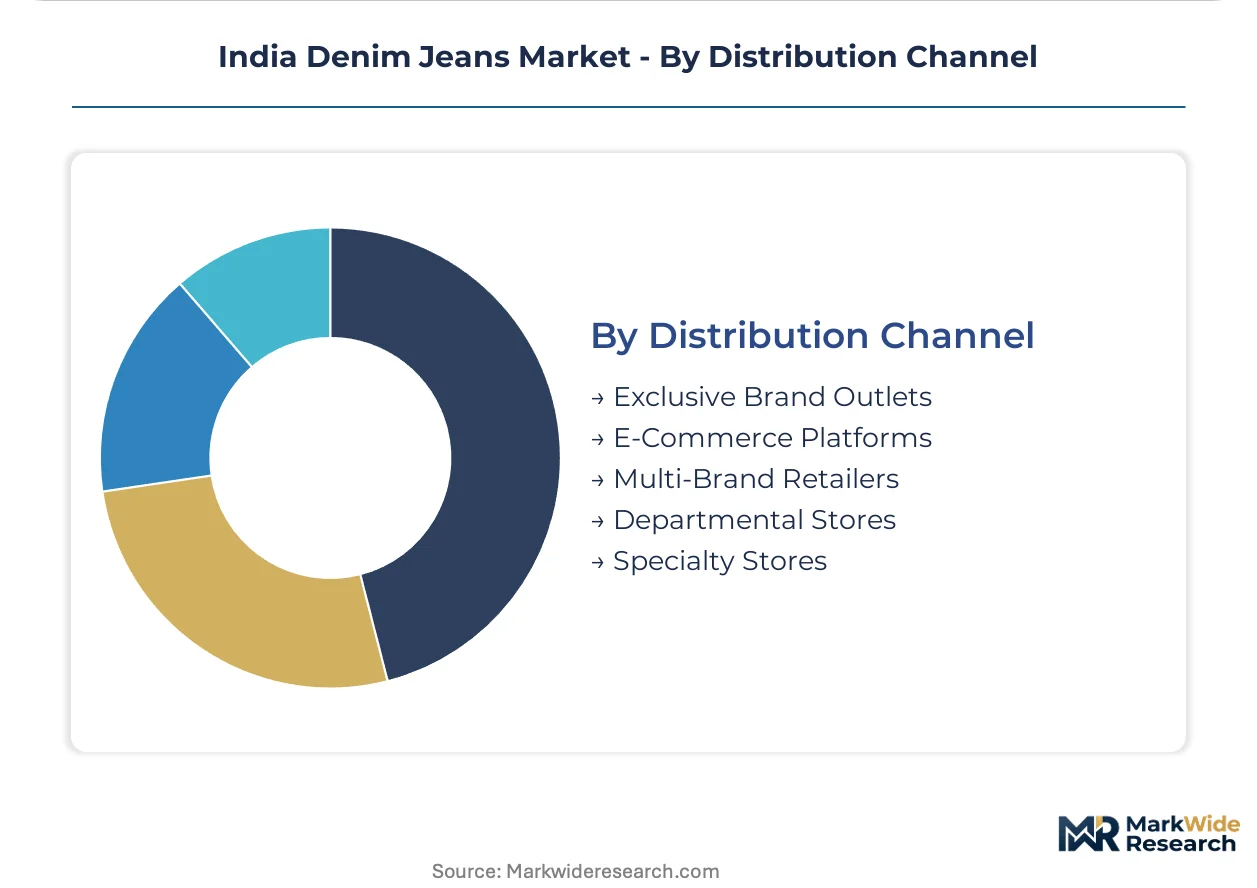
Margin structure varies dramatically, with exclusive brand outlets and owned e-commerce extracting 25-35 percentage points more per unit than multi-brand retail intermediaries while requiring customer acquisition investment.
- Exclusive Brand Outlets:Company-owned storefronts with full assortment control. Arvind Limited and Raymond UCO deploy in Maharashtra, Gujarat, and Karnataka for premium positioning and data capture.
- E-Commerce Platforms:Myntra, Nykaa Fashion, and owned direct-to-consumer sites. Fastest-expanding channel for tier-two city consumers and college students bypassing traditional intermediaries.
- Multi-Brand Retailers:Department store denim floors and independent apparel chains. Margin compression from inventory risk and promotional pricing intensity in Mumbai and Delhi.
- Departmental Stores:Full-line retailers with dedicated denim sections. Mature consumer base in Ahmedabad and Surat sustains volume for regular and relaxed fit specifications.
- Specialty Stores:Denim-focused retailers with expert fitting services. Selvedge and premium stretch positioning in Bengaluru and Hyderabad command price premiums through curation.
Multi-brand retailers dominate installed base. E-commerce platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra anchors denim export logistics, connecting Surat-Ahmedabad manufacturing clusters to global buyers through containerized shipping lanes.
Maharashtra
Mumbai's organized retail density and Pune's corporate workforce sustain premium denim absorption. BIS textile quality mandates elevate compliance costs for Thane-based wet-processing units. The Mumbai textile belt faces consolidation pressure as pollution control board enforcement intensifies around effluent discharge norms.
Gujarat
Ahmedabad and Surat concentrate India's denim fabric production with integrated mills commanding captive dyehouse advantages. Ministry of Textiles water-efficiency guidelines favor operators with multi-effect evaporator investments. The Surat-Ahmedabad corridor attracts capital fleeing Maharashtra's stricter zero liquid discharge implementation timelines.
Karnataka
Bengaluru's technology workforce and Hyderabad's pharmaceutical professionals expand stretch denim demand for semi-formal workplace contexts. State pollution control mandates in Telangana lag Gujarat enforcement intensity, drawing mid-scale finishing operations. The Bengaluru-Mysuru industrial corridor hosts expanding exclusive brand outlet networks targeting young professionals.
Tamil Nadu
Coimbatore's textile engineering base and Tiruppur's garment export infrastructure support denim cut-make-trim capacity. Central government PLI scheme incentives for man-made fiber apparel attract polyester-cotton blend investments. The Chennai-Coimbatore belt struggles with skill scarcity for laser finishing equipment operation.
Delhi-NCR
The National Capital Region's distribution hub function connects northern markets to Gujarat-Maharashtra supply sources. NGT-mandated pollution control restrictions on Yamuna basin effluent discharge compress wet-processing margins. Ghaziabad and Faridabad logistics parks enable e-commerce fulfillment velocity for tier-two city consumers.
India Denim Jeans Market Competitive Landscape
Listed leaders compete with private specialists across integrated manufacturing versus merchant processing capabilities. Arvind Limited and Raymond UCO leverage public market access for capital-intensive compliance investments while private mills retain operational flexibility. Three archetypes dominate: vertically integrated fabric-to-garment operators, standalone fabric merchants, and branded retail specialists. Capacity expansion and direct-to-consumer channel development constitute the primary competitive vectors as multi-brand retail margins compress.
Among integrated specialists, Arvind Limited and Raymond UCO exemplify the fabric-to-retail archetype with captive supply chains, while Nandan Denim anchors the merchant fabric tier supplying domestic brands and export-oriented manufacturers. These three entities represent distinct positioning strategies—backward integration into cotton sourcing, premium selvedge specialization, and bulk commodity supply—illustrating how scale and specialization bifurcate competitive returns.
| Leading Market Players |
|---|
| Jindal Worldwide |
| Sesha Jeans |
| Arvind Mills |
| Arvind Limited |
| DiZNEW |
| Raymond UCO |
| Denim Vistara Global |
| Bellary Jeans Manufacturers |
| Nandan Denim |
| Others |
Pricing and Supply Chain Analysis
Elastane substitution for rigid cotton constructions is redrawing supply geography toward Gujarat's integrated mills while compressing margin structures for Maharashtra's merchant processors. This input shift simultaneously elevates capital requirements for stretch-recovery equipment and concentrates pricing power with operators possessing captive yarn-to-fabric capabilities.
Pricing Analysis
Volume-discount tiering structures separate Raymond UCO's selvedge positioning from Arvind Limited's standard-tier scale economics and unorganized cluster commodity supply. Three-tier pricing stratification across premium, standard, and economy levels reflects fabric technology grade and BIS certification status as primary differentiation drivers. Pricing pressure stems from cotton price volatility and wet-processing compliance investments, with college students and tier-two e-commerce buyers exhibiting highest price sensitivity while exclusive brand outlet customers show lowest elasticity.
Supply Chain Analysis
India and Bangladesh anchor denim fabric and garment finishing capacity, with Gujarat's Surat-Ahmedabad corridor commanding captive dyehouse advantages over Tamil Nadu's cut-make-trim operations. Raw material flows draw from Maharashtra cotton ginneries, imported elastane filaments, and indigo dye concentrates. Single-source vulnerability concentrates in Surat-Ahmedabad wet-processing clustering exposed to monsoon-disrupted effluent discharge. Distribution runs through Jawaharlal Nehru Port Trust containerized exports, exclusive brand outlet networks in Maharashtra and Karnataka, and Myntra-led e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's denim ecosystem rewards operators with closed-loop water chemistry expertise and stretch-recovery formulation capabilities, while scarcity of laser-finishing technicians and membrane bioreactor operators constrains expansion timelines for sustainability-positioned production.
For Market Incumbents: Secure zero-liquid-discharge compliance ahead of Maharashtra Pollution Control Board enforcement intensification through multi-effect evaporator investments. Deepen captive yarn production to offset cotton price volatility threatening mid-tier margin structures. Channel control through exclusive brand outlet expansion in Bengaluru and Hyderabad captures margin surrendered to multi-brand retail intermediaries. For New Entrants and Emerging Players: BIS certification fast-tracks unlock multi-brand retail shelf access previously blocked by quality inconsistency perceptions. Underpenetrated Assam and Meghalaya markets offer white-space positioning for logistics-integrated direct-to-consumer brands. Algorithm-curated mobile commerce with virtual try-on overlays provides lowest customer acquisition cost entry for college student targeting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed fabric merchants lacking garment-forward integration. Five-to-ten-year viability favors operators with demonstrated PLI scheme qualification and demonstrated compliance automation. Watch for state pollution control board enforcement intensity divergence between Gujarat and Maharashtra as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Zero Liquid Discharge Compliance | Maharashtra Pollution Control Board mandates elevate capital barriers for wet-processing units. |
| Stretch Denim Capacity Expansion | Dual-core spun yarn investments capture preference shifts among Pune and Hyderabad professionals. |
| Direct-to-Consumer Channel Launch | Owned e-commerce storefronts extract 25-35 percentage point margin premiums over multi-brand retail. |
| BIS Certification Fast-Track | Standardized fabric testing protocols reduce import dependency for premium raw materials. |
| Northeast Geography Market Entry | Assam and Meghalaya latent demand offers first-mover positioning for logistics-integrated brands. |
Research Methodology
Initial hypotheses were tested against primary input from denim mill operations directors, brand sourcing managers, pollution control board enforcement officers, and e-commerce category buyers and refined through secondary validation. Trade data from Ministry of Textiles production surveys, DGFT export registrations, BIS certification databases, and state pollution control discharge records anchored quantitative triangulation. Bottom-up volume builds across product type, fabric technology, end user, and distribution channel segments reconciled with top-down market sizing.
Variance-decomposition framing isolated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled encompass product architecture, fabric technology tier, customer demographic, and channel economics with regional regulatory cluster overlays. CAGRs derived from historical trajectory analysis adjusted for PLI scheme incentive phase-ins and water-efficiency mandate compliance timelines. Forecast inputs incorporated cotton futures curve expectations and smartphone penetration trajectories in tier-two cities.
Underlying assumptions cover enforcement intensity continuity for Maharashtra and Gujarat pollution control boards, with deviation risk concentrated in monsoon-disrupted effluent discharge capacity and elastane import tariff adjustments. Forecasts reflect documented assumptions with revision triggers tied to regulatory enforcement divergence or cotton price volatility spikes. Recalibration cycles align with material shifts in Ministry of Textiles mandate implementation schedules and state-level zero-liquid-discharge deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Tights and Leggings Market
Apparel & Footwear
Plus Size Clothing Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Adaptive Shapewear Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Vegan Women's Fashion Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
Global Women Pajamas Suits Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
Heated Jacket Market