
 Gym Apparel Market | 2026-2036
Gym Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Apparel Market Outlook
Multi-source fabric procurement is consolidating as brands reduce supplier fragmentation to secure recycled polyester and organic cotton at scale. Nike leverages vertical control over knit innovation to protect margin pools in premium leggings. Under Armour competes through compression-science R&D anchored in Baltimore. Lululemon differentiates via community-driven design feedback loops that sustain price premiums.
Gym apparel encompasses engineered garments constructed from moisture-wicking synthetic blends or natural fibers with elastane content, manufactured through circular knitting or flatlock seaming to deliver four-way stretch, breathability, and abrasion resistance during resistance training, cardio, and flexibility work. Leggings and shorts command the largest volume pools, while spandex-weighted fabrications capture disproportionate margin due to performance premiums. The men's segment trails women's in absolute value but outpaces in entry-frequency among first-time gym members.
The EU Green Deal and REACH chemical restrictions are tightening disclosure requirements for dyeing processes and synthetic microfiber release, compelling reformulation of polyester-nylon blends. The US FTC's Green Guides and California's SB 657 transparency mandates further elevate compliance costs for brands selling across both jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate capital requirements for closed-loop recycling infrastructure.
Market Dynamics
The EU Green Deal's textile sustainability mandates are forcing rapid reformulation of polyester-nylon blends across the value chain, compressing legacy sourcing windows and elevating compliance capital requirements for brands operating in European markets.
Growth Catalysts
- Boutique Fitness Proliferation:CrossFit affiliates and specialized studios in the United States, China, and Germany are compressing apparel refresh cycles from annual to quarterly patterns, sustaining volume velocity in premium leggings and shorts.
- REACH Chemical Restrictions:ECHA's tightening disclosure requirements for dyeing processes are accelerating investment in waterless coloration technologies, creating first-mover advantages for compliant suppliers.
- Recycled Polyester Scale:Mechanical recycling infrastructure in Germany and the Netherlands is achieving commercial-grade rPET output, reducing virgin polymer dependency for moisture-wicking base layers.
Market Restraints
- Organic Cotton Input Volatility:Weather-driven yield fluctuations in India and Turkey are creating 15-20% price swings for GOTS-certified fiber, squeezing margin pools in natural-fiber product lines.
- Spandex Supply Concentration:Over 70% of global elastane production clusters in China and South Korea, exposing brands to single-source risk during port congestion or energy rationing events.
- Microfiber Release Technical Ceiling:Current filtration and yarn-coating technologies cannot achieve sub-10% synthetic fiber shedding during high-abrasion washing cycles, limiting sustainability claims.
Strategic Opportunities
- India Underpenetration:Organized fitness participation in Indian metros remains below 5% of addressable population, offering white-space expansion for entry-price compression wear.
- Extended Producer Responsibility Tailwinds:France's AGEC law and pending EU-wide textile EPR frameworks are mandating take-back infrastructure, rewarding brands with pre-positioned closed-loop recycling partnerships.
- Bio-Based Elastane Convergence:Fermentation-derived spandex from sugar feedstocks is converging with existing circular knitting equipment, enabling performance parity without petrochemical inputs.
Industry Challenges
- Digital Product Passport Implementation:EU CSRD-aligned traceability systems require SKU-level chemical disclosure, forcing IT architecture overhauls and supplier data integration at 18-month compliance deadlines.
- Flatlock Seam Specialist Scarcity:Four-way stretch construction demands skilled machine operators for chafe-free seaming, with training pipelines failing to match capacity expansion in Vietnam and Bangladesh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Apparel Market |
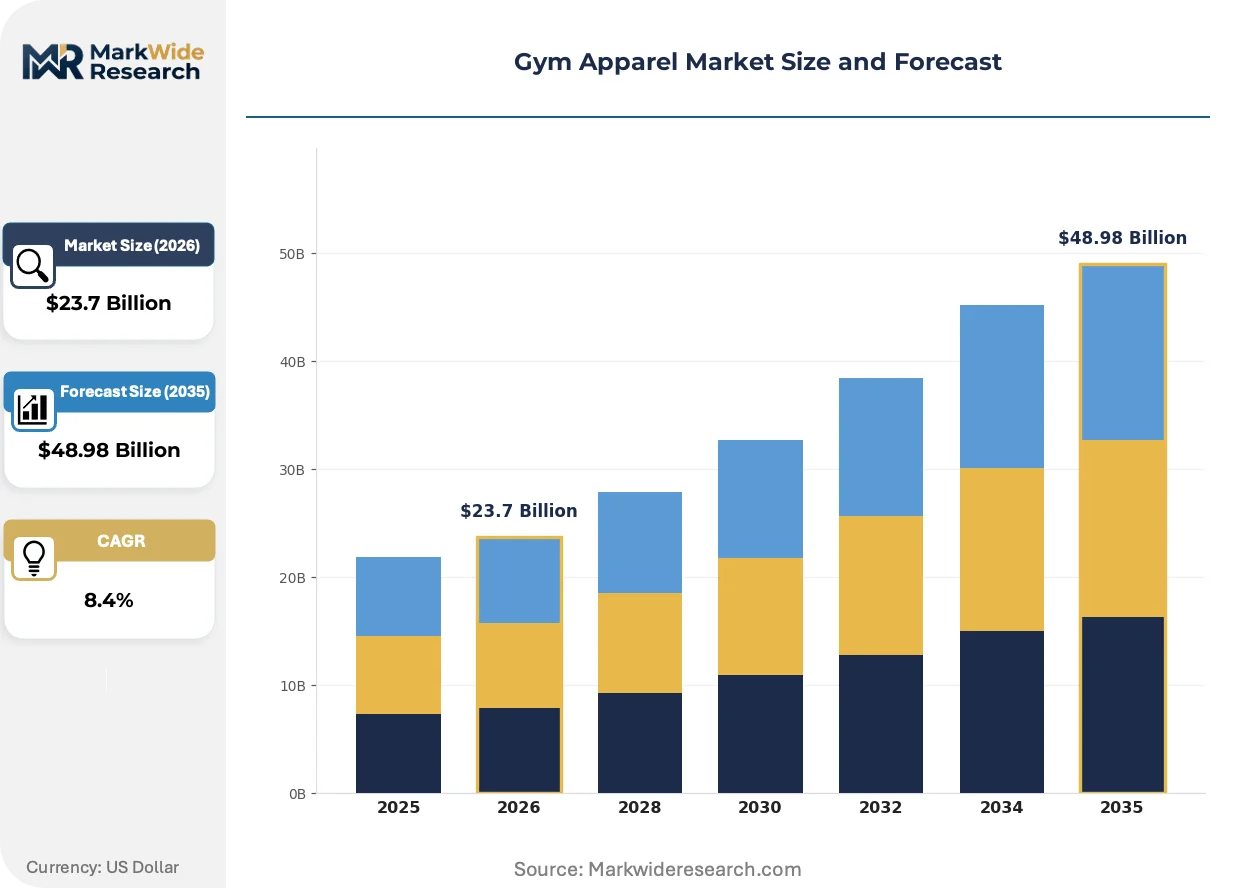
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Shorts, Tanks, Hoodies End User: Men, Women, Kids, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Fitness Centers Material: Cotton, Polyester, Nylon, Spandex |
| Companies Covered | ANTA Sportswear, Alo Yoga, Nike, Under Armour, Athleta, adidas, Gymshark, ASICS, Lululemon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Apparel Market Strategic Shifts
Material science breakthroughs and regulatory disclosure mandates are converging to reshape competitive positioning in performance wear, with sustainability credentials now functioning as primary purchase triggers alongside technical specifications.
Seamless circular knitting with integrated compression zones is overtaking traditional cut-and-sew construction for high-intensity training leggings. Boutique studios in Germany and the United States are specifying these garments for instructor uniforms, compressing production lead times from six weeks to ten days while eliminating thread failure points under load.
EU Green Deal textile sustainability requirements are mandating lifecycle impact disclosure for all garments sold in member states. Brands must now document water consumption, chemical inputs, and end-of-life pathways through standardized digital formats, elevating compliance costs most acutely for mid-tier private labels lacking captive sustainability teams.
Athlete-influencer co-creation models are displacing traditional seasonal design calendars in premium positioning. Lululemon's community feedback loops in Vancouver and London are compressing concept-to-shelf timelines, while direct-to-consumer channels in China bypass wholesale margin extraction entirely.
Gym Apparel Market Segmentation
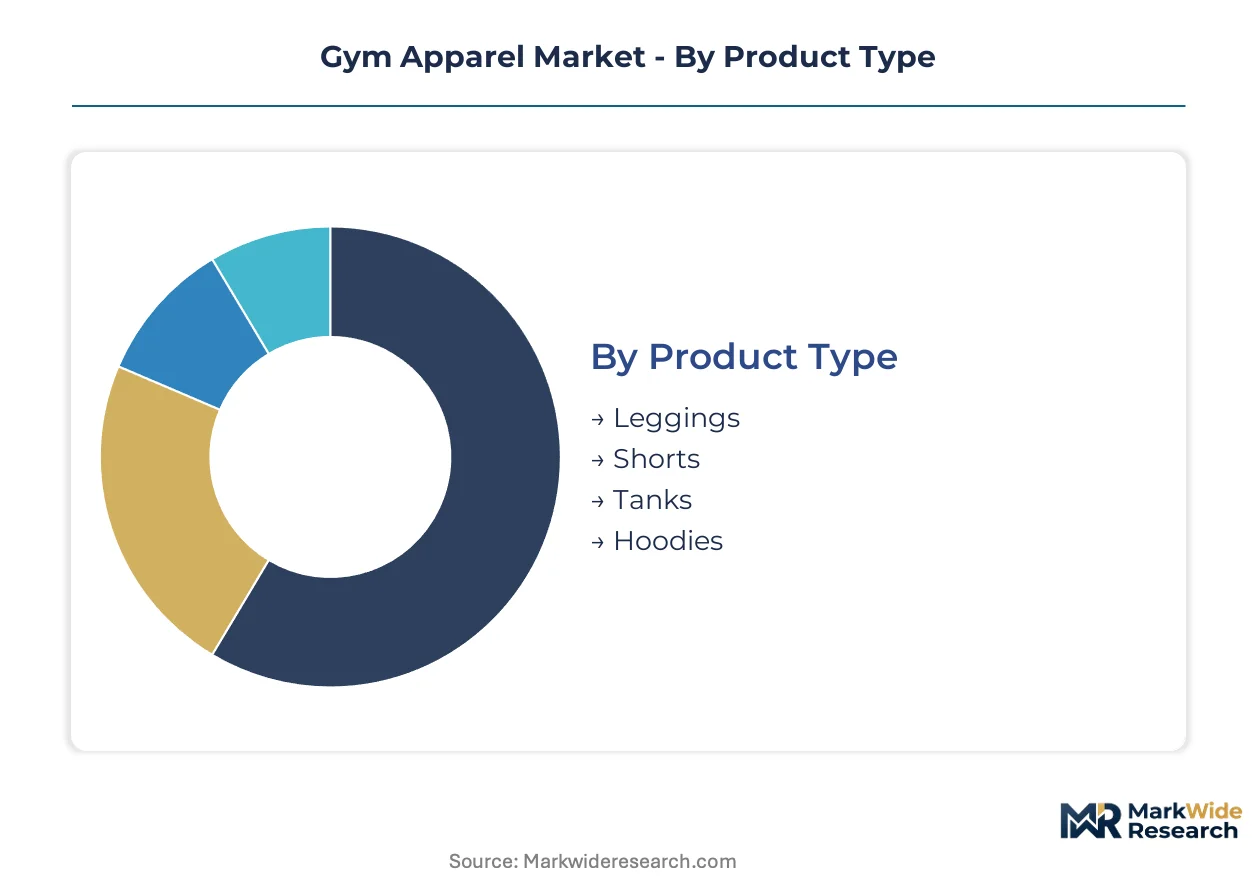
Gym apparel segmentation reveals how refresh cycles, performance specifications, and channel economics fragment demand across distinct purchase occasions. Understanding these divides enables targeted positioning against boutique studio procurement patterns and direct-to-consumer growth corridors.
Product Type:
Upgrade cycles vary dramatically by garment category, with compression leggings demanding quarterly replacement versus annual hoodie refresh patterns.
- Leggings:Engineered with four-way stretch nylon-spandex blends and gusseted crotch construction for squat-depth mobility. Boutique studios in Germany and the United States specify seamless circular-knit variants for instructor uniforms, compressing production lead times from six weeks to ten days.
- Shorts:Moisture-wicking polyester constructions with integrated compression liners dominate high-intensity training. CrossFit affiliates drive specification of abrasion-resistant flatlock seams for barbell contact zones.
- Tanks:Lightweight racerback silhouettes with dropped armholes target hypertrophy-focused resistance training. Breathable mesh paneling concentrates demand among bodybuilding subcultures in United States metro markets.
- Hoodies:Cotton-polyester fleece blends with athletic tapering serve warm-up and cool-down protocols. Seasonal demand spikes align with Q4 gym membership enrollment waves in temperate climates.
Leggings sit at the top of the volume ranking, with shorts climbing the fastest as boutique fitness formats proliferate.
End User:
Gender-based purchasing frequency creates divergent margin architectures, with women's segments sustaining premium pricing through design refresh velocity.
- Men:Entry-frequency leadership among first-time gym members drives volume in basic compression shorts and moisture-wicking tanks. Simplified color palettes and standardized fits reduce SKU complexity for mass-market positioning.
- Women:Absolute value concentration with highest per-transaction values in premium leggings and coordinated sets. Community-driven design feedback loops in Vancouver and London sustain price premiums through rapid concept-to-shelf compression.
- Kids:Growth contingent on youth sports formalization and school physical education mandates. Size scaling challenges and rapid outgrowth patterns compress margin pools versus adult equivalents.
- Fitness Enthusiasts:Performance-obsessed segment specifying technical specifications including CFM breathability ratings and UPF protection. Direct-to-consumer channels in China bypass wholesale margin extraction for this cohort.
Women command the largest absolute revenue pool, with fitness enthusiasts gaining share fastest through premium channel migration.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost tradeoffs, with fitness centers emerging as high-conversion, low-CPA environments.
- Online Retail:Dominates discovery and replenishment purchasing with algorithmic personalization driving cross-sell. Return rate elevation in fit-dependent categories compresses net margins versus physical retail.
- Specialty Stores:Curated assortments with trained staff enabling technical specification matching. Experiential merchandising including in-store sweat testing differentiates against mass-market alternatives.
- Department Stores:Volume concentration in entry-price tiers with seasonal promotional cadence. Private label expansion threatens branded positioning in this channel.
- Fitness Centers:Proximity-based impulse purchasing at point of workout with instructor endorsement carrying conversion weight. Limited SKU depth constrains basket expansion.
Online retail leads volume contribution, with fitness centers expanding most quickly as boutique formats scale.
Material:
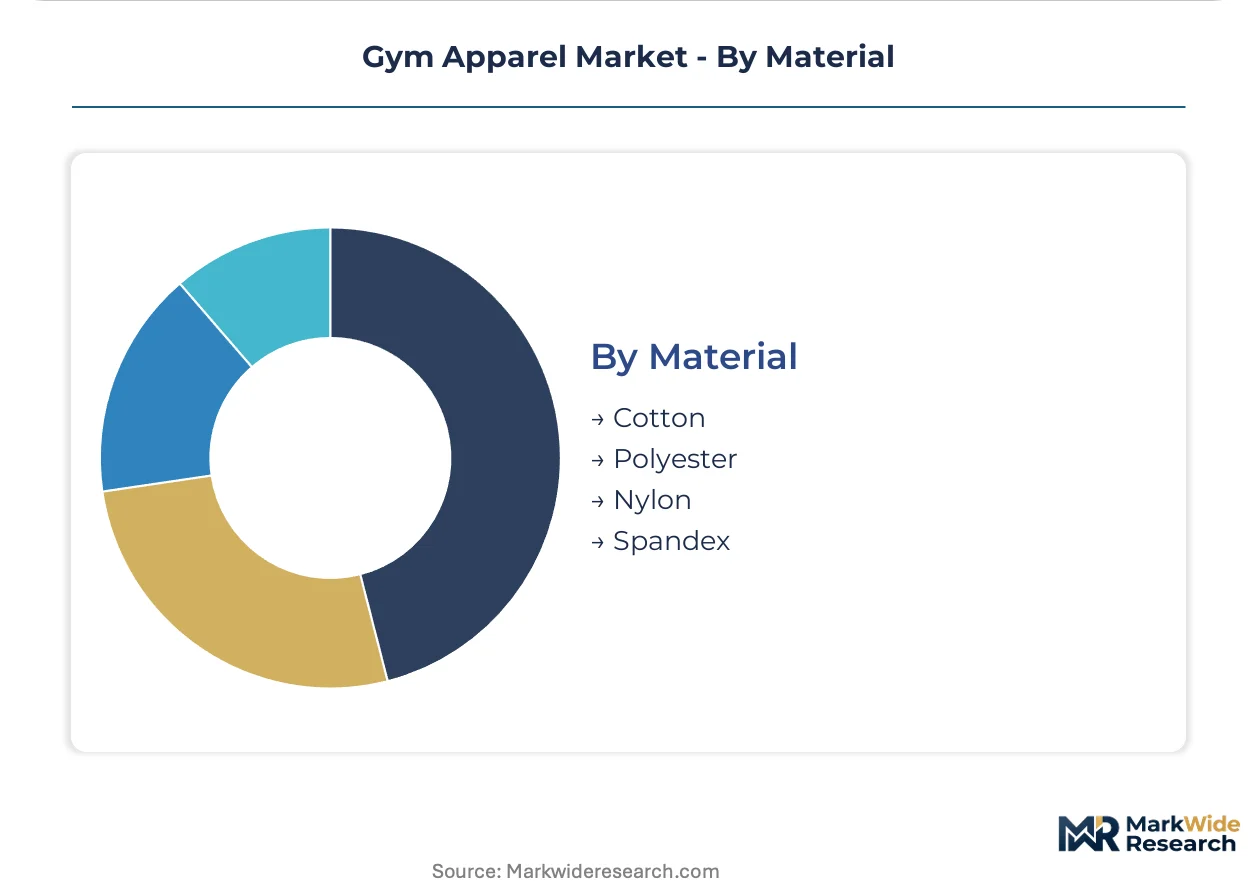
Raw material selection governs performance certification eligibility and regulatory compliance exposure across EU and US jurisdictions.
- Cotton:Natural fiber preference for low-intensity and lifestyle crossover applications. GOTS-certified organic variants face 15-20% price volatility from weather-driven yield fluctuations in India and Turkey.
- Polyester:Mechanical recycling infrastructure in Germany and the Netherlands achieves commercial-grade rPET output for moisture-wicking base layers. EU Green Deal disclosure mandates elevate compliance costs for virgin polymer alternatives.
- Nylon:Superior abrasion resistance for high-friction training modalities. REACH chemical restrictions on dyeing processes accelerate waterless coloration technology investment.
- Spandex:Elastane content determines compression graduation and recovery characteristics. Over 70% production concentration in China and South Korea creates single-source risk exposure.
Polyester dominates volume throughput, with spandex commanding steepest expansion trajectory as compression-science R&D intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors gym apparel demand through boutique fitness proliferation and direct-to-consumer channel maturation. Germany and China follow as volume centers, each shaped by distinct regulatory and industrial configurations.
United States
Boutique fitness studios in New York and Los Angeles compress apparel refresh cycles to quarterly patterns. The FTC's Green Guides elevate compliance costs for sustainability claims across state lines. CrossFit affiliates in Austin and Miami specify abrasion-resistant flatlock seaming for instructor uniforms.
China
Organized fitness participation in Shanghai and Beijing drives compression wear volume among first-time gym members. MIIT's dual carbon goals accelerate mechanical recycling infrastructure investment in Zhejiang province. Spandex production clusters in Jiangsu province expose brands to single-source risk during energy rationing events.
Germany
REACH chemical restrictions from ECHA force rapid reformulation of polyester-nylon blends for EU market access. Commercial-grade rPET output from mechanical recycling facilities in the Netherlands reduces virgin polymer dependency. Berlin and Munich host boutique studio chains specifying seamless circular-knit construction.
India
Organized fitness penetration in Mumbai and Delhi remains below five percent of addressable population. BIS certification requirements for textile imports create compliance friction for foreign brands. GOTS-certified organic cotton price volatility from weather-driven yield fluctuations squeezes margin pools.
United Kingdom
Athlete-influencer co-creation models in London compress concept-to-shelf timelines for premium positioning. The UK's post-EU regulatory divergence creates dual compliance burdens for brands serving both markets. Manchester and Birmingham concentrate direct-to-consumer fulfillment infrastructure.
Gym Apparel Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue community-driven design feedback and bio-based material innovation. The vendor base organizes around three archetypes: vertically integrated sportswear conglomerates, specialist compression-science developers, and direct-to-consumer digital natives. Dominant competitive moves include strategic partnerships with recycling infrastructure operators and portfolio diversification into closed-loop material systems.
Within the premium-tier vector, Lululemon exemplifies community-anchored positioning through Vancouver and London design feedback loops. Nike and Under Armour occupy scale-driven positions, with the former leveraging knit innovation control and the latter anchoring R&D in Baltimore. Among Asia-Pacific-based challengers, ANTA Sportswear represents vertical integration into performance wear manufacturing.
| Leading Market Players |
|---|
| ANTA Sportswear |
| Alo Yoga |
| Nike |
| Under Armour |
| Athleta |
| adidas |
| Gymshark |
| ASICS |
| Lululemon |
| Others |
Value Chain & Pricing Dynamics
Spandex-weighted fabrications trace cost pressure from elastane production clusters in China and South Korea through premium leggings pricing tiers, with compression-science R&D investments filtering into final consumer price points across boutique studio procurement channels.
Pricing Analysis
Input-cost pass-through from GOTS-certified organic cotton volatility in India and Turkey compresses margin pools in natural-fiber product lines. Three-tier pricing structure across premium, standard, and economy levels separates community-driven design feedback loops from mass-market entry-price compression wear. Pricing pressure stems from REACH chemical restrictions elevating dyeing process compliance costs. First-time gym members in the men's segment exhibit highest price sensitivity, while fitness enthusiasts sustain premium positioning through direct-to-consumer channels.
Supply Chain Analysis
Reverse-logistics flows for take-back infrastructure under France's AGEC law and pending EU-wide textile EPR frameworks are mandating closed-loop recycling partnerships. Manufacturing concentrates in Bangladesh, Vietnam, and China for cut-and-sew construction, with circular knitting equipment clustering in Germany and the Netherlands. Raw material dependencies center on recycled polyester from mechanical recycling facilities, organic cotton from GOTS-certified suppliers, and fermentation-derived bio-based elastane. Single-source vulnerability from over 70% spandex production concentration in China and South Korea exposes brands to energy rationing events. Distribution runs through direct-to-consumer channels, specialty stores with experiential merchandising, and fitness center proximity-based impulse purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gym apparel offers margin-expansion potential as bio-based elastane convergence with existing circular knitting equipment reduces petrochemical input dependency while premium tier pricing sustains through community-anchored design velocity.
For Market Incumbents: Deploy backward integration into mechanical recycling infrastructure to secure rPET supply streams against virgin polymer cost volatility. Anchor R&D investment in waterless coloration technologies to capture first-mover advantage under REACH chemical restrictions. Defensive consolidation through pre-positioned closed-loop recycling partnerships mitigates extended producer responsibility capital requirements. For New Entrants and Emerging Players: Direct-to-consumer channels in China offer the most penetrable route for bypassing wholesale margin extraction entirely. Target entry-price compression wear in Indian metros where organized fitness participation remains below five percent of addressable population. Community-driven design feedback loops enable rapid concept-to-shelf compression without legacy seasonal calendar constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where flatlock seam specialist scarcity in Vietnam and Bangladesh constrains capacity expansion against boutique fitness proliferation. Long-term viability favors brands with upstream control over knit innovation and pre-positioned sustainability certification. Acquisition target archetypes include specialist compression-science developers with captive bio-based elastane partnerships. Monitor EU CSRD-aligned digital product passport implementation deadlines as inflection indicator for compliance cost burden distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Secures rPET supply streams from Netherlands and Germany mechanical recycling facilities. |
| Waterless Coloration Technology Investment | Captures first-mover advantage under ECHA REACH dyeing disclosure mandates. |
| Community-Driven Design Feedback Loops | Compresses concept-to-shelf timelines through Vancouver and London studio networks. |
| Direct-to-Consumer Channel Expansion | Bypasses wholesale margin extraction in China fitness enthusiast segments. |
| Bio-Based Elastane Partnership Development | Enables fermentation-derived spandex performance parity without petrochemical inputs. |
Study Parameters
Multiple input streams — primary interviews with brand sustainability officers, boutique studio procurement managers, and circular knitting equipment specialists, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Secondary sources included EU ECHA regulatory filings, FTC Green Guides documentation, customs trade data for textile imports, and SEC 10-K disclosures from publicly traded sportswear conglomerates.
Data-stream reconciliation across product type, end user gender segment, distribution channel, and material composition dimensions anchored volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis incorporating boutique fitness studio expansion rates, regulatory compliance cost curves, and mechanical recycling infrastructure capacity buildouts.
The model assumes a particular technology adoption path; alternative pathways for bio-based elastane fermentation scale-up would alter the outlook. Forecasts reflect assumptions regarding REACH chemical restriction enforcement timelines and EU textile EPR framework implementation. Practitioners should monitor digital product passport compliance deadlines and flatlock seam training pipeline expansion in Vietnam and Bangladesh for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Men Jeans Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Designer Sneaker Market
Apparel & Footwear
North America Denim Jeans Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Cosplay Costumes Market