
 Europe Jeans Market | 2026-2036
Europe Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Jeans Market Foresight
Aftermarket repair and resale revenue is narrowing the margin gap with first-sale production across European denim. Levi Strauss & Co leverages its authorized vintage program to capture circular value, while Inditex sustains rapid inventory turnover through vertically controlled design-to-retail pipelines. MUD Jeans differentiates via a subscription-based leasing model that retains material ownership.
Jeans constitute trousers cut from twill-woven cotton denim, typically weighing 12 to 14.5 ounces per square yard, with indigo-dyed warp threads and undyed weft creating the characteristic blue surface. The garment serves as durable casual wear across occupational, social, and fashion contexts. Skinny and wide-leg cuts dominate unit volume, though selvedge denim commands the highest per-unit margins due to artisanal shuttle-loom construction and narrow-batch scarcity. Women's unisex-adjacent styling is the fastest-growing customer type as gender-fluid retail assortments expand across mid-range and luxury price tiers.
REACH restricts azo dyes and heavy-metal finishes, compelling reformulation of wash and distressing chemistry across Portuguese and Turkish finishing houses. The EU Green Deal's textile strategy mandates extended producer responsibility, forcing brands to redesign for recyclability or face compliance penalties. Stakeholders must monitor how ECHA expands restricted substance lists and whether circular business models achieve unit economics that outcompete conventional seasonal production.
Market Dynamics
EU Green Deal mandates and REACH chemical restrictions are forcing denim manufacturers to reconfigure finishing chemistry, water consumption, and end-of-life accountability across Portuguese and Turkish supply clusters.
Growth Catalysts
- REACH chemical reformulation:ECHA's expanding restricted substance lists are accelerating adoption of waterless dyeing and laser-based distressing technologies in Italian and Spanish finishing houses.
- Millennial and Gen-Z premium adoption:German and French consumers aged 25-40 are driving demand for heritage craftsmanship and selvedge construction, sustaining price premiums for artisanal shuttle-loom output.
- Organic cotton sourcing:Turkish and Greek cotton growers are capturing expanded contract volumes as brands redesign supply chains to meet EU Green Deal textile strategy benchmarks.
Market Restraints
- Water-intensive finishing:Traditional stone-washing and bleach-based distressing processes face escalating utility costs and regulatory scrutiny across Mediterranean production zones.
- Supply concentration in Turkey:Near-shoring has amplified dependency on a single geography for cut-make-trim operations, exposing brands to currency volatility and geopolitical friction.
- Biological indigo limitations:Microbial and plant-derived indigo alternatives remain cost-prohibitive at scale, constraining rapid decarbonization of dye chemistry.
Strategic Opportunities
- Subscription leasing models:Dutch and Scandinavian markets demonstrate viable unit economics for material-retention services that decouple revenue from virgin production.
- Authorized vintage channels:Secondary market authentication and repair infrastructure in France and Italy can capture circular value streams previously lost to uncontrolled resale.
- EU extended producer responsibility:Mandatory textile collection and recycling targets create first-mover advantage for brands designing disassembly-ready hardware and fiber-to-fiber recovery systems.
Industry Challenges
- Shuttle-loom operator scarcity:Artisanal selvedge production depends on aging specialized labor pools in Northern Italy and Japan, with limited apprenticeship pipeline replacement.
- Recyclability design retrofit:Existing garment architectures incorporating stretch fibers, rivets, and synthetic thread blends require costly redesign to meet emerging fiber-to-fiber recovery standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Jeans Market |
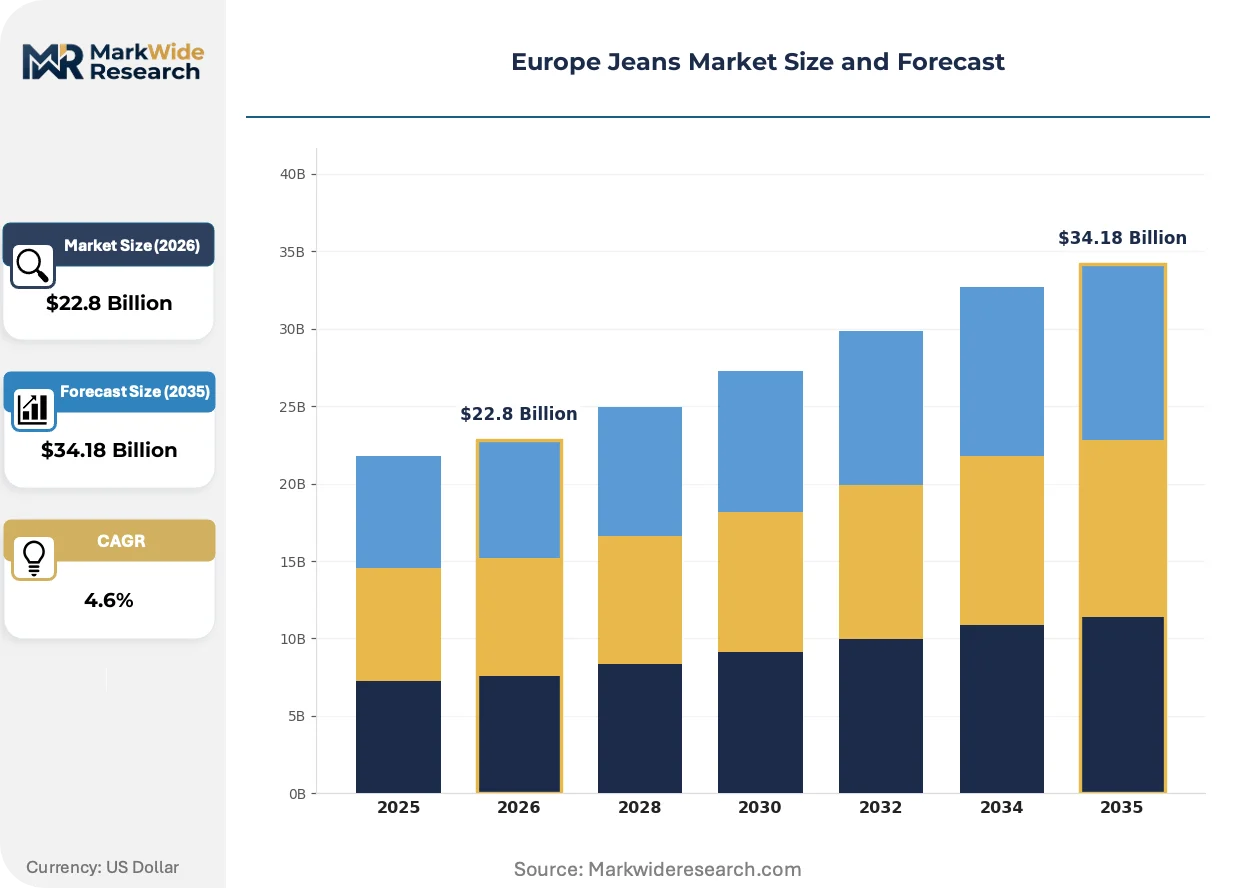
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny, Bootcut, Wide-leg, Boyfriend Material: Cotton, Denim Blend, Stretch Fabric, Selvedge Customer Type: Men, Women, Children, Unisex Price Tier: Luxury, Mid-range, Budget, Discount |
| Companies Covered | Gap Inc, VF Corporation, Levi Strauss & Co, Carhartt WIP, Kontoor Brands Inc, Inditex, Nudie Jeans Co, MUD Jeans, H&M Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Jeans Market Shifts & Advancements
Digital design-to-sample workflows, regulatory chemistry mandates, and circular business model experimentation are compressing traditional seasonal production calendars and rewiring value capture mechanisms across European denim.
Laser-based surface finishing is virtualizing physical sample development and wash experimentation. German and Italian technical centers are adopting 3D rendering and digital twinning to pre-visualize distressing patterns before physical production. This technology is virtualizing the traditional five-to-seven-round sample approval process, collapsing lead times from weeks to days while eliminating water and chemical waste from iterative prototyping.
REACH annex amendments are systematically restricting chromium-based mordants and synthetic surfactants in Portuguese finishing operations. ECHA's 2024-2025 substance evaluation roadmap is compelling reformulation of enzyme-based bio-stoning and ozone-based bleaching protocols. Premium Italian mills are responding fastest, leveraging existing clean chemistry investments to secure compliance ahead of enforcement windows.
Gender-fluid retail assortments are fragmenting traditional menswear-womenswear buying categories. French and British mid-range retailers are collapsing separate buying functions into unified unisex-adjacent merchandising teams. This shift concentrates fastest in urban flagships where Gen-Z foot traffic now exceeds legacy demographic targeting, forcing inventory planning around styling versatility rather than gender-segregated size curves.
Europe Jeans Market Segmentation
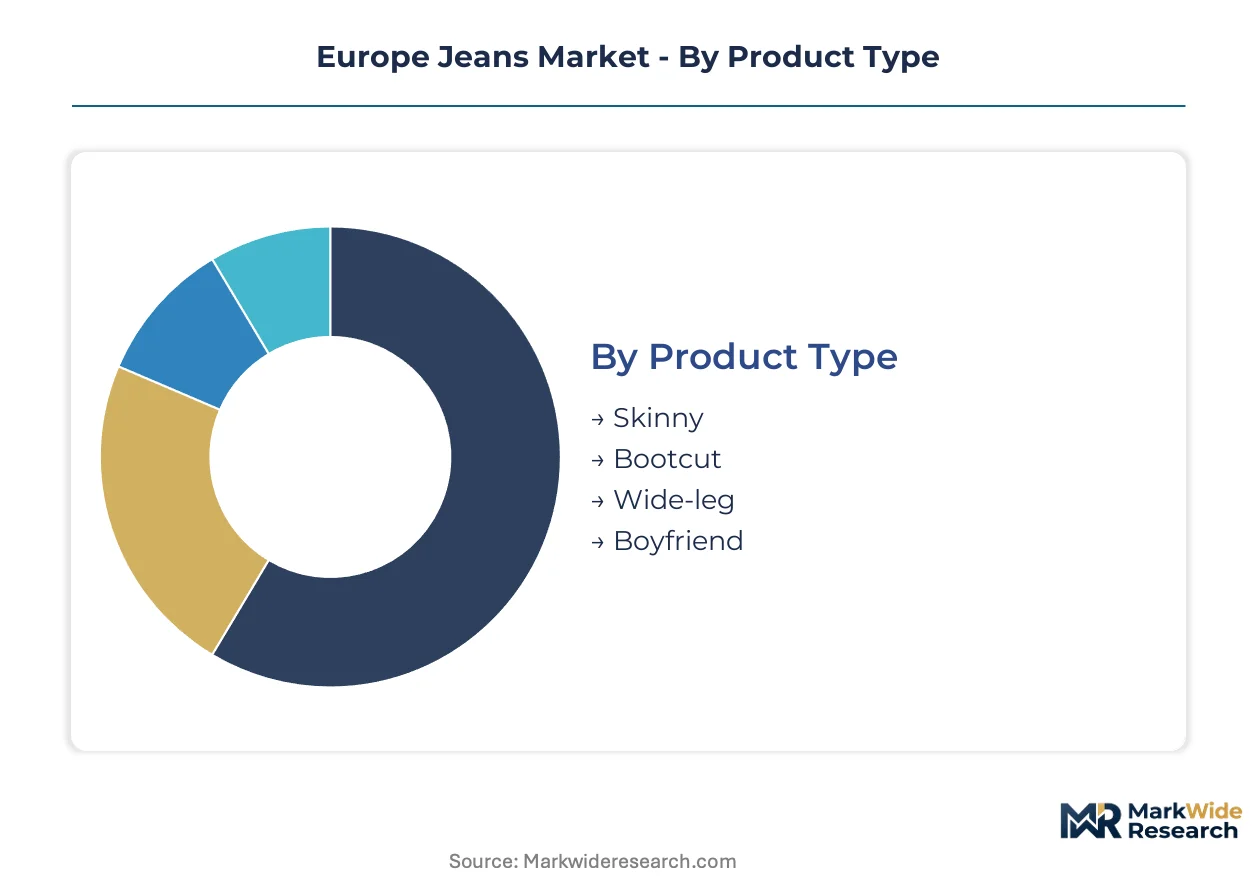
Jeans segmentation across Europe reflects divergent sourcing economics, regulatory compliance burdens, and generational styling preferences. Understanding how product architecture, material composition, and customer targeting interlock reveals where margin capture concentrates and where volume expansion accelerates.
Product Type:
Silhouette architecture determines finishing complexity, fabric consumption rates, and seasonal inventory risk across Mediterranean production clusters.
- Skinny:Form-fitting cuts with high elastane integration dominate unit volume in German and French fast-fashion retail. Tapered leg openings require precision pattern grading that elevates cut-make-trim labor costs relative to looser fits.
- Wide-leg:Relaxed silhouettes with elevated rise measurements are capturing accelerated adoption among Gen-Z consumers in Italian and Spanish urban flagships. Higher fabric yield per garment shifts margin pressure toward raw material procurement rather than assembly labor.
- Bootcut:Flared leg openings calibrated for footwear clearance retain steady demand in UK and Scandinavian occupational workwear channels.
- Boyfriend:Oversized borrowed-from-him styling concentrates in French premium contemporary assortments targeting millennial women.
Skinny cuts command the established base. The steepest expansion runs through Wide-leg silhouettes.
Material:
Fiber composition and construction method dictate compliance pathways under REACH dye restrictions and EU Green Deal recyclability mandates.
- Selvedge:Shuttle-loom woven denim with self-finished edges commands the highest per-unit margins in European specialty retail. Narrow-batch production from Northern Italian and Japanese mills sustains scarcity premiums despite constrained volume scalability.
- Stretch Fabric:Elastane-blended constructions incorporating Lycra or elastomultiester dominate mass-market German and UK volume. Multi-fiber architectures complicate end-of-life recycling under emerging extended producer responsibility frameworks.
- Cotton:Pure cellulosic fiber remains baseline for Turkish and Greek contract growers supplying organic certification tracks.
- Denim Blend:Polyester-cotton hybrids balance durability and cost in Portuguese finishing house output for mid-range Southern European distribution.
Selvedge anchors margin concentration. Stretch Fabric carries the broadest volume footprint.
Customer Type:
Demographic targeting is fragmenting as gender-fluid merchandising collapses traditional buying functions across French and British retail headquarters.
- Unisex:Gender-neutral sizing and styling architectures are expanding shelf space fastest in urban Gen-Z destinations. Unified inventory pools reduce markdown risk compared to gender-segregated size curve planning.
- Women:Female-skewed assortments retain revenue concentration in Italian heritage craftsmanship positioning and French luxury denim houses.
- Men:Masculine-coded workwear and raw denim traditions persist in German and Scandinavian specialty retail.
- Children:Growth-calibrated sizing with reinforced stress points serves Southern European family-centric retail formats.
Women's segmentation holds the established revenue base. Unisex positioning is climbing the fastest across new store openings.
Price Tier:
Cost stratification maps directly to supply chain transparency requirements, artisanal labor inputs, and circular service attach rates.
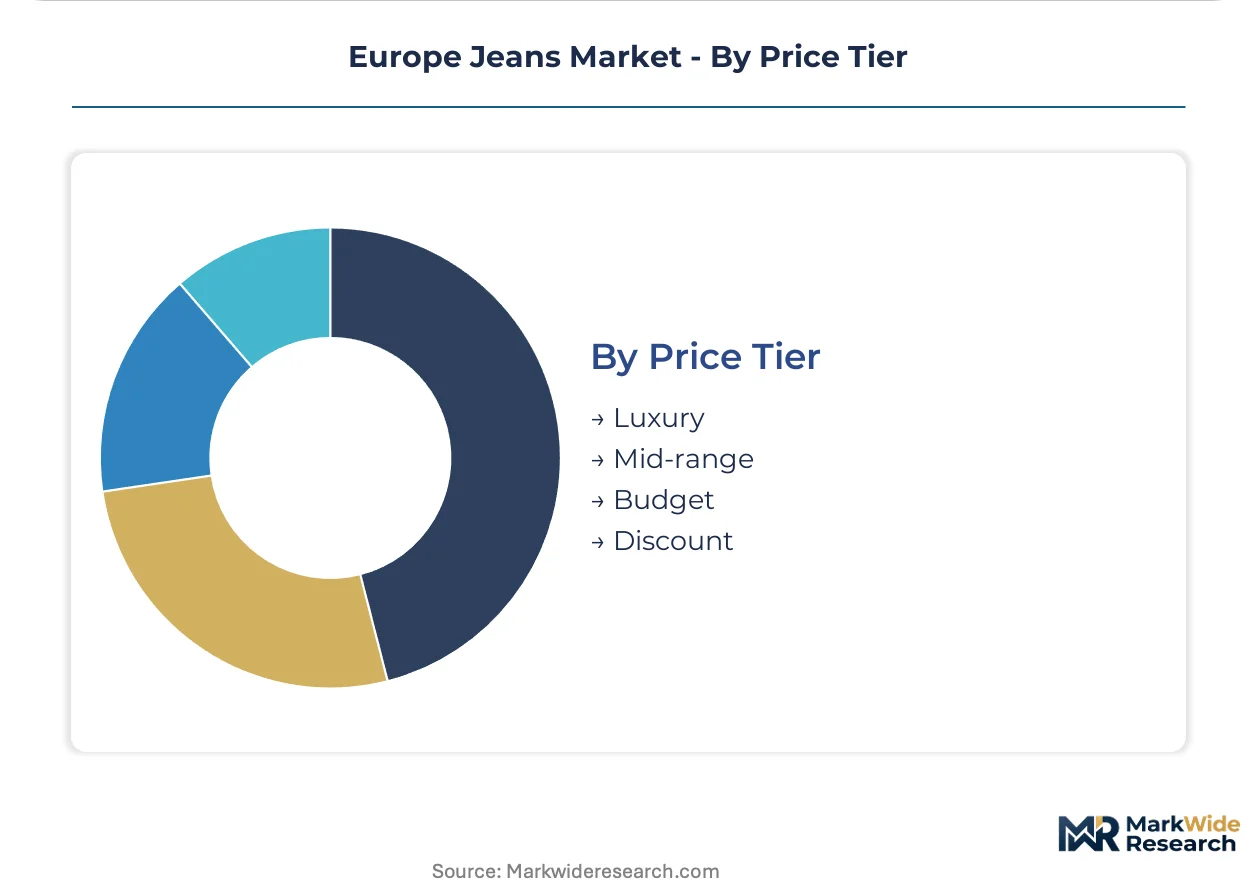
- Luxury:Hand-finished distressing, Japanese or Italian mill provenance, and repair service bundling define positioning in Paris and Milan flagships. Price architecture absorbs elevated compliance costs for small-batch REACH-compliant chemistry.
- Mid-range:Vertically controlled design-to-retail pipelines with rapid inventory turnover dominate Spanish and German mass-market leadership. This tier concentrates investment in laser finishing and digital sample virtualization.
- Budget:Turkish cut-make-trim dependency with minimized finishing stages supplies price-sensitive Southern European hypermarket channels.
- Discount:Off-price residual inventory and unauthorized secondary market flows capture marginal demand in Eastern European border trade zones.
Mid-range pricing controls volume leadership. Luxury tier is gaining share fastest on circular service attachment and provenance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity divides European denim demand sharply. German and Scandinavian buyers absorb premium provenance costs, while Southern European markets prioritize volume accessibility through Turkish sourcing corridors.
Germany
Millennial and Gen-Z consumers in Berlin and Hamburg drive heritage selvedge adoption at price points 40-60% above mass-market baselines. The country's national consumer protection authority enforces strict textile labeling under the Textile Labelling Act, compelling transparent fiber composition disclosure. Bavarian technical centers in Munich anchor laser-finishing R&D partnerships with Italian mill suppliers.
France
Parisian luxury flagships and Lyon-based heritage houses sustain artisanal shuttle-loom premiums through repair-service bundling. ANSM and DGCCRF coordinate enforcement of REACH-compliant chemistry in finishing operations. The Auvergne-Rhône-Alpes cluster concentrates specialized indigo-dyeing knowledge transferred from 19th-century textile traditions.
Italy
Veneto and Lombardy mills command narrow-batch scarcity premiums for Japanese-import shuttle looms operated by aging specialized labor pools. The Ministry of Economic Development administers Made in Italy certification protocols that block geographic mislabeling. Biella's wool-denim hybrid innovation centers are pivoting toward EU Green Deal-compliant waterless dyeing installations.
United Kingdom
London's gender-fluid retail flagships and Manchester's vintage authentication infrastructure capture circular value streams from Gen-Z resale activity. The Competition and Markets Authority monitors extended producer responsibility compliance ahead of 2025 textile collection mandates. Birmingham's manufacturing heritage is reviving through small-batch selvedge workshops serving Japanese export contracts.
Netherlands
Amsterdam and Rotterdam consumers demonstrate viable unit economics for subscription-based denim leasing models that decouple revenue from virgin production. The Netherlands Enterprise Agency subsidizes circular business model pilot programs under EU Green Deal innovation funding. The Randstad logistics corridor enables rapid reverse-logistics infrastructure for material-retention services.
Europe Jeans Market Competitive Landscape
Heritage conglomerates and circular-native challengers split the market into competing value-capture logics. Consolidation pressure concentrates among five to seven vertically integrated groups controlling premium Italian mill access and rapid-turnover Spanish retail pipelines. Three archetypes dominate: legacy American workwear houses with authorized vintage channels, Scandinavian sustainability-native operators with material-retention ownership, and fast-fashion conglomerates with design-to-retail compression. Competitive moves center on circular service attachment rates and backward integration into Portuguese finishing capacity.
Within the heritage conglomerate tier, Levi Strauss & Co and VF Corporation exemplify repair-infrastructure and vintage-authentication strategies that extend garment lifecycle revenue. Among circular-native specialists, MUD Jeans occupies a position representing subscription-leasing unit economics proven in Dutch and Scandinavian markets. At the rapid-turnover end, Inditex anchors scale-driven design-to-retail compression with laser-finishing virtualization that collapses sample lead times.
| Leading Market Players |
|---|
| Gap Inc |
| VF Corporation |
| Levi Strauss & Co |
| Carhartt WIP |
| Kontoor Brands Inc |
| Inditex |
| Nudie Jeans Co |
| MUD Jeans |
| H&M Group |
| Others |
Supply & Pricing Matrix
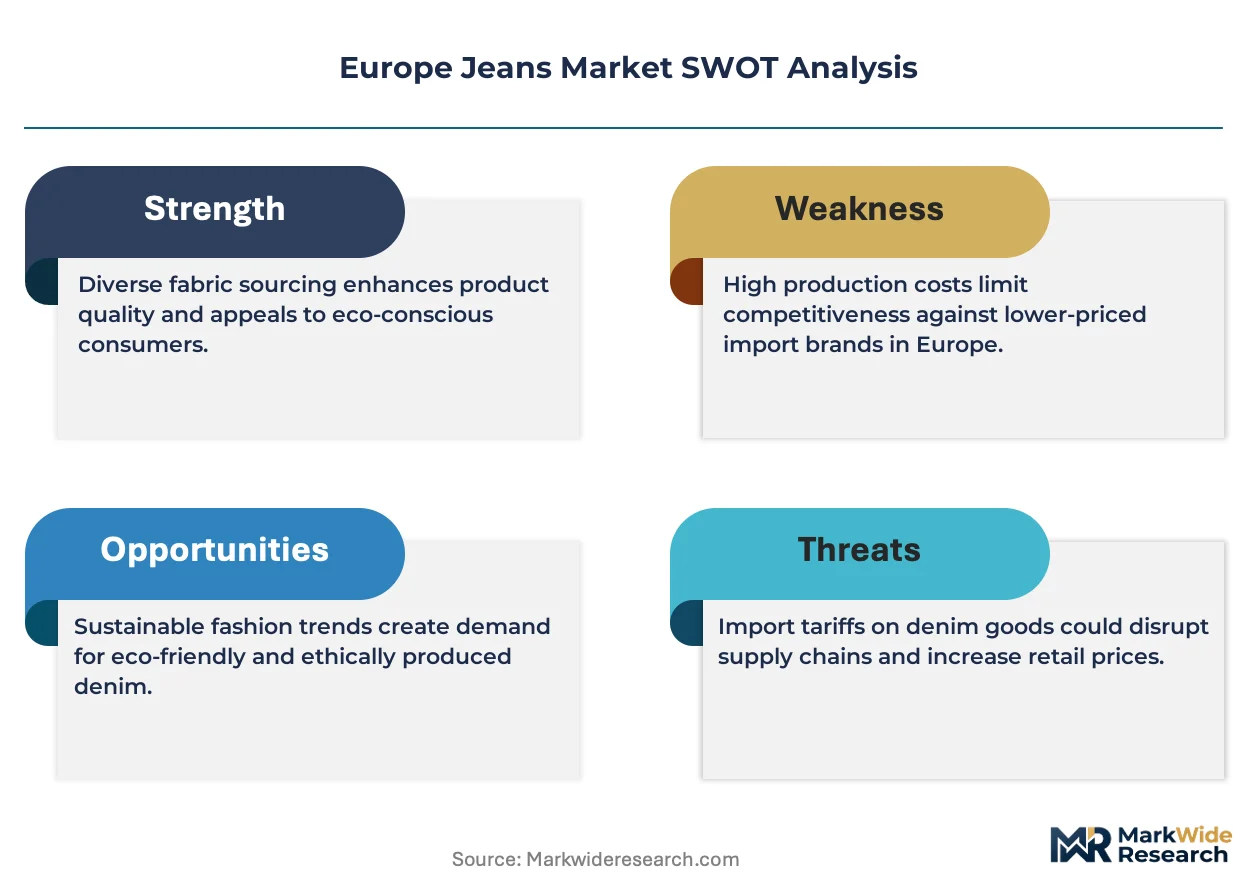
Turkish lira volatility and single-source dependency in cut-make-trim operations compress margin buffers across mid-range pricing tiers while forcing brands toward Portuguese and Greek alternative sourcing corridors. REACH compliance costs for waterless dyeing installations widen spreads between artisanal heritage positioning and mass-market discount channels.
Pricing Analysis
Aftermarket repair and resale revenue streams now drive lifetime value capture for heritage-positioned brands. Three-tier pricing structure across premium selvedge, mid-range stretch fabric, and economy cotton tiers separates buyers by provenance transparency and circular service attachment. Pricing pressure stems from biological indigo cost premiums constraining rapid decarbonization of dye chemistry. Budget-tier buyers in Southern European hypermarkets exhibit highest price sensitivity; luxury purchasers in Paris and Milan flagships absorb elevated compliance costs with minimal volume elasticity.
Supply Chain Analysis
Organic cotton feedstock from Turkish and Greek growers anchors raw material procurement for EU Green Deal compliance tracks. Cut-make-trim concentration in Turkey, Portugal, and Romania creates geographic clustering around Mediterranean finishing infrastructure. Supply chain risk centers on currency volatility amplifying input cost unpredictability for brands without backward integration into Portuguese dye houses. Distribution runs through vertically controlled design-to-retail pipelines for rapid-turnover Spanish conglomerates and heritage-brand authorized vintage channels for circular value retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as subscription-leasing interoperability and digital twin standardization reshape how brands capture value beyond unit sales. The ecosystem shift toward material-retention services decouples revenue from virgin production cycles.
For Market Incumbents: Insulate selvedge margin pools by capturing aging Northern Italian shuttle-loom operator capacity through apprenticeship pipeline investments and exclusive mill contracts. Defend against circular-native challengers by accelerating laser-finishing virtualization to collapse sample lead times and reduce water-intensive prototyping costs. Prioritize backward integration into Portuguese finishing houses to secure REACH-compliant chemistry capacity ahead of ECHA enforcement windows.
For New Entrants and Emerging Players: Establish a beachhead in Dutch and Scandinavian subscription-leasing markets where unit economics for material-retention services have achieved proof-of-concept. Target gender-fluid unisex-adjacent styling as the fastest-expanding customer type across French and British urban flagships. Deploy direct-to-consumer digital fitting technology to bypass incumbent retail gatekeeper relationships and capture Gen-Z preference data.
For Investors and Strategic Acquirers: Circular-native specialists with proven subscription-leasing infrastructure represent the most defensible acquisition archetype for long-term viability across the five-to-ten year horizon. Brands with captive organic cotton sourcing contracts and waterless dyeing installations command premium positioning as EU Green Deal mandates harden. Watch ECHA substance evaluation roadmap expansions as the critical inflection signal for chemistry reformulation cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Leasing Model Expansion | MUD Jeans demonstrates viable unit economics for material-retention revenue decoupled from virgin production. |
| Laser-Finishing Virtualization | German technical centers collapse sample lead times from weeks to days while eliminating water waste from iterative prototyping. |
| Portuguese Finishing House Acquisition | Backward integration secures REACH-compliant chemistry capacity ahead of ECHA enforcement windows. |
| Authorized Vintage Channel Buildout | Levi Strauss captures circular value streams previously lost to uncontrolled secondary market resale. |
| Shuttle-Loom Operator Apprenticeship Pipeline | Exclusive mill contracts in Northern Italy defend artisanal selvedge scarcity premiums against volume competitors. |
Research Methodology
A standing panel of denim brand supply chain directors, Portuguese finishing house technical managers, Italian mill weaving supervisors, and French luxury retail buyers provided ongoing calibration across the research cycle. Primary interview data combined with secondary validation from customs trade records, EU ECHA substance evaluation filings, and organic cotton certification databases. Bottom-up unit economics modeling for subscription-leasing services triangulated against top-down market sizing from retail audit data.
Scenario-bracketing around REACH compliance cost trajectories and biological indigo scale economics framed projection boundaries across the analysis window. Segmentation dimensions modeled include silhouette architecture, fiber composition, customer targeting, and price tier positioning. CAGRs derived from historical volume trajectories adjusted for generational preference shifts and regulatory mandate timelines. Forecast inputs incorporated EU Green Deal textile strategy implementation pace and ECHA restricted substance list expansion schedules.
Stress conditions across Turkish currency volatility, organic cotton yield variability, and shuttle-loom operator retirement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and circular business model adoption curves. Cross-checking against Nielsen retail audit data and customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Body Shaper Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Thimbles Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Sports Bras Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Apparel and Leather Products Market
Apparel & Footwear
Women's Blazer Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Global Luxury Underwear Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Erotic Lingerie Market