
 Chlorine Disinfectant Market | 2026-2036
Chlorine Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorine Disinfectant Market Analysis
The EU Drinking Water Directive revision is consolidating demand for higher-purity chlorine disinfectants across European municipal networks. Ecolab leverages its integrated water treatment platform to sustain service contracts with large-scale utilities. Olin Corporation anchors North American chlorine production through its chlor-alkali manufacturing network.
Chlorine disinfectants encompass chlorine-releasing compounds—principally sodium hypochlorite, calcium hypochlorite, and chlorine dioxide—typically formulated at active chlorine concentrations between 5% and 15% for commercial applications, functioning through oxidation of microbial cell walls and enzyme systems. Sodium hypochlorite dominates municipal water treatment due to its liquid form and ease of automated dosing, while chlorine dioxide occupies premium industrial segments where trihalomethane formation must be minimized. Calcium hypochlorite leads swimming pool applications for its granular stability and transport efficiency.
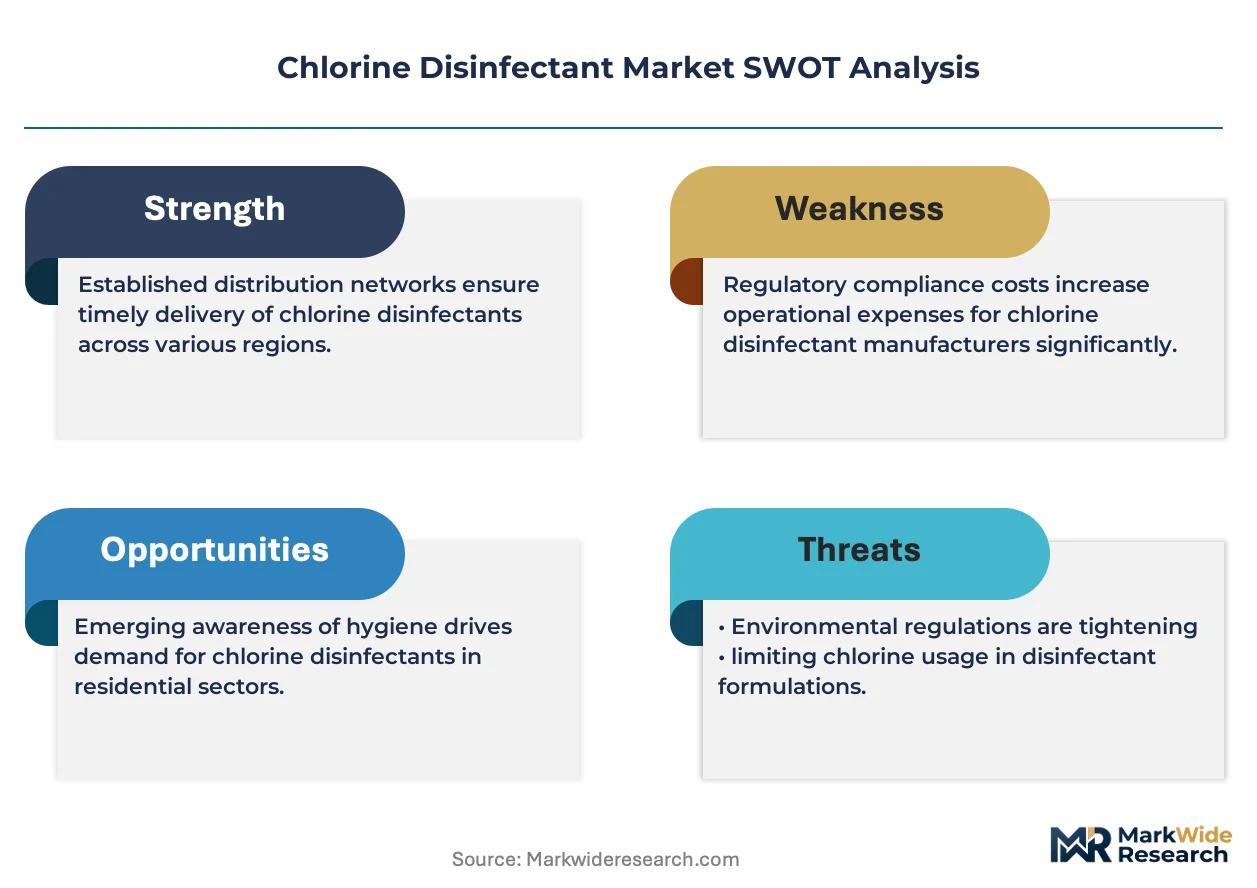
EPA regulations under the Safe Drinking Water Act govern maximum residual disinfectant levels in US public water systems, while the EU Drinking Water Directive sets parallel standards across member states. India's Central Pollution Control Board enforces effluent chlorine limits for industrial discharge. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies and avoid market access delays.
Market Dynamics
Municipal utilities across Brazil, India, and EU member states are simultaneously tightening residual disinfectant standards while expanding automated dosing infrastructure, creating synchronized demand pull for higher-purity chlorine formulations and precision delivery systems.
Growth Catalysts
- EU Drinking Water Directive revision:Tighter residual chlorine limits in municipal networks are forcing upgrades to sodium hypochlorite dosing systems. Utilities in Germany and France are retrofitting legacy infrastructure.
- Urban sanitation infrastructure:India's Central Pollution Control Board effluent mandates are accelerating chlorine dioxide adoption for industrial discharge treatment in Maharashtra and Gujarat.
- Automated dosing technology:Real-time residual monitoring systems are reducing operator dependency and enabling 24/7 compliance in Brazilian water treatment plants.
Market Restraints
- Caustic soda feedstock volatility:Chlor-alkali production costs swing with energy prices, compressing margins for sodium hypochlorite manufacturers in energy-importing regions.
- Trihalomethane formation constraints:Organic-rich source waters limit chlorine dose rates, forcing utilities toward chlorine dioxide or combined disinfection approaches.
- Transportation hazard classification:Calcium hypochlorite granular shipments face stringent ADR and DOT regulations, raising logistics costs for pool chemical distributors.
Strategic Opportunities
- Secondary disinfection in distribution networks:India's smart city initiatives are funding rechlorination stations to maintain residual levels across aging pipe infrastructure in Delhi and Bangalore.
- On-site chlorine dioxide generation:Precursor chemical systems eliminate transport risks and are penetrating food processing and pharmaceutical water loops.
- Electrochlorination units:Seawater-fed systems are displacing bulk hypochlorite deliveries at coastal desalination and power plant cooling water facilities.
Industry Challenges
- Analyzer calibration expertise:Automated residual monitoring requires skilled technicians scarce in smaller municipal utilities, causing compliance gaps.
- Legacy infrastructure compatibility:Retrofitting Victorian-era water treatment works with modern dosing skids demands custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorine Disinfectant Market |
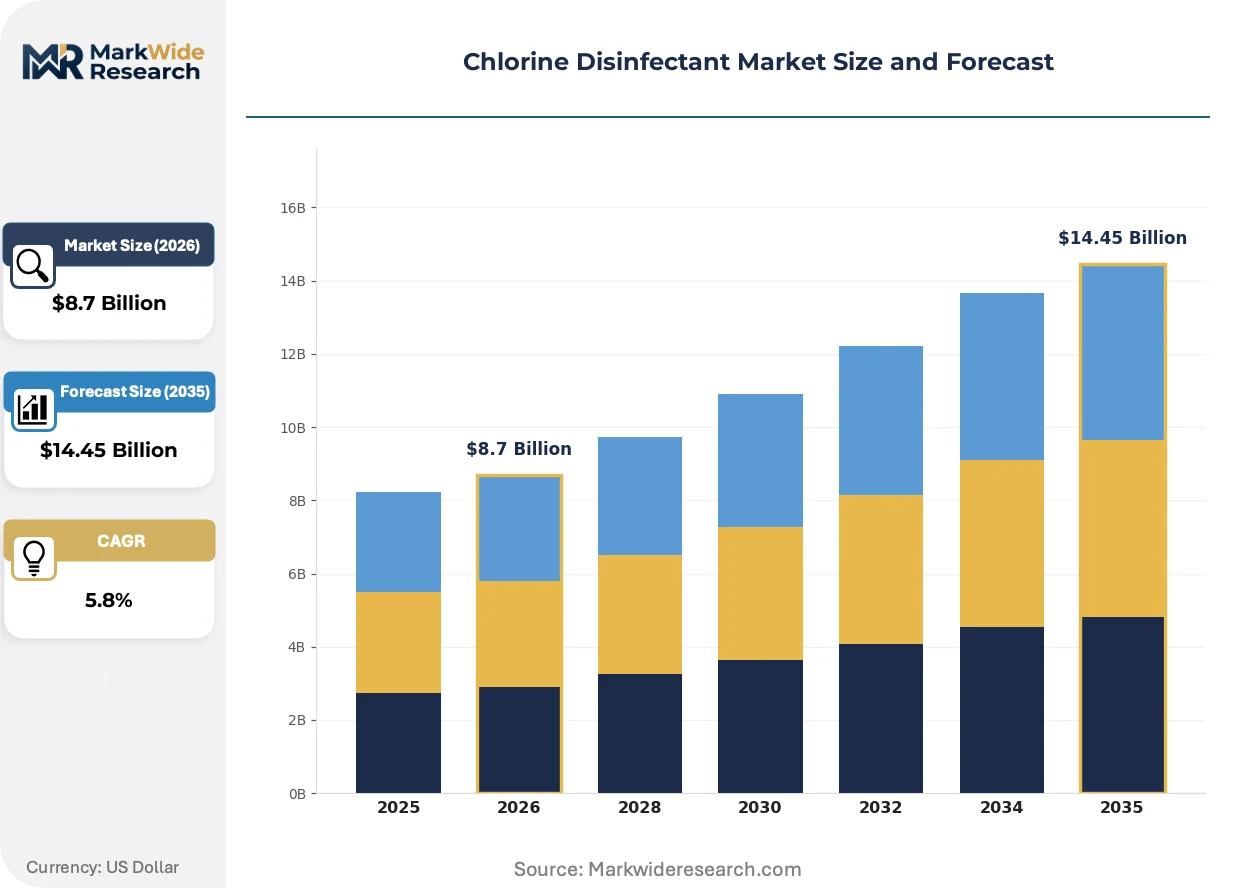
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chlorine, Sodium Hypochlorite, Calcium Hypochlorite, Chlorine Dioxide Application: Water Treatment, Swimming Pools, Agriculture, Food Processing End User: Households, Healthcare Facilities, Industrial, Municipalities Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesale |
| Companies Covered | Ecolab, The Clorox Company, Procter & Gamble, Reckitt Benckiser, 3M Company, BASF SE, Olin Corporation, Solvay, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorine Disinfectant Market Emerging Trajectories
Digital control systems and predictive maintenance platforms are displacing manual residual testing and scheduled maintenance cycles across municipal and industrial water treatment operations, compressing response times to contamination events.
Membrane electrolysis cell technology is automating on-site sodium hypochlorite production at remote treatment facilities. Mining operations in Western Australia and oilfield service camps in Alberta are deploying containerized units to eliminate bulk chemical trucking. The technology is automating supply security for locations beyond reliable distributor reach.
EPA's forthcoming Lead and Copper Rule revisions will mandate optimized corrosion control through pH and alkalinity adjustment alongside disinfection. Water systems in Michigan and Illinois are piloting integrated dosing protocols. Small community systems lacking technical capacity face the steepest compliance burden and are consolidating into regional authorities.
Performance-based service contracts are displacing chemical supply agreements in European municipal procurement. Veolia and Suez are bundling residual guarantee clauses with equipment leases in French and Belgian concessions. Dutch water boards pioneered this structure and are exporting contract templates to Scandinavian utilities seeking operational risk transfer.
Chlorine Disinfectant Market Segmentation
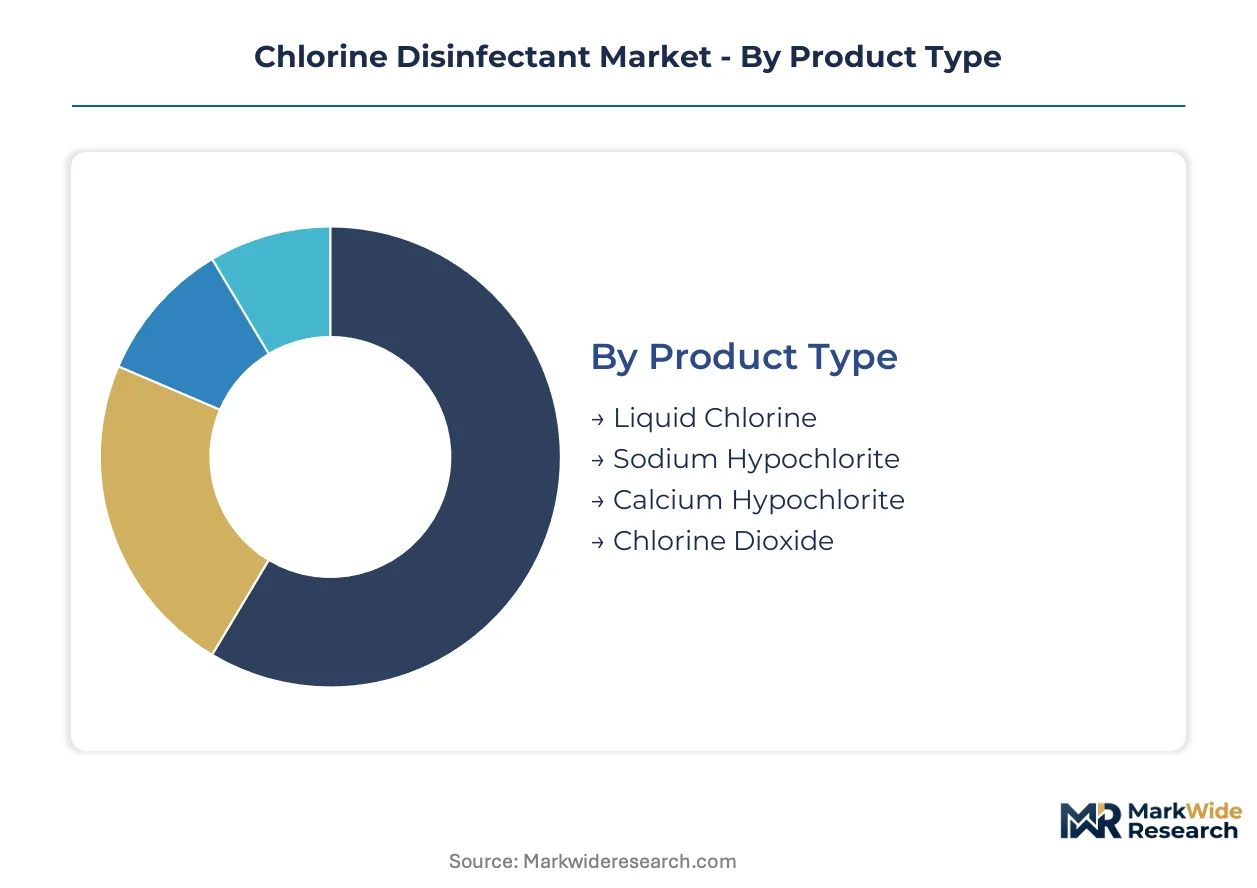
Segmentation in chlorine disinfectants reveals how formulation chemistry, delivery logistics, and regulatory compliance intersect to determine procurement patterns across municipal, industrial, and consumer channels.
Product Type:
Buyers select formulations based on stability requirements, dosing infrastructure, and trihalomethane risk tolerance.
- Sodium Hypochlorite:Aqueous solution containing 5-15% active chlorine, delivered in bulk tankers or IBCs for automated dosing systems. Municipal utilities in Germany and France favor this form for retrofitting legacy treatment works under EU Drinking Water Directive residual limits.
- Chlorine Dioxide:Generated on-site from sodium chlorite and acid precursors, minimizing transport hazards and eliminating trihalomethane formation in organic-rich source waters. Industrial facilities in Maharashtra adopt this technology for effluent compliance with India's Central Pollution Control Board discharge mandates.
- Liquid Chlorine:Elemental chlorine gas liquefied under pressure, deployed at large-scale water treatment plants with specialized containment infrastructure.
- Calcium Hypochlorite:Granular solid with 65-70% available chlorine, packaged in drums for swimming pool maintenance and emergency disinfection where liquid stability is problematic.
Volume sits with sodium hypochlorite; growth tilts toward chlorine dioxide.
Application:
End-use contexts dictate concentration specifications, contact time requirements, and residual monitoring protocols.
- Water Treatment:Municipal drinking water and wastewater disinfection requiring continuous residual maintenance through distribution networks. Brazil's expanding urban utilities drive automated dosing system deployments.
- Swimming Pools:Recreational water maintenance demanding rapid-acting oxidation with minimal eye and skin irritation. Calcium hypochlorite granules dominate this segment for transport efficiency and shelf stability.
- Agriculture:Irrigation system biofilm control and post-harvest wash water sanitation in fresh produce operations.
- Food Processing:Equipment and surface disinfection requiring NSF-certified formulations with rapid degradation to prevent taint.
Water treatment commands the largest volume footprint; food processing exhibits the steepest expansion trajectory.
End User:
Procurement sophistication varies from bulk tender contracts to retail shelf purchases.
- Municipalities:City and regional water authorities operating multi-plant networks with 24/7 compliance obligations. Dutch water boards pioneered performance-based service contracts now migrating to Belgian and Scandinavian utilities.
- Industrial:Manufacturing facilities, power plants, and mining operations with process water and cooling tower requirements. Western Australian mining camps deploy containerized electrochlorination units to eliminate chemical trucking.
- Healthcare Facilities:Hospitals and clinics requiring sporicidal efficacy against healthcare-associated pathogens.
- Households:Consumer bleach purchases for domestic sanitation, concentrated in emerging market urbanization corridors.
Municipalities anchor procurement volume; industrial users are gaining share fastest through on-site generation adoption.
Distribution Channel:
Channel selection reflects order scale, technical support needs, and geographic remoteness.
- Distributors:Regional chemical distributors maintaining local inventory and technical service capabilities for mid-sized industrial accounts.
- Direct Sales:Manufacturer-to-utility contracts for large municipal tenders with integrated equipment leasing and residual guarantee clauses.
- Wholesale:Volume aggregation for pool chemical retailers and agricultural supply cooperatives.
- Online Retail:E-commerce platforms serving household consumers and small commercial accounts with packaged product fulfillment.
Direct sales capture the largest contract value; distributor networks are expanding most quickly into secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors chlorine disinfectant procurement volume through Brazil's municipal water utility consolidation. The city's Sabesp network drives automated sodium hypochlorite dosing retrofits across southeastern treatment plants.
United States
EPA Lead and Copper Rule revisions are forcing corrosion control upgrades alongside disinfection optimization. Michigan and Illinois water systems pilot integrated pH-alkalinity-chlorine dosing protocols. Chicago's Department of Water Management deploys real-time residual monitoring across its Lake Michigan intake network.
Germany
EU Drinking Water Directive residual limits are accelerating legacy infrastructure modernization. German utilities favor bulk sodium hypochlorite deliveries for automated retrofit compatibility. Rhine-Ruhr metropolitan utilities bundle performance guarantees with equipment leases under Dutch-imported contract templates.
India
Central Pollution Control Board effluent mandates are driving chlorine dioxide adoption in industrial discharge treatment. Maharashtra and Gujarat chemical clusters deploy precursor-based generation systems. Delhi's smart city rechlorination stations maintain residuals across aging distribution pipes.
Brazil
Sabesp and regional utilities expand sodium hypochlorite dosing capacity under ANVISA-aligned municipal standards. Automated residual monitoring reduces operator dependency in southeastern treatment plants. Rio de Janeiro's water utility network retrofits legacy chlorination infrastructure.
France
Veolia and Suez bundle residual guarantee clauses with equipment leases in municipal concessions. French water boards export performance-based contract structures to Belgian and Scandinavian utilities. Paris metropolitan utilities tighten residual standards under EU directive harmonization.
Chlorine Disinfectant Market Vendor Landscape
The competitive structure tilts toward integrated service providers with captive chemical supply. Chlor-alkali producers anchor supply security for downstream formulations. Three archetypes dominate: diversified chemical conglomerates with water treatment divisions, specialized disinfectant formulators with regional distribution networks, and integrated facility service providers bundling chemicals with equipment. Capacity expansion and performance-based contracting represent the dominant competitive vectors.
Within the integrated service tier, Ecolab and Olin Corporation exemplify archetype positioning through their respective water treatment platforms and chlor-alkali manufacturing networks. BASF SE represents the diversified chemical conglomerate model with European formulation capabilities. These three companies anchor the competitive landscape through distinct strategic positioning rather than overlapping market approaches.
| Leading Market Players |
|---|
| Ecolab |
| The Clorox Company |
| Procter & Gamble |
| Reckitt Benckiser |
| 3M Company |
| BASF SE |
| Olin Corporation |
| Solvay |
| Kemira |
| Others |
Supply Flow & Price Mechanics
Municipal water utilities in Germany, France, and Brazil concentrate procurement through multi-year performance contracts, anchoring value-based pricing models that bundle chemical supply with residual guarantee clauses and equipment leasing. This buyer concentration shifts pricing power toward integrated service providers capable of absorbing operational risk.
Pricing Analysis
Value-based pricing anchored to residual compliance outcomes dominates municipal tenders in the EU and Brazil, with Veolia and Suez bundling uptime guarantees into concession agreements. Price differentiation separates NSF-certified food-grade formulations from standard municipal grades, while volume scale drives tiered structures for bulk sodium hypochlorite deliveries. Pricing pressure stems from caustic soda feedstock volatility in energy-importing regions, compressing margins for non-integrated formulators. Small municipal utilities exhibit highest price sensitivity due to technical capacity constraints, while industrial users accept premium chlorine dioxide systems for effluent compliance.
Supply Chain Analysis
Direct-to-utility channels handle large municipal tenders with integrated equipment leases, while regional distributors serve mid-sized industrial accounts with localized inventory. Geographic supply concentrates in the United States, Germany, and China through chlor-alkali manufacturing networks. Raw material dependencies draw from salt, electricity, and caustic soda inputs. Supply chain risk centers on single-source vulnerability for sodium chlorite precursors in chlorine dioxide generation systems. Distribution runs through bulk tanker logistics for liquid formulations and ADR-regulated shipments for granular calcium hypochlorite.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where chlor-alkali production control determines margin sustainability and supply security for downstream disinfectant formulations.
For Market Incumbents: Extend performance-based service contracts into secondary cities and industrial zones where technical capacity gaps create compliance vulnerabilities. Deepen captive chlor-alkali supply to offset caustic soda price volatility threatening non-integrated competitors. Acquire regional distributors in Brazil and India to secure last-mile delivery infrastructure against emerging local formulators. For New Entrants and Emerging Players: Capture on-site chlorine dioxide generation opportunities in India's Maharashtra and Gujarat chemical clusters where Central Pollution Control Board effluent mandates outpace incumbent response capacity. Target containerized electrochlorination deployments in Western Australian mining and Alberta oilfield camps beyond reliable bulk chemical distribution. Partner with smart city infrastructure funds for rechlorination station build-operate contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap chlor-alkali producers with stranded capacity in European energy markets facing margin compression. Long-term viability hinges on backward integration into salt and power inputs rather than formulation-only positioning. Monitor EU Drinking Water Directive enforcement intensity and ANVISA alignment progress in Brazil as inflection indicators for contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Production | Captive caustic soda supply insulates Olin Corporation and BASF SE from energy price volatility. |
| On-Site Generation Technology Deployment | Precursor-based chlorine dioxide systems eliminate transport hazards for Maharashtra industrial facilities. |
| Performance-Based Service Contract Expansion | Dutch water board contract templates migrate residual risk to Veolia and Suez in Belgian concessions. |
| Containerized Electrochlorination Rollout | Seawater-fed units displace bulk deliveries at Western Australian mining camps beyond distributor reach. |
| Smart City Rechlorination Infrastructure | Delhi and Bangalore stations maintain residuals across aging distribution pipes under municipal funding. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with municipal utility procurement officers, chlor-alkali plant managers, water treatment equipment engineers, and regional chemical distributors validated demand patterns and pricing structures. Secondary sources included EPA Safe Drinking Water Act documentation, EU Drinking Water Directive revisions, India Central Pollution Control Board effluent standards, Brazil ANVISA alignment protocols, SEC 10-K filings from disclosed chemical producers, and Cefic chlor-alkali production statistics. Bottom-up segmentation modeling and top-down macroeconomic reconciliation ensured cross-verification of volume and value estimates.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework. Modeled segments encompassed sodium hypochlorite, chlorine dioxide, liquid chlorine, and calcium hypochlorite formulations across municipal, industrial, healthcare, and household end-use contexts. CAGRs were derived from trend extrapolation of regulatory-driven infrastructure investment cycles and chlor-alkali capacity expansion pipelines. Industry-specific forecast inputs incorporated EU Drinking Water Directive implementation timelines and India's smart city rechlorination funding allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to energy price trajectories affecting chlor-alkali economics and regulatory enforcement variance across jurisdictions. Forecasts reflect documented assumptions regarding municipal procurement consolidation rates and on-site generation technology adoption curves. Practitioners should monitor caustic soda price indices, EU residual limit enforcement actions, and Brazilian utility automation tender awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Warehouse Fumigants Market
Disinfectants and Preservatives
Salon Disinfectants Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Continuously Sterilized Product Market