
 Infusion Chair Market | 2026-2036
Infusion Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Infusion Chair Market Foresight
Polyurethane foam is expanding its share in infusion chair cushioning, displacing traditional latex cores that degrade under repeated disinfectant exposure. Hill-Rom leverages its clinical furniture R&D infrastructure to develop pressure-mapping surfaces for extended chemotherapy sessions. Stryker anchors its position through hospital bed and chair integration, selling bundled patient-handling systems that reduce procurement complexity for integrated delivery networks. Zhangjiagang Bestran Technology Co., Ltd competes on manufacturing scale, exporting cost-optimized electric recliners to mid-tier outpatient clinics across Southeast Asia and Latin America.
An infusion chair is a purpose-built patient seating device designed for extended stationary therapy, typically featuring adjustable recline angles from 90 to 180 degrees, weight capacities exceeding 350 pounds, and surfaces engineered for chemical resistance and cleanability. These chairs serve chemotherapy, dialysis, blood transfusion, and biologic drug administration where patients remain seated for two to eight hours. Recliner chairs command the largest revenue share due to their dominance in oncology infusion suites where Trendelenburg positioning and full-flat recline reduce vasovagal events. Adjustable chairs represent the fastest-growing form segment, driven by ambulatory surgery centers seeking multi-procedure flexibility from a single capital purchase. Vinyl upholstery leads material selection for its balance of disinfectant tolerance and cost, though premium leather variants penetrate concierge oncology and executive health programs where aesthetic differentiation supports per-visit pricing.
FDA 21 CFR Part 820 quality system requirements and ISO 13485 medical device standards govern infusion chair design validation, biocompatibility testing, and post-market surveillance obligations for manufacturers selling into US healthcare facilities. The EPA's antimicrobial coating registration protocols add compliance layers for chairs treated with silver-ion or copper-alloy surfaces marketed as infection-prevention features. Stakeholders must monitor how CMS outpatient prospective payment system reimbursement adjustments affect capital equipment replacement cycles at hospital-affiliated infusion centers.
Market Dynamics
The infusion chair market is experiencing structural compression as outpatient oncology volumes surge while FDA sterilization-grade material mandates raise manufacturing costs simultaneously. This tension between demand expansion and compliance burden is forcing capital equipment decisions toward multi-procedure flexibility.
Growth Catalysts
- Outpatient clinic expansion:Hospital-affiliated infusion centers in the United States are replacing aging chair stock with pressure-relief models to handle rising chemotherapy and biologic administration volumes.
- ISO 13485 adoption:Medical device quality system standardization is accelerating design validation protocols across manufacturing facilities serving North American and European healthcare systems.
- Powered recline technology:Electric positioning systems are penetrating ambulatory surgery centers seeking Trendelenburg capability and full-flat recline from single capital purchases.
Market Restraints
- Steel and aluminum input volatility:Frame material cost fluctuations compress margin structures for manufacturers maintaining price competitiveness in mid-tier outpatient segments.
- Supply concentration in Southeast Asian component sourcing:Dependence on concentrated electronics and actuator suppliers creates vulnerability to logistics disruptions affecting electric recliner production timelines.
- Latex core degradation limitation:Traditional cushioning materials face accelerated replacement cycles under repeated disinfectant exposure, raising total cost of ownership for budget-conscious buyers.
Strategic Opportunities
- Latin America outpatient infrastructure:Mid-tier clinics in Brazil and Mexico present white space for cost-optimized electric recliners with essential positioning features.
- Silver-ion surface integration:EPA-registered antimicrobial coating protocols create premium positioning for chairs marketed as infection-prevention assets in oncology suites.
- Concierge oncology aesthetic differentiation:Premium leather upholstery variants penetrate executive health programs where per-visit pricing models reward capital investment in patient experience.
Industry Challenges
- Biocompatibility testing timelines:FDA 21 CFR Part 820 validation requirements extend product development cycles for new cushioning materials and surface treatments.
- Legacy fleet integration complexity:Replacement chair procurement must coordinate with existing patient-handling systems and facility spatial constraints in renovated infusion suites.
- Specialized technician scarcity:Electric recliner maintenance and repair capabilities concentrate with authorized service networks, limiting rapid response in remote outpatient locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infusion Chair Market |
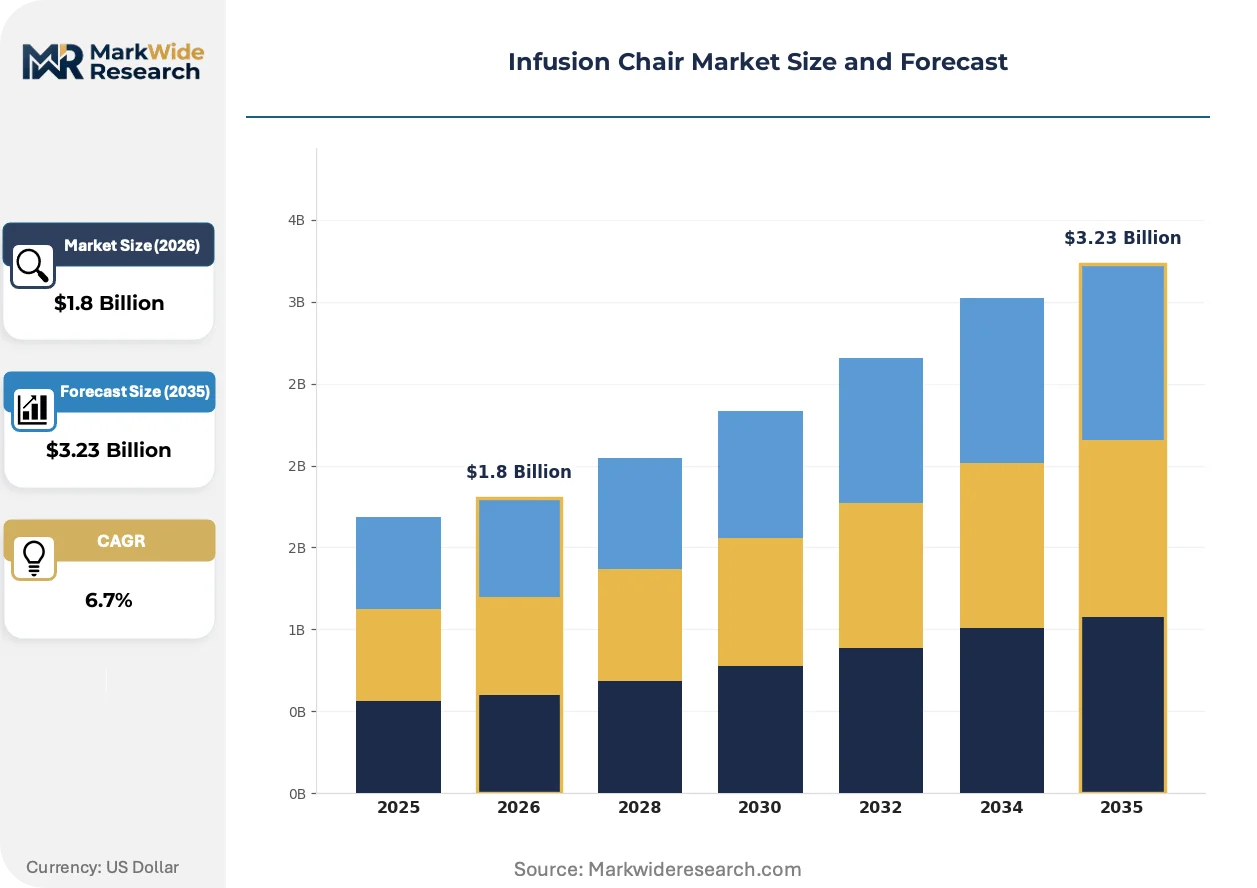
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chair, Recliner Chair, Specialty Chair, Pediatric Chair End User: Hospitals, Outpatient Clinics, Home Care, Rehabilitation Centers Material: Fabric, Vinyl, Leather, Plastic Form: Fixed Chair, Adjustable Chair, Mobile Chair, Foldable Chair |
| Companies Covered | Champion Manufacturing, Hill-Rom, Invacare Corporation, IOA, Steelcase, Zhangjiagang Bestran Technology Co., Ltd, Medline, Stryker, Winco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infusion Chair Market Shifts & Advancements
Material substitution and regulatory alignment are actively compressing traditional design paradigms while procurement models favor flexible, multi-procedure assets over single-purpose equipment. These forces are reshaping how manufacturers prioritize R&D investment and channel strategy.
Polyurethane foam is expanding into infusion chair cushioning cores, displacing latex formulations that degrade under repeated exposure to hospital-grade disinfectants. Oncology infusion suites in the United States are adopting these surfaces at accelerated replacement cycles. This material transition is expanding into mid-tier outpatient markets previously constrained by latex's shorter functional lifespan.
EPA antimicrobial coating registration protocols are tightening marketing claims for infection-prevention surfaces, requiring validated test data for silver-ion and copper-alloy treatments. Manufacturers must now maintain separate documentation streams for coated versus standard vinyl upholstery. Hospital outpatient departments are responding by specifying certified surfaces in procurement tenders to reduce liability exposure.
Integrated delivery networks are consolidating capital equipment purchasing through bundled patient-handling system contracts rather than standalone chair procurement. Ambulatory infusion centers face pressure to standardize fleet configurations across multiple sites. This behavioral shift is most visible in United States metropolitan markets where health system consolidation has concentrated buying authority at regional procurement offices.
Infusion Chair Market Segmentation
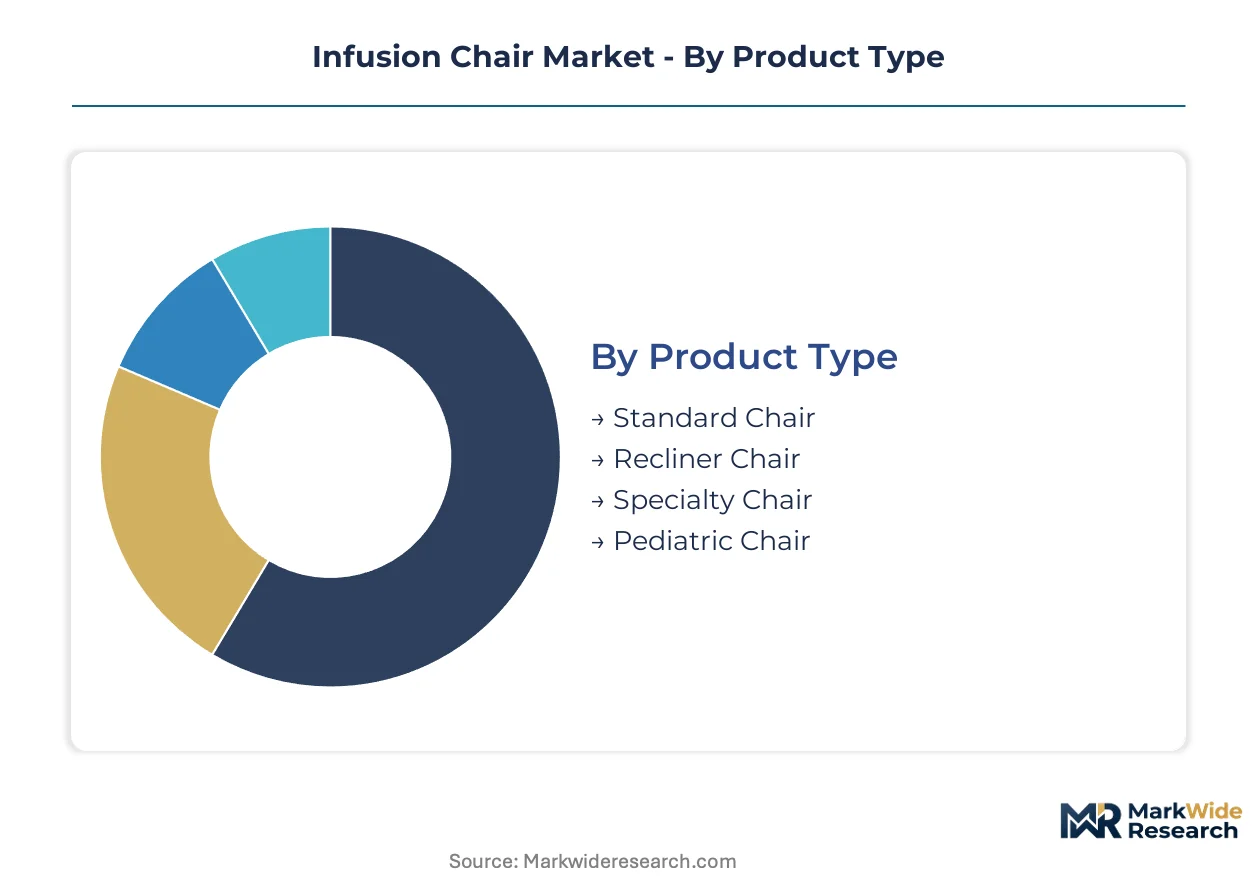
Infusion chair procurement patterns diverge sharply between high-volume oncology infusion suites and specialized pediatric or home-care environments. Material selection and form factor decisions cascade from these use-case distinctions, with disinfectant tolerance and positioning flexibility driving specification priorities across end-user categories.
Product Type:
Revenue concentration favors powered recline systems with extended positioning ranges, while standard configurations retain volume share in budget-constrained procurement environments.
- Recliner Chair:Electric or manual recline mechanisms spanning 90 to 180 degrees support Trendelenburg positioning for vasovagal event management during extended chemotherapy sessions. United States hospital outpatient departments specify these for oncology suites where patient stability during four-to-eight-hour infusions is non-negotiable.
- Standard Chair:Fixed or limited-adjustment seating with steel or aluminum frames and vinyl upholstery serves high-throughput blood transfusion and short-duration antibiotic administration. Mid-tier outpatient clinics in Southeast Asia and Latin America prioritize these for capital efficiency in high-volume, low-margin service lines.
- Specialty Chair:Bariatric-rated frames exceeding 450-pound capacity and pressure-relief surfaces address patient populations with mobility limitations and extended immobility risks.
- Pediatric Chair:Scaled dimensions with safety harness integration and anxiety-reducing design elements serve oncology and immunology departments treating pediatric patients.
Mature deployment sits with Recliner Chair configurations in established oncology infrastructure. Newer deployment is concentrated in Pediatric Chair segments as children's hospital infusion capacity expands.
End User:
Procurement authority is consolidating through integrated delivery networks in metropolitan markets, while independent outpatient clinics retain fragmented purchasing patterns.
- Hospitals:Inpatient oncology units and infusion suites within academic medical centers drive specification for pressure-mapping surfaces and full-flat recline capability. These facilities coordinate replacement cycles with CMS outpatient prospective payment system reimbursement adjustments.
- Outpatient Clinics:Ambulatory infusion centers and hospital-affiliated oncology clinics represent the fastest-expanding demand segment, replacing aging chair stock with powered recline models to handle rising biologic administration volumes.
- Home Care:Portable electric recliners with battery backup and reduced weight specifications serve patients receiving home-based chemotherapy and immunoglobulin therapy.
- Rehabilitation Centers:Dual-purpose seating supporting both infusion and physical therapy positioning serves post-acute care settings with multi-procedure flexibility requirements.
Established infrastructure concentrates in Hospitals. Capacity expansion is accelerating most quickly in Outpatient Clinics.
Material:
Surface selection balances disinfectant tolerance against patient comfort and aesthetic positioning in premium service lines.
- Vinyl:Polyvinyl chloride formulations with welded seams and chemical-resistant topcoats dominate standard procurement for their balance of cleanability and cost. EPA antimicrobial coating registration protocols are tightening specification requirements for treated variants.
- Leather:Premium upholstered surfaces penetrate concierge oncology and executive health programs where per-visit pricing models reward capital investment in differentiated patient experience.
- Fabric:Breathable textile surfaces with moisture-barrier backing serve pediatric and psychiatric settings where thermal comfort and reduced institutional appearance are prioritized.
- Plastic:Injection-molded polypropylene shells with integrated drainage channels serve dialysis and blood collection environments requiring aggressive disinfection protocols.
Volume deployment rests with Vinyl surfaces across standard procurement. Premium positioning is gaining traction fastest in Leather variants.
Form:
Capital efficiency pressures are shifting procurement toward multi-procedure flexibility rather than single-purpose fixed installations.
- Adjustable Chair:Electric actuator systems enabling height, backrest, and leg rest positioning from a single control interface serve ambulatory surgery centers seeking procedure flexibility. These configurations are climbing the fastest as integrated delivery networks standardize fleet specifications across multiple sites.
- Mobile Chair:Locking casters and compact footprints enable repositioning within infusion suites and transport between treatment areas without patient transfer.
- Fixed Chair:Stationary installations with hard-plumbed electrical and data connections serve permanent oncology suite configurations with dedicated patient stations.
- Foldable Chair:Collapsible steel frames with detachable upholstery support temporary infusion capacity expansion and emergency response deployments.
Permanent infrastructure favors Fixed Chair installations. Flexible deployment is expanding most rapidly in Adjustable Chair configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech special economic zones in Malaysia and Puerto Rico are concentrating infusion chair component manufacturing, drawing contract fabricators seeking proximity to United States hospital procurement networks and ASEAN clinic expansion corridors.
United States
Hospital outpatient departments in Texas and Florida are replacing aging chair fleets with powered recline models to accommodate rising biologic infusion volumes. FDA 21 CFR Part 820 quality system requirements are extending design validation timelines for manufacturers seeking to serve academic medical centers. The Research Triangle Park cluster in North Carolina anchors clinical furniture R&D coordination between device manufacturers and oncology health systems.
Germany
University hospital infusion suites in Bavaria and North Rhine-Westphalia are standardizing on pressure-mapping surfaces for extended chemotherapy sessions. EU Medical Device Regulation (MDR) conformity assessment procedures are tightening biocompatibility documentation requirements for cushioning materials and antimicrobial coatings. The Baden-Württemberg medical technology corridor around Tübingen and Stuttgart concentrates precision actuator and sensor component production for electric recliner systems.
China
Provincial hospital oncology departments in Jiangsu and Guangdong provinces are expanding infusion capacity to address rising cancer incidence and biologic drug availability. National Medical Products Administration (NMPA) medical device registration rules are harmonizing with ISO 13485 standards for domestic manufacturers targeting export markets. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou dominates steel frame fabrication and electric actuator assembly for mid-tier clinic segments.
Brazil
Private oncology clinic chains in São Paulo and Minas Gerais are importing cost-optimized electric recliners to expand ambulatory infusion capacity. ANVISA medical device registration pathways are lengthening for imported clinical furniture lacking local biocompatibility testing documentation. The São Paulo metropolitan medical device distribution hub coordinates last-mile logistics for replacement chair procurement across Southeast Latin America.
India
Tertiary care hospital infusion centers in Maharashtra and Karnataka are upgrading from fixed to adjustable chair configurations for multi-procedure flexibility. Central Drugs Standard Control Organization (CDSCO) medical device rules are formalizing quality system requirements for domestic manufacturers previously operating under voluntary standards. The Mumbai-Pune medical device manufacturing corridor is attracting contract fabricators serving both domestic hospital procurement and export markets in Africa and the Middle East.
Infusion Chair Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated delivery network procurement favoring bundled patient-handling system suppliers while independent clinics source through regional distributors. The vendor base concentrates around three strategic archetypes: diversified medical device conglomerates with hospital bed and chair integration capabilities; clinical furniture specialists with dedicated oncology R&D infrastructure; and contract manufacturers competing on scale for mid-tier export markets. Competitive positioning depends on M&A activity consolidating regional service networks and strategic partnerships securing actuator and electronics supply commitments.
Among diversified medical device conglomerates, Hill-Rom and Stryker occupy positions anchoring bundled procurement relationships with integrated delivery networks. Zhangjiagang Bestran Technology Co., Ltd exemplifies the scale-driven contract manufacturing archetype, with its corporate structure indicating Chinese manufacturing concentration targeting cost-optimized electric recliner export segments. Champion Manufacturing represents the clinical furniture specialist archetype, with its naming convention suggesting dedicated patient seating focus rather than diversified medical device breadth.
| Leading Market Players |
|---|
| Champion Manufacturing |
| Hill-Rom |
| Invacare Corporation |
| IOA |
| Steelcase |
| Zhangjiagang Bestran Technology Co., Ltd |
| Medline |
| Stryker |
| Winco |
| Others |
Supply & Pricing Matrix
Captive in-house production of electric actuators and pressure-mapping electronics anchors pricing power for integrated hospital furniture suppliers serving North American academic medical centers. This backward integration insulates premium-tier manufacturers from steel and aluminum input volatility while locking in margin structures that mid-tier contract manufacturers cannot replicate under FDA 21 CFR Part 820 validation requirements.
Pricing Analysis
Volume concentration in standard fixed-frame chairs serving Southeast Asian and Latin American outpatient clinics runs on thinner margin structures than premium powered recline systems specified by United States hospital outpatient departments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified manufacturers with full validation documentation from regional assemblers competing on capital efficiency. Cost compression in mid-tier segments is intensifying because Zhangjiagang Bestran Technology and comparable contract manufacturers exploit scale economies in Yangtze River Delta fabrication clusters. Price-sensitive buyers cluster in independent outpatient clinics across Brazil and Mexico, while least-sensitive procurement originates from integrated delivery networks bundling patient-handling system contracts.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Brazil's ANVISA localization requirements are reshaping sourcing patterns for manufacturers seeking hospital procurement eligibility. Component supply concentrates in China for steel frame fabrication and electric actuator assembly, Malaysia for MedTech special economic zone electronics integration, and Germany for precision sensor production around the Baden-Württemberg corridor. Raw material dependencies span medical-grade polyurethane foam cushioning, antimicrobial-coated vinyl upholstery, and aluminum structural extrusions. Single-source vulnerability concentrates in concentrated Southeast Asian electronics suppliers serving electric recliner motor systems. Distribution runs through regional medical device distributors in São Paulo and Mumbai-Pune corridors coordinating last-mile logistics for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 820 quality system requirements erect a cost-of-compliance barrier that advantages validated incumbents while filtering out undercapitalized entrants lacking biocompatibility testing infrastructure. This regulatory moat intensifies as EPA antimicrobial coating registration protocols add documentation layers for infection-prevention surface claims.
For Market Incumbents: Anchor bundled procurement relationships with integrated delivery networks through patient-handling system integration spanning beds, chairs, and transfer equipment. Defend against Zhangjiagang Bestran Technology scale competition by deepening ISO 13485-certified R&D investment in pressure-mapping surfaces for extended chemotherapy sessions. Prioritize backward integration into electric actuator production to insulate margin structures from Southeast Asian electronics supply volatility. For New Entrants and Emerging Players: Enter via cost-optimized electric recliner segments in Brazil and Mexico where ANVISA registration pathways favor local biocompatibility documentation. White-space concentration sits with mid-tier outpatient clinics in Southeast Asia seeking essential positioning features without premium-tier pricing. Pursue private oncology clinic chains in São Paulo and Minas Gerais through distributor partnerships leveraging São Paulo metropolitan logistics hubs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking clinical furniture vertical integration. Long-term viability favors manufacturers with captive ISO 13485 validation infrastructure and EPA-registered antimicrobial surface portfolios. Watch CMS outpatient prospective payment system reimbursement adjustments as the inflection signal for capital equipment replacement cycle acceleration at hospital-affiliated infusion centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Investment | Validates design protocols for United States academic medical center procurement eligibility. |
| Pressure-Mapping Surface R&D | Hill-Rom leverages clinical furniture infrastructure for extended chemotherapy session differentiation. |
| Backward Integration into Actuator Production | Stryker anchors margin protection against Southeast Asian electronics supply concentration. |
| EPA Antimicrobial Coating Registration | Creates premium positioning for infection-prevention claims in oncology suite tenders. |
| Latin America Distribution Partnership | São Paulo hub coordinates last-mile logistics for Brazilian and Mexican clinic expansion. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, biomedical engineers, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, material, and form segmentation dimensions.
Rate-of-change decomposition separates volume expansion in outpatient clinic segments from value migration toward powered recline and pressure-relief configurations. The analytical framework models infusion chair procurement across recliner, standard, specialty, and pediatric product types; hospitals, outpatient clinics, home care, and rehabilitation center end users; vinyl, leather, fabric, and plastic materials; and adjustable, mobile, fixed, and foldable forms. CAGRs derive from procedure volume projections for chemotherapy, dialysis, and biologic administration cross-referenced with replacement cycle analysis of aging chair fleets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement intensity variations and steel input volatility shocks. Forecasts reflect assumptions regarding outpatient oncology volume trajectories, reimbursement stability, and supply chain logistics normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Medical Bed Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Medical Mattress Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Global Chemotherapy Chairs Market