
 Horse Stable Supplies Market | 2026-2036
Horse Stable Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Stable Supplies Market Foresight
Premium-grade stable equipment is reorganizing competitive dynamics across the horse stable supplies sector. Georg Kieffer Sattlerwarenfabrik GmbH leverages its German craftsmanship heritage to dominate bespoke leather goods for competitive stables. LeMieux differentiates through technical textile innovation in saddle pads and therapeutic boots. Cavallo GmbH anchors its position with precision-engineered hoof protection systems favored by professional farriers.
Horse stable supplies encompass equipment, consumables, and infrastructure materials used in equine housing, care, and training environments, typically constructed from leather, high-density polyethylene, galvanized steel, or compressed natural fibers with specifications for load-bearing capacity, moisture resistance, and animal safety certification. These products serve commercial breeding operations, competitive training centers, and recreational riding facilities by ensuring animal welfare compliance and operational efficiency. Bedding products command the largest revenue pool due to recurring purchase frequency, while grooming tools generate the highest per-unit margins through premium material positioning. Online retail channels are capturing volume growth as equine facilities consolidate procurement through digital platforms, though specialty stores retain loyalty among professional trainers seeking fitting services.
FDA guidelines on animal feed additives and EPA standards for agricultural runoff influence formulation choices in U.S. stable bedding and feed segments, while REACH chemical restrictions in Europe constrain synthetic material sourcing for rubberized flooring and protective gear. USDA biosecurity protocols shape facility design requirements for commercial breeding operations, particularly in interstate transport corridors. Stakeholders must monitor evolving welfare certification standards from FEI and national equestrian federations, as these specifications increasingly determine market access for equipment suppliers serving competitive segments.
Market Dynamics
REACH compliance is compressing synthetic material sourcing across European supply chains while professional trainers in Germany accelerate replacement cycles for Olympic-grade equipment.
Growth Catalysts
- FEI welfare certification:Competitive stables in Germany and France now mandate equipment meeting federation standards, creating pull-through demand for certified bedding and protective gear.
- Hemp-based bedding:Agricultural processors in the Netherlands and Belgium are scaling fiber output for equine applications, displacing traditional straw in commercial breeding operations.
- Biosecurity infrastructure:USDA protocols for interstate transport corridors are mandating facility upgrades across Kentucky and Texas breeding centers.
Market Restraints
- Natural rubber price volatility:Flooring manufacturers face margin compression from Southeast Asian supply disruptions and energy-intensive processing costs.
- REACH synthetic restrictions:ECHA chemical limitations on phthalates and flame retardants are constraining formulation options for rubberized mats and protective boots.
- Leather tanning capacity:Italian and Spanish tanneries dominate premium hide processing, creating geographic concentration risk for bespoke saddle producers.
Strategic Opportunities
- Digital procurement platforms:Commercial stables in France and the UK are consolidating vendor relationships through specialized equine supply marketplaces.
- Therapeutic textile convergence:Technical fabric innovations combining ceramic fiber with moisture-wicking polymers are opening premium positioning in rehabilitation equipment.
- EU Green Deal incentives:Carbon accounting requirements for agricultural operations are accelerating demand for compostable bedding and circular material recovery systems.
Industry Challenges
- Farrier certification bottlenecks:Professional hoof care associations in Germany and Austria report insufficient apprenticeship pipeline for precision-fitted protection systems.
- Legacy facility retrofit costs:Concrete drainage and ventilation upgrades required for FEI compliance are straining capital budgets at older training centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Stable Supplies Market |
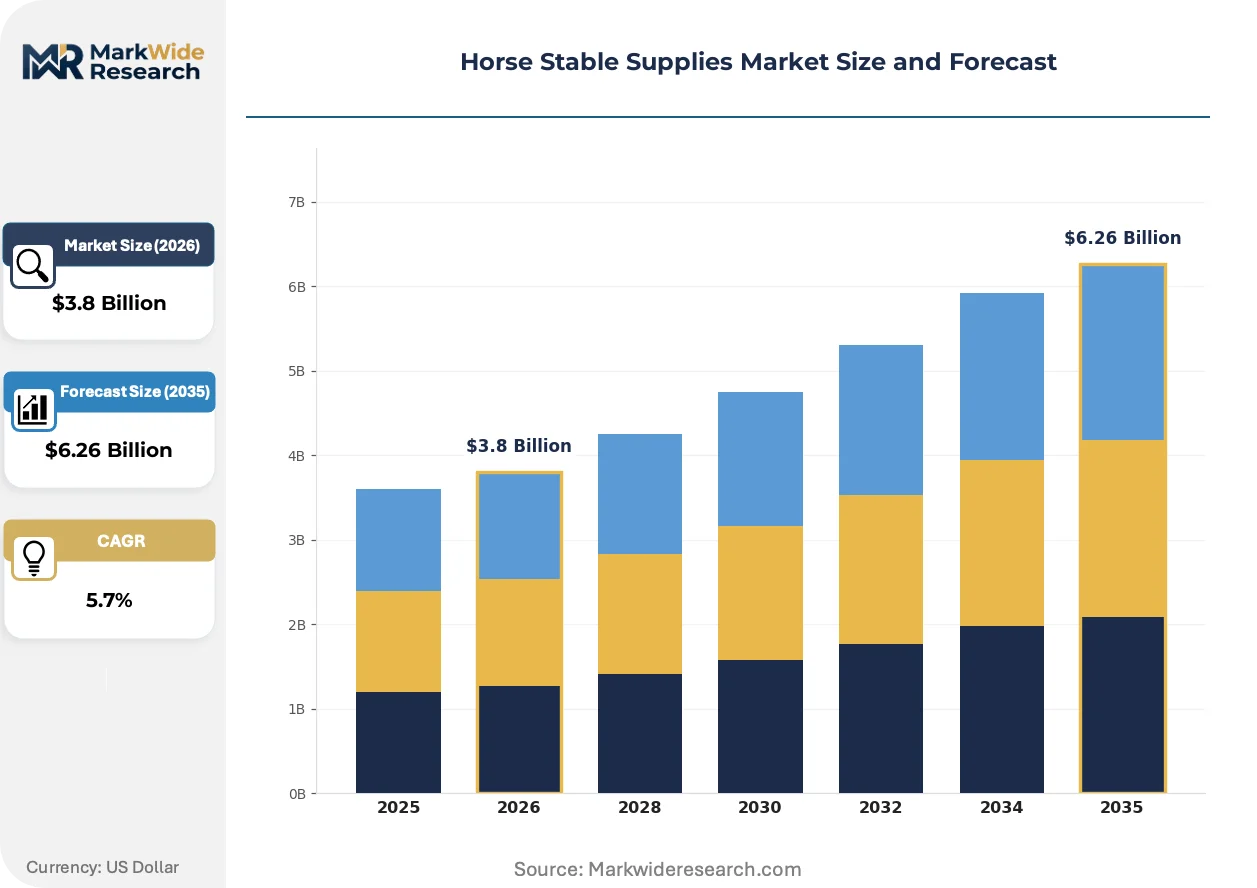
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Feed, Fencing, Grooming Tools Use Case: Dressage, Jumping, Racing, Trail Riding Customer Type: Professional Trainers, Casual Owners, Equine Facilities, Veterinarians Distribution Channel: Online Retail, Specialty Stores, Agricultural Suppliers, Trade Shows |
| Companies Covered | Georg Kieffer Sattlerwarenfabrik GmbH, Cavallo GmbH, LeMieux, Bates Saddles, Horze-Equestrian, Colonial Saddlery, Decathlon, Amerigo Saddle, Dainese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Stable Supplies Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are simultaneously reshaping product specifications and procurement criteria across the equine equipment sector.
Precision-molded polyurethane hoof boots are displacing traditional nailed steel shoes in professional farrier practices. Veterinary clinics in Germany and Switzerland report faster rehabilitation outcomes with these systems. The shift is compressing demand for forge-based farrier services while expanding technical fitting training requirements.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of synthetic bedding binders and rubber flooring vulcanization agents. Manufacturers serving French and Belgian markets report extended product development cycles. Equestrian centers are responding by diversifying supplier bases across compliant Portuguese and Czech producers.
Consolidated procurement through specialized digital platforms is restructuring buyer-vendor relationships. Commercial breeding operations in Kentucky and Texas now negotiate annual contracts through integrated supply portals. Specialty retailers in these regions are unbundling fitting services from product sales to defend margin positions.
Horse Stable Supplies Market Segmentation
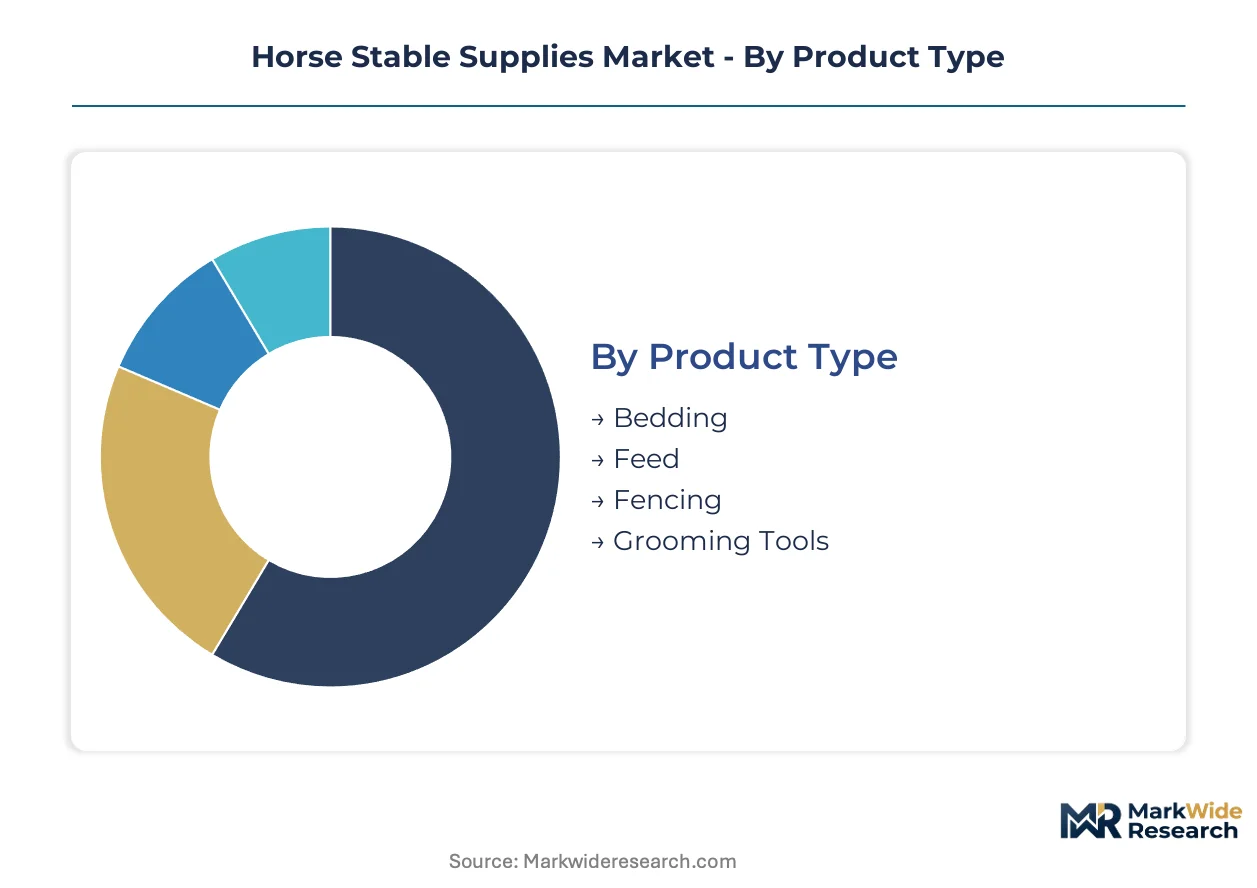
Segmentation in horse stable supplies determines procurement patterns across divergent regulatory environments and performance requirements. FEI welfare standards, USDA biosecurity protocols, and REACH chemical restrictions each reshape product specifications differently across customer tiers and use cases.
Product Type:
REACH Annex XVII restrictions on phthalates and persistent organic pollutants differentiate material compliance burdens across product categories, with synthetic-intensive segments facing extended reformulation cycles.
- Bedding:Compressed natural fibers and hemp-based substrates dominate commercial breeding operations in Kentucky and the Netherlands. Agricultural processors in Belgium are scaling fiber output specifically for equine applications, displacing traditional straw in facilities subject to EU Green Deal carbon accounting requirements.
- Feed:FDA guidelines on animal feed additives constrain formulation choices for U.S. commercial stables, while moisture-resistant storage systems command premium positioning in humid climates. Professional trainers in Germany prioritize certified nutritional profiles for Olympic-level competition horses.
- Fencing:High-density polyethylene and galvanized steel configurations balance load-bearing capacity against animal safety certification.
- Grooming Tools:Premium material positioning through technical textile innovation and ceramic fiber integration generates the highest per-unit margins in the sector.
Bedding handles the majority of throughput due to recurring purchase frequency; grooming tools are expanding most quickly on margin capture.
Use Case:
Performance tier determines equipment replacement velocity and certification stringency, with Olympic-grade infrastructure driving compressed upgrade cycles.
- Dressage:Precision-engineered hoof protection and therapeutic boots dominate rehabilitation protocols. Veterinary clinics in Germany and Switzerland report faster outcomes with polyurethane systems, compressing demand for traditional forge-based farrier services.
- Jumping:Protective gear specifications concentrate demand for REACH-compliant rubberized mats and flame-retardant materials. French and Belgian equestrian centers diversify supplier bases across Portuguese and Czech producers to manage compliance risk.
- Racing:Biosecurity infrastructure mandates from USDA protocols strain capital budgets at older training centers in Kentucky and Texas.
- Trail Riding:Recreational facilities prioritize cost-efficient bedding and basic grooming equipment over premium positioning.
Dressage commands the steepest premium tier; jumping is gaining share fastest on regulatory pull-through.
Customer Type:
Procurement consolidation patterns separate volume-driven facilities from relationship-dependent professional segments.
- Professional Trainers:Bespoke leather goods and precision-fitted equipment anchor competitive positioning. Farrier certification bottlenecks in Germany and Austria constrain service capacity for precision hoof protection systems.
- Casual Owners:Online retail channels capture volume growth as digital platforms consolidate vendor relationships.
- Equine Facilities:Annual contract negotiations through integrated supply portals restructure buyer-vendor dynamics in Kentucky and Texas.
- Veterinarians:Rehabilitation equipment specifications prioritize technical fabric innovations combining ceramic fiber with moisture-wicking polymers.
Equine facilities generate the largest absolute volume; veterinarians are climbing fastest on therapeutic textile convergence.
Distribution Channel:
Channel economics reflect unbundling pressure as fitting services separate from product transactions.
- Online Retail:Specialized equine supply marketplaces consolidate procurement for commercial breeding operations in France and the UK. Kentucky and Texas facilities negotiate annual contracts through integrated portals.
- Specialty Stores:Fitting services and craftsmanship heritage defend margin positions against digital displacement. German bespoke saddle producers retain loyalty through heritage positioning.
- Agricultural Suppliers:Volume throughput for bedding and feed segments leverages existing farm supply infrastructure.
- Trade Shows:Product launch visibility and professional network maintenance concentrate in FEI-sanctioned events.
Online retail captures the dominant volume trajectory; specialty stores defend the highest margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German competitive stables absorb premium equipment costs without volume contraction. Kentucky breeding operations negotiate aggressively on bedding contracts through consolidated procurement portals.
United States
Kentucky and Texas breeding centers drive equipment replacement cycles under USDA interstate biosecurity mandates. FDA feed additive guidelines constrain formulation choices for commercial stables. The Bluegrass region around Lexington concentrates precision-farrier service demand for Olympic-grade hoof protection systems.
Germany
FEI welfare certification requirements pull through demand for certified bedding and protective gear across competitive training facilities. REACH chemical restrictions tighten material standards for synthetic products. The Rhine-Main cluster anchors bespoke leather craftsmanship heritage serving international equestrian centers.
France
Normandy breeding operations scale hemp-based bedding output under EU Green Deal carbon accounting incentives. ECHA phthalate limitations force supplier diversification toward Portuguese and Czech producers. The Paris Basin concentrates professional trainer procurement for dressage and jumping equipment.
United Kingdom
Digital procurement platforms consolidate vendor relationships for commercial stables across England and Wales. Specialty retailers unbundle fitting services from product sales to defend margins. The Cotswolds cluster maintains heritage positioning in bespoke saddle production for competitive segments.
Netherlands
Agricultural processors scale fiber output specifically for equine bedding applications displacing traditional straw. EU circular material recovery requirements accelerate compostable substrate demand. The Gelderland region concentrates hemp processing infrastructure serving Belgian and German export markets.
Horse Stable Supplies Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the horse stable supplies sector. The market structure fragments across heritage craftsmen, technical textile innovators, and scale-driven sporting goods conglomerates. Three archetypes dominate: German precision-engineering specialists, British equestrian heritage brands, and diversified sporting goods multinationals. Competitive moves concentrate on digital procurement platform partnerships and therapeutic textile patent licensing rather than capacity expansion.
Among German fabricators, Georg Kieffer Sattlerwarenfabrik GmbH and Cavallo GmbH exemplify the precision-engineering archetype through their geographic concentration in Rhine-Main industrial clusters. LeMieux occupies a position representing British technical textile innovation in therapeutic equipment. These three companies anchor the premium-tier competitive vector where craftsmanship heritage and veterinary clinical validation determine procurement decisions.
| Leading Market Players |
|---|
| Georg Kieffer Sattlerwarenfabrik GmbH |
| Cavallo GmbH |
| LeMieux |
| Bates Saddles |
| Horze-Equestrian |
| Colonial Saddlery |
| Decathlon |
| Amerigo Saddle |
| Dainese |
| Others |
Supply & Pricing Matrix
Annual contract negotiations through integrated supply portals lock in bedding volume commitments for Kentucky breeding centers while capping price escalation exposure against volatile natural fiber markets. This structure concentrates procurement leverage among large equine facilities and compresses margin recovery for mid-tier distributors serving fragmented recreational stables.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European synthetic bedding and rubberized flooring segments. Certification-grade products command substantial premiums over standard formulations as ECHA chemical restrictions constrain compliant supplier pools. Price differentiation separates FEI-certified equipment from recreational-grade alternatives, with German Olympic-level stables absorbing steep premiums without volume contraction. Cost compression in synthetic material tiers is intensifying because Southeast Asian rubber supply disruptions and energy-intensive processing cycles squeeze manufacturer margins. Kentucky commercial breeding operations exhibit the sharpest price sensitivity, negotiating aggressively on bedding contracts through consolidated procurement portals.
Supply Chain Analysis
Inventory cycles for hemp-based bedding extend lead times during Belgian agricultural processor harvest windows, compressing just-in-time availability for Dutch and German export markets. Raw material sourcing draws from Italian and Spanish tanneries for premium leather goods, Southeast Asian natural rubber plantations for flooring substrates, and Netherlands-Belgium hemp fiber processing clusters for bedding alternatives. Single-source vulnerability concentrates in Italian premium hide processing where geographic concentration risk constrains bespoke saddle producer capacity. Distribution runs through specialized equine supply marketplaces for commercial volume, specialty retailers for fitting-dependent premium goods, and agricultural supply channels for bedding and feed throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The horse stable supplies sector rewards players who control scarce technical fitting capabilities and certified material access, with farrier certification bottlenecks in Germany and Austria constraining service capacity for precision hoof protection deployment.
For Market Incumbents: Compound heritage positioning in bespoke leather craftsmanship with digital procurement platform partnerships to defend against marketplace unbundling of product and fitting services. Invest in REACH-compliant synthetic material R&D to preempt regulatory displacement, while securing long-term offtake agreements with Belgian hemp processors to lock in bedding supply access ahead of EU Green Deal carbon accounting acceleration. For New Entrants and Emerging Players: Anchor in therapeutic textile convergence opportunities where ceramic fiber innovations meet veterinary rehabilitation demand, a segment climbing fastest on margin capture with limited incumbent patent density. Target underpenetrated veterinary clinic procurement channels for precision-molded polyurethane hoof boots, leveraging clinical outcome data from German and Swiss veterinary networks as the primary go-to-market credential. For Investors and Strategic Acquirers: Capital is best deployed toward precision-engineering specialists with captive farrier certification pipelines and REACH-compliant material science capabilities, assets that deepen competitive moats across the analysis window. Watch farrier apprenticeship graduation rates in Germany and Austria as the inflection signal for service capacity expansion feasibility and precision-fitted equipment penetration ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA chemical restrictions force product development cycle extensions that compliant manufacturers convert into pricing power. |
| Digital Procurement Platform Integration | Kentucky and Texas breeding centers consolidate vendor relationships through specialized equine supply marketplaces. |
| Therapeutic Textile Patent Licensing | Ceramic fiber innovations from British technical textile developers open premium positioning in veterinary rehabilitation equipment. |
| Farrier Certification Pipeline Investment | German and Austrian professional associations report insufficient apprenticeship throughput for precision hoof protection system deployment. |
| EU Green Deal Circular Recovery Systems | Carbon accounting requirements for agricultural operations accelerate compostable bedding and material recovery infrastructure demand. |
Research Methodology
The analysis maps bedding substrates, grooming equipment, protective gear, and infrastructure materials, each validated through professional trainers, farrier association representatives, veterinary clinic procurement officers, and commercial breeding facility managers. Primary fieldwork combined structured interviews with stable operators across Kentucky, Texas, Germany, France, and the Netherlands alongside secondary validation through FEI welfare certification databases, ECHA REACH substance restriction filings, USDA biosecurity protocol documentation, and EU Green Deal agricultural incentive records. Bottom-up segment sizing triangulated against top-down market envelope checks ensures internal consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, use case performance tier, customer procurement consolidation pattern, and distribution channel structure. CAGRs derived from segment-level growth trajectory analysis incorporating replacement cycle compression at German Olympic-grade facilities, hemp bedding displacement rates in Belgian and Dutch commercial operations, and digital procurement platform adoption curves in Kentucky breeding centers.
Material uncertainties — regulatory enforcement intensity variations, natural rubber supply disruption duration, farrier certification pipeline expansion rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about FEI welfare standard adoption timelines and EU circular material recovery infrastructure deployment. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Goat Handling Equipment Market