
 Animal Cage Market | 2026-2036
Animal Cage Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Cage Market Analysis
Buyer concentration in the Animal Cage Market is shifting as large laboratory networks and consolidated veterinary hospital chains displace fragmented independent purchases. Mason Company, LLC leverages its manufacturing scale to dominate institutional contracts across North American research corridors. Schroer Manufacturing Company anchors its position through specialized stainless steel enclosures engineered for GLP-compliant facilities. Technik, Inc competes by sustaining deep product lines tailored to vivarium operators with stringent sanitation protocols.
Animal cages are fabricated enclosures designed to house, transport, or temporarily restrain animals, typically constructed from welded stainless steel wire, high-density polyethylene, or powder-coated aluminum with specifications dictating bar spacing, ventilation aperture ratios, and load-bearing thresholds for species-specific welfare compliance. Their primary commercial purpose spans laboratory research containment, veterinary clinical housing, commercial breeding operations, and wildlife rehabilitation holding. Wire cages occupy the largest share among product types due to durability demands in high-throughput laboratory settings, while plastic cages represent the fastest-growing category as disposable, autoclavable formats gain preference in pathogen-sensitive research environments. Among end users, laboratories command premium pricing through specification-intensive procurement, whereas pet stores operate on volume-driven, standardized sizing across small-to-medium enclosures.
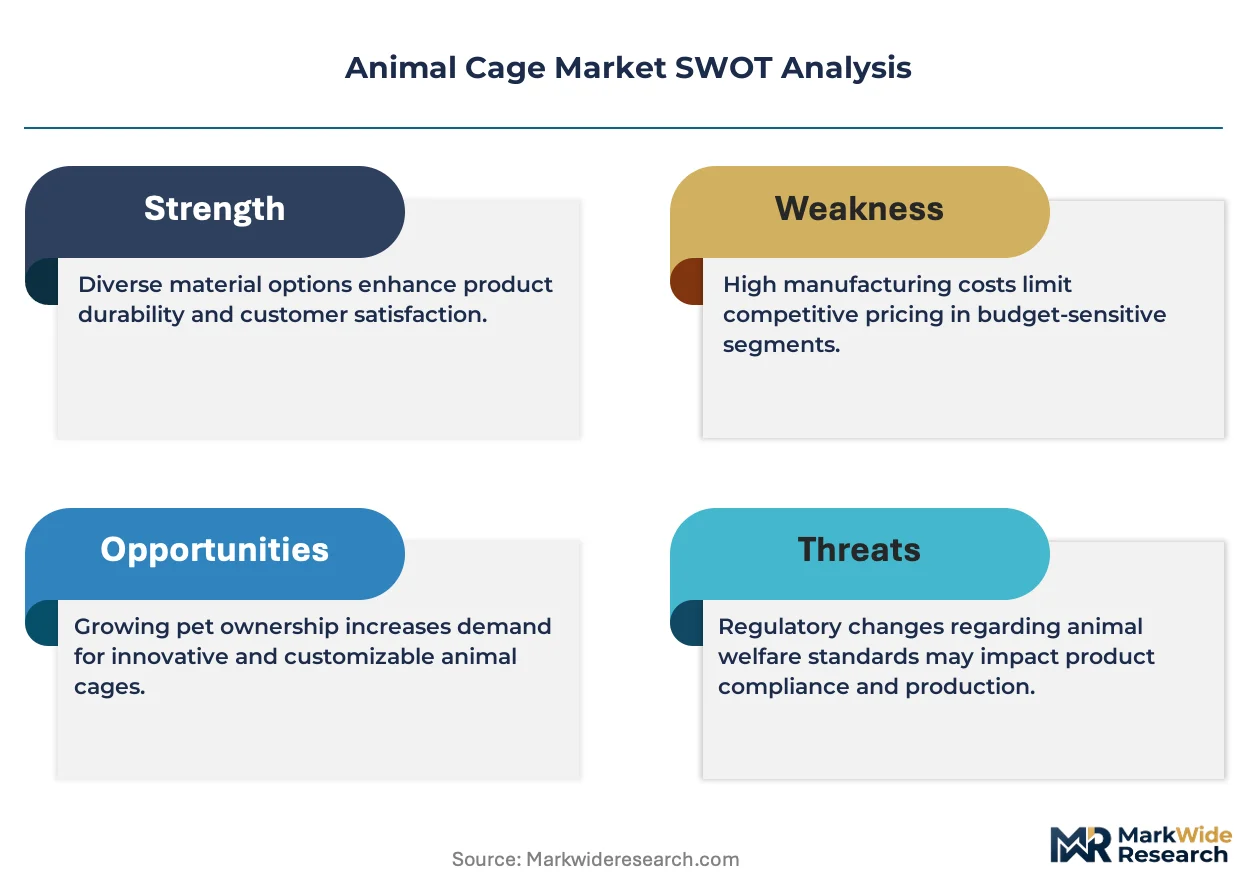
The FDA enforces cage dimensional and material standards through Good Laboratory Practice regulations that mandate sanitization compatibility and species-appropriate spatial minimums, while the EPA's TSCA guidelines indirectly influence cage selection in chemical exposure studies requiring specialized containment. The EU's Directive 2010/63/EU imposes species-specific enclosure enrichment mandates that manufacturers must embed into design protocols for CE-marked research products. Stakeholders must monitor evolving welfare standards across multiple jurisdictions to align R&D pipelines with compliance trajectories that will determine market access eligibility.
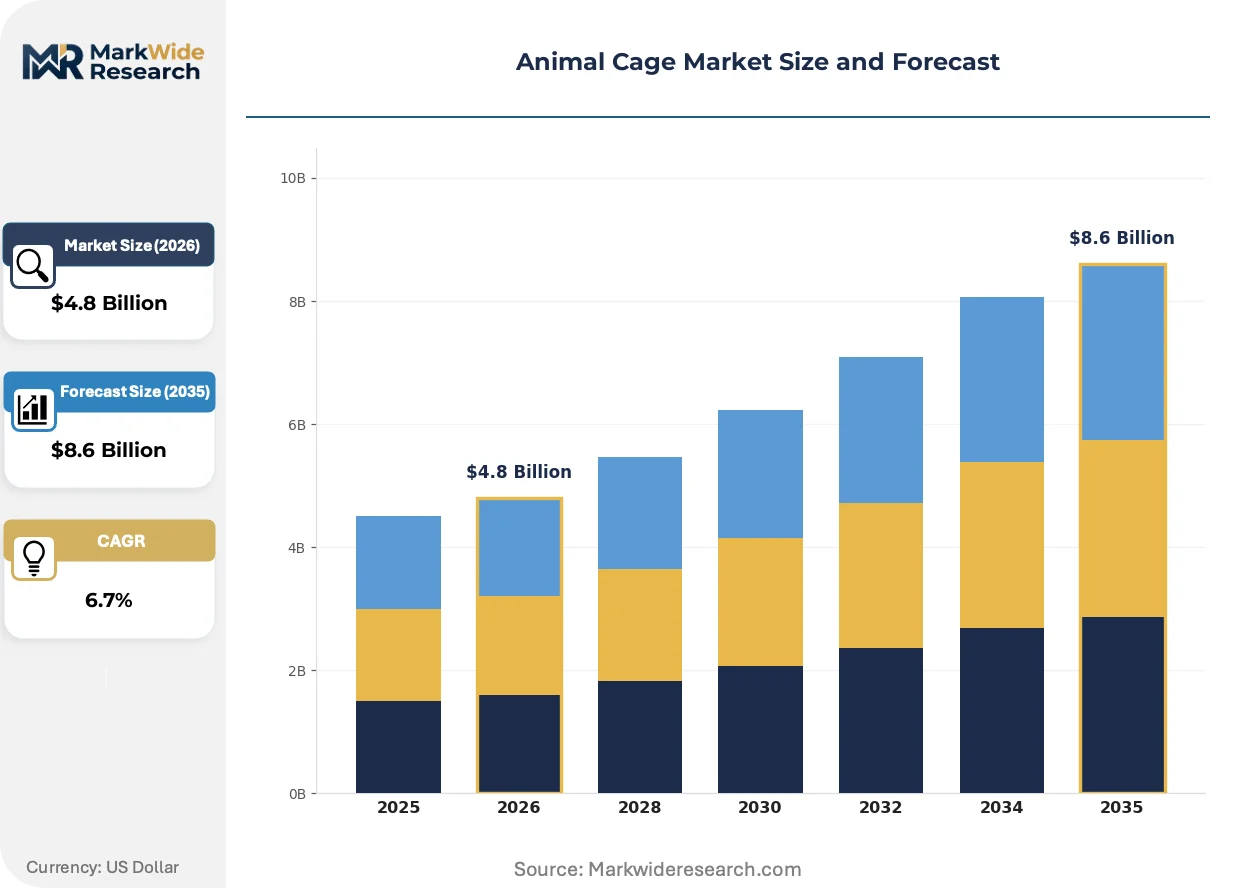
Market Dynamics
Consolidation among laboratory networks and veterinary hospital chains is concentrating procurement authority into fewer buyers with specification-intensive demands, compressing vendor margins while elevating compliance requirements across stainless steel and disposable plastic enclosure categories.
Growth Catalysts
- EU Directive 2010/63/EU enrichment mandates:Species-specific housing requirements are accelerating replacement cycles in German and French research facilities, forcing upgrades to larger, enriched enclosures with nesting materials and social housing compatibility.
- High-throughput laboratory expansion:Centralized vivarium infrastructure in the United States is standardizing on autoclavable, disposable plastic cages to eliminate cross-contamination risks in pathogen-sensitive oncology and infectious disease studies.
- Veterinary inpatient housing protocols:Quarantine and isolation standards at North American specialty clinics are expanding stainless steel cage procurement for infectious disease management and post-surgical recovery wards.
Market Restraints
- Stainless steel raw material volatility:Nickel and chromium price swings are compressing fabrication margins for GLP-compliant welded wire enclosures, forcing manufacturers to absorb costs or risk contract losses.
- Supply concentration in Chinese polymer feedstock:High-density polyethylene and polypropylene resin for disposable cages depends on concentrated Asian petrochemical suppliers, exposing buyers to shipping disruptions and tariff exposure.
- Sanitization validation bottlenecks:FDA Good Laboratory Practice requirements for documented cage cleaning protocols create extended qualification timelines that delay facility commissioning and revenue recognition.
Strategic Opportunities
- Indian pharmaceutical research expansion:CDSCO-aligned toxicology facilities and CRO infrastructure investments are creating demand for CE-marked, species-compliant enclosures as domestic outsourcing accelerates.
- IoT-enabled environmental monitoring:Sensor-integrated cages that track temperature, humidity, and activity patterns are converging with vivarium automation platforms, opening premium pricing tiers for data-generating hardware.
- USDA wildlife rehabilitation mandates:Federal and state wildlife agency standards for temporary holding facilities are standardizing cage specifications for raptor, mammal, and reptile recovery centers across state park networks.
Industry Challenges
- Vivarium technician certification gaps:AABL-accredited facility managers with specialized training in species-specific housing requirements remain scarce, constraining expansion timelines for new research sites.
- Legacy cage fleet interoperability:Stainless steel racks, watering systems, and cage formats from 1990s-era installations resist integration with modern disposable cage automation, forcing costly facility overhauls.
- Multi-jurisdiction welfare standard divergence:Misalignment between FDA spatial minimums, EU enrichment rules, and AAALAC International guidelines complicates global CRO operations with standardized equipment procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Cage Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Cages, Plastic Cages, Portable Cages, Wooden Cages Application: Pet Ownership, Research Facilities, Breeding, Wildlife Rehabilitation End User: Veterinarians, Pet Stores, Breeders, Laboratories Size: Small, Medium, Large, Extra Large |
| Companies Covered | GteBel SA, Technik, Inc, Edemco Dryers, Inc, Narang Medical Limited, Groomer's Best, Inc., Mason Company, LLC, Schroer Manufacturing Company, ZOOM SCIENTIFIC WORLD, Medical Master Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Cage Market Emerging Trajectories
Disposable, single-use cage formats are displacing traditional sanitization-dependent workflows as pathogen containment priorities reshape procurement specifications across pharmaceutical and academic research corridors.
Autoclavable high-density polyethylene cages with integrated filter tops and disposable water bottles are consolidating procurement preferences among GLP-compliant toxicology facilities. Large pharmaceutical sponsors and contract research organizations in Massachusetts and New Jersey are mandating single-use formats for oncology and immunology studies to eliminate residual contamination risks. This shift is compressing demand for reusable stainless steel enclosures in high-throughput screening applications while expanding recurring revenue streams for consumable cage suppliers.
REACH chemical restrictions and the EU Green Deal circular economy mandates are tightening material disclosure requirements for plastic cage manufacturers selling into European research markets. Substances of very high concern in polymer stabilizers and colorants face phased elimination, forcing reformulation of legacy product lines. German and Dutch vivarium operators are now demanding full material passports and recyclability certifications as standard procurement criteria, elevating compliance costs for non-EU suppliers.
Specification authority is migrating from individual facility managers to centralized procurement offices at consolidated laboratory networks and veterinary hospital systems. Multi-site contracts with standardized cage formats, automated watering compatibility, and unified service agreements are displacing fragmented, site-level purchasing decisions. This concentration is most visible across the United States, where national CRO chains and specialty veterinary platforms are leveraging volume commitments to extract price concessions and dedicated inventory guarantees from enclosure manufacturers.
Animal Cage Market Segmentation
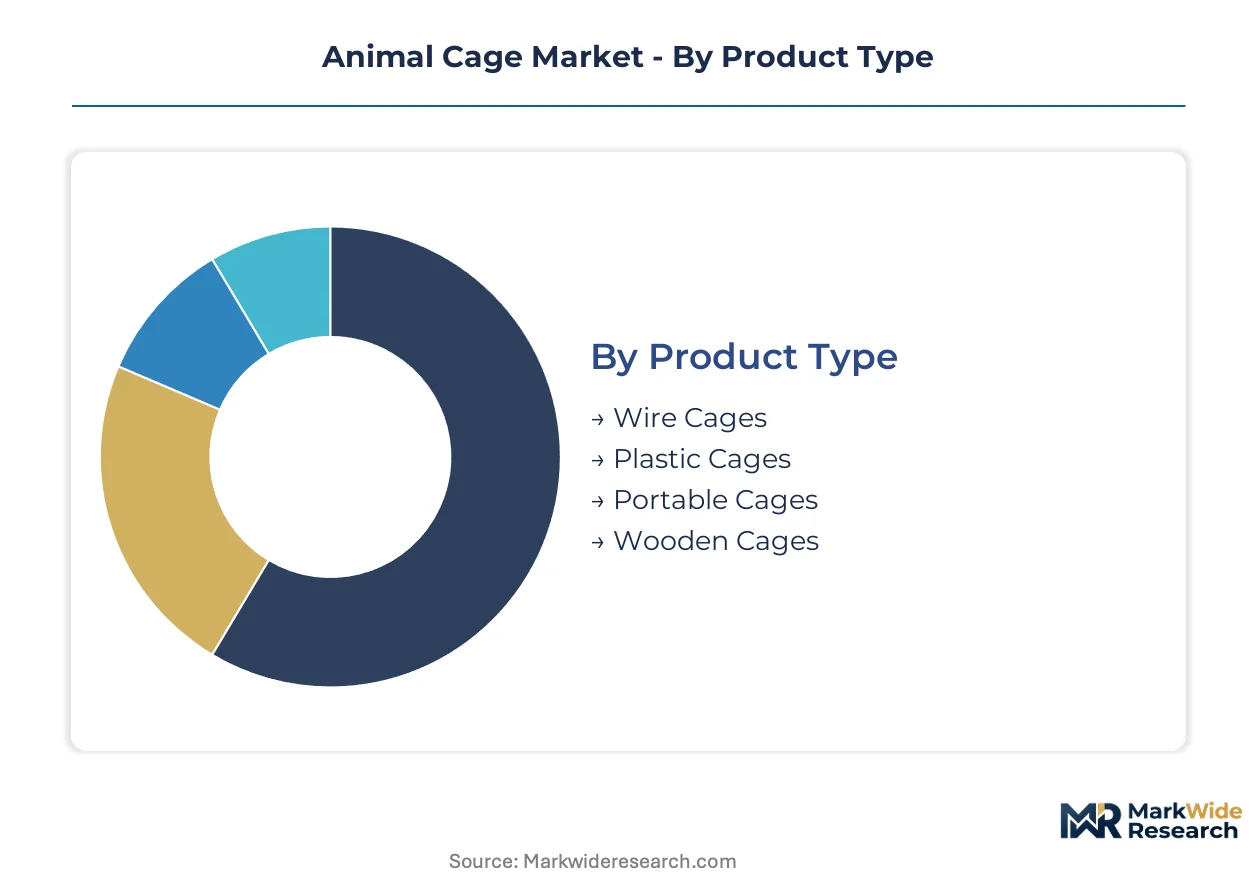
Animal cage procurement splits sharply between specification-intensive institutional buyers and volume-driven consumer channels. Understanding where each segment sits within integrated facility systems versus standalone purchase decisions shapes vendor positioning and R&D allocation.
Product Type:
Wire cages embed deeply into automated rack systems and centralized sanitation infrastructure, while portable and wooden formats serve disconnected, standalone use cases with minimal facility integration.
- Wire Cages:Fabricated from welded stainless steel wire with powder-coated or electropolished finishes, these enclosures withstand repeated autoclave cycles and automated washing systems. Demand concentrates in Massachusetts and New Jersey pharmaceutical corridors where GLP-compliant toxicology facilities mandate durability for high-throughput screening protocols.
- Plastic Cages:Injection-molded high-density polyethylene or polypropylene formats with integrated filter tops and disposable water bottles eliminate cross-contamination risks. Academic medical centers in California and Texas are standardizing on single-use plastics for infectious disease and oncology studies to bypass sanitization validation bottlenecks.
- Portable Cages:Lightweight aluminum or polymer folding enclosures for field research and temporary holding.
- Wooden Cages:Solid pine or plywood constructions for small mammal breeders and exotic pet retail displays.
Wire cages lead volumes today; plastic cages are gaining share fastest.
Application:
Research facilities and breeding operations anchor the cost tier with premium specification requirements, while pet ownership and wildlife rehabilitation sit at standardized, price-sensitive procurement levels.
- Research Facilities:Vivarium operators demand species-specific spatial minimums, enrichment compatibility, and documented sanitization protocols aligned with FDA Good Laboratory Practice regulations. German centralized laboratory infrastructure is accelerating replacement cycles for CE-marked, enriched enclosures.
- Breeding:Commercial rodent and canine breeding facilities require high-density housing with automated watering and waste management systems. Contract breeders in North Carolina and Indiana are consolidating procurement through multi-site standardization programs.
- Pet Ownership:Residential consumers purchase through retail and e-commerce channels with minimal regulatory oversight.
- Wildlife Rehabilitation:State and federal wildlife agencies mandate temporary holding specifications for raptor, mammal, and reptile recovery.
Research facilities command premium pricing tiers; breeding applications scale through volume concentration.
End User:
Laboratories and veterinarians drive margin through compliance-intensive procurement, whereas pet stores and breeders operate on standardized formats with limited customization.
- Laboratories:Academic and pharmaceutical research sites specify autoclavable materials, interoperability with automation platforms, and full material traceability. National CRO chains are centralizing cage procurement across Massachusetts, New Jersey, and California sites.
- Veterinarians:Specialty clinics and hospital systems require stainless steel inpatient housing for quarantine protocols and post-surgical recovery wards. North American veterinary chains are expanding isolation capacity to meet infectious disease management standards.
- Pet Stores:Retail chains stock standardized small-to-medium enclosures for consumer self-selection.
- Breeders:Commercial operations prioritize durability and sanitation efficiency across high-turnover housing systems.
Laboratories dominate specification authority; veterinarians are consolidating fastest through chain acquisition.
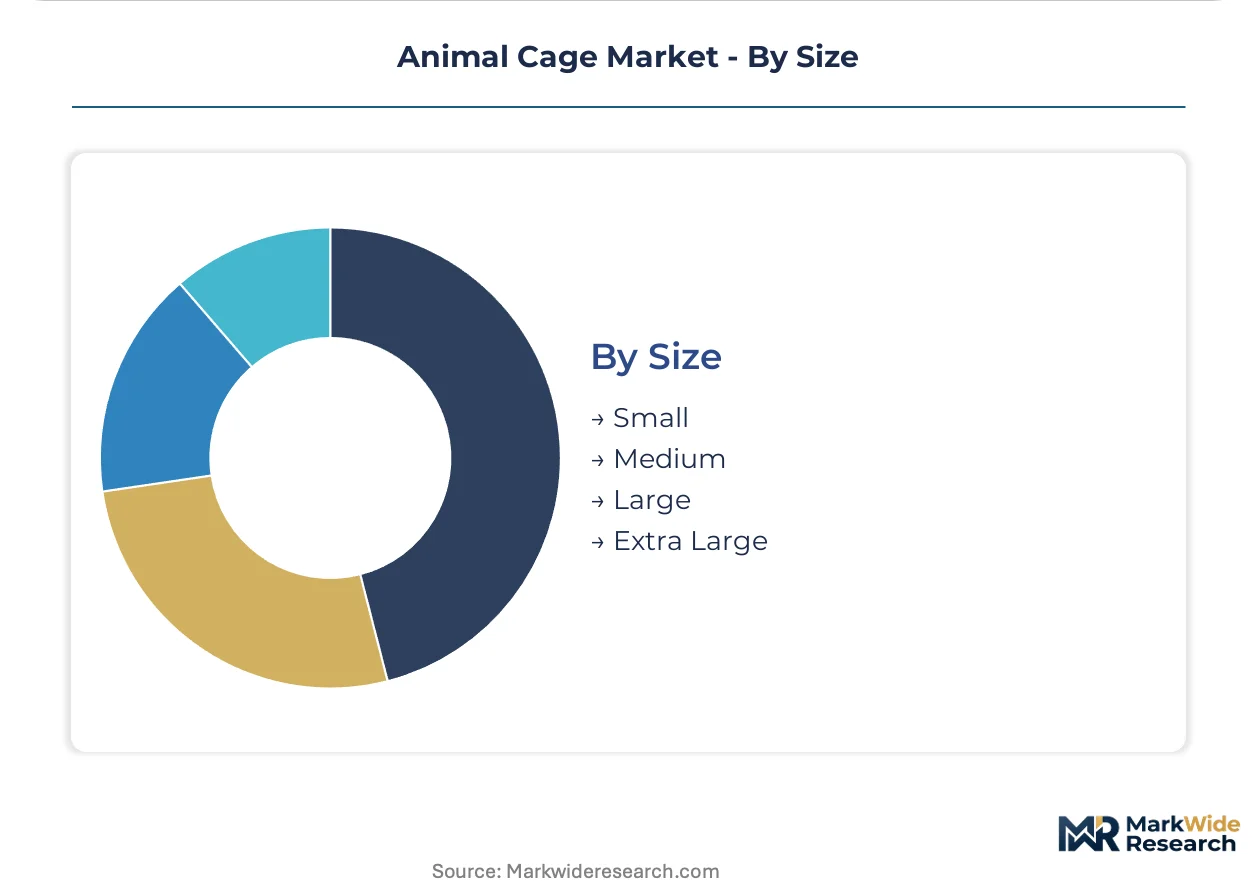
Size:
Small and medium formats align with high-throughput, space-constrained vivarium automation, while large and extra-large cages serve specialized species requirements with lower installation density.
- Small:Rodent and small mammal enclosures designed for rack-mounted, high-density housing in pharmaceutical screening facilities. EU Directive 2010/63/EU spatial minimums are forcing upgrades from legacy 1990s-era formats in German and French research sites.
- Medium:Rabbit, feline, and medium canine housing for toxicology studies and veterinary inpatient wards. Massachusetts CRO infrastructure is standardizing medium formats for reproductive toxicology protocols.
- Large:Canine and non-human primate enclosures for long-term studies and breeding colonies.
- Extra Large:Agricultural and large mammal research applications with specialized ventilation and enrichment requirements.
Small cages dominate installation counts; medium formats are climbing fastest on toxicology demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's centralized laboratory infrastructure accelerates cage replacement cycles faster than the fragmented procurement patterns visible across Italian research sites. Regulatory divergence between FDA spatial minimums and EU enrichment mandates forces multi-national CROs to maintain parallel inventory stocks across Atlantic operations.
United States
Pharmaceutical toxicology corridors in Massachusetts and New Jersey standardize on autoclavable disposable cages for oncology and immunology protocols. FDA Good Laboratory Practice regulations mandate documented sanitization compatibility and species-appropriate spatial minimums that elevate specification requirements. National CRO chains centralize procurement across multi-site networks, compressing vendor margins while extracting dedicated inventory guarantees.
Germany
EU Directive 2010/63/EU enrichment mandates force upgrades to larger, enriched enclosures with nesting materials and social housing compatibility. The country's centralized laboratory infrastructure accelerates replacement cycles for CE-marked research products. Bavarian and Baden-Württemberg vivarium clusters demand full material passports and recyclability certifications as standard procurement criteria.
India
CDSCO-aligned toxicology facilities and contract research organization infrastructure investments create demand for CE-marked, species-compliant enclosures. Domestic pharmaceutical outsourcing accelerates as global sponsors seek cost-efficient preclinical capacity. Maharashtra and Karnataka research parks import specification-intensive housing systems to meet international audit standards.
China
NMPA regulatory alignment with OECD test guidelines elevates enclosure specifications for domestic toxicology facilities. Yangtze River Delta and Pearl River Delta biotech clusters invest in GLP-compliant vivarium infrastructure to capture international pharmaceutical outsourcing contracts. Polymer feedstock concentration in coastal petrochemical corridors exposes cage manufacturers to supply volatility.
United Kingdom
AAALAC International accreditation requirements at academic medical centers sustain premium procurement for specification-intensive housing systems. London and Southeast England CRO clusters standardize cage formats to enable multi-site study continuity. Post-Brexit regulatory divergence from EU Directive 2010/63/EU creates compliance complexity for cross-border research operations.
Animal Cage Market Vendor Landscape
North American producers anchor one tier; European specialists hold specification authority in enriched enclosure categories. The vendor base stratifies across three tiers: scale-driven institutional contractors, compliance-focused stainless steel fabricators, and disposable plastic consumable suppliers. Two dominant competitive moves are reshaping positioning: multi-site contract consolidation among laboratory networks and backward integration into polymer feedstock by disposable cage manufacturers.
Among North American fabricators, Mason Company, LLC and Schroer Manufacturing Company exemplify divergent strategic archetypes. Mason represents the scale-driven institutional contractor model with manufacturing breadth across standardized formats. Schroer occupies the compliance-specialist position through stainless steel fabrication protocols engineered for GLP-validated facilities. Technik, Inc sits within the premium-tier vector, serving vivarium operators with stringent sanitation requirements through deep product line configurations. These three anchors illustrate how vendor positioning fragments across procurement authority concentration, material specialization, and regulatory compliance depth.
| Leading Market Players |
|---|
| GteBel SA |
| Technik, Inc |
| Edemco Dryers, Inc |
| Narang Medical Limited |
| Groomer's Best, Inc. |
| Mason Company, LLC |
| Schroer Manufacturing Company |
| ZOOM SCIENTIFIC WORLD |
| Medical Master Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Nickel and chromium feedstock costs cascade through stainless steel cage fabrication tiers, compressing margins for GLP-compliant welded wire manufacturers while elevating premium pricing for electropolished finishes in Massachusetts pharmaceutical corridors. Polymer resin volatility from Asian petrochemical suppliers feeds into disposable plastic cage pricing, creating divergence between autoclavable polyethylene tiers and standard injection-molded formats.
Pricing Analysis
Capacity additions in Chinese polymer feedstock are reshaping price floors for disposable cage categories while stainless steel fabrication remains tethered to nickel exchange volatility. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked enriched enclosures from FDA-compliant baseline formats and uncertified commercial breeding cages. Cost compression in standard wire tiers is intensifying because consolidated CRO procurement extracts volume concessions. Pet store retail channels exhibit highest price sensitivity; pharmaceutical toxicology facilities demonstrate lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Single-source vulnerability sits with concentrated Chinese high-density polyethylene and polypropylene resin suppliers serving disposable cage manufacturers. Raw material sourcing draws from German stainless steel mills, Indian polymer compounders, and Taiwanese precision filtration component fabricators. Tariff exposure on Asian petrochemical imports threatens margin stability for consumable cage producers. Distribution runs through vivarium equipment distributors with regional service capabilities, direct institutional contracts with national CRO chains, and veterinary supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal cage procurement consolidation creates margin-expansion headroom for vendors capturing multi-site standardization contracts, with premium-tier displacement of legacy stainless steel formats in pathogen-sensitive research environments.
For Market Incumbents: Extend automation compatibility roadmaps to capture disposable cage replacement cycles in Massachusetts and New Jersey pharmaceutical corridors. Backward integration into polymer compounding mitigates Chinese resin supply volatility threatening consumable tier margins. CE marking investments defend position against REACH material disclosure mandates elevating compliance costs for non-EU suppliers. For New Entrants and Emerging Players: Enter via IoT-enabled environmental monitoring cages converging with vivarium automation platforms, targeting premium data-generating hardware tiers underserved by incumbent fabricators. Indian CDSCO-aligned toxicology facilities represent the most penetrable geography, with Maharashtra research parks importing specification-intensive housing to meet international audit standards. Position through sensor-integrated cage formats with temperature and humidity tracking capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where national CRO chains centralize procurement authority across multi-site networks, compressing fragmented vendor margins. Acquisition target archetypes include disposable plastic cage specialists with captive polymer sourcing and CE-marking capabilities for EU market access. Signal to monitor: AAALAC International accreditation mandates at Indian and Chinese research facilities accelerating specification-intensive enclosure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Disposable Cage Manufacturing Scale-Up | Captures single-use format preference in FDA GLP toxicology facilities across Massachusetts corridors. |
| Backward Integration into Polymer Compounding | Reduces exposure to Chinese resin supply volatility and REACH material disclosure compliance costs. |
| CE Marking and EU Enrichment Certification | Unlocks German centralized laboratory replacement cycles driven by Directive 2010/63/EU mandates. |
| IoT Sensor Integration Partnership | Converges cage hardware with vivarium automation platforms for premium data service revenue streams. |
| Multi-Site CRO Contract Consolidation | Leverages procurement authority concentration to extract volume commitments and inventory guarantees. |
Methodological Framework
Multiple input streams — primary interviews with vivarium operators, regulatory affairs specialists, and CRO procurement directors; secondary validation through FDA GLP guidance documents, EU Directive 2010/63/EU implementation reports, and AAALAC International accreditation databases; trade data from polymer resin customs records and stainless steel mill output statistics — were reconciled through bottom-up facility enumeration and top-down market sizing triangulation.
Historical cage procurement patterns were cross-referenced against panel input from pharmaceutical toxicology executives and veterinary hospital chain operators across the analysis window. Segmentation dimensions modeled include product material tier, end-use application intensity, regulatory compliance level, and regional procurement concentration. CAGRs were derived from facility expansion pipelines, replacement cycle acceleration factors, and species-specific housing standard upgrades. Industry-specific forecast inputs incorporated CDSCO alignment timelines in India and NMPA GLP adoption trajectories in China.
Inputs from regulatory filing databases and institutional procurement records were available through the study window; gaps in real-time polymer resin pricing transparency and CRO contract term confidentiality introduce uncertainty bands around disposable cage volume projections. Forecasts reflect documented assumptions regarding EU enrichment mandate enforcement intensity and FDA GLP inspection frequency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Animal Feed Mixer Market