
 Cattle Handling Systems Market | 2026-2036
Cattle Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Handling Systems Market Outlook
Modular chute-and-pen bundling is repositioning buyer choice toward configurable systems that scale with herd size. Arrowquip leverages digital scale integration and quiet-hydraulic design to differentiate its offerings in premium segments. Priefert Manufacturing anchors its position through in-house steel fabrication and extensive dealer networks across the US Plains. MJE Livestock Equipment specializes in custom-engineered solutions for commercial feedyards requiring high-throughput configurations.
Cattle handling systems comprise corrals, chutes, gates, and restraining equipment engineered from galvanized steel or powder-coated tubular frameworks designed to direct, contain, and process livestock with minimal stress and human injury risk. These systems functionally integrate squeeze chutes with hydraulic or manual head gates, adjustable alley widths, and anti-backup features to achieve throughput rates exceeding 150 head per hour in commercial operations. Manual technology still occupies the largest installed base among small-to-mid operations, while fully automatic systems represent the fastest-growing category as labor scarcity drives capital substitution in large dairies and feedlots. Permanent installation dominates value capture given concrete foundations and fixed infrastructure requirements, though mobile systems are gaining traction among contract grazers and seasonal operations.
USDA Food Safety and Inspection Service humane handling enforcement and OSHA agricultural workplace standards directly shape equipment design mandates, particularly regarding non-slip flooring, V-sides to prevent leg injuries, and pressure-limiting squeeze mechanisms. ISO 10954 and relevant ASTM livestock equipment standards further condition export market access and product liability exposure for manufacturers. Stakeholders must monitor evolving animal welfare audit protocols from major beef packers and dairy cooperatives, as these private standards increasingly dictate minimum system specifications ahead of regulatory mandates.
Market Dynamics
Commercial beef feedlots in the Texas-Oklahoma-Kansas corridor are expanding covered working facilities to meet processor audit requirements, compressing procurement timelines and forcing capital equipment decisions ahead of traditional replacement cycles.
Growth Catalysts
- USDA Humane Handling Enforcement:Food Safety and Inspection Service audits now mandate non-slip flooring and pressure-limiting squeeze mechanisms, compelling yard operators to upgrade legacy infrastructure.
- Labor Scarcity in Large Dairies:Fully automatic handling systems are substituting capital for declining agricultural workforce availability, accelerating replacement of manual chutes.
- ISO 10954 Certification:Export market access for North American manufacturers now requires compliance with international livestock equipment standards, expanding addressable market scope.
Market Restraints
- Galvanized Steel Price Volatility:Tubular framework input costs fluctuate with scrap metal and zinc pricing, compressing fabrication margins during commodity spikes.
- Concrete Foundation Requirements:Permanent installation infrastructure demands significant site preparation and curing time, limiting rapid deployment for seasonal operations.
- Manual Technology Lock-In:Small-to-mid operations retain substantial installed base of legacy squeeze chutes, creating replacement inertia despite efficiency gains.
Strategic Opportunities
- Mobile System Development:Contract grazers and seasonal cattle operations require portable corral configurations that deploy without permanent foundations.
- Digital Scale Integration:Converging load-cell technology with hydraulic chute systems enables real-time weight data capture for precision feeding programs.
- Quiet-Hydraulic Design:Reduced noise emission systems address animal welfare audit protocols from major beef packers ahead of regulatory mandates.
Industry Challenges
- Welding Certification Requirements:In-house steel fabrication demands AWS-certified welders, constraining production scaling for regional manufacturers.
- Dealer Network Coverage Gaps:Extensive service and parts distribution across the US Plains requires capital-intensive territory development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Handling Systems Market |
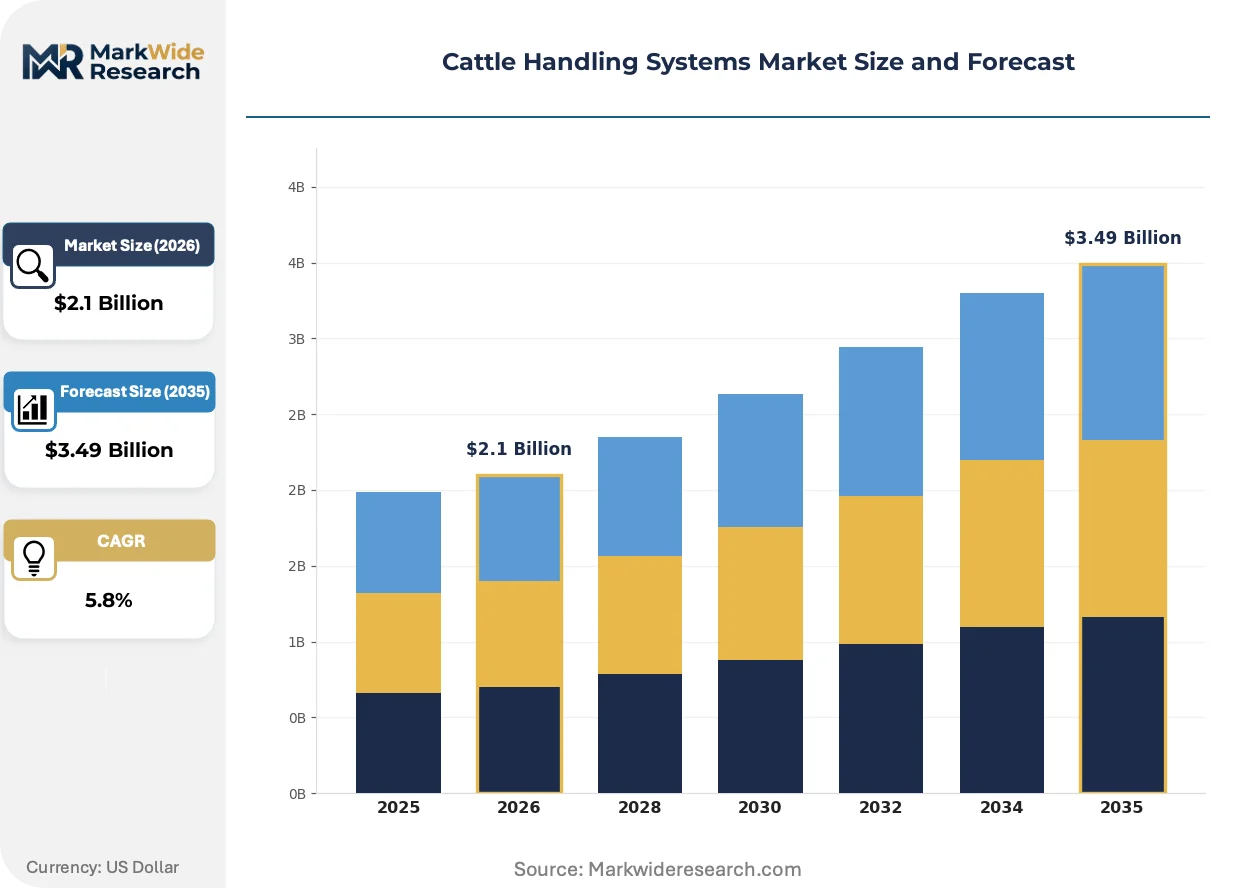
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gates, Chutes, Sorting Systems, Panels Technology: Manual, Semi-Automatic, Fully Automatic, Remote-Controlled End User: Dairies, Beef Farms, Research Facilities, Livestock Shelters Installation: On-Farm, Mobile, Permanent, Temporary |
| Companies Covered | MJE Livestock Equipment, Priefert Manufacturing, Arrowquip, Bison Industries, Behlen Country, D-S Livestock Equipment, Powder River, TUFF BUILT, Hi-Hog Farm & Ranch Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Handling Systems Market Strategic Shifts
Equipment architecture is fragmenting from fixed installations toward reconfigurable platforms that adapt to shifting herd sizes and seasonal throughput demands.
Modular chute-and-pen bundling is modularizing system architecture across the premium equipment tier. Galvanized steel tubular frameworks now incorporate standardized connection points allowing rapid reconfiguration of alley widths and pen arrangements. Large commercial feedyards in the Texas-Oklahoma-Kansas corridor are adopting these platforms to accommodate variable lot sizes without complete system replacement. This modularity is modularizing capital deployment, enabling phased upgrades rather than single large outlays.
OSHA agricultural workplace standards are tightening operator safety specifications for squeeze chute design. New mandates require anti-backup features and emergency release mechanisms that exceed prior voluntary guidelines. Commercial beef operations with more than fifty employees face inspection priority, driving preemptive equipment replacement ahead of enforcement actions. Manufacturers are redesigning head gate geometry to comply while maintaining throughput rates.
Buyer concentration among large-scale yard operators is compressing sales cycles and shifting negotiation leverage. Procurement teams now bundle chute, pen, and scale purchases into single-source contracts, marginalizing smaller fabricators lacking full product portfolios. This concentration is most visible in the Texas Panhandle and western Kansas, where feedlot construction continues at scale. After-sales service and parts availability have become decisive selection criteria alongside equipment specifications.
Cattle Handling Systems Market Segmentation
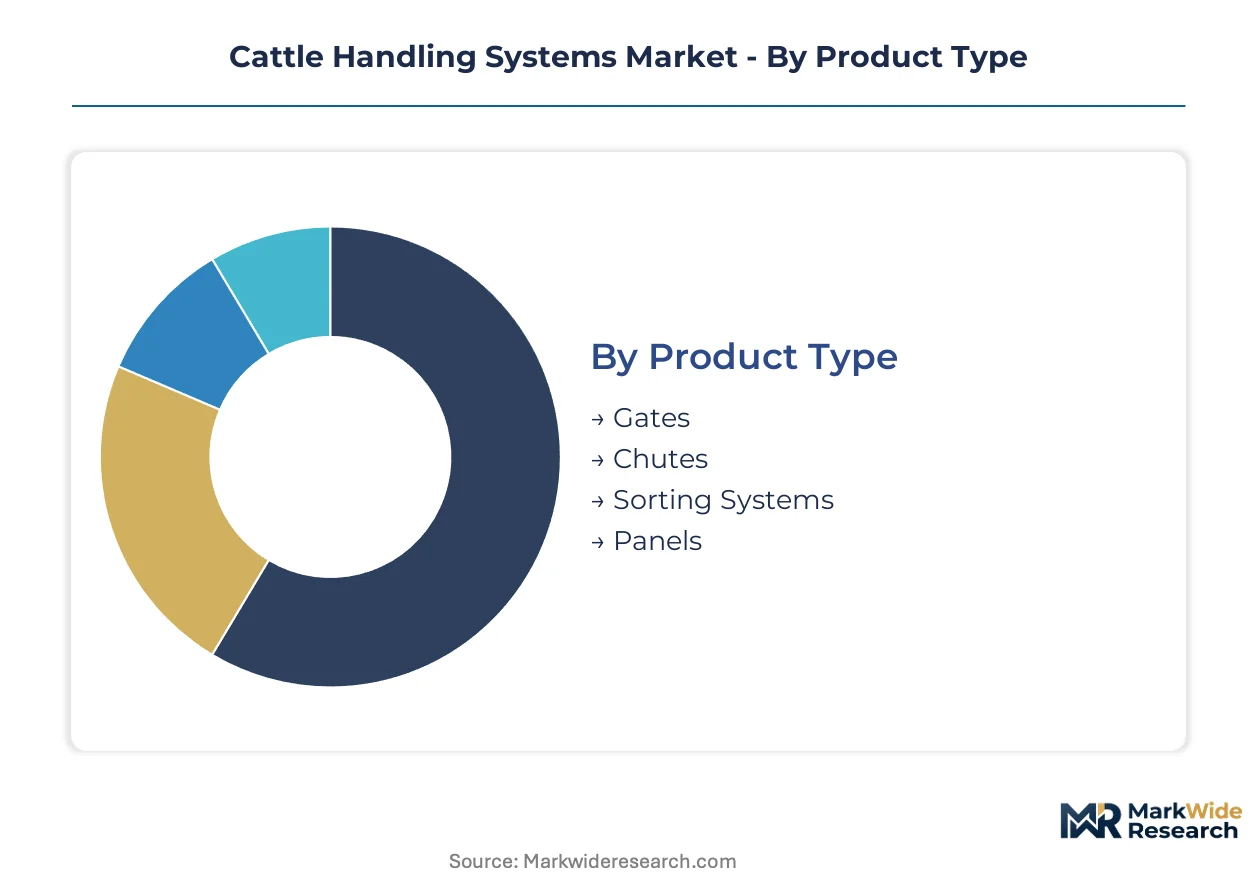
Procurement teams in large commercial feedyards bundle purchases across multiple product categories, forcing suppliers to demonstrate interoperability across gates, chutes, and digital systems. Segmentation clarity enables buyers to match capital deployment intensity with operational scale and regulatory exposure.
Product Type:
Steel fabrication capabilities determine which fabricators can compete for high-volume gate and chute contracts versus accessory-only supply.
- Gates:Tubular steel swing and slide configurations incorporate adjustable latches and spring-loaded hinges for high-traffic alley control. Demand concentrates in Texas Panhandle feedlots expanding covered working facilities to satisfy USDA FSIS processor audit protocols.
- Chutes:Squeeze mechanisms with hydraulic or manual head gates direct livestock flow while limiting handler injury risk; V-side designs prevent leg injuries under tightening OSHA agricultural workplace standards. Growth tilts toward units integrating load-cell scales for real-time weight capture in precision feeding programs.
- Sorting Systems:Alley-width adjusters and directional gates enable rapid cattle flow separation without complete system redesign.
- Panels:Corral perimeter construction from galvanized tubular frameworks provides modular pen configuration flexibility for seasonal operations.
Volume sits with Gates; growth tilts toward Chutes.
Technology:
Labor availability thresholds at individual operations dictate automation investment timing and technology tier selection.
- Manual:Lever-operated squeeze mechanisms and physical alley gates retain dominance among small-to-mid operations with stable workforce availability. Replacement inertia persists despite efficiency disadvantages.
- Semi-Automatic:Hydraulic assist for head gates and powered alley directional controls reduce handler physical strain while preserving operational oversight. Dairies in the Upper Midwest deploy these configurations to manage throughput without full automation capital commitment.
- Fully Automatic:Sensor-activated entry, hydraulic squeeze, and integrated scale systems achieve throughput exceeding 150 head per hour. Labor scarcity in large commercial feedlots accelerates displacement of manual alternatives.
- Remote-Controlled:Wireless operator positioning outside the chute envelope addresses OSHA inspection priorities for facilities employing more than fifty workers.
Manual technology holds the installed base; fully automatic configurations are climbing the fastest.
End User:
Regulatory audit intensity varies sharply across end-use segments, concentrating premium equipment demand where processor compliance pressure is highest.
- Dairies:Milking parlor throughput requirements and animal welfare audit protocols from major cooperatives drive investment in quiet-hydraulic chute designs that reduce bovine stress indicators.
- Beef Farms:Commercial feedlots in the Texas-Oklahoma-Kansas corridor face compressed procurement timelines as covered facility construction accelerates to meet packer audit requirements.
- Research Facilities:Universities and veterinary institutions require precision restraint for data collection and pharmaceutical testing protocols.
- Livestock Shelters:Municipal and nonprofit operations prioritize handler safety features given limited staff training resources and liability exposure.
Beef farms dominate capital deployment; dairies show the steepest expansion trajectory for automatic system substitution.
Installation:
Foundation requirements and deployment speed create distinct buyer segments with opposing capital intensity preferences.
- On-Farm:Site-fabricated configurations using local welding contractors reduce transportation costs for remote ranch operations with irregular throughput needs.
- Mobile:Skid-mounted or trailer-based corral systems deploy without concrete curing delays, serving contract grazers and seasonal backgrounding operations in the Great Plains.
- Permanent:Concrete-anchored chutes and fixed alley layouts capture the largest value share given infrastructure durability and integration with facility-wide processing workflows.
- Temporary:Panel-based portable enclosures assemble for branding or veterinary events without permanent site modification.
Permanent installation anchors revenue; mobile systems are gaining share fastest among non-traditional operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in North American steel fabrication centers while consumption patterns track cattle density corridors and regulatory enforcement intensity across distinct national markets.
United States
Commercial feedlots in the Texas-Oklahoma-Kansas corridor drive capital equipment procurement as USDA FSIS humane handling audits tighten. OSHA agricultural workplace standards now mandate anti-backup features and emergency release mechanisms for facilities employing more than fifty workers. Amarillo and Dodge City anchor yard construction activity as covered working facilities expand to satisfy processor compliance protocols.
Canada
Prairie province cattle operations invest in mobile handling configurations to serve contract grazing and seasonal backgrounding needs. Health Canada veterinary equipment guidelines influence restraint mechanism specifications for export-oriented beef producers. Alberta's feedlot corridor between Lethbridge and Brooks generates concentrated demand for high-throughput hydraulic chute systems.
Australia
Extensive pastoral operations in Queensland and Western Australia prioritize portable corral systems given remote station locations and irregular mustering schedules. The country's national agricultural safety regulator enforces handler injury prevention standards that shape gate and alley design requirements. Roma and Dalby serve as distribution nodes for equipment serving the northern beef supply chain.
Brazil
Large-scale integrated beef operations in Mato Grosso and Goiás accelerate automation adoption as labor availability tightens in frontier agricultural zones. ANVISA pharmaceutical oversight of veterinary drug administration protocols influences precision restraint requirements for pharmaceutical testing. The Sorriso-Sinop corridor represents the fastest-growing regional market for semi-automatic handling configurations.
Germany
Dairy cooperatives in Lower Saxony and Bavaria deploy quiet-hydraulic chute designs to satisfy animal welfare audit protocols from major milk processors. EU machinery directives and CE marking requirements condition equipment import specifications for North American manufacturers. The Münsterland dairy cluster generates specialized demand for integrated scale systems supporting precision feeding programs.
Cattle Handling Systems Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base organizes around fabrication scale, geographic coverage density, and technology integration depth rather than consolidated national dominance. Three archetypes predominate: in-house steel fabricators with captive supply chains, regional specialists serving custom-engineered projects, and technology-forward developers converging digital systems with hydraulic equipment. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement teams consolidate supplier relationships.
Among North American fabricators, Priefert Manufacturing and Arrowquip occupy positions at opposite ends of the technology-integration spectrum, with MJE Livestock Equipment anchoring the custom-engineered tier for commercial feedyard applications. Priefert exemplifies the in-house fabrication archetype through extensive dealer network coverage. Arrowquip represents the premium technology vector converging digital scale integration with equipment design. MJE sits within the specialized project segment serving high-throughput configurations requiring site-specific engineering.
| Leading Market Players |
|---|
| MJE Livestock Equipment |
| Priefert Manufacturing |
| Arrowquip |
| Bison Industries |
| Behlen Country |
| D-S Livestock Equipment |
| Powder River |
| TUFF BUILT |
| Hi-Hog Farm & Ranch Equipment |
| Others |
Value Chain & Pricing Dynamics
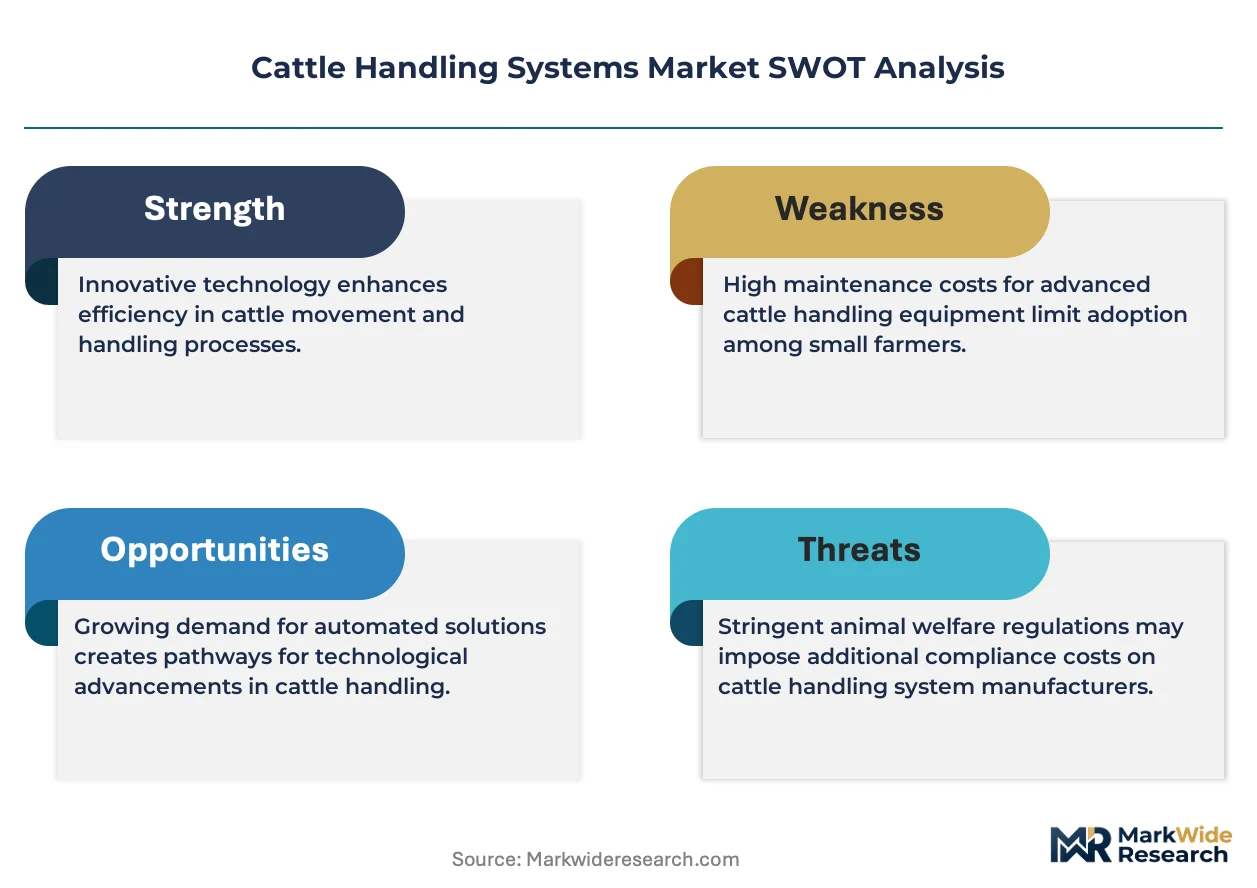
Galvanized steel tubular framework costs cascade through three distinct pricing tiers as scrap metal and zinc volatility compress fabrication margins at the premium hydraulic-chute tier while contract grazers at the economy mobile-system tier absorb transport premiums from Great Plains distribution nodes.
Pricing Analysis
Margin tightening in premium hydraulic chutes reflects ISO 10954 certification investment and digital scale integration costs. Three-tier pricing structure across premium, standard, and economy levels separates quiet-hydraulic systems with load-cell convergence from manual lever-operated alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Small-to-mid operations exhibit highest price sensitivity, resisting replacement despite efficiency gaps, while large commercial feedlots prioritize throughput over unit cost.
Supply Chain Analysis
Welding certification scarcity in Texas and Oklahoma steel fabrication centers constrains production scaling for regional manufacturers seeking AWS-certified labor pools. Supply concentrates in the United States, Canada, and Australia, drawing from galvanized steel coil, hydraulic actuator components, and precision load-cell instrumentation. Single-source vulnerability sits with specialized hydraulic valve suppliers serving automated chute architectures. Distribution runs through captive dealer networks across the US Plains, with Amarillo and Dodge City anchoring parts availability for commercial feedlot procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle handling systems sector is consolidating around captive steel fabrication and proprietary dealer territory control as incumbents race to secure upstream raw material sourcing and downstream service coverage.
For Market Incumbents: Deploy captive welding certification programs to lock in fabrication capacity before AWS-qualified labor pools tighten further. Expand hydraulic component inventory depth at Amarillo and Dodge City distribution nodes to preempt parts-availability disqualification from large feedlot bundling contracts. Labor scarcity in rural fabrication zones and procurement consolidation among Texas-Oklahoma-Kansas yard operators threaten margin compression without vertical integration into steel coil sourcing. For New Entrants and Emerging Players: Contract grazers and seasonal backgrounding operations in the Great Plains represent the most penetrable buyer archetype, currently underserved by permanent-installation-focused incumbents. Skid-mounted corral configurations without concrete foundation requirements address deployment speed gaps. Digital scale integration partnerships with precision-feeding software providers offer a go-to-market angle distinct from legacy fabricators. For Investors and Strategic Acquirers: USDA FSIS audit enforcement acceleration is the leading indicator that capital replacement cycles will compress ahead of traditional equipment lifespans, favoring manufacturers with compliant product portfolios already positioned. Long-term viability rests on fabrication scale and dealer density rather than technology differentiation alone. Acquisition targets should demonstrate captive steel processing and established service territories in the Texas Panhandle. Watch for major beef packer welfare audit protocol publication as the signal triggering preemptive yard equipment upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Sourcing | Captive galvanized steel supply insulates margin from scrap metal and zinc price spikes. |
| Dealer Network Expansion in US Plains | Territory density in Amarillo-Dodge City corridor secures large feedlot bundling contract eligibility. |
| Quiet-Hydraulic Product Line Development | Reduced noise emission designs preempt major beef packer welfare audit mandates ahead of regulatory action. |
| Mobile System Platform Launch | Skid-mounted configurations capture contract grazer demand without permanent foundation capital barriers. |
| Digital Scale Integration Partnership | Load-cell convergence with hydraulic chutes enables real-time weight data for precision feeding programs. |
Study Parameters
USDA enforcement bulletins, OSHA agricultural workplace standards, and ISO livestock equipment documentation formed the secondary backbone, cross-referenced with customs records tracking galvanized steel tubular framework trade flows. Primary interviews with feedlot procurement directors, hydraulic equipment engineers, and AWS-certified welding contractors validated secondary findings. Bottom-up equipment shipment estimates and top-down cattle inventory projections were triangulated to anchor market sizing.
Historical trendline analysis across the projection horizon modeled technology substitution rates from manual to fully automatic systems. Segmentation dimensions included product architecture, automation tier, end-use intensity, and installation permanence. CAGRs were derived from equipment replacement cycle compression and regulatory audit timeline acceleration. Forecast inputs incorporated cattle herd density shifts in the Texas-Oklahoma-Kansas corridor and labor availability indices for rural fabrication zones.
Revisions become necessary when galvanized steel price volatility exceeds historical bands, USDA FSIS enforcement priorities shift, or major beef packer welfare audit protocols introduce specifications diverging from current equipment standards. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
China Horse Riding Equipment Market