
 China Office Furniture Market | 2026-2036
China Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
China Office Furniture Market Analysis
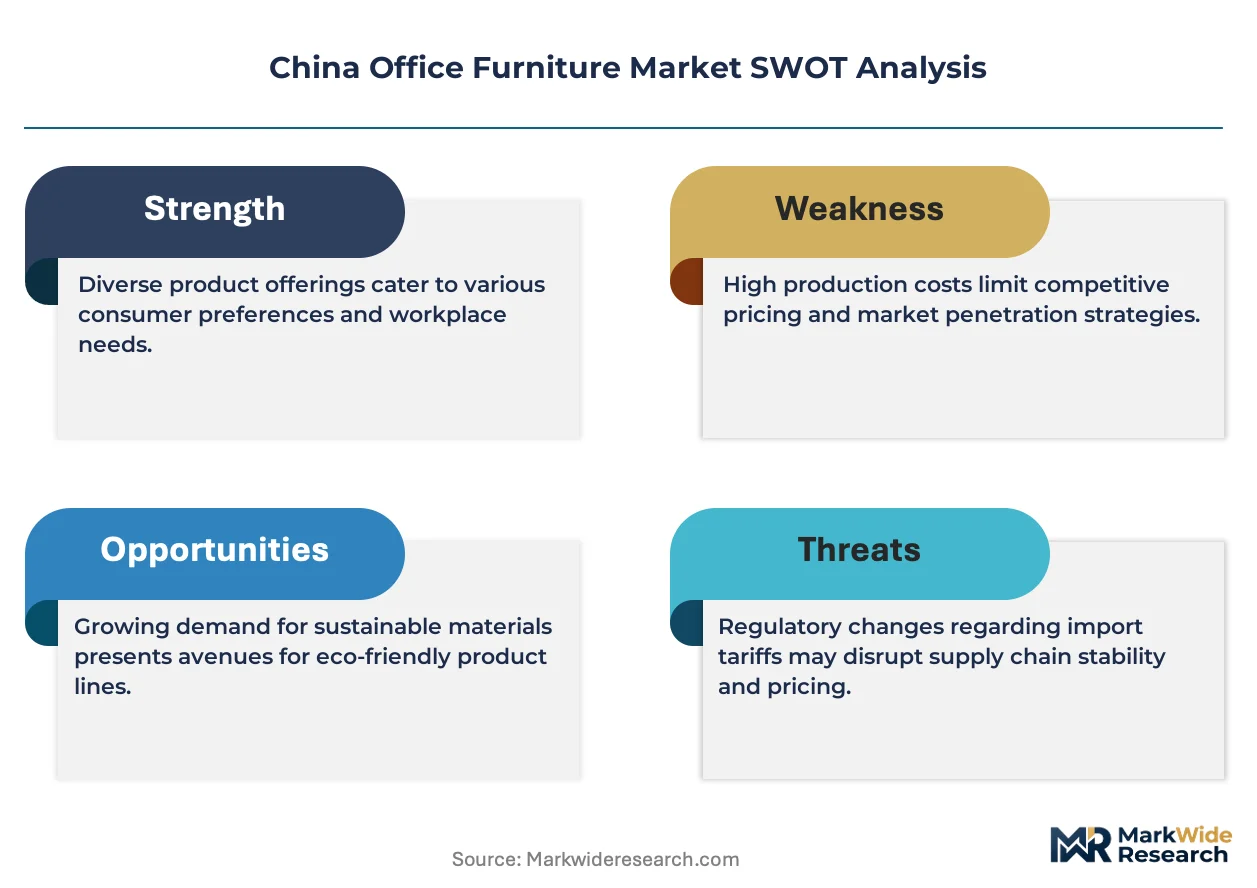
GB/T 39600-2021 formaldehyde emission grading for wood-based panels is collapsing the supplier base for domestic manufacturers seeking premium positioning. Sunon Group leverages captive laminate production to sustain margin control across its seating and systems lines. Lamex Office Furniture anchors its position through Hong Kong-origin design credentials that differentiate its offerings in tier-one commercial towers. Henglin Home Furnishings competes on vertical integration into particleboard and veneer sourcing.
Office furniture encompasses workstations, seating, storage systems, and partition solutions engineered for commercial productivity environments, typically fabricated from engineered wood substrates, steel frames, and polymer components with load-bearing specifications tested to GB/T 10357 standards. The primary purpose is to organize human workflow density while supporting ergonomic posture over eight-hour use cycles. Ergonomic seating commands the deepest margin pool as corporations absorb premium pricing for adjustable lumbar and mesh-back configurations. Metal-framed desking is accelerating fastest among SME fit-outs seeking durability at lower per-unit cost. Wood-dominant traditional styling occupies a shrinking but defensible niche in government procurement channels.
SAMR enforces product quality certification under CCC-marking protocols for metal and glass furniture, while MEE implements dual carbon goals that constrain VOC-emitting coating processes in the Pearl River Delta manufacturing cluster. MIIT's industrial standard updates for smart office integration are beginning to shape R&D allocation toward sensor-embedded workstations. Stakeholders must monitor whether GB standard harmonization with ISO 21016 will open export pathways or erect new compliance barriers for domestic producers.
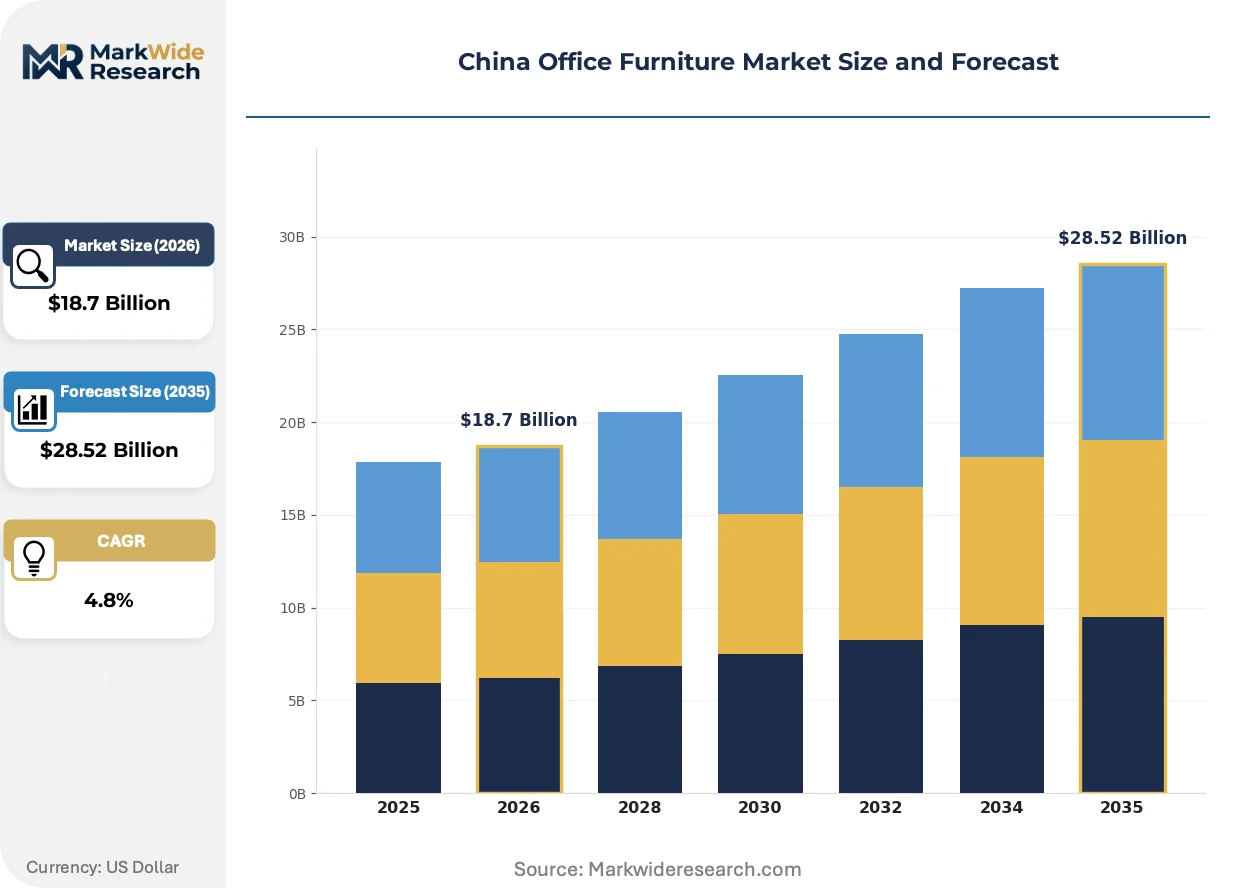
Market Dynamics
GB/T 39600-2021 formaldehyde emission standards are compressing the supplier base for domestic manufacturers while technology firms in Shenzhen and Hangzhou accelerate workspace refurbishment cycles, creating simultaneous cost pressure and demand expansion.
Growth Catalysts
- Dual carbon goals enforcement:MEE constraints on VOC-emitting coating processes in the Pearl River Delta are driving capital investment into cleaner production lines that qualify for green procurement tenders.
- Smart office integration mandate:MIIT industrial standard updates for sensor-embedded workstations are redirecting R&D allocation toward IoT-capable furniture systems in Yangtze River Delta manufacturing clusters.
- Technology sector fit-out surge:Shenzhen and Hangzhou technology firms are compressing refurbishment cycles to eighteen-month intervals, generating recurring demand for ergonomic seating and modular workstation systems.
Market Restraints
- Particleboard input cost volatility:Domestic wood-based panel pricing fluctuates with imported softwood pulp exposure, squeezing margin predictability for systems furniture producers.
- Supplier base concentration:GB/T 39600-2021 E0-grade certification has eliminated over half of legacy laminate suppliers, creating single-source risk for premium positioning manufacturers.
- Steel frame substitution pressure:Metal-framed desking from SME-focused producers is capturing price-sensitive segments that previously specified engineered wood substrates.
Strategic Opportunities
- Sensor-embedded workstation convergence:Integration of occupancy sensors with height-adjustable desking creates premium positioning for manufacturers with MIIT-compliant smart office credentials.
- Hong Kong-origin design arbitrage:Design credentials from Hong Kong studios differentiate offerings in tier-one commercial towers where multinational tenant standards apply.
- Government procurement channel:Wood-dominant traditional styling retains defensible volume in state procurement channels where aesthetic conventions persist despite private sector shifts.
Industry Challenges
- CCC-marking timeline compression:SAMR product quality certification protocols for metal and glass furniture impose six-to-nine month approval windows that delay new product launches.
- Smart-legacy system integration:Sensor-embedded workstations face compatibility friction with existing building management systems in older commercial tower stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Office Furniture Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Storage Units, Cubicles Material: Wood, Metal, Plastic, Glass End User: Corporations, SMEs, Government, Educational Institutions Design Style: Modern, Traditional, Ergonomic, Minimalist |
| Companies Covered | Sunon Group, Lamex Office Furniture, Henglin Home Furnishings, Huasheng Furniture, QUAMA Office Furniture, Dious Furniture, Onlead Office Furniture, Aurora Office Furniture, Zhongtai Furniture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Office Furniture Market Emerging Trajectories
Workspace technology is compressing hardware footprints while regulatory pressure on material emissions intensifies, reshaping both product architecture and supply chain configuration.
Sensor-embedded height-adjustable desking is miniaturizing control modules to under-desk footprints that preserve aesthetic minimalism. Technology sector buyers in Shenzhen and Hangzhou specify these configurations for open-plan density optimization. The technology is miniaturizing mechanical components into slim-profile bases that accommodate cable management without bulk.
GB/T 39600-2021 formaldehyde emission grading is collapsing the domestic supplier base for E0-grade laminates. Manufacturers with captive particleboard production sustain margin control while competitors face sourcing instability. Premium positioning producers are responding by securing long-term supply agreements with certified panel mills or integrating backward into substrate production.
Corporate facility managers are unbundling furniture procurement from general contractor fit-out packages. Direct manufacturer relationships are displacing distributor intermediaries in technology sector accounts with standardized specifications. This pattern concentrates in Hangzhou and Shenzhen where procurement teams maintain dedicated furniture specification staff.
China Office Furniture Market Segmentation
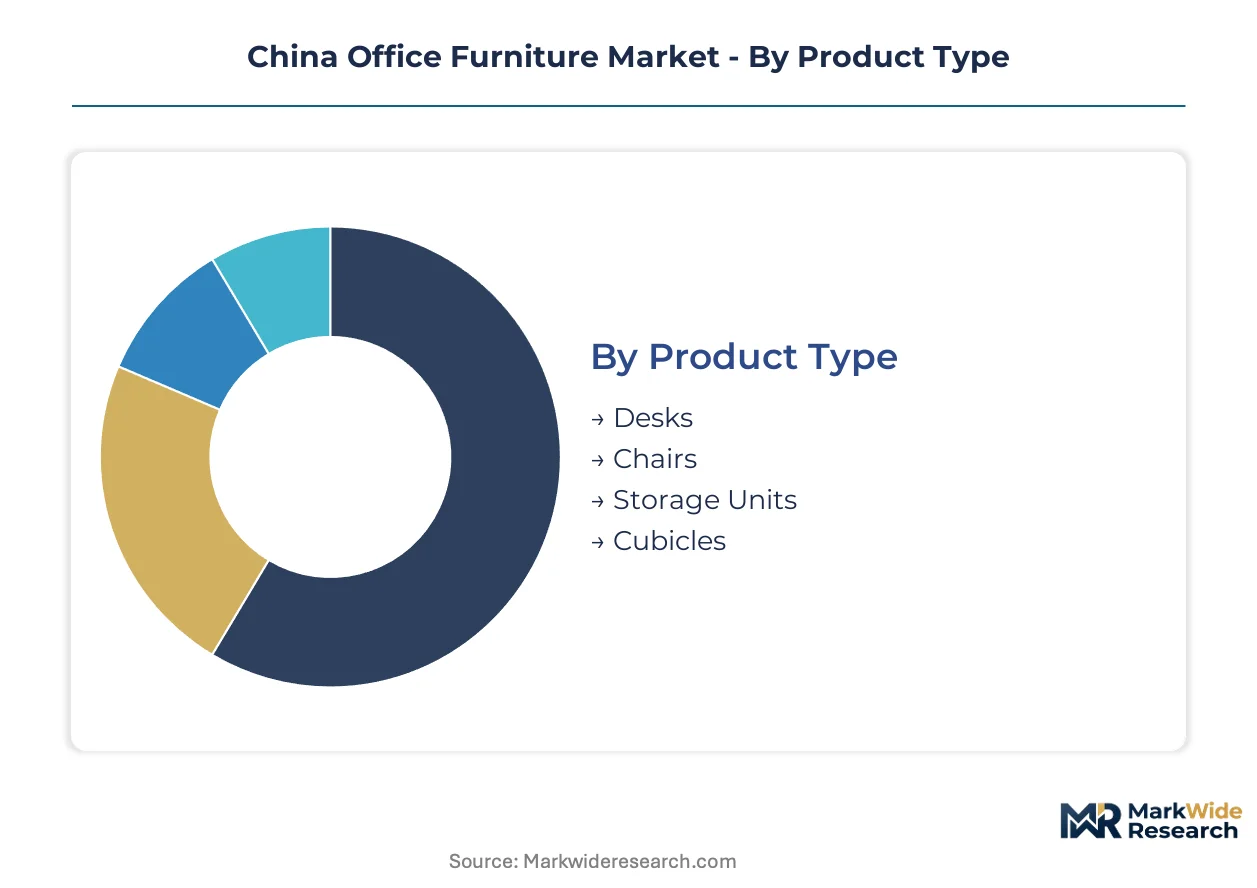
Segmentation in China's office furniture market reveals how procurement channels fragment across customer sophistication levels. Technology firms in Shenzhen and Hangzhou route premium ergonomic specifications through direct manufacturer relationships, while government and educational channels retain traditional distributor networks.
Product Type:
Channel concentration varies sharply by product category, with ergonomic seating and modular systems flowing through specification-driven direct sales while storage and basic desking move through contractor bundles.
- Desks:Height-adjustable and fixed-height configurations fabricated from engineered wood substrates, steel frames, or hybrid constructions. Demand concentrates in Yangtze River Delta technology corridors where eighteen-month refurbishment cycles from Hangzhou and Shenzhen firms prioritize cable-integrated, sensor-embedded surfaces.
- Chairs:Ergonomic seating with adjustable lumbar, mesh-back, and synchronized tilt mechanisms commands the deepest margin pool in the market. Corporations absorb premium pricing for eight-hour posture support, with procurement teams in tier-one commercial towers specifying Hong Kong-origin design credentials.
- Storage Units:Filing cabinets, shelving systems, and mobile pedestals fabricated from metal or engineered wood. Government procurement channels sustain volume for wood-dominant traditional styling despite private sector shifts toward metal-framed durability.
- Cubicles:Partition-based workstation systems with acoustic dampening and integrated power delivery. SME fit-outs in secondary cities drive metal-framed substitution pressure that captures price-sensitive segments away from engineered wood substrates.
By volume, storage units lead through government and educational channel density. By growth pace, ergonomic chairs are climbing the fastest on technology sector specification upgrades.
Material:
Cost tier stratification separates premium positioning from mass-market competition, with certification-grade substrates commanding supply premiums and steel capturing SME price sensitivity.
- Wood:Engineered wood substrates including particleboard, MDF, and veneer laminates graded to GB/T 39600-2021 E0 formaldehyde standards. Captive particleboard production at integrated manufacturers sustains margin control while competitors face sourcing instability from collapsed supplier bases.
- Metal:Steel and aluminum framing for desking, seating bases, and storage systems. SME-focused producers accelerate metal-framed desking adoption by offering durability at lower per-unit cost than wood-dominant alternatives.
- Plastic:Polymer components for chair shells, cable management, and accent elements. Injection-molded parts enable aesthetic minimalism in open-plan density optimization for technology sector buyers.
- Glass:Tempered glass surfaces for executive desking and meeting tables. SAMR CCC-marking protocols impose six-to-nine month approval windows that delay new product launches for metal and glass furniture categories.
By installed base, engineered wood dominates. By specification momentum, metal framing is gaining share fastest on SME procurement patterns.
End User:
Customer type determines pricing power and procurement sophistication, with multinational-tenant commercial towers operating on design credential differentiation while state channels retain aesthetic conventions.
- Corporations:Large enterprises with dedicated facility management and furniture specification staff. Direct manufacturer relationships are displacing distributor intermediaries in technology sector accounts with standardized ergonomic requirements.
- SMEs:Small and medium enterprises prioritizing durability at lower per-unit cost. Metal-framed desking from price-focused producers captures this segment through contractor bundle procurement.
- Government:State procurement channels where wood-dominant traditional styling retains defensible volume despite private sector shifts toward modern and ergonomic configurations.
- Educational Institutions:Universities and training facilities with budget-constrained, high-durability requirements. Basic metal-framed desking and storage systems dominate this channel through centralized purchasing frameworks.
By contract value, corporations lead. By procurement reform velocity, educational institutions are expanding most quickly on facility modernization programs.
Design Style:
Application context drives style selection, with productivity-focused environments specifying ergonomic and minimalist configurations while formal reception and executive spaces retain traditional references.
- Modern:Clean-lined configurations with neutral palettes and integrated technology accommodation. Technology firms in Shenzhen and Hangzhou specify modern styling for open-plan density optimization with sensor-embedded workstations.
- Traditional:Wood-dominant aesthetics with classical proportion and veneer prominence. Government procurement channels sustain this style where aesthetic conventions persist despite private sector shifts.
- Ergonomic:Human-centered design prioritizing adjustable support, task movement, and eight-hour posture accommodation. Corporations absorb premium pricing for this style in seating and height-adjustable desking categories.
- Minimalist:Reduced visual mass, concealed hardware, and monochromatic finishes. Hong Kong-origin design credentials differentiate minimalist offerings in tier-one commercial towers where multinational tenant standards apply.
By specification frequency, modern styling leads. By positioning premium, ergonomic design commands the steepest expansion trajectory on workplace health program adoption.
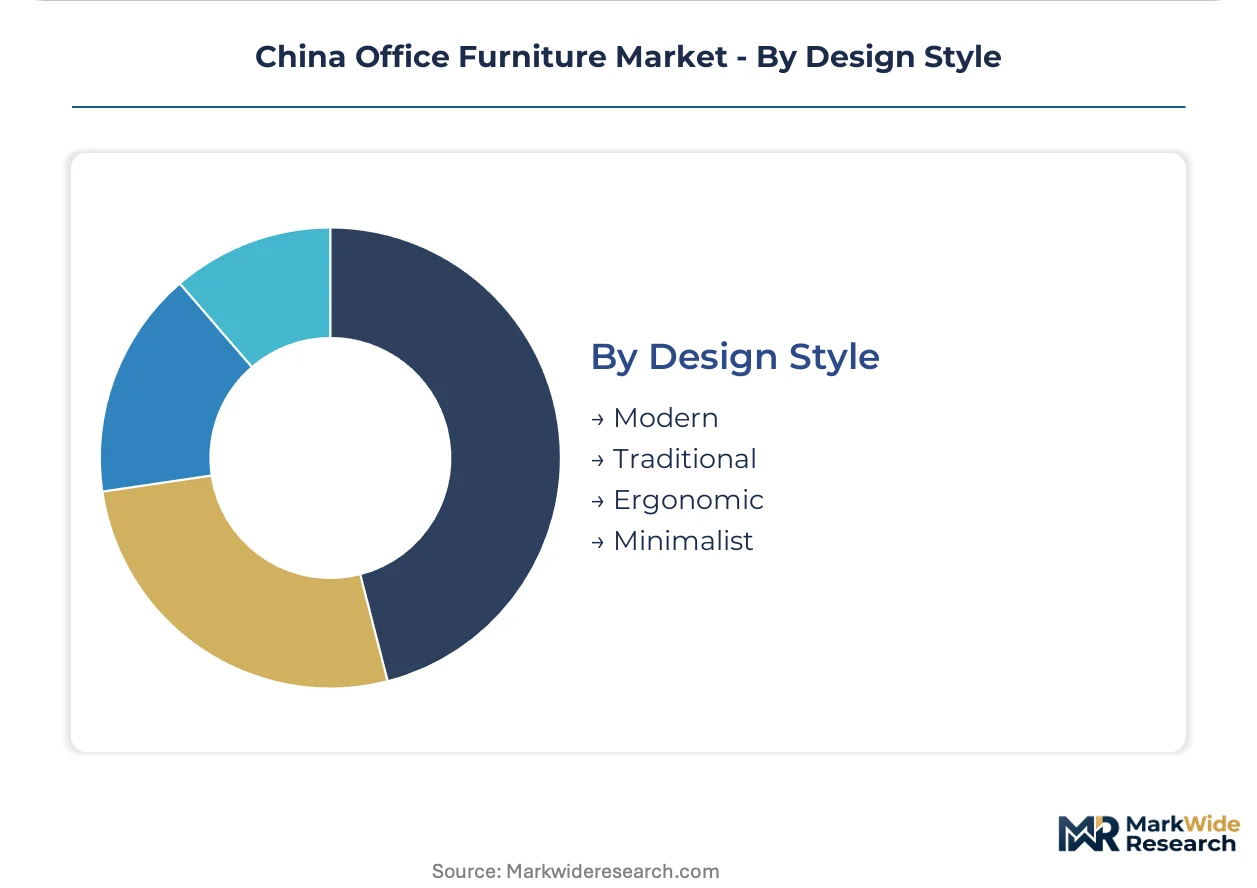
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement teams concentrate in coastal manufacturing corridors where technology sector refurbishment cycles drive specification velocity. Provincial industrial policies and municipal carbon targets reshape production geography.
Yangtze River Delta
Hangzhou technology firms compress refurbishment cycles to eighteen-month intervals, generating recurring demand for ergonomic seating. MIIT smart office integration standards redirect R&D toward sensor-embedded workstations. Shanghai commercial towers anchor specification-driven procurement for Hong Kong-origin design credentials.
Pearl River Delta
Shenzhen technology campuses prioritize open-plan density optimization with minimalist workstation configurations. MEE dual carbon goals constrain VOC-emitting coating processes, forcing capital investment into cleaner production lines. Dongguan manufacturing clusters supply metal-framed desking to SME fit-outs seeking durability at lower per-unit cost.
Beijing-Tianjin-Hebei
Government procurement channels sustain volume for wood-dominant traditional styling despite private sector shifts. GB/T 39600-2021 formaldehyde emission grading eliminates uncertified laminate suppliers from state tender eligibility. Langfang furniture industrial zones consolidate particleboard production for premium positioning manufacturers.
Sichuan-Chongqing
Educational institution modernization programs expand procurement of basic metal-framed desking and storage systems. Western China development initiatives channel infrastructure investment into facility upgrades. Chengdu manufacturing bases serve interior markets with cost-focused production configurations.
Shandong Peninsula
Wood-based panel production clusters face imported softwood pulp cost volatility that squeezes margin predictability. Provincial environmental inspections accelerate consolidation among uncertified substrate producers. Qingdao port logistics support export-oriented manufacturers seeking ISO 21016 harmonization pathways.
China Office Furniture Market Vendor Landscape
Player mix skews toward vertically integrated domestic specialists with captive substrate production. The supplier base compresses as GB/T 39600-2021 certification eliminates legacy laminate providers. Three archetypes dominate: integrated manufacturers controlling particleboard supply, design-credential players leveraging Hong Kong studio associations, and metal-focused producers capturing SME price sensitivity. Competitive moves concentrate on backward integration into certified panel mills and direct procurement relationships displacing distributor intermediaries.
Among integrated specialists, Sunon Group and Henglin Home Furnishings exemplify the captive production archetype that sustains margin control amid sourcing instability. Lamex Office Furniture occupies a position anchored through Hong Kong-origin design differentiation in tier-one commercial towers. These three represent the strategic spectrum from upstream supply control to specification-driven premium positioning.
| Leading Market Players |
|---|
| Sunon Group |
| Lamex Office Furniture |
| Henglin Home Furnishings |
| Huasheng Furniture |
| QUAMA Office Furniture |
| Dious Furniture |
| Onlead Office Furniture |
| Aurora Office Furniture |
| Zhongtai Furniture |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Pearl River Delta laminate mills shapes both supply concentration and price floors for domestic manufacturers competing on GB/T 39600-2021 E0-grade certification. Scale advantages among integrated producers with captive particleboard operations translate into margin insulation that smaller competitors cannot replicate without backward integration into certified substrate production.
Pricing Analysis
Cost-plus contracts with softwood pulp indexation dominate raw material procurement for engineered wood substrate producers, passing through commodity volatility to systems furniture manufacturers. Pricing stratifies across E0-certified premium positioning, E1-grade standard offerings, and uncertified economy tiers driven by formaldehyde compliance grade and volume scale. Pricing pressure stems from metal-framed desking substitution in SME segments that previously specified wood-dominant alternatives. Government procurement channels exhibit lowest price sensitivity due to aesthetic convention requirements, while technology sector buyers absorb premiums for ergonomic and sensor-embedded configurations.
Supply Chain Analysis
Inventory cycles extending twelve to sixteen weeks for imported softwood pulp create lead-time vulnerability for non-integrated manufacturers lacking captive particleboard supply. Manufacturing concentrates in China, with secondary sourcing from Malaysia and Vietnam for veneer laminates and metal component stamping. The supply chain draws from engineered wood substrates, steel framing, and polymer components while facing single-source risk from GB/T 39600-2021 supplier base compression. Distribution runs through direct manufacturer relationships displacing distributor intermediaries in technology sector accounts, alongside traditional contractor-bundle channels for government and educational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT smart office integration standards are accelerating technology-cycle disruption, compressing product obsolescence timelines and rewarding manufacturers with sensor-embedded workstation capabilities.
For Market Incumbents: Shield margin position by securing long-term E0-grade laminate supply agreements or integrating backward into certified particleboard production before supplier base compression eliminates sourcing alternatives. Accelerate MIIT-compliant smart office credential acquisition to defend against sensor-embedded workstation entrants from adjacent technology sectors. For New Entrants and Emerging Players: Lead with metal-framed desking configurations targeting SME fit-outs in secondary cities where price sensitivity and durability requirements favor steel over engineered wood substrates. Penetrate the Sichuan-Chongqing educational institution modernization channel through centralized purchasing frameworks with basic storage and desking specifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive substrate production and established GB/T 39600-2021 certification. Long-term viability hinges on smart office integration capabilities and direct procurement relationships with technology sector accounts. Watch for MIIT standard harmonization with ISO 21016 as signal for export pathway expansion or new compliance barrier formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Panel Production | Captive E0-grade supply insulates margin control from GB/T 39600-2021 supplier base compression. |
| Smart Office Credential Acquisition | MIIT-compliant sensor-embedded workstations unlock technology sector procurement in Hangzhou and Shenzhen. |
| Direct Manufacturer Relationship Development | Bypassing distributor intermediaries captures specification-driven technology sector accounts with standardized ergonomic requirements. |
| Metal-Framed Product Line Expansion | Steel desking configurations penetrate SME price-sensitive segments away from engineered wood competition. |
| Hong Kong Design Studio Partnership | Origin credentials differentiate offerings in tier-one commercial towers with multinational tenant standards. |
Methodological Framework
Desk research of customs trade databases, GB standards documentation, and provincial industrial policy filings preceded structured interviews with furniture procurement managers at technology firms, facility management directors at commercial tower operators, manufacturing executives at integrated producers, and regulatory affairs specialists at SAMR certification bodies. Primary fieldwork combined with secondary validation across MIIT industrial standard updates, MEE environmental compliance records, and Pearl River Delta manufacturing cluster surveys. Bottom-up demand modeling triangulated against top-down production capacity estimates.
Variance decomposition across product type, material grade, end-user channel, and design style dimensions informed volume and value outputs over the projection horizon. CAGRs derived from weighted average of historical trajectory analysis and forward-looking capacity expansion schedules. Forecast inputs incorporated technology sector refurbishment cycle compression, GB/T 39600-2021 certification penetration curves, and smart office integration adoption rates.
Forecasts assume regulatory continuity in SAMR product certification protocols and MEE dual carbon enforcement regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
UAE Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
India Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Office Seat Cushion Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Rental Furniture Market