
 Durometers Market | 2026-2036
Durometers Market Size, Share, and Industry Trends Forecast 2026-2036
Durometers Market Analytics
Durometer sourcing is rebalancing from single-source OEM relationships toward multi-vendor qualification programs. Mitutoyo leverages its metrology heritage to anchor premium digital Shore instrument demand in Japanese automotive supply chains. Zwick Roell competes through materials testing system integration, extending its hardness platform into full mechanical characterization workflows. Elcometer differentiates by controlling coastal distribution networks for portable durometers serving marine coating inspectors.
A durometer measures material hardness through standardized indentation resistance, typically quantified via Shore, Rockwell, Barcol, or Vickers scales with defined spring forces and indenter geometries. Shore durometers dominate polymer and elastomer testing floors due to ASTM D2240 ubiquity across automotive seal and tire plants. Digital durometers capture expanding share from analog units as quality control labs mandate data logging and SPC connectivity; portable configurations lead aerospace MRO tarmacs where field hardness verification prevents fastener galling. Analog durometers retain stubborn presence in educational facilities where calibration simplicity outweighs feature density.
FDA 21 CFR Part 820 governs medical device durometer validation for silicone implant hardness consistency, while ISO 17025 accreditation pressures third-party labs toward traceable Rockwell and Vickers calibration chains. ASTM D2240 and DIN 53505 divergence in Shore scale interpretation creates compliance friction for multinational rubber compounders operating across US and European specifications. Stakeholders must monitor evolving MDR documentation demands in Europe, where durometer traceability now feeds into broader material master data systems for implantable device submissions.
Market Dynamics
Automotive OEMs are consolidating Shore hardness validation protocols across tiered supply chains, forcing instrument vendors to align calibration traceability with ISO 17025 and DIN 53505 simultaneously. This dual-standard pressure is compressing durometer replacement cycles and elevating specification requirements for laboratory-grade units.
Growth Catalysts
- ISO 17025 Lab Accreditation Mandates:Third-party testing facilities in Germany and China face mandatory recertification deadlines, driving replacement demand for traceable Rockwell and Vickers calibration chains.
- Automotive Seal and Tire Plants:ASTM D2240 ubiquity across polymer manufacturing floors sustains baseline Shore durometer procurement even as digital units capture expanding share.
- Shenzhen and Nagoya Industrial Corridors:East Asian manufacturing cluster concentration concentrates instrument demand within high-volume electronics and precision component testing facilities.
Market Restraints
- ASTM D2240 and DIN 53505 Divergence:Interpretation friction in Shore scale calibration creates compliance overhead for multinational rubber compounders operating across US and European specifications.
- Silicone Raw Material Volatility:Medical-grade elastomer input cost swings compress margin buffers for durometer manufacturers serving FDA 21 CFR Part 820-governed implant validation markets.
- Educational Facility Analog Retention:Calibration simplicity preferences in universities and technical institutes slow digital upgrade cycles for entry-level Shore instruments.
Strategic Opportunities
- EU MDR Documentation Demands:Europe's evolving material master data requirements for implantable device submissions create durometer traceability integration opportunities with broader quality management systems.
- Aerospace MRO Field Verification:Portable digital configurations address tarmac-based fastener galling prevention needs, opening service-contract revenue streams outside traditional laboratory sales.
- Wireless SPC Connectivity:Bluetooth-enabled data logging convergence with statistical process control platforms is expanding into automotive tier-one supplier networks seeking real-time hardness monitoring.
Industry Challenges
- Multi-Vendor Qualification Complexity:Procurement teams managing durometer sourcing rebalancing from single-source OEM relationships face expanded supplier audit and calibration cross-verification workloads.
- Legacy Analog-to-Digital Migration Friction:Quality control labs with entrenched manual measurement workflows encounter technician retraining costs and temporary productivity dips during digital instrument rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durometers Market |
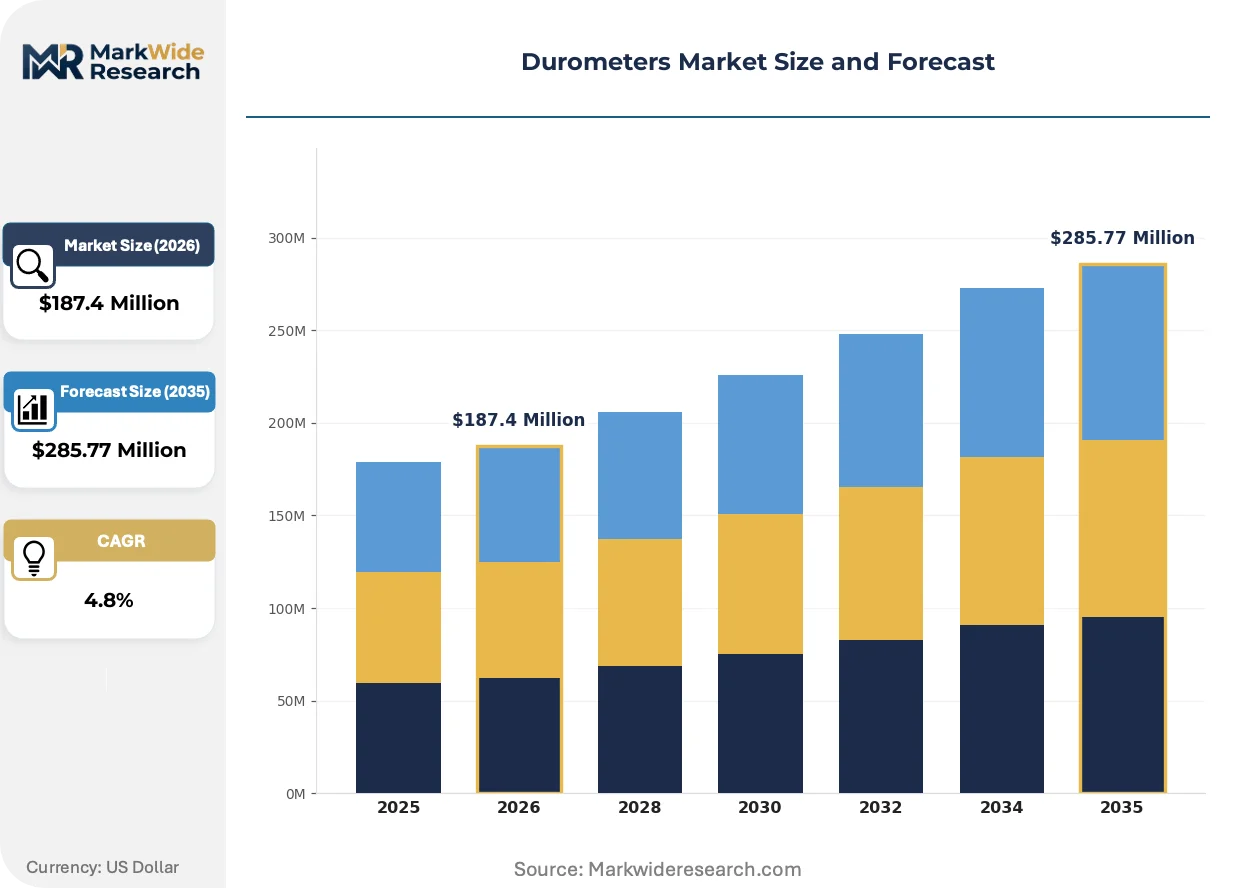
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shore Durometer, Barcol Durometer, Rockwell Durometer, Vickers Durometer Application: Automotive Components, Medical Devices, Consumer Products, Aerospace Materials Technology: Digital Durometers, Analog Durometers, Hardness Testers, Portable Durometers End User: Manufacturers, Quality Control Labs, Research Institutions, Educational Facilities |
| Companies Covered | Mitutoyo, Zwick Roell, Elcometer, Wilson, PCE Instruments, PTC Instruments, Rex Gauge, Bareiss, Struers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durometers Market Evolving Landscape
Digital instrumentation with embedded connectivity is displacing standalone analog units across hardness testing workflows. Regulatory traceability mandates and real-time quality monitoring requirements are compressing replacement timelines and elevating specification floors.
Wireless durometer systems with integrated data logging and cloud-based calibration tracking are expanding into automotive and aerospace supply chains. Tier-one suppliers in Japan and Germany are adopting these platforms to satisfy OEM real-time audit requirements. The technology is compressing traditional manual record-keeping workflows and enabling predictive maintenance scheduling for testing equipment.
Europe's MDR framework is tightening material characterization documentation for implantable silicone devices. Durometer traceability must now feed into centralized material master data systems rather than standalone test reports. German medical device manufacturers are responding by integrating hardness validation into broader ERP-embedded quality modules.
Buyer consolidation among automotive OEMs is compressing instrument vendor qualification cycles. Tiered supply chain managers now mandate multi-source durometer approval before plant-level procurement authorization. This pattern is most visible in Nagoya-centered Japanese automotive networks and Stuttgart-surrounded German supplier ecosystems.
Durometers Market Segmentation
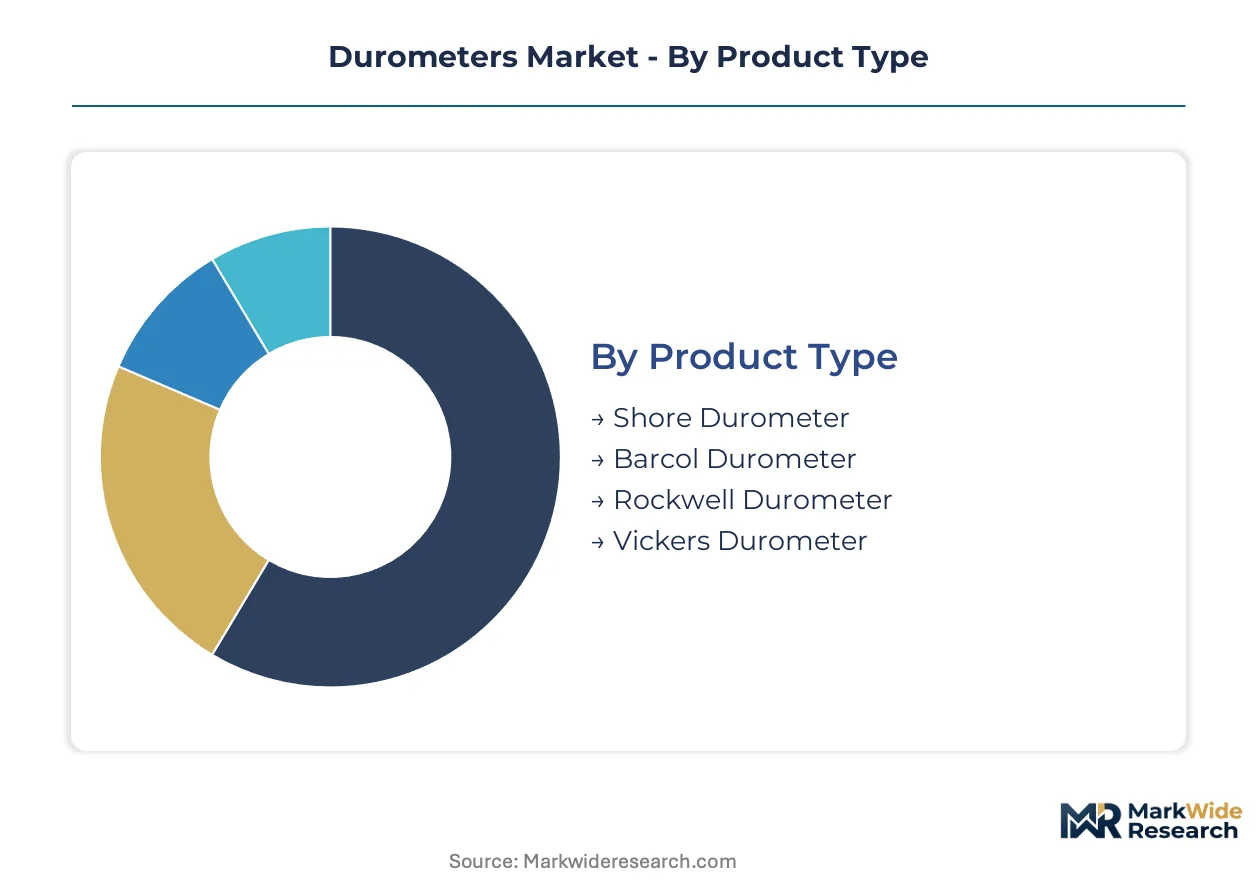
Durometer procurement decisions hinge on calibration traceability requirements, end-use regulatory burdens, and field portability needs. Buyers weigh ISO 17025 compliance against unit cost across polymer testing floors, medical device cleanrooms, and aerospace maintenance hangars.
Product Type:
Buyers select durometer scales based on material class and mandated test protocols, with Shore dominance in elastomers and Rockwell/Vickers anchoring metals and ceramics.
- Shore Durometer:Spring-loaded indenters measure elastomer hardness via Shore A, D, or OO scales. Automotive seal plants in Stuttgart and Nagoya mandate ASTM D2240-compliant Shore instruments for O-ring validation, with digital units displacing analog configurations for SPC integration.
- Barcol Durometer:A portable indentation device using a truncated cone indenter for reinforced plastics and composites. Marine coating inspectors along coastal distribution networks favor Barcol units for fiberglass hull hardness verification where laboratory access is limited.
- Rockwell Durometer:Measures permanent indentation depth under preload and major load sequences. Metals testing facilities in Germany require traceable Rockwell calibration chains under DIN EN ISO 6508 for automotive component certification.
- Vickers Durometer:Diamond pyramid indenter delivers microhardness measurements for thin sections and surface layers. Medical device manufacturers serving FDA 21 CFR Part 820-governed implant markets specify Vickers for silicone diaphragm validation.
Shore durometers lead on scale; Vickers durometers lead on momentum in medical-grade applications.
Application:
End-use sectors impose divergent specification floors, with automotive and medical driving premium instrument procurement while aerospace prioritizes portability.
- Automotive Components:Tire plants and seal manufacturers deploy Shore durometers across polymer compounding floors. OEM consolidation in Japan and Germany compresses replacement cycles as tiered suppliers dual-source calibrated instruments for audit readiness.
- Medical Devices:Silicone implant manufacturers face FDA and EU MDR documentation demands. Durometer traceability must feed ERP-embedded quality modules rather than standalone test reports, elevating specification requirements for laboratory-grade units.
- Consumer Products:Footwear and sporting goods manufacturers utilize entry-level Shore instruments for mid-market quality assurance. Educational facility procurement sustains analog unit demand where calibration simplicity outweighs connectivity features.
- Aerospace Materials:MRO tarmacs require portable digital configurations for fastener galling prevention. Field verification protocols in maintenance hangars open service-contract revenue streams outside traditional laboratory sales channels.
Automotive components lead on scale; medical devices lead on specification intensity.
Technology:
Connectivity and data logging capabilities now separate procurement tiers, with wireless SPC integration commanding premium positioning.
- Digital Durometers:Embedded microprocessors deliver direct hardness readouts with Bluetooth-enabled data logging. Tier-one automotive suppliers in Shenzhen industrial corridors adopt these platforms for real-time hardness monitoring and predictive maintenance scheduling.
- Analog Durometers:Mechanical dial indicators require operator interpretation but offer calibration simplicity. Technical institutes and universities retain analog configurations for entry-level training where feature density adds unnecessary complexity.
- Hardness Testers:Bench-mounted systems integrate durometer modules with full mechanical characterization workflows. Materials testing laboratories in China leverage these platforms for ISO 17025-accredited multi-parameter validation.
- Portable Durometers:Battery-powered handheld units enable field deployment without laboratory infrastructure. Aerospace MRO operators specify portable configurations for tarmac-based verification where equipment mobility prevents operational delays.
Digital durometers lead on adoption velocity; portable durometers lead on expansion into non-laboratory environments.
End User:
Procurement authority concentrates in quality control infrastructure, with manufacturing floors and accredited laboratories driving replacement demand.
- Manufacturers:Polymer compounders and component fabricators deploy durometers across production floors for in-process hardness verification. Multi-vendor qualification programs now precede plant-level procurement authorization in consolidated automotive supply chains.
- Quality Control Labs:Third-party testing facilities face mandatory ISO 17025 recertification deadlines in Germany and China. These entities drive replacement demand for traceable calibration chains and elevate specification floors for laboratory-grade instruments.
- Research Institutions:Materials science departments require precision hardness mapping for alloy and composite development. Grant-funded acquisitions prioritize multi-scale capability over unit cost in university laboratory settings.
- Educational Facilities:Technical training programs utilize entry-level Shore instruments for workforce development. Analog retention in these settings slows digital upgrade cycles and sustains legacy supplier relationships.
Quality control labs lead on specification intensity; manufacturers lead on procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Nagoya industrial corridors concentrate durometer procurement for electronics and precision component testing. German automotive supply chains drive laboratory-grade specification demand. East Asian manufacturing clusters anchor volume procurement while European regulatory pressure elevates calibration standards.
Germany
Automotive OEM consolidation across Stuttgart-surrounded supplier ecosystems compresses instrument replacement cycles. DIN 53505 and ISO 17025 dual-standard pressure forces tier-one suppliers toward multi-vendor qualification programs. Bavarian testing facilities drive traceable Rockwell calibration chain demand for component certification.
China
MIIT-mandated quality infrastructure investments accelerate digital durometer adoption in Shenzhen electronics corridors. GB standards alignment with international hardness protocols supports export-oriented manufacturing. Pearl River Delta precision component plants concentrate procurement for real-time SPC connectivity.
Japan
METI-backed metrology standardization reinforces Mitutoyo's domestic supply chain anchoring in Nagoya automotive networks. JIS-compliant Shore instrument specifications govern tiered supplier audit readiness. Chubu region tire and seal manufacturers sustain premium digital unit demand.
United States
FDA 21 CFR Part 820 governs medical device durometer validation for silicone implant consistency across Massachusetts and Minnesota device corridors. ASTM D2240 ubiquity sustains baseline Shore procurement in automotive polymer plants. Southeast technical institutes retain analog configurations for workforce training.
India
BIS certification requirements for testing equipment elevate specification floors in Maharashtra automotive component clusters. PLI scheme incentives for precision manufacturing expand quality control infrastructure investment. Gujarat chemical and polymer processing facilities drive entry-level Shore instrument volume.
Durometers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless connectivity and cloud-based calibration tracking. The vendor base stratifies across metrology heritage specialists, materials testing system integrators, and portable instrument distributors. Three archetypes dominate: precision measurement heritage firms, full mechanical characterization platform providers, and coastal distribution network controllers. Competitive moves concentrate on multi-vendor qualification program penetration and Bluetooth-enabled SPC integration partnerships.
Among heritage metrology specialists, Mitutoyo anchors premium digital Shore demand in Japanese automotive supply chains. Zwick Roell occupies the materials testing system integration tier, extending hardness platforms into full mechanical characterization workflows. Elcometer exemplifies coastal distribution network control for portable durometers serving marine coating inspectors. These three represent distinct competitive vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| Mitutoyo |
| Zwick Roell |
| Elcometer |
| Wilson |
| PCE Instruments |
| PTC Instruments |
| Rex Gauge |
| Bareiss |
| Struers |
| Others |
Value Network & Pricing Analysis
Silicone raw material volatility feeds through durometer manufacturing cost structures into tiered pricing stratification across laboratory-grade, industrial-grade, and educational-grade instrument categories. ASTM D2240 and DIN 53505 calibration complexity elevates premium tier pricing power for ISO 17025-accredited units serving automotive OEM validation protocols.
Pricing Analysis
Input-cost pass-through from medical-grade elastomer supply constraints compresses margin buffers for FDA 21 CFR Part 820-governed implant validation markets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited laboratory instruments from industrial floor units and entry-level educational configurations. Price differentiation hinges on certification grade and Bluetooth-enabled SPC connectivity. Pricing pressure stems from multi-vendor qualification program proliferation forcing audit-ready calibration documentation. Educational facilities exhibit highest price sensitivity; medical device manufacturers show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
MIIT-mandated local-content rules in China and METI-backed metrology standardization in Japan are reshaping component sourcing for precision measurement instrument assembly. Manufacturing concentrates in China, Japan, and Germany. Supply chains draw from specialized spring steel indenter suppliers, embedded microprocessor vendors, and calibration reference block producers. Single-source vulnerability persists in diamond pyramid indenter supply for Vickers durometers. Distribution runs through direct OEM relationships in automotive supply chains and coastal network controllers for portable marine inspection units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The durometers market reads as a late-cycle quality story where ISO 17025 accreditation mandates and EU MDR documentation demands are shifting procurement toward premium-specification laboratory-grade instruments with integrated ERP traceability.
For Market Incumbents: Extend calibration service contract portfolios to capture recurring revenue from compressed replacement cycles in automotive tier-one supplier networks. Deepen backward integration into spring-loaded indenter manufacturing to defend margin position against silicone raw material volatility. Fortify multi-vendor qualification program penetration through DIN 53505 and ASTM D2240 dual-standard certification capabilities. For New Entrants and Emerging Players: Capture aerospace MRO field verification segments where portable digital configurations address tarmac-based fastener galling prevention needs outside traditional laboratory sales channels. Target wireless SPC connectivity white space in Shenzhen industrial corridor electronics testing facilities. Pursue service-contract-first go-to-market models rather than capital equipment displacement. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented coastal distribution networks for portable durometers lack scale to meet multi-vendor qualification audit requirements. Long-term viability favors precision metrology heritage firms with captive calibration reference block production and embedded software development capabilities. Watch Bluetooth-enabled data logging adoption velocity in Japanese automotive supply chains as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Contract Expansion | Recurring revenue capture from ISO 17025 recertification deadlines in Germany and China. |
| Backward Integration into Indenter Manufacturing | Margin defense against silicone raw material volatility in medical-grade elastomer supply chains. |
| Wireless SPC Connectivity Platform Launch | Real-time hardness monitoring adoption in Shenzhen automotive tier-one supplier networks. |
| Multi-Standard Certification Investment | Dual ASTM D2240 and DIN 53505 compliance for multinational rubber compounder procurement. |
| Coastal Distribution Network Acquisition | Marine coating inspector access for portable Barcol durometer field verification deployment. |
Research Methodology
Multiple input streams — primary interviews with quality control lab managers, automotive tier-one supplier procurement leads, and medical device regulatory affairs directors; secondary validation against customs trade data, ISO 17025 accreditation registries, and FDA 510(k) submission databases — were reconciled through bottom-up instrument shipment tracking and top-down end-use demand estimation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of product type, application, technology, and end-user dimensions with geographic production cluster overlays. CAGRs were derived from instrument replacement cycle compression analysis and digital adoption curve calibration. Forecast inputs incorporated MIIT-mandated quality infrastructure investment timelines and EU MDR documentation requirement phase-ins.
Regulatory enforcement variance, silicone raw material price spikes, and automotive OEM consolidation pace are the dominant revision risks to modeled demand trajectories. Forecasts reflect documented assumptions regarding ISO 17025 recertification deadline adherence and Bluetooth-enabled SPC platform penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Gold Tester Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Viscometer Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Durability Testing Systems Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Host Cell Contaminant Testing Market