
 Body Glitters Market | 2026-2036
Body Glitters Market Size, Share, and Industry Trends Forecast 2026-2036
Body Glitters Market Insights
Multi-source formulation partnerships is shifting as specialty chemical suppliers compete with vertically integrated beauty houses. Fenty Beauty leverages direct-to-consumer channel control to capture premium positioning. Moon Glitter anchors its presence through professional makeup artist relationships. L'Oréal Paris sustains manufacturing scale across multiple regional production sites.
Body glitters comprise cosmetic-grade reflective particles, typically aluminum-based or biodegradable film substrates sized between 0.002 and 0.150 inches, designed for temporary skin adhesion through gel, cream, or loose-delivery vehicles. Loose Glitter occupies the largest volume position due to professional versatility, while Gel Glitter captures expanding share among festival consumers seeking mess-free application. Online Retail leads distribution growth as beauty salons and specialty stores face foot-traffic compression.
The FDA regulates color additives under 21 CFR 73 and 74, restricting certain metallic pigments from eye-area use, while the EU REACH microplastic restriction forces reformulation toward cellulose or mineral-based alternatives. Health Canada and the FDA both scrutinize particle inhalation risks, tightening testing protocols for spray-delivery formats. Stakeholders must monitor regulatory divergence between North American and European permissible particle compositions to avoid market-access disruption.
Market Dynamics
EU REACH microplastic restrictions are forcing wholesale reformulation across the body glitters supply base, compressing timelines for cellulose and mineral-based alternatives while fragmenting permissible ingredient lists between regulatory jurisdictions.
Growth Catalysts
- Festival makeup applications:Professional makeup artists at music and cultural events drive bulk purchasing of loose glitter formats for high-volume temporary applications.
- REACH regulation phase-in:The EU's staged microplastic ban creates immediate pull for biodegradable film substrates as brands race to maintain European market access.
- Cellulose substrate innovation:Advances in plant-derived film manufacturing reduce cost gaps with conventional aluminum-based particles, accelerating adoption.
Market Restraints
- Aluminum pigment cost volatility:Raw material price swings for metallic substrates compress margin stability for mid-tier suppliers dependent on conventional formulations.
- Supply concentration in specialty chemical hubs:Germany and China dominate biodegradable substrate precursor production, creating single-source vulnerability for reformulating brands.
- FDA eye-area restrictions:21 CFR 73 and 74 prohibitions on certain metallic pigments limit cross-promotional bundling with eye cosmetics, constraining portfolio expansion.
Strategic Opportunities
- India professional salon channel:Underpenetrated organized retail and festival culture in Mumbai and Bangalore offer first-mover positioning for gel-format entrants.
- Health Canada spray-format pathway:Tightened inhalation-risk testing protocols create premium positioning for compliant aerosol-delivery systems.
- Direct-to-consumer subscription models:Festival-season timing and influencer collaboration enable recurring revenue capture outside traditional retail markups.
Industry Challenges
- Cosmetic toxicologist scarcity:Specialized formulation chemists capable of navigating divergent FDA-REACH permissible particle lists command premium compensation, stretching R&D budgets.
- Dual-certification timeline compression:Parallel safety dossier preparation for North American and European submission windows strains smaller manufacturers without dedicated regulatory affairs functions.
- Legacy gel-vehicle compatibility:Existing cream and gel bases require reformulation to suspend cellulose particles without aggregation, demanding unplanned pilot-scale testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Glitters Market |
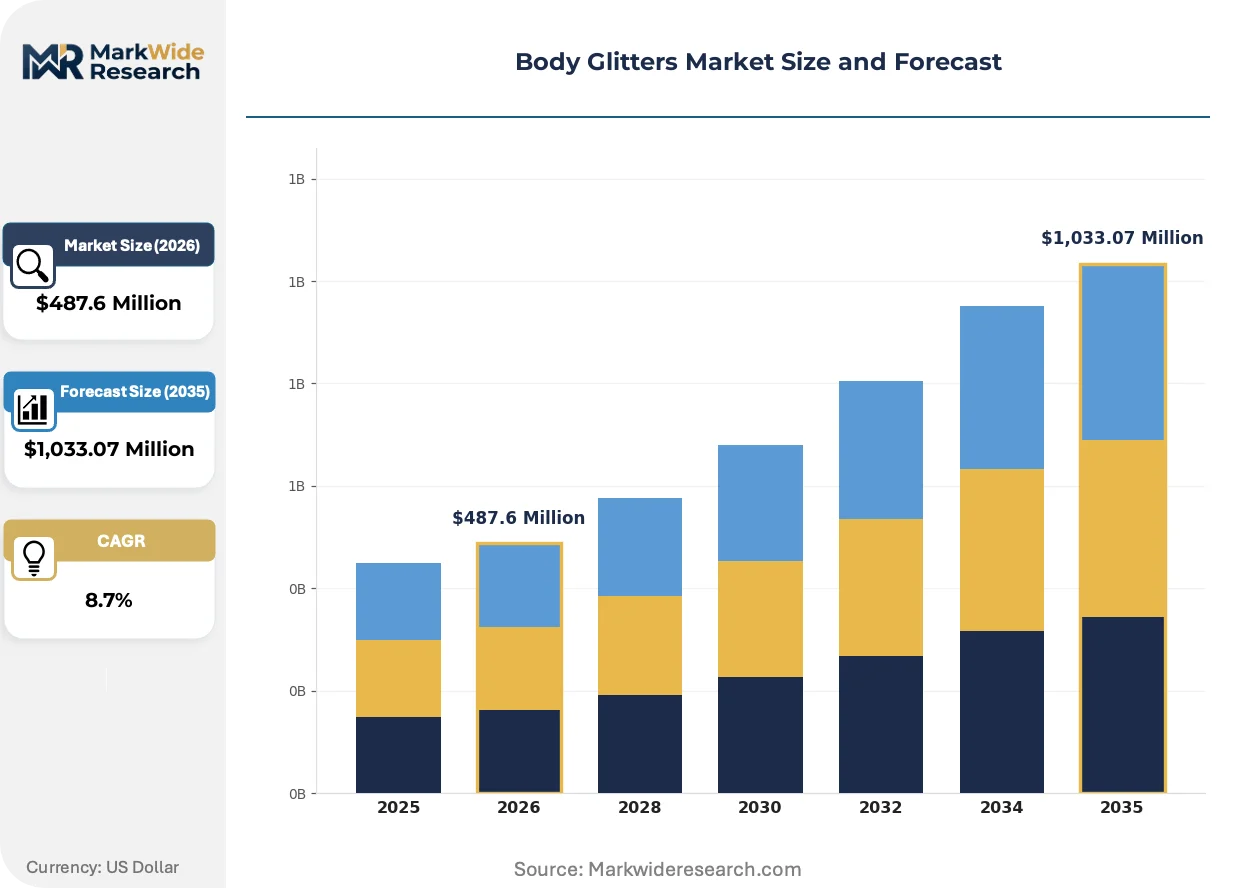
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Glitter, Gel Glitter, Spray Glitter, Cream Glitter End User: Cosmetic Retailers, Event Planners, Makeup Artists, Individuals Application: Parties, Festivals, Photoshoots, Theatrical Productions Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Beauty Salons |
| Companies Covered | e.l.f. Cosmetics, Urban Decay, Fenty Beauty, Too Faced Cosmetics, NYX Professional Makeup, L'Oréal Paris, Moon Glitter, ColourPop Cosmetics, Huda Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Glitters Market Trends and Innovations
Active reformulation investment is compressing product development cycles as brands pivot from petroleum-derived substrates toward bio-based alternatives ahead of regulatory deadlines.
Cellulose film substrates sized between 0.002 and 0.150 inches are absorbing market share from aluminum-based alternatives as the dominant reflective particle technology. Professional makeup artists in Los Angeles and New York creative hubs are adopting these biodegradable options for festival applications at accelerating rates. The technology is absorbing reformulation R&D budgets that previously targeted particle shape innovation, redirecting supplier technical service resources toward compatibility testing with existing gel and cream vehicles.
REACH microplastic restriction Annex XV entries are forcing ingredient list divergence between European and North American product variants. The regulation's 2026-2030 phase-in timeline is compressing supplier qualification windows and fragmenting production runs. Gel-format festival products face the steepest compliance burden, as loose glitter offers easier substrate substitution without vehicle reformulation.
Beauty salon foot-traffic compression is redirecting volume toward online retail and direct brand channels. Festival consumers in the United States are bypassing specialty stores for influencer-curated kits with pre-matched color palettes. This channel rotation is most visible in Los Angeles, where professional artist endorsement drives direct-to-consumer conversion rates above conventional cosmetic category benchmarks.
Body Glitters Market Segmentation
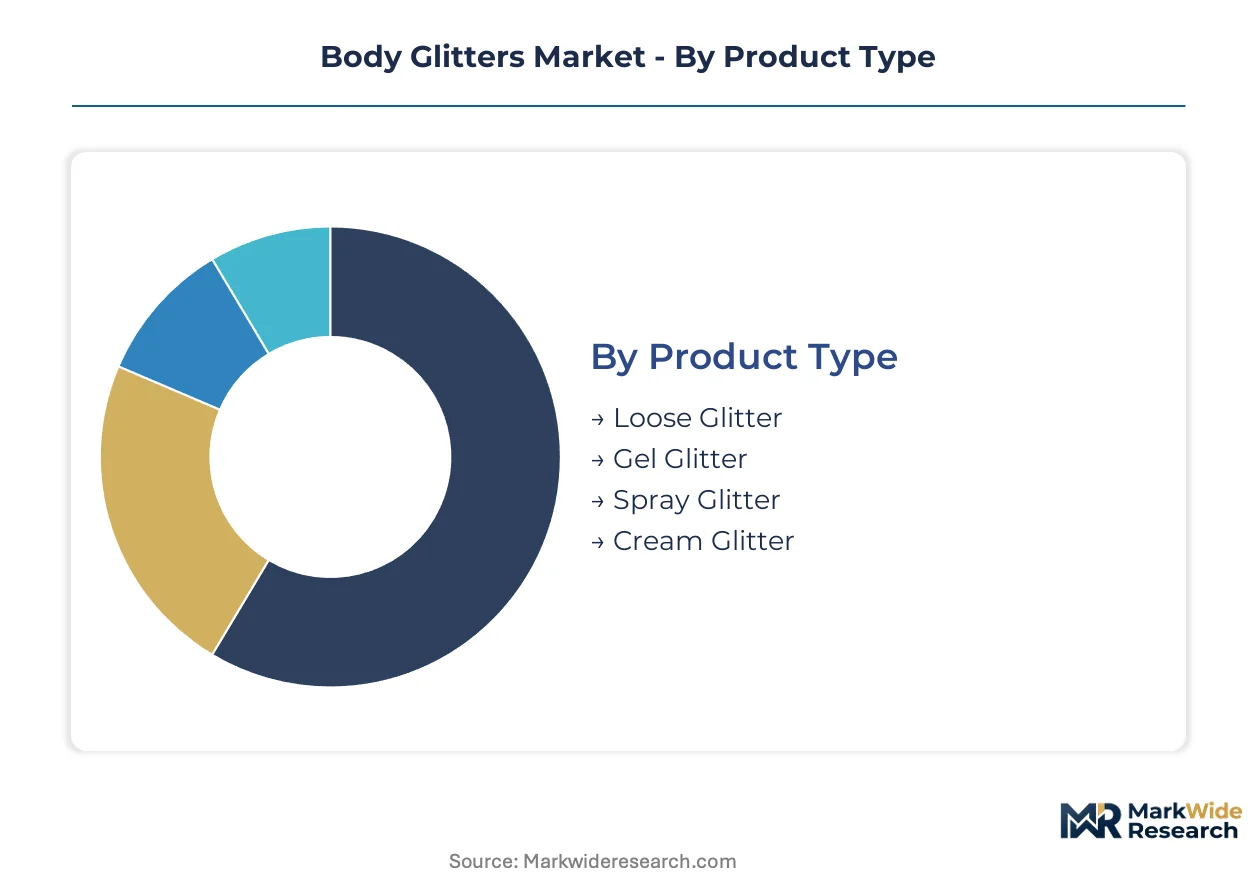
Body glitters segmentation reveals divergent growth mechanics across formulation physics, professional versus consumer use cases, and channel economics. Understanding these splits exposes where reformulation costs concentrate and where premium positioning commands sustainable margin.
Product Type:
Volume leadership sits with loose formats favored by professionals, while gel and spray vehicles capture premium pricing through convenience and compliance advantages.
- Loose Glitter:Dry reflective particles in aluminum or cellulose substrates deliver maximum color intensity and blendability for professional makeup artists. Festival applications in Los Angeles and New York drive bulk purchasing, though EU REACH microplastic restrictions now force substrate transitions that raise per-unit input costs.
- Gel Glitter:Pre-suspended particles in aqueous or silicone vehicles eliminate airborne dispersion and simplify application for non-professional users. The format absorbs the steepest compliance burden under REACH Annex XV, as gel bases require reformulation to maintain cellulose particle suspension without aggregation.
- Spray Glitter:Aerosol-delivery systems face tightened Health Canada inhalation-risk protocols that create premium positioning for compliant formulations.
- Cream Glitter:Emulsion-based vehicles target theatrical and photoshoot applications where extended wear time justifies higher price points.
Today's leader: Loose Glitter. Tomorrow's challenger: Gel Glitter.
End User:
Professional versus amateur purchasing patterns split sharply on volume scale, technical specification requirements, and regulatory liability exposure.
- Cosmetic Retailers:Stock-keeping units concentrate on gel and cream formats with extended shelf stability and lower shrinkage risk than loose alternatives.
- Event Planners:Bulk procurement for music festivals and corporate activations favors loose glitter in professional quantities, with Los Angeles event production companies representing concentrated demand.
- Makeup Artists:Individual practitioners and agency collectives maintain diverse format inventories, with cellulose substrate adoption accelerating fastest among Los Angeles and New York creative hub professionals responding to client sustainability preferences.
- Individuals:Direct-to-consumer purchases through online retail channels favor pre-curated kits with matched color palettes, bypassing specialty store markups.
Professional channels anchor current volume. Individual direct purchasing is climbing the fastest.
Application:
Use-case environments dictate durability requirements, skin contact duration, and cleanup complexity that shape formulation selection.
- Festivals:Extended outdoor wear in variable conditions demands sweat-resistant gel vehicles and high-visibility cellulose substrates, with EU REACH compliance now a procurement prerequisite for European event production.
- Parties:Shorter-duration indoor use permits lower-cost aluminum-based loose glitter where regulatory jurisdiction permits.
- Photoshoots:Controlled studio environments prioritize color accuracy and camera-reflective properties over wear time.
- Theatrical Productions:Stage lighting requirements and eight-hour performance schedules drive cream-format preference for adhesion durability.
Festivals command the highest growth trajectory. Theatrical applications face budget compression from venue operating cost pressures.
Distribution Channel:
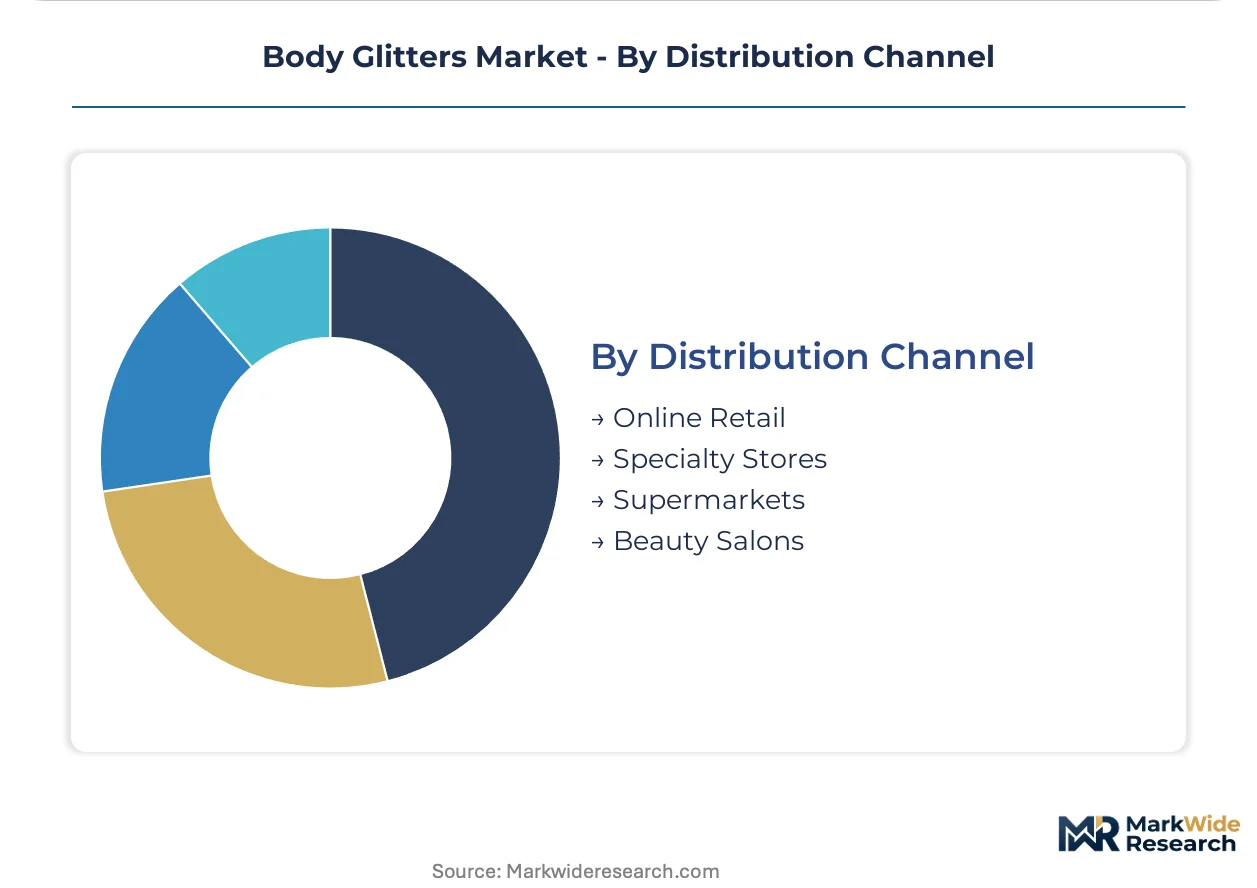
Channel economics fragment between high-margin direct relationships and scale-dependent retail partnerships with divergent working capital requirements.
- Online Retail:Influencer-curated kits and subscription models capture recurring revenue outside traditional retail markups, with conversion rates in Los Angeles exceeding conventional cosmetic category benchmarks.
- Specialty Stores:Foot-traffic compression redirects volume toward digital channels, though professional artist supply relationships sustain residual positioning.
- Supermarkets:Mass-market placement targets impulse purchasing with lower-unit-price gel formats, constrained by FDA eye-area restriction labeling requirements.
- Beauty Salons:Organized retail penetration in Mumbai and Bangalore offers first-mover positioning for professional-grade gel format entrants.
Online Retail leads expansion. Beauty Salons in underpenetrated markets represent the steepest share-gain opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions with lower compliance-transition costs, while festival-demand clusters in specific metro areas concentrate procurement volume regardless of manufacturing location.
United States
Festival culture in Los Angeles and New York creative hubs sustains bulk loose-glitter procurement by professional makeup artists. FDA 21 CFR 73 and 74 color-additive restrictions constrain eye-area formulations but permit broader body applications. Los Angeles event production companies now specify cellulose substrates for sustainability-mandated corporate activations.
Germany
EU REACH Annex XV microplastic restrictions are compressing reformulation timelines for brands serving European festival circuits. ECHA enforcement creates immediate demand-pull for biodegradable film substrates from domestic specialty chemical suppliers. Cologne and Düsseldorf beauty trade fairs anchor professional artist supply relationships across the continent.
China
Domestic festival adoption in Shanghai and Guangzhou is accelerating gel-format preference among younger consumers. NMPA cosmetic registration requirements for imported products create compliance friction for foreign brands seeking direct market entry. Zhejiang and Jiangsu provinces concentrate aluminum-pigment precursor manufacturing for conventional formulations.
India
Organized retail underpenetration in Mumbai and Bangalore offers first-mover positioning for professional-grade gel entrants targeting festival makeup applications. BIS cosmetic standards lack microplastic-specific provisions, reducing near-term reformulation pressure versus European counterparts. Delhi-NCR event management companies are importing loose cellulose formats for destination weddings and cultural celebrations.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates dual-certification burden for brands serving both markets. London-based professional makeup artist agencies are standardizing cellulose substrate specifications across European and domestic tour schedules. Manchester and Birmingham festival circuits sustain mid-tier gel-format volume despite retail channel compression.
Body Glitters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer positioning and biodegradable substrate specialization. The vendor base splits between vertically integrated beauty conglomerates with captive chemical supply and independent formulators dependent on external substrate procurement. Three archetypes dominate: multinational scale players with regional manufacturing footprints, influencer-native digital brands with channel control, and professional-supply specialists with artist-relationship networks. Competitive moves concentrate on M&A for substrate technology access and strategic partnerships with specialty chemical suppliers.
Within the influencer-native tier, Fenty Beauty exemplifies direct-to-consumer channel control and premium positioning. L'Oréal Paris represents multinational scale with distributed manufacturing across multiple regional production sites. Moon Glitter anchors the professional-supply archetype through makeup artist relationship networks. These three occupy distinct competitive vectors without direct overlap in procurement or distribution economics.
| Leading Market Players |
|---|
| e.l.f. Cosmetics |
| Urban Decay |
| Fenty Beauty |
| Too Faced Cosmetics |
| NYX Professional Makeup |
| L'Oréal Paris |
| Moon Glitter |
| ColourPop Cosmetics |
| Huda Beauty |
| Others |
Pricing and Supply Chain Analysis
Premium-credential cellulose substrate certification separates professional-grade festival supply from mass-market aluminum alternatives, compressing margin structures at the commodity tier while rewarding upstream control over biodegradable precursor manufacturing in Germany and Zhejiang province. This bifurcation concentrates pricing power with specialty chemical houses capable of REACH-compliant particle production, forcing downstream formulators to absorb input cost premiums or surrender shelf space to vertically integrated beauty conglomerates.
Pricing Analysis
Distributor markups on gel-format festival kits absorb the steepest compression as direct-to-consumer influencer channels bypass wholesale layers entirely. Three-tier pricing structure across premium cellulose, standard aluminum, and economy mineral substrates tracks certification burden and particle suspension complexity. Pricing pressure stems from EU REACH Annex XV compliance timelines accelerating reformulation R&D spend. Individual festival consumers exhibit highest price sensitivity through online retail, while Los Angeles event production companies prioritize sustainability credentials over unit cost.
Supply Chain Analysis
Specialized cosmetic toxicologist availability in Germany and limited cellulose film engineering talent in China's Zhejiang province constrain production scaling for compliant substrate output. Raw material flows draw from aluminum pigment precursors in Jiangsu province, cellulose derivatives from German specialty chemical hubs, and silicone gel vehicles from South Korean polymer manufacturers. Single-source vulnerability concentrates in biodegradable substrate precursor supply. Distribution runs through direct brand channels and professional artist supply relationships, with online retail capturing accelerating share from compressed specialty store footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in body glitters hinges on cellulose substrate cost curves flattening against aluminum alternatives as manufacturing scale accumulates in compliant jurisdictions, alongside premium-tier gel formats capturing festival consumer willingness to pay for mess-free application.
For Market Incumbents: Deepen captive supply relationships with German and Zhejiang cellulose precursor manufacturers to secure reformulation timelines ahead of REACH enforcement waves. Defend professional artist channel positioning through exclusive biodegradable substrate access, while accelerating gel-vehicle compatibility testing to prevent aggregation failures that would cede festival market share to nimbler formulators.
For New Entrants and Emerging Players: Capture underpenetrated professional salon distribution in Mumbai and Bangalore through gel-format SKUs tailored to Indian festival culture and BIS regulatory flexibility. White-space concentration in organized retail penetration and direct-to-consumer subscription timing around global festival calendars offers first-mover positioning without incumbent legacy reformulation burdens.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual-certification capabilities for FDA and REACH divergent particle lists command scarcity premiums in M&A markets. Acquisition targets center on independent formulators with established professional artist networks and cellulose substrate technical partnerships. The signal to watch is Health Canada spray-format compliance pathway progression, which would validate premium aerosol-delivery R&D bets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellulose Substrate Backward Integration | Captures REACH-compliant supply security and compresses input cost volatility for festival-grade output. |
| Professional Artist Network Expansion | Secures bulk procurement relationships with Los Angeles and New York event production companies. |
| Gel-Vehicle Compatibility R&D Investment | Resolves cellulose particle aggregation challenges that threaten festival application performance. |
| Direct-to-Consumer Subscription Launch | Bypasses retail markup compression through influencer-curated kit timing with global festival calendars. |
| Dual-Certification Regulatory Affairs Buildout | Enables parallel FDA and REACH dossier preparation without external consultant dependency. |
Research Methodology
Bottom-up festival procurement modeling reconciled against top-down specialty chemical substrate production tracking forms the analytical core of this study. Primary interviews with professional makeup artists, event production procurement leads, cosmetic regulatory affairs directors, and specialty chemical supplier technical service teams combined with secondary validation from FDA 21 CFR filings, ECHA REACH Annex XV entries, customs trade data on aluminum pigment flows, and professional beauty trade fair exhibitor records. Triangulation across these sources calibrated volume estimates and reformulation timeline assumptions.
Input-output matrices mapped cellulose and aluminum substrate supply through gel, loose, spray, and cream vehicle conversion to end-use segments across the projection horizon. Segmentation dimensions modeled include product format physics, professional versus consumer buyer archetype, festival versus theatrical versus party application environment, and channel economics from direct-to-consumer through specialty retail. CAGRs derived from regression analysis against regulatory phase-in schedules and substrate substitution elasticity estimates, with festival demand clustering in named metro areas serving as regional allocation anchors.
REACH enforcement acceleration, cellulose manufacturing scale-up delays, and festival consumer channel preference shifts are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on regulatory timeline adherence and substrate cost convergence trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
DIY Eyelash Extension Market