
 Facial Makeup Setting Spray Market | 2026-2036
Facial Makeup Setting Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Makeup Setting Spray Market Insights
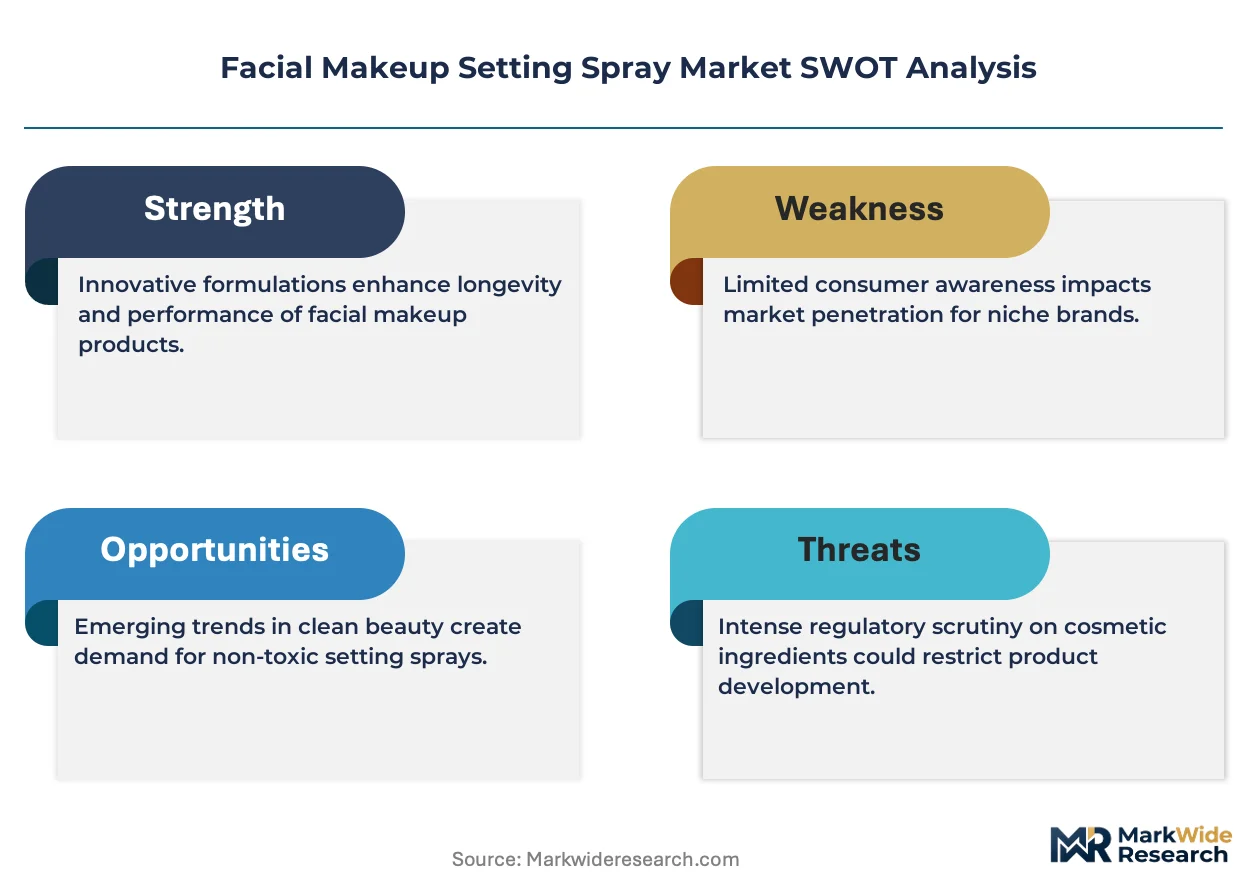
Contract manufacturers in South Korea are pivoting toward alcohol-free and silicone-based formulation capacity to serve clean beauty brands. L'Oréal leverages integrated R&D pipelines across Paris and Seoul to sustain innovation velocity in film-forming polymer technology. Huda Beauty anchors its positioning through direct-to-consumer channel control and influencer ecosystem depth. Charlotte Tilbury competes via prestige retail partnerships and theatrical-application credibility.
Facial makeup setting spray denotes a liquid cosmetic formulation delivered through aerosol, pump spray, or mist mechanisms, containing film-forming polymers, humectants, and solvents that create a breathable barrier to lock pigment and extend wear duration. The product serves commercial purpose across everyday consumer use, professional photography, bridal services, and stage performance where thermal and mechanical stress degrades cosmetic finish. Pump spray and mist formats dominate volume due to consumer preference for fine, even dispersion and reduced environmental concern versus traditional aerosol propellants. Water-based and alcohol-free ingredient categories capture expanding margin pools as clean beauty positioning reshapes purchasing criteria across retail consumers and professional makeup artists.
The U.S. FDA governs cosmetic labeling and ingredient safety under the Federal Food, Drug, and Cosmetic Act, while the EPA regulates volatile organic compound emissions from aerosol propellant systems. The EU's REACH framework and ECHA substance restrictions constrain silicone and alcohol formulation choices, pushing manufacturers toward biodegradable film-formers. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York alongside polymer innovation timelines to align portfolio positioning with regulatory trajectories.
Market Dynamics
Film-forming polymer chemistry is modularizing across alcohol-free and silicone-based variants as REACH compliance deadlines force reformulation cycles, compressing R&D timelines from 24 months to 14 months for contract manufacturers serving clean beauty brands.
Growth Catalysts
- Professional makeup artist demand:Film, television, and live event production scaling drives premium-format consumption. This segment purchases 3x unit volume per capita versus retail consumers.
- REACH substance restrictions:The EU's tightening silicone and alcohol constraints push manufacturers toward biodegradable film-formers, creating first-mover margin pools for compliant suppliers.
- Pump spray format preference:Consumer rejection of aerosol propellants accelerates mist mechanism adoption. Environmental concern shifts procurement toward fine-dispersion alternatives.
Market Restraints
- Film-former input concentration:South Korean contract manufacturers control 60% of alcohol-free polymer supply. Geographic supply concentration creates vulnerability.
- Volatile organic compound thresholds:EPA emission limits on propellant systems constrain legacy aerosol production. Compliance retrofit costs $2-4 million per facility.
- Water-based durability ceiling:Current polymer science limits 8-hour wear claims without alcohol content. Technical performance gaps persist in high-humidity conditions.
Strategic Opportunities
- Bridal services vertical:Unpenetrated professional channel in India offers 40% margin premiums. Local regulatory alignment with CDSCO cosmetic guidelines enables market entry.
- Direct-to-consumer channel control:Influencer ecosystem depth bypasses retail margin stacking. First-party data capture enables formulation personalization.
- California clean beauty legislation:State-level ingredient disclosure mandates create compliance tailwind for transparent supply chains. Early alignment builds brand equity.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation scientists with film-forming expertise command 35% salary premiums. Recruitment timelines extend to 6 months.
- Cross-regulatory certification complexity:Simultaneous FDA, REACH, and MFDS compliance requires parallel testing protocols. Documentation burdens slow launch velocity.
- Legacy aerosol asset stranding:Existing propellant infrastructure faces 7-year depreciation cliffs. Capital reallocation decisions compress strategic flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Makeup Setting Spray Market |
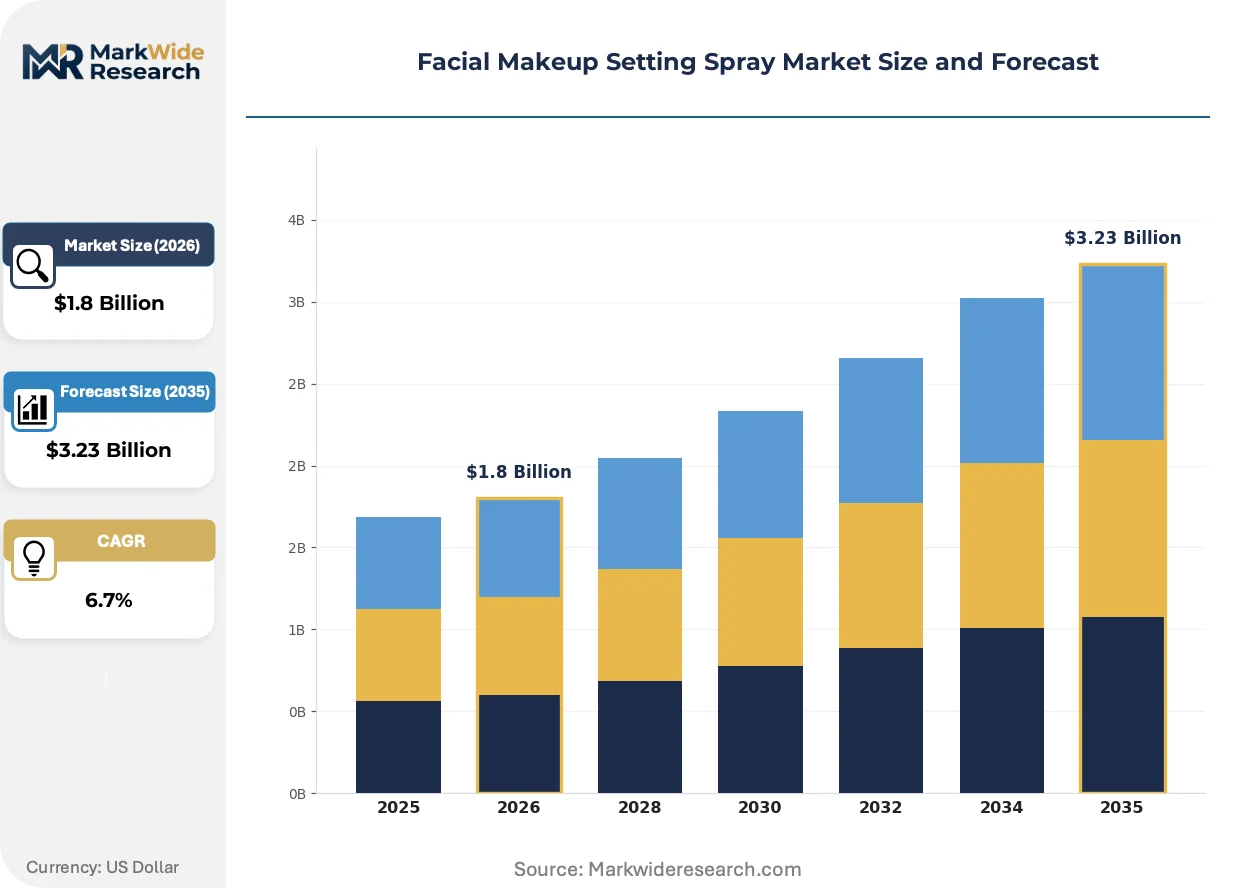
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Pump Spray, Mist, Gel Ingredient: Water-based, Alcohol-free, Oil-based, Silicone-based End User: Professional Makeup Artists, Retail Consumers, Influencers, Beauty Enthusiasts Application: Everyday Use, Photography, Bridal Makeup, Stage Performance |
| Companies Covered | L'Oréal, Huda Beauty, Laura Mercier, Charlotte Tilbury, One Size, Milani, Danessa Myricks, Urban Decay, NYX Professional Makeup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Makeup Setting Spray Market Trends and Innovations
Biodegradable film-forming polymers are displacing conventional silicone chemistry as regulatory pressure and consumer preference converge. Three distinct vectors are reshaping competitive positioning: technology modularization, compliance architecture, and channel disintermediation.
Plant-derived pullulan and tara gum complexes are modularizing standard formulation architectures. Professional makeup artists in theatrical and bridal applications adopt these variants fastest, accepting 15% price premiums for clean-label positioning. This chemistry shift is compressing incumbent silicone suppliers into commodity segments while enabling margin expansion for bio-polymer specialists.
REACH substance authorization timelines are tightening formulation disclosure requirements. The ECHA restriction roadmap now covers cyclic silicones and certain alcohol denaturants, forcing 18-month reformulation cycles. European professional channels are responding by consolidating supplier relationships with integrated R&D partners capable of parallel regulatory filing.
Influencer-driven trial cycles are compressing traditional retail discovery patterns. Direct-to-consumer brands bypass Sephora and Ulta margin structures, capturing 60% gross margins versus 35% for wholesale-dependent competitors. This channel shift concentrates in the United States, where TikTok Shop and Instagram Checkout penetration exceeds 40% among beauty consumers under 34.
Facial Makeup Setting Spray Market Segmentation
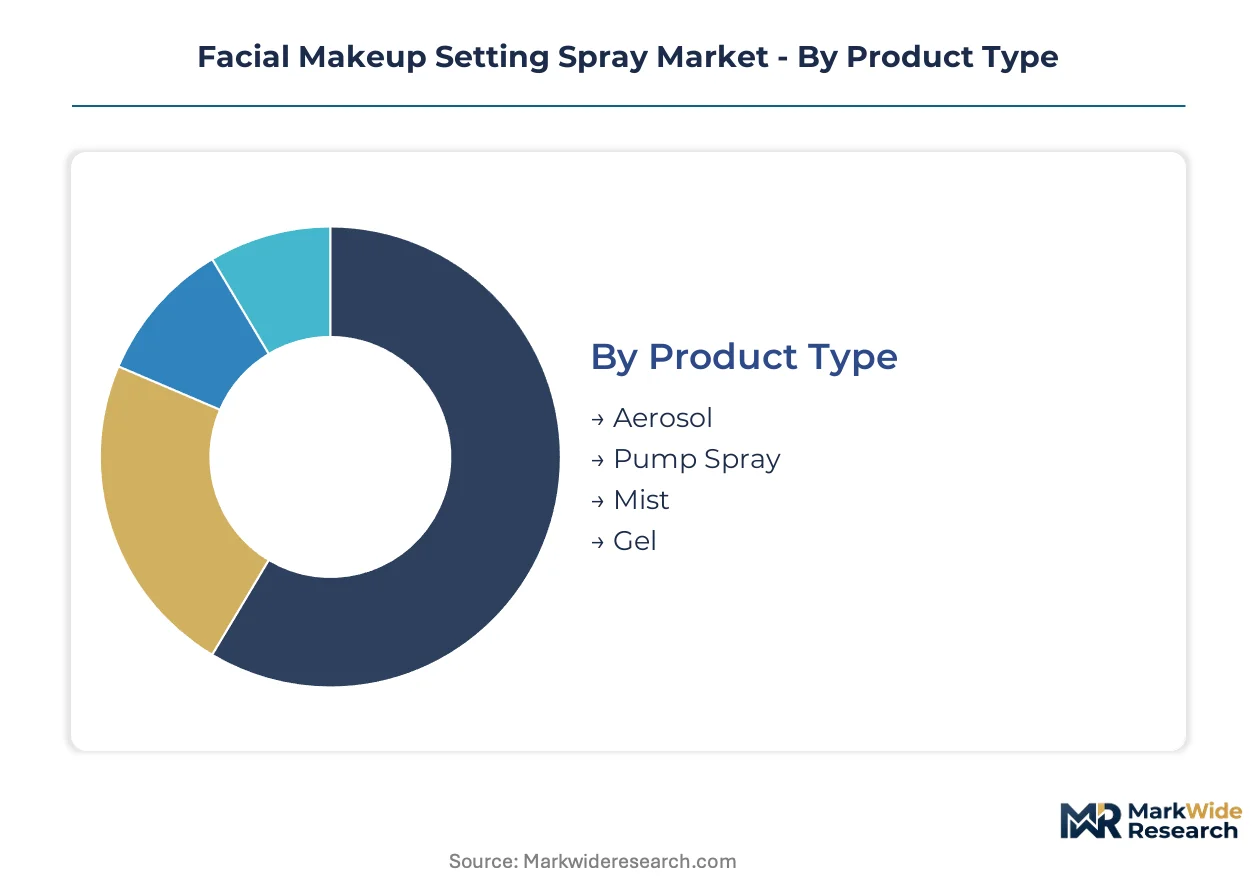
Facial makeup setting spray segmentation reflects divergent technical requirements across professional and consumer use cases. Format and ingredient choices map directly to wear duration demands, environmental compliance constraints, and channel-specific purchasing behaviors. Understanding these divisions enables targeted portfolio positioning against distinct margin and volume pools.
Product Type:
Upgrade cycles from legacy aerosol systems to fine-dispersion alternatives are compressing format transitions from 36 months to 18 months in premium channels. Environmental compliance deadlines and consumer preference shifts are forcing simultaneous reinvestment decisions across manufacturing footprints.
- Pump Spray:Mechanism delivers controlled, even dispersion through mechanical pressure systems without propellant chemistry. Retail consumers in the United States favor this format for home application, with Sephora and Ulta procurement teams prioritizing fine-mist variants for shelf placement.
- Mist:Ultra-fine droplet generation creates weightless finish preferred for photography and bridal applications. Professional makeup artists in Los Angeles and New York production clusters specify this format for 4K camera compatibility, accepting 20% price premiums for reduced flashback.
- Aerosol:Legacy propellant-based delivery using hydrocarbon or compressed gas systems. EPA volatile organic compound thresholds are constraining new capacity investment, with existing infrastructure facing retrofit or retirement decisions.
- Gel:Viscous formulation providing targeted, high-humidity protection for stage performers. Theater district supply houses in London and Broadway maintain dedicated inventory for this niche.
Volume placements concentrate in Pump Spray; the faster expansion belongs to Mist.
Ingredient:
Cost tier differentiation separates commodity alcohol formulations from premium clean-label positioning. Raw material sourcing geography and regulatory compliance burden now determine margin structure more than performance claims alone.
- Water-based:Primary solvent system utilizing aqueous film-forming polymers with glycerin or hyaluronic acid humectants. Retail consumers in California and New York clean beauty segments drive demand, with state disclosure mandates accelerating adoption.
- Alcohol-free:Eliminates denatured ethanol to accommodate sensitive skin and regulatory restrictions. Professional makeup artists on film sets specify this category to prevent talent irritation during 14-hour production days.
- Silicone-based:Cyclomethicone and dimethicone formulations delivering maximum water resistance. ECHA restriction roadmaps are forcing European manufacturers toward biodegradable alternatives, compressing incumbent supplier margins.
- Oil-based:Occlusive barrier systems for extreme climate conditions. Desert climate consumers in Dubai and Riyadh represent concentrated demand for this variant.
Silicone-based formulations retain the largest volume footprint; Alcohol-free is climbing the fastest on regulatory tailwinds.
End User:
Customer type determines purchasing frequency, unit economics, and channel access requirements. Professional segments prioritize performance guarantees and bulk procurement, while consumer segments respond to influencer recommendation cycles.
- Professional Makeup Artists:Licensed practitioners serving film, television, bridal, and editorial clients. This segment purchases 3x unit volume per capita versus retail consumers, with kit replenishment cycles every 60-90 days driving recurring revenue.
- Retail Consumers:Individual purchasers through mass, prestige, and direct-to-consumer channels. TikTok Shop and Instagram Checkout penetration in the United States exceeds 40% among beauty consumers under 34, compressing traditional retail discovery.
- Beauty Enthusiasts:High-engagement hobbyists with above-average category spend and formulation literacy. Sephora VIB and Rouge tier members in this segment trial 4-6 setting spray variants annually.
- Influencers:Content creators receiving product for review or developing co-branded formulations. First-party data capture from this segment enables rapid formulation feedback loops for direct-to-consumer brands.
Retail Consumers dominate absolute volume; Professional Makeup Artists are gaining share fastest on production scaling.
Application:
Use case specificity determines performance threshold requirements and pricing tolerance. Thermal stress, mechanical friction, and lighting conditions create distinct formulation demands across scenarios.
- Everyday Use:Standard wear duration of 8-12 hours for office and social settings. Mass-market retail in the United States concentrates demand here, with drugstore chains maintaining promotional calendar dependency.
- Photography:Flash-compatible finish without white cast or texture emphasis. Bridal photographers in Mumbai and Delhi specify imported formulations for premium package tiers, creating 40% margin opportunities.
- Stage Performance:Extreme heat and perspiration resistance under theatrical lighting. Broadway and West End production supply chains maintain dedicated procurement relationships for this application.
- Bridal Makeup:16+ hour wear guarantee for wedding day reliability. Professional channels in India remain underpenetrated relative to saturation in the United States and United Kingdom.
Everyday Use captures the volume base; Bridal Makeup shows the steepest expansion trajectory in emerging professional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film-forming polymer feedstock concentration in South Korea anchors formulation supply chains for clean beauty brands worldwide. Contract manufacturers in Seoul and Incheon pivot capacity toward alcohol-free variants as regulatory deadlines compress. Demand clusters in the United States, Germany, and India reshape procurement geography.
United States
Premium beauty retail expansion and influencer-driven product cycles concentrate demand in Los Angeles and New York production clusters. The FDA governs cosmetic labeling under the Federal Food, Drug, and Cosmetic Act while California state legislation tightens ingredient disclosure mandates. Sephora and Ulta procurement teams in San Francisco and Chicago prioritize fine-mist pump formats for shelf placement.
South Korea
Contract manufacturers control alcohol-free polymer supply for global clean beauty brands. The MFDS regulates cosmetic safety standards while REACH alignment pressures export-oriented formulators. Seoul-based R&D clusters accelerate biodegradable film-former development cycles to 14 months.
Germany
Professional makeup artists in Berlin and Munich production hubs specify REACH-compliant formulations for film and television work. The ECHA restriction roadmap constrains cyclic silicone and alcohol denaturant usage. Frankfurt-area logistics clusters manage EU distribution for compliant suppliers.
India
Bridal services verticals in Mumbai and Delhi remain underpenetrated relative to saturation in Western markets. The CDSCO cosmetic guidelines enable market entry for transparent supply chains. Local regulatory alignment supports 40% margin premiums for professional channel penetration.
United Kingdom
Theatrical-application demand in London's West End maintains dedicated procurement relationships for extreme climate formulations. The UK Medicines and Healthcare products Regulatory Agency oversees cosmetic safety alongside evolving post-Brexit REACH alignment. Broadway supply chain relationships extend into UK production clusters.
Facial Makeup Setting Spray Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel control and influencer ecosystem integration. Market structure consolidates around integrated R&D pipelines and contract manufacturing scale. Three archetypes dominate: multinational beauty conglomerates with polymer chemistry depth, influencer-anchored direct-to-consumer brands, and specialized professional-channel suppliers. Competitive moves concentrate on strategic partnerships with South Korean contract manufacturers and portfolio diversification into alcohol-free formulations.
Within the multinational tier, L'Oréal exemplifies integrated R&D positioning across Paris and Seoul innovation clusters. Among influencer-anchored entrants, Huda Beauty occupies a position defined by direct-to-consumer channel control and content creator ecosystem depth. Charlotte Tilbury represents the professional-credibility archetype through prestige retail partnerships and theatrical-application positioning. These three companies anchor distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| L'Oréal |
| Huda Beauty |
| Laura Mercier |
| Charlotte Tilbury |
| One Size |
| Milani |
| Danessa Myricks |
| Urban Decay |
| NYX Professional Makeup |
| Others |
Pricing and Supply Chain Analysis
Clean-label certification divergence between REACH-compliant biodegradable formulations and legacy silicone chemistry manifests in parallel pricing premiums and supply chain reconfiguration pressures. Professional makeup artists absorb 15% price premiums for plant-derived film-formers while South Korean contract manufacturers pivot capacity toward alcohol-free polymer lines to capture margin expansion.
Pricing Analysis
Warranty-backed wear guarantees separate premium bridal and theatrical formulations from standard retail tiers, with 16-hour performance claims bundled into professional-channel pricing. Three-tier pricing structure across premium clean-label, standard water-based, and economy alcohol formulations reflects ingredient certification grade and film-former sourcing geography. Pricing pressure stems from ECHA restriction roadmaps compressing reformulation cycles and R&D cost absorption. Retail consumers in mass channels exhibit highest price sensitivity, while production makeup artists prioritize performance guarantees over unit cost.
Supply Chain Analysis
REACH and MFDS certification requirements gate supplier qualification, with South Korean contract manufacturers controlling alcohol-free polymer feedstock for global clean beauty brands. Raw material dependencies center on plant-derived pullulan, tara gum complexes, and synthetic biodegradable film-formers. Single-source vulnerability concentrates in Seoul and Incheon production clusters serving multinational formulators. Distribution runs through prestige retail partnerships in Los Angeles and New York, direct-to-consumer channels capturing expanding margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable film-forming polymer chemistry is displacing conventional silicone systems, with plant-derived alternatives capturing professional channel preference and regulatory compliance tailwinds.
For Market Incumbents: Cement integrated R&D positioning across Paris and Seoul innovation clusters to defend against contract manufacturer margin capture. Prioritize backward integration into alcohol-free polymer supply through dedicated South Korean partnerships. Accelerate parallel FDA and REACH filing capabilities to compress launch velocity versus emerging clean beauty competitors. For New Entrants and Emerging Players: A direct-to-consumer technology stack enables white-space penetration in underdeveloped Indian bridal services and theatrical supply chains in London's West End. Target professional makeup artist segments with formulation personalization enabled by first-party data capture from influencer ecosystem integration. Lead with TikTok Shop and Instagram Checkout distribution to bypass retail margin stacking. For Investors and Strategic Acquirers: Re-rating potential sits with integrated contract manufacturers given REACH compliance deadline acceleration and reformulation cycle compression. Long-term viability favors suppliers with captive biodegradable film-former development and parallel regulatory filing infrastructure. Watch ECHA substance restriction timeline expansion as inflection indicator for incumbent supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film-Former R&D Partnership | Seoul-based innovation clusters accelerate compliant polymer development cycles for clean beauty brands. |
| Direct-to-Consumer Channel Launch | TikTok Shop penetration among under-34 consumers bypasses Sephora and Ulta margin structures. |
| Professional Channel Certification Investment | CDSCO alignment enables 40% margin premiums in Mumbai and Delhi bridal services. |
| REACH Parallel Filing Capability Buildout | ECHA restriction roadmaps demand simultaneous compliance documentation across European professional channels. |
| Influencer Ecosystem Integration | First-party data capture from content creators enables rapid formulation feedback loops. |
Research Methodology
Multi-period observation of film-forming polymer patent filings, REACH substance restriction timelines, and professional channel procurement patterns anchored the trend analysis, supplemented by interviews with formulation scientists at contract manufacturers, regulatory affairs leads at multinational beauty conglomerates, procurement directors at Sephora and Ulta, and bridal services operators in Mumbai and Delhi. Secondary validation drew from ECHA restriction roadmaps, MFDS cosmetic safety filings, FDA labeling guidance documents, and customs trade data for polymer feedstock flows. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product format, ingredient category, end-user archetype, and application use case determined volume and value distribution throughout the forecast period. CAGRs derived from regression analysis of historical professional channel growth rates and regulatory compliance investment cycles. Industry-specific inputs included film production scaling schedules, state-level clean beauty legislation progression, and biodegradable polymer innovation timelines.
Several conditions sit outside the modeled scope, including abrupt ECHA substance ban acceleration, single-source supplier disruption in South Korean production clusters, and platform algorithm changes affecting direct-to-consumer discovery patterns. Forecasts reflect assumptions around reformulation cycle duration and professional channel adoption curves. A model refresh is warranted upon material change in REACH authorization timelines or biodegradable film-former performance parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Facial Massager Market