
 Shavers Market | 2026-2036
Shavers Market Size, Share, and Industry Trends Forecast 2026-2036
Shavers Market Analysis
Subscription bundling of replacement blade cartridges with electric handles is consolidating buyer loyalty and raising switching costs across the shavers industry. Koninklijke Philips N.V. leverages its grooming ecosystem to sustain recurring revenue through proprietary blade systems. Société BIC SA anchors its position in disposable razors through mass-market retail density and price-point accessibility. Xiaomi Corporation competes aggressively via direct-to-consumer channels that undercut traditional premium positioning.
Shavers encompass handheld devices with oscillating or rotating cutter mechanisms, typically employing stainless steel or titanium-coated blades operating at 3,000–14,000 cutting motions per minute to sever facial or body hair at the skin surface. Electric shavers dominate value generation due to higher unit economics and attachment ecosystems, while waterproof feature sets command margin premiums as consumers prioritize wet-dry versatility across bathroom environments. The barber and beauty salon end-user channel represents a concentrated professional segment where durability specifications and commercial warranty terms differentiate procurement decisions.
The EU F-Gas Regulation and REACH chemical compliance frameworks govern refrigerants in cooling-assisted laser hair removal devices and blade coating substances respectively, tightening market access for non-compliant imports. The US FDA oversees medical-grade laser and electrolysis equipment that competes peripherally with traditional shavers, while China's SAMR enforces GB standards for electrical safety in rechargeable appliances. Stakeholders must monitor how battery chemistry regulations and right-to-repair legislation reshape product architecture and aftermarket service obligations.
Market Dynamics
The EU Green Deal's ecodesign requirements are forcing material substitution across blade coatings and motor housings while China's manufacturing scale concentrates upstream supply for lithium-ion power cells.
Growth Catalysts
- REACH chemical compliance:Manufacturers reformulating blade coatings to eliminate restricted substances are capturing preferential shelf placement in European retail chains.
- Barber and beauty salon channel:Professional-grade durability specifications and extended commercial warranties are deepening institutional procurement of cordless rotary systems.
- Titanium-coated blade adoption:Extended edge retention from vapor-deposited coatings is reducing replacement frequency and building recurring attachment revenue streams.
Market Restraints
- Stainless steel input volatility:Aerospace and medical device competition for specialty alloys creates margin compression during commodity price spikes.
- Guangdong-Shenzhen manufacturing concentration:Single-region dependency for precision motor assemblies exposes buyers to logistics disruption and tariff volatility.
- Medical-grade laser substitution:FDA-cleared home laser devices are capturing permanent hair reduction demand among high-income urban demographics.
Strategic Opportunities
- Right-to-repair legislation:EU and US state-level mandates for replaceable batteries and standardized fasteners are opening aftermarket service and spare parts revenue.
- Wet-dry waterproof convergence:IPX7-rated systems are capturing bathroom-counter consolidation as consumers abandon separate dry-only units.
- Direct-to-consumer channel expansion:Subscription blade replenishment models are bypassing traditional retail markups and capturing lifetime value data.
Industry Challenges
- GB standards electrical certification:China's SAMR testing protocols for rechargeable appliances extend product launch timelines by 4-8 months for non-domestic entrants.
- Cross-platform blade incompatibility:Proprietary cartridge geometries fragment aftermarket supply and complicate inventory planning for multi-brand retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shavers Market |
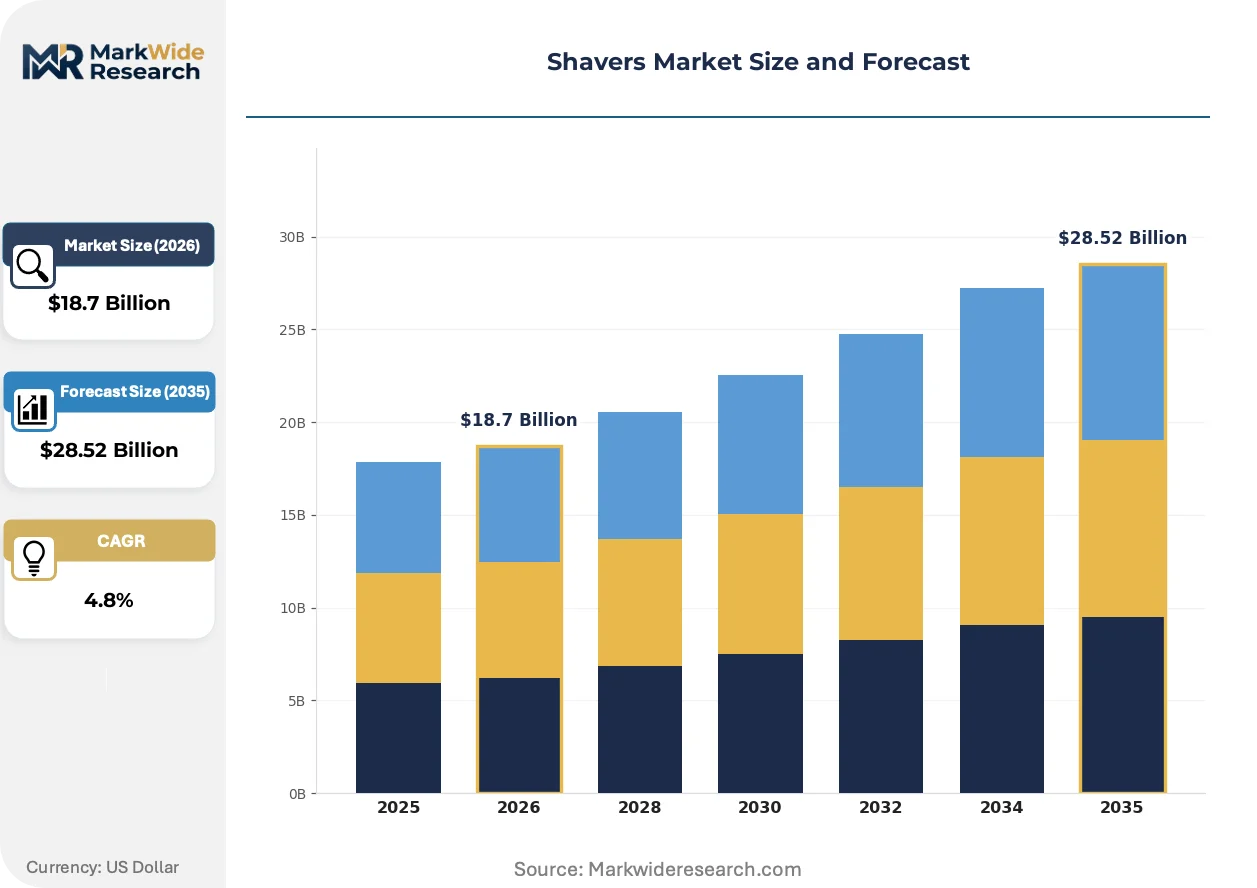
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Shavers, Safety Razors, Disposable Razors, Straight Razors Feature: Waterproof, Rechargeable, Corded, Travel Size End User: Men, Women, Barbers, Beauty Salons Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Drugstores |
| Companies Covered | Wahl Clipper Corporation, Société BIC SA, Koninklijke Philips N.V., Edgewell Personal Care, Spectrum Brands Holdings Inc., The Procter & Gamble Company, Conair Corporation, Xiaomi Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shavers Market Emerging Trajectories
Modular power architectures and sensor-driven personalization are compressing product lifecycles while regulatory pressure on disposability accelerates design-for-repair mandates across major economies.
Self-sharpening blade systems using deposited diamond-like carbon coatings are extending functional lifespans beyond 18 months. Professional barbers in Seoul and São Paulo are adopting these units to reduce downtime. The technology is modularizing maintenance schedules into predictable subscription intervals rather than reactive replacement.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are reshaping cooling-assisted laser hair removal device supply chains. Manufacturers are pivoting to thermoelectric or air-cooled architectures. Medical-grade equipment competing peripherally with traditional shavers faces the steepest redesign costs and certification delays.
Buyers are unbundling after-sales service from hardware procurement, demanding transparent parts pricing and third-party repair access. Mass-market retailers in Berlin and Toronto are piloting in-store blade sharpening stations to recapture foot traffic lost to e-commerce. This behavior is most pronounced among millennial male consumers who treat grooming appliances as durable goods rather than disposable consumables.
Shavers Market Segmentation
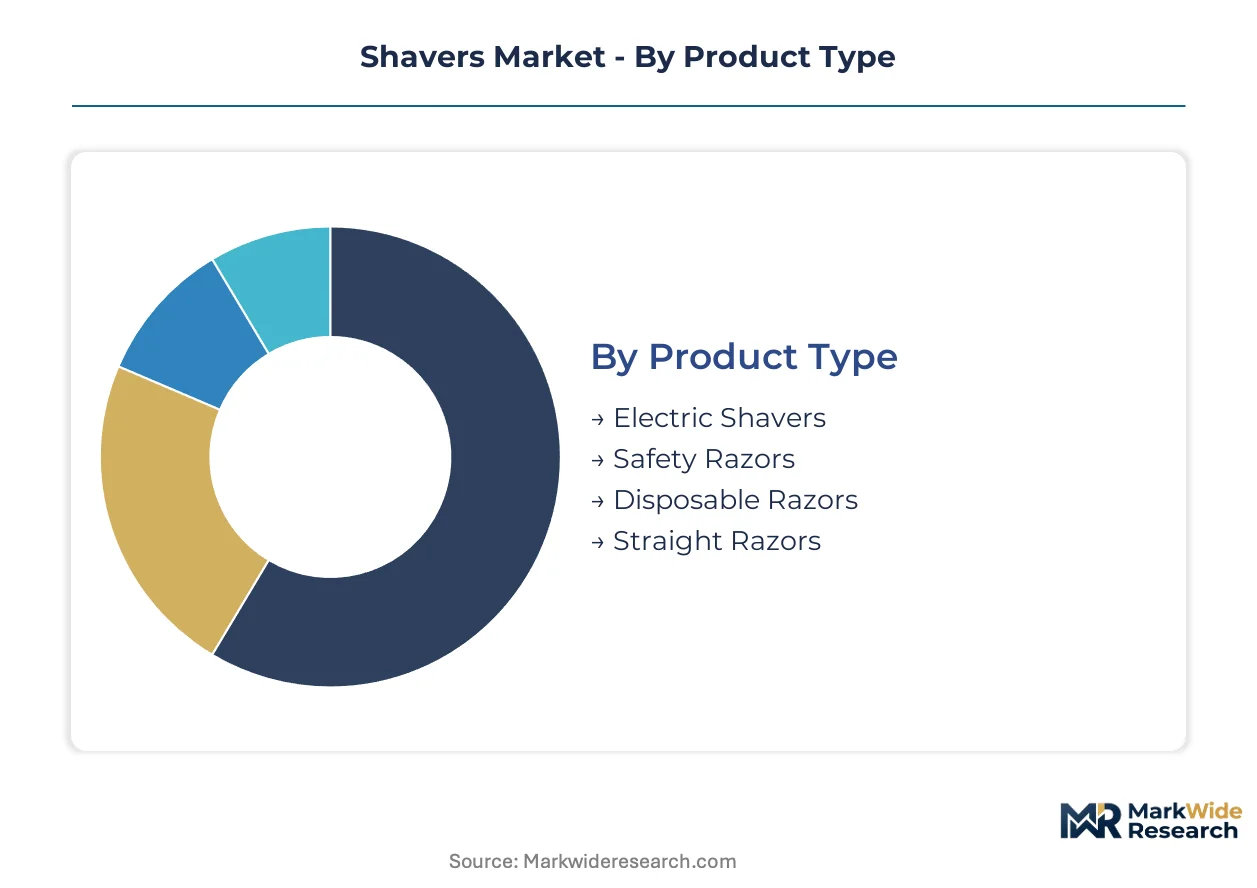
Shavers segment along four dimensions that determine procurement patterns, margin structures, and channel economics. Product type governs replacement frequency and attachment ecosystems. Feature sets command price premiums based on bathroom-use versatility. End-user identity shapes durability specifications and warranty expectations. Distribution channel selection determines brand positioning and customer lifetime value capture.
Product Type:
Price elasticity and replacement cadence separate buyers across this category.
- Electric Shavers:Rotary and foil systems with oscillating cutter mechanisms operating at 3,000–14,000 cutting motions per minute. Men in China and Germany drive demand through e-commerce and specialty retail channels where attachment ecosystems and proprietary blade systems build recurring revenue.
- Safety Razors:Double-edge designs with replaceable blade cartridges. Wet-shaving enthusiasts in the United States and United Kingdom concentrate demand through subscription services and direct-to-consumer platforms that emphasize cost-per-shave economics and reduced plastic waste.
- Disposable Razors:Fixed-blade units for single-use or limited-use applications. Mass-market retail density in Brazil and India supports volume distribution through hypermarkets and drugstores where price-point accessibility dominates procurement decisions.
- Straight Razors:Fixed-blade designs requiring stropping and professional honing. Professional barbers in Japan and Italy maintain demand through specialized supply chains where craftsmanship heritage and extended service intervals justify premium positioning.
Electric shavers lead volumes today; safety razors are gaining share fastest.
Feature:
Use environment and mobility requirements determine feature prioritization.
- Waterproof:IPX7-rated systems enabling wet-dry operation across sink and shower environments. Consumers in South Korea and Australia concentrate demand where bathroom-counter consolidation eliminates separate dry-only units and commands margin premiums.
- Rechargeable:Lithium-ion powered cordless operation with 45–90 minute runtimes. Urban professionals in France and Canada prioritize travel portability and counter clutter reduction, driving preference for USB-C charging compatibility and battery status indicators.
- Corded:Continuous mains-powered operation eliminating battery degradation concerns. Institutional buyers in commercial barbershops across Spain and Mexico select corded units for uninterrupted daily use where power reliability outweighs mobility requirements.
- Travel Size:Compact form factors under 15 centimeters for luggage optimization. Frequent travelers in Singapore and the United Arab Emirates drive demand through airport retail and online channels where TSA compliance and dual-voltage compatibility determine selection.
Waterproof specifications dominate premium positioning; rechargeable systems are expanding most quickly into mid-tier price bands.
End User:
Durability expectations and procurement authority define this segmentation.
- Men:Core consumer segment with facial and body grooming requirements across age demographics. Adoption deepens in China and the United States through subscription bundling of replacement cartridges and ecosystem lock-in via proprietary blade geometries.
- Women:Leg, underarm, and bikini-area grooming with preference for ergonomically contoured handles. Demand concentrates in Germany and Japan through specialty beauty retailers where colorways and grip textures differentiate mass-market from premium positioning.
- Barbers:Professional-grade durability specifications with commercial warranty terms. Cordless rotary systems with titanium-coated blades gain preference in Brazil and Turkey where reduced downtime and extended edge retention support high-volume daily operations.
- Beauty Salons:Institutional procurement with centralized purchasing and service contract requirements. Extended warranty coverage and transparent parts pricing drive vendor selection in Italy and South Korea where third-party repair access is becoming mandatory.
Men represent the largest addressable base; barbers are climbing the fastest as professional channels consolidate procurement.
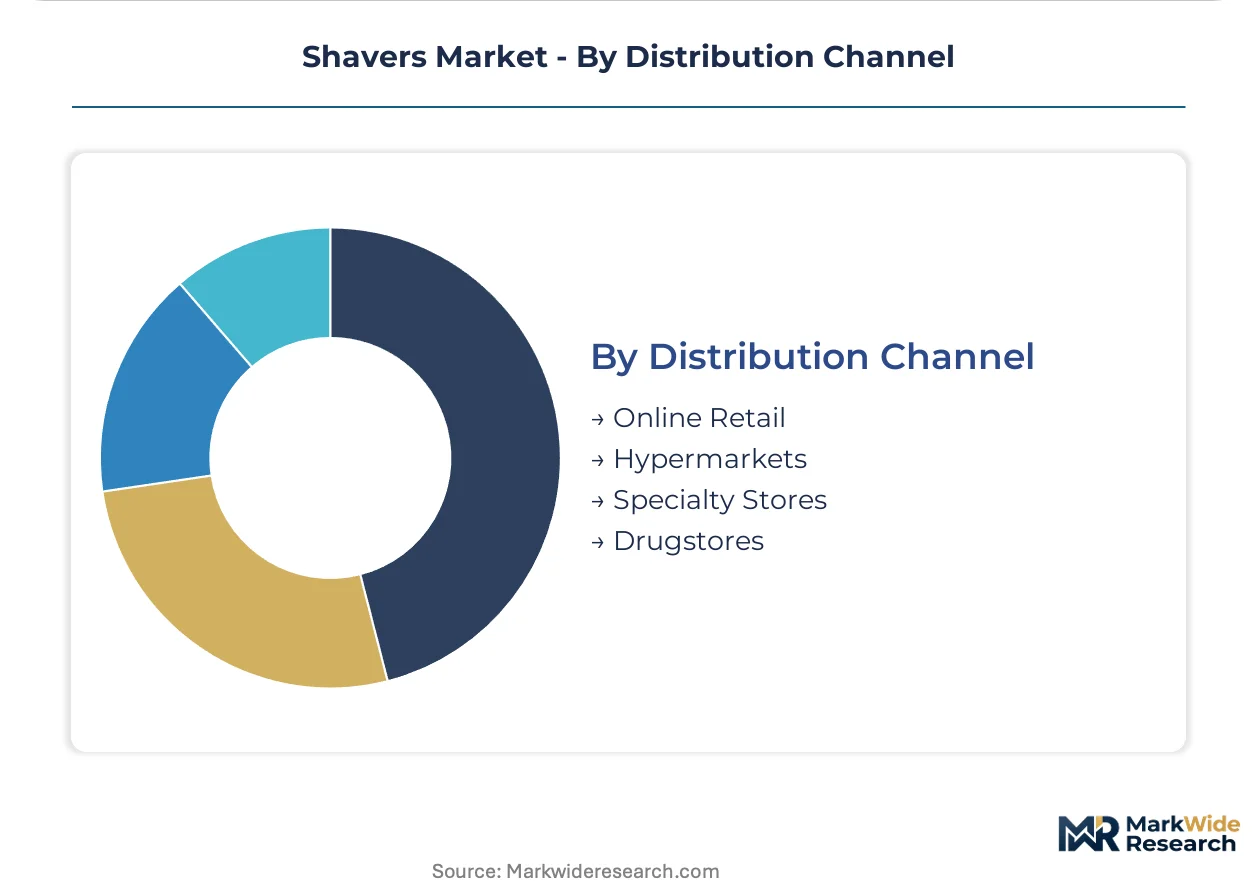
Distribution Channel:
Customer acquisition cost and lifetime value capture vary sharply by channel.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Xiaomi and subscription blade services in China and the United States bypass traditional retail markups and capture usage data for replenishment optimization.
- Hypermarkets:Mass-market retail with high foot traffic and promotional intensity. Société BIC SA anchors disposable razor placement in France and Brazil through shelf-space dominance and price-point accessibility.
- Specialty Stores:Curated assortments with trained staff and demonstration capabilities. Philips and premium grooming ecosystems concentrate in Germany and the United Kingdom where consultative selling supports attachment revenue and brand loyalty.
- Drugstores:Convenience-oriented retail with impulse purchase dynamics. Travel-size and disposable formats dominate in Japan and Canada where proximity purchasing and promotional bundling drive volume.
Online retail leads value generation today; specialty stores are gaining share fastest through ecosystem bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision blade engineering for consumer grooming appliances during the early twentieth century, establishing quality benchmarks that persist across European and Asian manufacturing hubs today. This industrial heritage shapes procurement standards and regulatory frameworks governing personal care equipment worldwide.
China
Domestic manufacturing scale in Guangdong and Zhejiang provinces supplies lithium-ion power cells and precision motor assemblies for cordless rotary systems. SAMR enforces GB standards for electrical safety in rechargeable appliances, extending certification timelines for non-domestic entrants. Shenzhen-based fabricators concentrate wet-dry waterproof production for export markets across Southeast Asia and Europe.
Germany
Wet-shaving enthusiasts drive safety razor demand through subscription services emphasizing cost-per-shave economics and plastic waste reduction. ECHA oversees REACH chemical compliance for blade coatings, restricting substances in vapor-deposited titanium layers. Solingen's blade-making tradition anchors premium straight razor craftsmanship serving professional barbers across Italy and Turkey.
United States
Millennial male consumers treat grooming appliances as durable goods, demanding transparent parts pricing and third-party repair access. FDA oversees medical-grade laser hair removal equipment competing peripherally with traditional shavers. Mass-market retailers in Chicago and Los Angeles pilot in-store blade sharpening stations to recapture foot traffic lost to e-commerce platforms.
Brazil
Professional barbers in São Paulo adopt titanium-coated cordless systems to reduce downtime during high-volume daily operations. ANVISA regulates electrical safety for commercial salon equipment entering the market through Rio de Janeiro port facilities. Hypermarket chains in Minas Gerais sustain disposable razor volume through shelf-space dominance and promotional bundling strategies.
Japan
Specialty beauty retailers in Tokyo and Osaka differentiate women's grooming devices through ergonomic handle contours and colorway customization. METI guides industrial standards for battery chemistry in compact travel-size appliances. Osaka-based manufacturers supply sensor-driven personalization modules compressing product lifecycles across premium electric shaver segments.
Shavers Market Vendor Landscape
The competitive structure tilts toward ecosystem-driven recurring revenue models anchored by proprietary blade geometries. Consolidated positions among diversified personal care conglomerates coexist with agile direct-to-consumer specialists. Three archetypes dominate: integrated grooming ecosystem operators, mass-market disposable specialists, and vertically integrated electronics fabricators. M&A activity concentrates on attachment technology acquisitions, while geographic expansion targets professional barber channels in emerging economies.
Among diversified personal care conglomerates, Koninklijke Philips N.V. and The Procter & Gamble Company exemplify ecosystem-centric positioning through proprietary blade systems and subscription bundling infrastructure. Xiaomi Corporation occupies a distinct tier as a direct-to-consumer electronics specialist leveraging manufacturing scale to undercut traditional premium positioning. Société BIC SA represents the mass-market disposable archetype, anchoring volume distribution through retail density and price-point accessibility across developing economies.
| Leading Market Players |
|---|
| Wahl Clipper Corporation |
| Société BIC SA |
| Koninklijke Philips N.V. |
| Edgewell Personal Care |
| Spectrum Brands Holdings Inc. |
| The Procter & Gamble Company |
| Conair Corporation |
| Xiaomi Corporation |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Proprietary blade geometry lock-in separates premium electric ecosystems from commodity disposable tiers, with the former commanding recurring revenue through cartridge subscriptions while the latter competes on manufacturing scale and retail slotting fees. This bifurcation concentrates margin capture among ecosystem operators who control both handle and blade pricing, while mass-market players absorb input volatility through Guangdong-based fabrication density.
Pricing Analysis
Subscription bundling of replacement cartridges with electric handles anchors the dominant pricing architecture, with premium tiers capturing lifetime value through proprietary geometries while economy tiers compete on per-unit cost. Price differentiation rests on wet-dry waterproof certification and titanium-coated blade longevity. Cost compression in stainless steel inputs is intensifying as aerospace and medical device demand competes for specialty alloys. Mass-market disposable buyers exhibit highest price sensitivity; professional barber channels show lowest sensitivity due to downtime cost calculations.
Supply Chain Analysis
Dual-sourcing mandates from European retailers are forcing qualification of alternative motor suppliers beyond Guangdong-Shenzhen concentration. Precision motor assemblies and lithium-ion power cells draw from China, Japan, and South Korea. Raw material dependencies include stainless steel alloys, titanium vapor-deposition feedstock, and rare-earth magnetic components. Single-region vulnerability for precision motor assemblies exposes buyers to logistics disruption and tariff volatility. Distribution runs through direct-to-consumer platforms, hypermarket chains, and specialty retail with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shavers market functions as a stable compounder, with replacement blade economics and ecosystem lock-in generating predictable recurring revenue streams that smooth demand cyclicality.
For Market Incumbents: Cement ecosystem loyalty through proprietary blade geometry patents and subscription replenishment infrastructure that raises switching costs. Deepen vertical integration into precision motor production to reduce Guangdong-Shenzhen concentration risk. Prioritize wet-dry waterproof certification investment to capture bathroom-counter consolidation demand and defend margin position against direct-to-consumer entrants. For New Entrants and Emerging Players: Begin with unbundled aftermarket service offerings targeting millennial male consumers who treat grooming appliances as durable goods and demand transparent parts pricing. Professional barber channels in Brazil and Turkey present the most penetrable white-space, with titanium-coated cordless systems reducing downtime cost. Deploy direct-to-consumer subscription models that bypass traditional retail markups and capture usage data for replenishment optimization. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary blade technology and subscription infrastructure create durable competitive moats with predictable cash flow profiles. Target acquisition archetypes include specialist coating technology providers and regional direct-to-consumer platforms with established replenishment algorithms. Watch for right-to-repair legislation acceleration as an inflection signal that would reshape aftermarket service economics and parts pricing transparency.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Blade System Expansion | Ecosystem lock-in through cartridge geometry patents captures recurring revenue and raises rival switching costs. |
| Direct-to-Consumer Channel Launch | Xiaomi's bypass of traditional retail markups demonstrates margin capture potential through data-driven replenishment. |
| Titanium Coating Technology Acquisition | Vapor-deposition expertise extends blade lifespan beyond 18 months and supports professional barber channel penetration. |
| Wet-Dry Waterproof Certification Investment | IPX7-rated systems command bathroom-counter consolidation premiums and eliminate separate dry-only unit demand. |
| Right-to-Repair Service Infrastructure | EU and US state-level mandates for replaceable batteries and standardized fasteners open aftermarket parts revenue streams. |
Methodological Framework
Coverage spans China, Germany, the United States, Brazil, and Japan, with primary inputs from each market informing demand patterns and regulatory constraints. The research combines structured interviews with product managers at grooming appliance manufacturers, procurement leads at professional barber supply chains, regulatory affairs specialists navigating REACH and GB standards, and category buyers at mass-market retailers. Secondary validation draws from SAMR electrical safety filings, ECHA chemical restriction updates, FDA laser equipment clearances, and retail audit data tracking attachment ecosystem penetration. Bottom-up demand modeling and top-down macroeconomic triangulation ensure consistency across volume and value outputs.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product type (electric, safety, disposable, straight), feature configuration (waterproof, rechargeable, corded, travel-size), end-user identity (men, women, barbers, beauty salons), and distribution channel (online retail, hypermarkets, specialty stores, drugstores). CAGRs derive from regression analysis of historical replacement cycles, subscription adoption curves, and professional channel procurement patterns. Industry-specific inputs include lithium-ion battery cost trajectories and titanium coating technology diffusion rates.
Several conditions sit outside the modeled scope, including abrupt raw material price spikes in specialty stainless steel alloys, geopolitical disruption of Guangdong-Shenzhen manufacturing corridors, and accelerated medical-grade laser substitution among high-income demographics. Deviation in right-to-repair legislative timelines or REACH chemical restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Global Canes and Walking Sticks Market