
 Shoe Deodorizer Market | 2026-2036
Shoe Deodorizer Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Deodorizer Market Analysis
Athletic footwear production is realigning toward integrated hygiene solutions as performance brands demand factory-applied odor control. S.C. Johnson & Son Inc. leverages its aerosol manufacturing infrastructure to supply private-label deodorizers to major shoe brands. Reckitt Benckiser sustains retail shelf dominance through multi-channel distribution networks spanning supermarkets and e-commerce platforms. Adidas AG anchors demand from the brand side, specifying antimicrobial treatments across its performance and lifestyle lines.
Shoe deodorizers are formulated products designed to neutralize or absorb malodorous compounds generated by bacterial decomposition of perspiration within footwear enclosures, typically delivered through spray propellant systems, porous insert substrates, or powder dispersions containing activated carbon or biocidal agents. Spray formulations lead volume sales through immediate efficacy and familiar application mechanics, though charcoal-based inserts capture expanding margin pools as consumers prioritize reusable, plastic-reducing alternatives. Essential oil segments compete on natural-positioning differentiation, while antimicrobial agent formulations face formulation cost pressures despite superior persistent protection.
The EPA governs volatile organic compound limits in aerosol shoe deodorizers, compelling reformulation toward compressed gas or pump-spray delivery systems. REACH compliance in Europe restricts certain biocidal actives, redirecting R&D toward enzymatic and plant-derived odor neutralization pathways. Stakeholders must monitor evolving chemical substance registrations across the EPA and ECHA frameworks, as regulatory divergence between the United States and European Union threatens to fragment product portfolios and testing requirements.
Market Dynamics
Athletic footwear manufacturers now specify factory-applied antimicrobial treatments as standard procurement terms, compressing aftermarket deodorizer margins while redirecting R&D toward integrated hygiene systems and sustainable substrate materials.
Growth Catalysts
- REACH biocidal restrictions:European chemical regulations are accelerating enzymatic and plant-derived formulation development, opening premium positioning for compliant suppliers.
- Activated carbon substrate innovation:Reusable charcoal inserts are capturing consumer preference shifts toward plastic-reducing alternatives with extended lifecycles.
- German leather care traditions:Premium heritage markets sustain specialized deodorizer demand for high-end footwear maintenance protocols.
Market Restraints
- Propellant reformulation costs:EPA volatile organic compound limits force compressed gas and pump-spray retooling, elevating production expenses.
- Supply concentration in aerosol infrastructure:Manufacturing capacity clusters with legacy spray equipment owners, constraining substrate diversification.
- Essential oil efficacy limitations:Natural-positioned products demonstrate shorter odor-neutralization persistence versus synthetic biocidal alternatives.
Strategic Opportunities
- Private-label athletic partnerships:Performance brands seek white-label deodorizer supply for retail accessory programs and direct-to-consumer bundles.
- Subscription refill models:Charcoal insert replenishment services create recurring revenue streams through e-commerce direct channels.
- EU Green Deal alignment:Biodegradable packaging mandates favor compostable substrate developers with certified circular supply chains.
Industry Challenges
- Cross-regulatory testing fragmentation:Divergent EPA and ECHA substance registration requirements multiply certification timelines and portfolio complexity.
- Legacy aerosol equipment stranded assets:Capital-intensive plant retooling for compressed gas systems demands multi-year depreciation recovery.
- Biocidal active ingredient sourcing:REACH-restricted compound substitution requires reformulation expertise scarce among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Deodorizer Market |
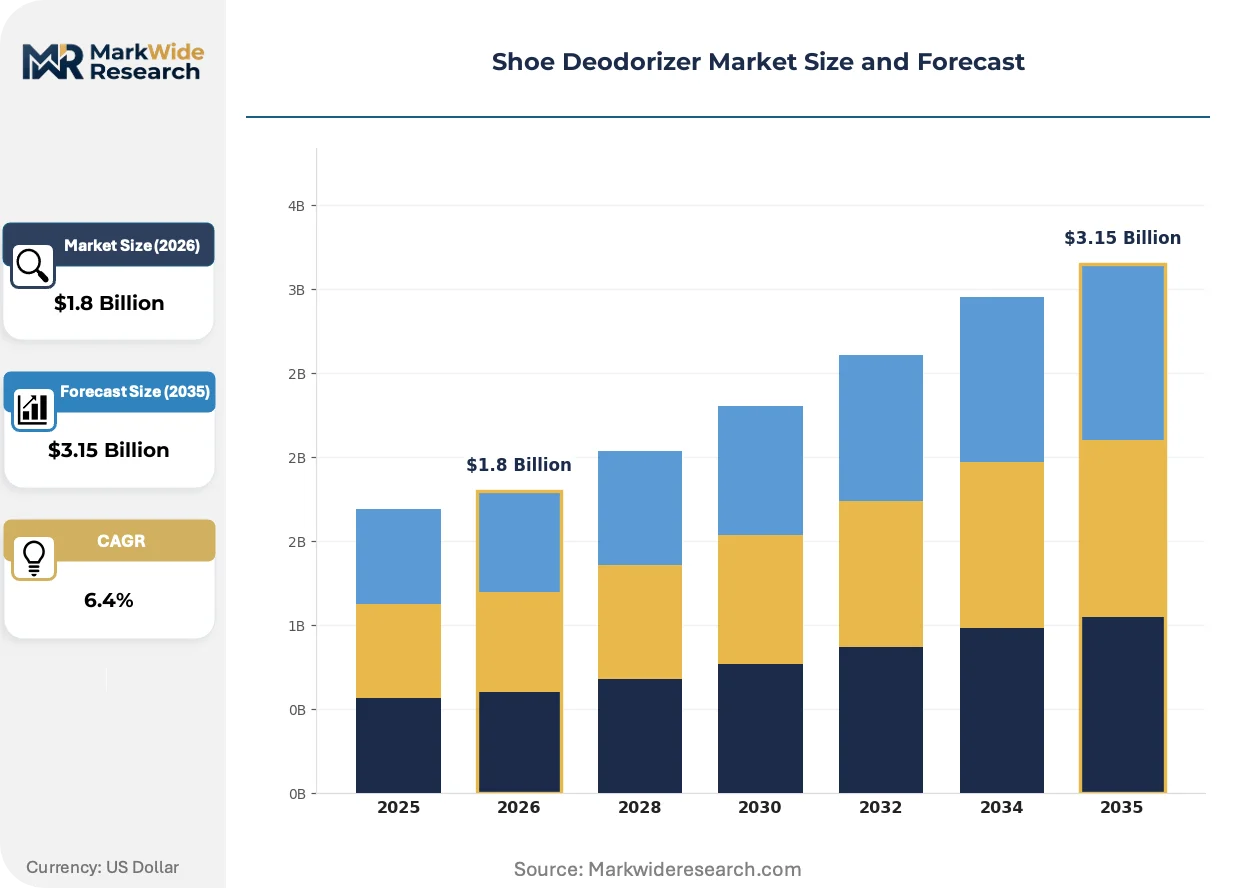
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Powder, Inserts, Wipes Active Ingredient: Baking Soda, Charcoal, Essential Oils, Antimicrobial Agents Packaging Type: Aerosol Can, Bottle, Pouch, Box End User: Consumers, Retailers, Manufacturers, Wholesalers |
| Companies Covered | Blistex Inc., Grangers International Ltd., S.C. Johnson & Son Inc., Griffin Brands Inc., Fiebing Co. Inc., Reckitt Benckiser, Adidas AG, StinkBOSS, Angelus Shoe Polish, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Deodorizer Market Emerging Trajectories
Formulation chemistry and delivery mechanisms are diverging sharply between regulatory jurisdictions, while buyer preferences split between immediate efficacy and sustainability credentials. This tension is forcing parallel product development tracks.
Enzymatic odor neutralization technology is integrating bacterial decomposition interruption at the molecular level. Athletic footwear brands are specifying these treatments for factory application across performance lines. The shift is compressing aftermarket spray volumes while elevating technical service requirements for substrate suppliers.
REACH biocidal product regulations are restricting quaternary ammonium compounds and certain silver-based actives across European formulations. Manufacturers are redirecting R&D budgets toward plant-derived alternatives and probiotic-based competitive inhibition systems. German and French formulators face the steepest compliance curves given their premium positioning reliance on persistent protection claims.
Direct-to-consumer subscription models are displacing supermarket impulse purchases for insert-based products. Charcoal substrate suppliers are building proprietary replenishment apps and loyalty programs to capture lifetime value. This behavioral shift concentrates most visibly in urban United States markets where e-commerce penetration in personal care accessories exceeds traditional retail channels.
Shoe Deodorizer Market Segmentation
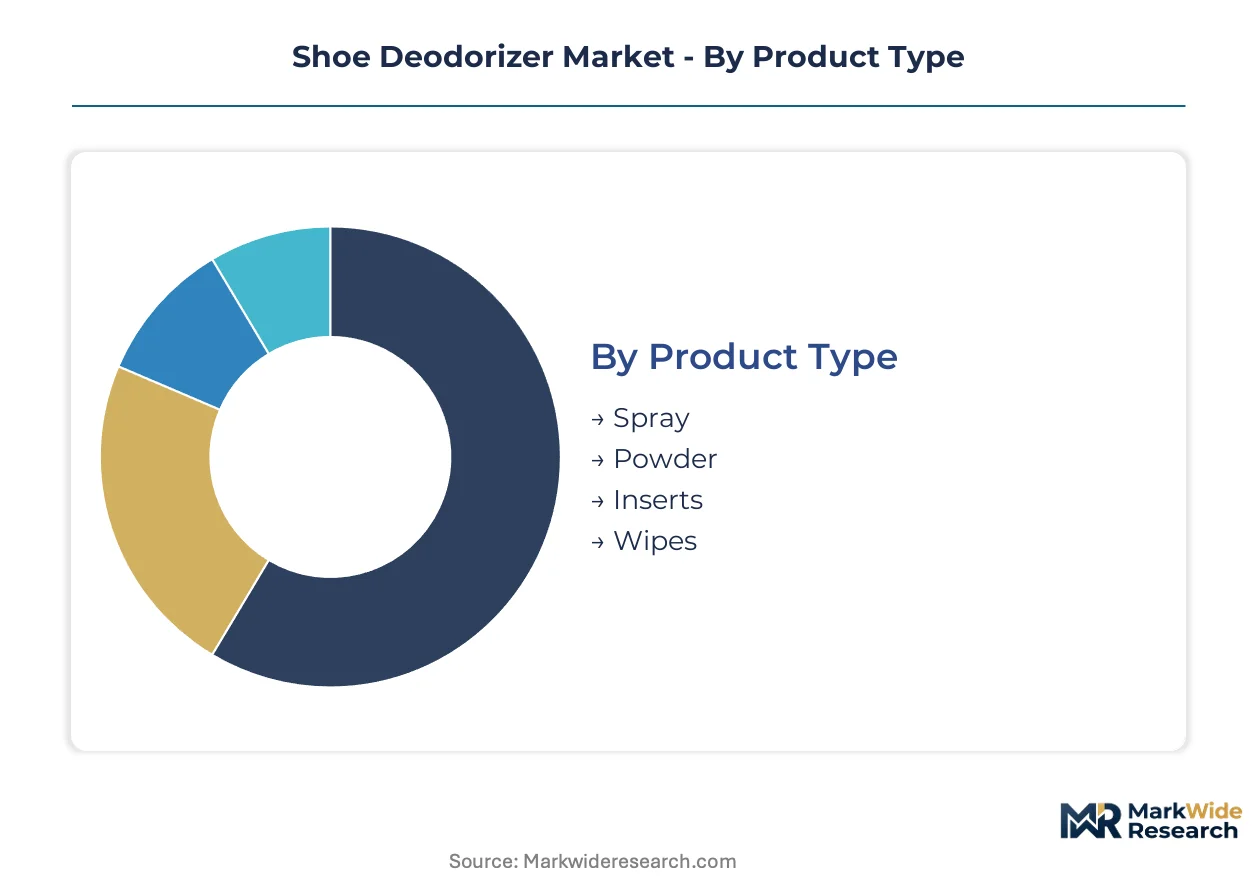
Shoe deodorizer buyers diverge sharply between immediate efficacy seekers and sustainability-focused purchasers, forcing suppliers to maintain parallel formulation portfolios. Segmentation reveals how regulatory pressure and application context reshape procurement priorities across delivery formats and active chemistry platforms.
Product Type:
Application frequency and reusability expectations separate buyers in this dimension, with athletic users prioritizing speed and heritage footwear owners favoring longevity.
- Spray:Propellant-based systems deliver instant odor neutralization through atomized biocidal or enzymatic mist. Demand clusters in United States mass retail channels where convenience positioning drives impulse purchases, though EPA volatile organic compound limits are forcing compressed gas retooling that elevates unit costs.
- Inserts:Porous substrates—activated carbon, zeolite, or mineral clay—absorb moisture and malodorous compounds through passive diffusion. German and French premium footwear maintenance protocols sustain specialized demand for reusable charcoal variants that align with plastic-reduction preferences.
- Powder:Fine-particulate formulations containing baking soda or talc absorb perspiration residue through capillary action. Bulk procurement by athletic facility operators and team equipment managers concentrates volumes.
- Wipes:Pre-moistened towelettes impregnated with quick-drying sanitizing agents target travel and gym bag applications. Single-use positioning limits adoption against reusable alternatives.
Spray leads volumes today; inserts are gaining share fastest.
Active Ingredient:
Chemistry selection tracks regulatory jurisdiction more than end-use, with European formulators accelerating plant-derived substitution under REACH biocidal restrictions.
- Baking Soda:Sodium bicarbonate neutralizes acidic odor compounds through pH modification, offering low-cost, broadly compatible formulation. Mass-market powder and spray applications in United States dollar stores and supermarket channels sustain baseline volumes despite limited persistence.
- Charcoal:Activated carbon substrates adsorb volatile organic compounds through micropore surface area exceeding 500 square meters per gram. Japanese and South Korean consumers drive premium positioning for bamboo-derived variants with certified regeneration cycles.
- Essential Oils:Tea tree, eucalyptus, and lavender extracts compete on natural-positioning differentiation. Efficacy limitations against persistent bacterial colonies constrain penetration in athletic applications.
- Antimicrobial Agents:Quaternary ammonium compounds, silver ions, and triclosan derivatives interrupt bacterial metabolism. REACH restrictions across European Union member states are redirecting R&D toward enzymatic alternatives.
Antimicrobial agents dominate value capture; charcoal is climbing the fastest.
Packaging Type:
Container selection reflects distribution channel economics and shelf-life requirements, with e-commerce penetration favoring lightweight, shatter-resistant formats.
- Aerosol Can:Pressurized metal containers enable fine mist delivery with extended shelf stability. United States manufacturing infrastructure concentration with legacy equipment owners constrains substrate diversification timelines.
- Bottle:Pump-spray and squeeze dispensers accommodate thicker gel or liquid formulations. German private-label suppliers favor recyclable PET with post-consumer content for retail brand alignment.
- Pouch:Flexible film packaging reduces shipping cube and material weight for direct-to-consumer subscription models. Charcoal insert replenishment services in urban United States markets favor compostable certified structures.
- Box:Rigid paperboard containers house pre-measured powder sachets or insert pairs. Premium unboxing experiences support gifting positioning in Japanese department store channels.
Aerosol can leads installed base; pouch is expanding most quickly.
End User:
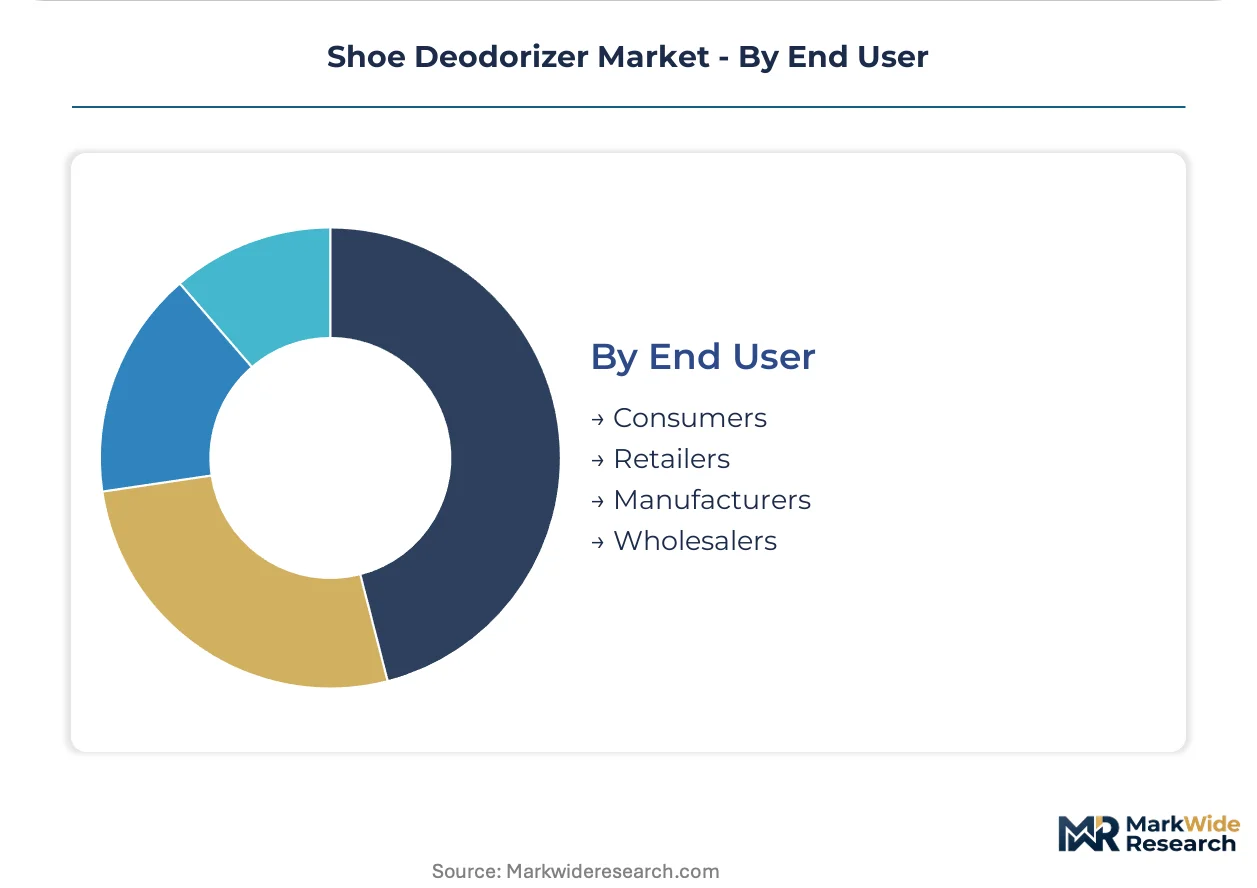
Procurement authority and volume scale define this split, with manufacturers capturing factory-applied treatments and retailers building private-label accessory programs.
- Consumers:Individual purchasers selecting retail or direct-channel products for personal footwear maintenance. Subscription refill adoption concentrates among urban millennials in United States and German metropolitan markets.
- Retailers:Supermarkets, sporting goods chains, and e-commerce platforms sourcing private-label or branded inventory. Multi-channel distribution networks spanning Walmart, Amazon, and Decathlon sustain shelf dominance for established suppliers.
- Manufacturers:Athletic footwear brands specifying antimicrobial finishing systems for factory application. Adidas AG and comparable performance labels now mandate integrated odor control as standard procurement terms.
- Wholesalers:Distributors aggregating bulk volumes for institutional buyers including hotels, gyms, and team sports organizations. Price compression and logistics efficiency requirements favor standardized aerosol and powder formats.
Consumers generate transaction volume; manufacturers are capturing value fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the United States and European Union is reshaping production geography as manufacturers seek cost-of-compliance arbitrage. EPA volatile organic compound limits and REACH biocidal restrictions create divergent formulation requirements that favor localized production clusters.
United States
Mass retail channels and athletic footwear culture sustain spray-format dominance. EPA regulations governing aerosol propellants force compressed gas retooling investments. Manufacturing concentrates in legacy aerosol infrastructure corridors around Chicago and New Jersey industrial zones.
Germany
Premium leather care traditions and heritage footwear maintenance protocols sustain specialized insert demand. REACH compliance requirements accelerate enzymatic formulation development. Formulation R&D clusters in Cologne-Düsseldorf chemical corridor with proximity to ECHA regulatory expertise.
China
Contract manufacturing capacity for activated carbon substrates scales rapidly to serve export markets. National standards on volatile organic compound emissions in consumer products tighten compliance requirements. Production gravity centers on Zhejiang and Guangdong provinces with bamboo-derived charcoal innovation.
Japan
Department store gifting channels and unboxing experience expectations sustain premium packaging formats. METI guidelines on chemical substance management influence formulation choices. Tokyo-Osaka corridor hosts specialized substrate suppliers serving luxury footwear brands.
France
Natural-positioning consumer preferences sustain essential oil segment development despite efficacy limitations. ANSM oversight of biocidal products restricts certain active ingredients. Lyon-based formulators specialize in plant-derived odor neutralization pathways for compliant export formulations.
Shoe Deodorizer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf presence commanding premium positioning in spray formats while substrate innovation favors agile material suppliers. The market exhibits moderate concentration at the branded tier with fragmentation among private-label contract producers. Three archetypes dominate: multinational consumer goods conglomerates with aerosol infrastructure, athletic footwear brands integrating factory-applied treatments, and specialized substrate developers building direct-to-consumer subscription channels. Competitive moves center on regulatory compliance portfolio diversification and e-commerce channel capture.
Among multinational consumer goods conglomerates, S.C. Johnson & Son Inc. and Reckitt Benckiser occupy positions exemplifying scale-driven retail distribution dominance. Adidas AG represents the athletic brand archetype specifying integrated hygiene systems. These three entities anchor the competitive structure by embodying distinct strategic vectors: aerosol manufacturing infrastructure, multi-channel retail shelf access, and factory-applied antimicrobial procurement authority.
| Leading Market Players |
|---|
| Blistex Inc. |
| Grangers International Ltd. |
| S.C. Johnson & Son Inc. |
| Griffin Brands Inc. |
| Fiebing Co. Inc. |
| Reckitt Benckiser |
| Adidas AG |
| StinkBOSS |
| Angelus Shoe Polish |
| Others |
Supply Flow & Price Mechanics
Premium charcoal insert tiers diverge from mass-market aerosol formats by certification grade and reusability claims, with that bifurcation manifesting in both pricing power and supply chain configurations. German private-label suppliers command margin premiums through post-consumer PET packaging and ECHA-aligned enzymatic formulations, while United States contract manufacturers absorb compressed gas retooling costs without corresponding price recovery.
Pricing Analysis
Distributor margin layers compress most acutely in supermarket channels where Reckitt Benckiser and S.C. Johnson & Son Inc. sustain shelf access through promotional fund pools. Three-tier pricing structure across premium, standard, and economy levels tracks active ingredient persistence and packaging format, with enzymatic formulations in recyclable bottles capturing 40-60 point spreads over baking soda powders. Cost compression in aerosol tiers is intensifying because EPA volatile organic compound compliance demands multi-year equipment depreciation. Athletic footwear manufacturers exhibit lowest price sensitivity given factory-applied antimicrobial specifications, while dollar store consumers in United States mass retail drive hardest bargain hunting.
Supply Chain Analysis
Activated carbon feedstock rests on Zhejiang and Guangdong province bamboo processors in China, German chemical corridor enzymatic formulators, and Japanese specialty carbon activation facilities. Key inputs span microporous carbon substrates with 500+ square meter per gram surface area, compressed gas propellant systems, and plant-derived biocidal actives subject to REACH substitution timelines. Single-source vulnerability concentrates in Chinese bamboo charcoal supply where export quota fluctuations disrupt replenishment cycles for United States subscription services. Distribution runs through sporting goods chains, Amazon direct-to-consumer fulfillment, and Adidas AG factory-direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enzymatic formulation premiums and subscription refill economics, justified by REACH-driven biocidal substitution costs that compliant suppliers pass through with limited pushback.
For Market Incumbents: Anchor aerosol infrastructure value through compressed gas retooling completion ahead of EPA enforcement phases, while acquiring enzymatic formulation capabilities scarce among mid-tier competitors. Threat substitution from probiotic-based competitive inhibition systems demands R&D redirection toward bacterial decomposition interruption at molecular level. Certification investment in EU Green Deal-aligned compostable packaging secures channel access as German and French retailers tighten sustainability procurement terms. For New Entrants and Emerging Players: Begin with direct-to-consumer charcoal insert subscriptions in urban United States markets where e-commerce penetration in personal care accessories exceeds traditional retail velocity. White-space targets include athletic facility bulk powder procurement and Japanese department store gifting channels demanding premium unboxing experiences. Go-to-market angle centers on certified regeneration cycle transparency for bamboo-derived activated carbon substrates. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance expertise fragments across Cologne-Düsseldorf chemical corridor formulators and Lyon-based plant-derived specialists. Long-term viability favors acquisition targets with captive enzymatic R&D pipelines and established ECHA regulatory affairs capabilities. Signal to watch: Adidas AG and comparable performance brands expanding factory-applied antimicrobial specifications to lifestyle footwear lines, compressing aftermarket volumes faster than projected.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Formulation Development | REACH biocidal restrictions redirect R&D budgets toward compliant odor neutralization pathways. |
| Compressed Gas Retooling | EPA volatile organic compound limits force multi-year capital deployment for aerosol infrastructure owners. |
| Subscription Refill Model Launch | Direct-to-consumer charcoal replenishment captures lifetime value in urban United States markets. |
| Compostable Packaging Certification | EU Green Deal alignment secures retail shelf access across German and French premium channels. |
| Factory-Applied Treatment Partnership | Adidas AG procurement specifications create captive demand for integrated antimicrobial finishing systems. |
Methodological Framework
Direct dialogue with brand managers at consumer goods conglomerates, category buyers at sporting goods retailers, enzymatic formulation chemists in German chemical corridor, and supply planners at activated carbon substrate developers grounded qualitative findings. Secondary validation drew from EPA regulatory filings, ECHA biocidal product registrations, Nielsen retail audit data for personal care accessories, and customs records tracking bamboo charcoal export volumes. Bottom-up demand modeling triangulated against top-down category spend analysis.
Top-down macroeconomic framing anchored volume projections while bottom-up SKU-level data refined segment splits across spray, insert, powder, and wipe formats. Segmentation dimensions modeled include product type, active ingredient chemistry, packaging format, and end-user procurement authority, with regulatory jurisdiction overlay capturing EPA and ECHA divergence. CAGRs derived from historical trajectory analysis adjusted for propellant reformulation cost absorption and subscription model penetration curves. Industry-specific inputs incorporated athletic footwear production forecasts and REACH biocidal restriction phase-in timelines.
Several conditions sit outside the modeled scope, including sudden EPA enforcement acceleration, ECHA substance ban list expansion beyond quaternary ammonium compounds, and raw material price spikes in activated carbon feedstock. Forecasts reflect assumptions on regulatory implementation pacing and consumer willingness-to-pay for sustainability credentials. A small set of named triggers warrants ongoing watch: Adidas AG factory-applied treatment mandate expansion, Chinese bamboo charcoal export quota adjustments, and compressed gas propellant supply bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Smart Hairbrush Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Electrical Neck Warmer Market