
 Disposable Razor Blades Market | 2026-2036
Disposable Razor Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Razor Blades Market Analysis
Asset-light direct-to-consumer leasing and subscription financing is fragmenting competitive dynamics in the disposable razor blades space. Procter & Gamble leverages its manufacturing scale to sustain cost advantages across mass-market cartridge lines. Harry's competes through channel control, operating primarily via digital subscriptions that bypass traditional retail markups. Edgewell Personal Care anchors its position through brand strength in drugstore and supermarket distribution networks.
Disposable razor blades are precision-ground metal edges, typically stainless steel or carbon steel, mounted in plastic or metal housings with lubrication strips; they are manufactured through stamping, grinding, and coating processes to achieve sharpness measured in edge radii below 50 nanometers for safe consumer hair removal. Cartridge systems dominate value pools due to recurring blade replacement purchases, while double-edge formats sustain niche demand among traditional wet-shaving enthusiasts and professional barbers. Stainless steel leads material selection for corrosion resistance, though alloy compositions are gaining traction in premium positioning segments.
FDA regulates blade safety and labeling claims in the United States, while REACH governs chemical composition of coatings and lubricants across European markets; both frameworks elevate compliance costs but also barrier entry for non-compliant imports. BIS certification requirements in India affect market access for imported blade assemblies. Stakeholders must monitor evolving material restrictions and subscription-channel tax classifications as regulatory scope expands beyond traditional product safety into environmental disposal mandates.
Market Dynamics
Subscription-based direct-to-consumer distribution is fragmenting traditional retail dominance in disposable razor blades, forcing incumbents to restructure channel economics while specialty barber-grade formats capture premium positioning.
Growth Catalysts
- Urban male grooming expansion:Indian metropolitan consumers are shifting from single-blade traditional razors toward cartridge systems, creating sustained replacement demand.
- REACH compliance elevation:European chemical safety mandates for lubrication strip formulations are accelerating R&D investment in biocompatible coating alternatives.
- Barber-grade specialization:Professional wet-shaving establishments across Turkey, Italy, and Japan are driving demand for precision-ground double-edge formats.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for corrosion-resistant alloys compress margin predictability for mass-market cartridge producers.
- FDA labeling friction:United States safety claim verification requirements extend product launch timelines and elevate compliance expenditure.
- Electric substitution threat:Battery-powered facial trimmers from grooming appliance manufacturers are capturing convenience-oriented users in North American and Western European households.
Strategic Opportunities
- BIS certification pathways:India's quality standard harmonization creates accessible entry for compliant foreign blade assembly suppliers.
- Biodegradable handle convergence:Plant-fiber reinforced plastics combined with metal blade recycling programs address emerging EU Green Deal disposal mandates.
- Specialized dermatological formats:Sensitive-skin lubrication formulations for post-chemotherapy or eczema-prone users represent underserved therapeutic positioning.
Industry Challenges
- Precision grinding skill scarcity:Edge radius control below 50 nanometers requires specialized metallurgical expertise concentrated in Solingen, Germany and Seki, Japan.
- Coating equipment capex intensity:Physical vapor deposition systems for blade surface treatments demand seven-figure capital commitments with extended depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Razor Blades Market |
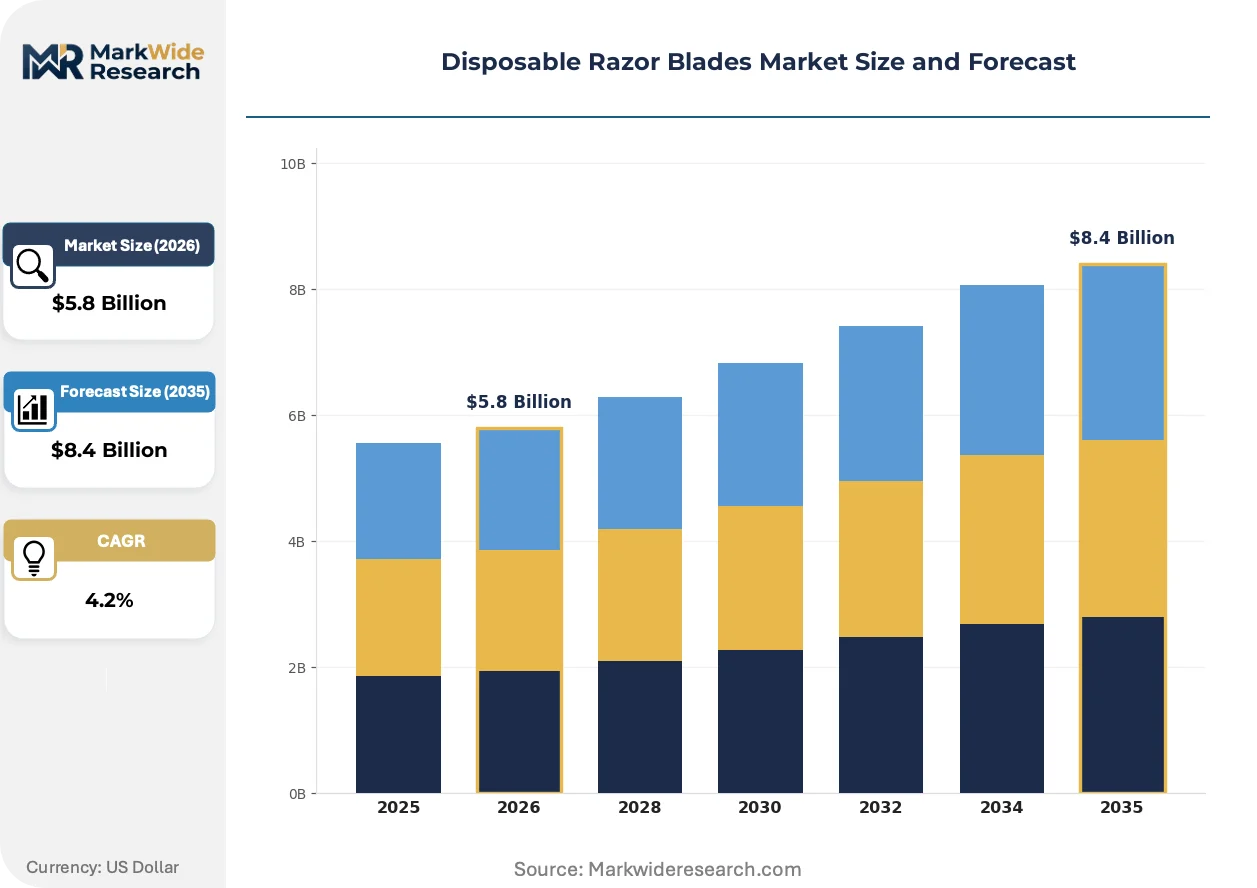
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Edge, Cartridge, Straight Edge, Single Edge Material: Stainless Steel, Carbon Steel, Plastic, Alloy Customer Type: Men, Women, Barbers, Retailers Distribution Channel: Online, Supermarkets, Drugstores, Convenience Stores |
| Companies Covered | Procter & Gamble, Edgewell Personal Care, BIC Group, Dorco, Kai Group, Super-Max, Lord International, Feather Safety Razor, Harry's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Razor Blades Market Emerging Trajectories
Coating chemistry breakthroughs and regulatory material restrictions are simultaneously enabling premium positioning and forcing formulation overhauls across lubrication strip technologies.
Atomic layer deposition for blade edge coatings is rendering obsolete traditional polymer-based lubrication strips in premium cartridge systems. High-end grooming subscription services in Scandinavia and South Korea are adopting these friction-reducing surfaces at accelerated replacement cycles. The technology is rendering obsolete conventional three-to-five blade stacking architectures by enabling comparable shave quality with fewer cutting elements.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling European manufacturers to reformulate hydrophobic blade coatings. Industrial consequence includes accelerated qualification timelines for silicone and ceramic-based alternatives. German and French personal care brands are most affected, responding with supply chain regionalization to maintain EU market access.
Direct-to-consumer subscription bundling is compressing traditional retail replenishment cycles. Drugstore and supermarket blade aisles in United States and United Kingdom are experiencing volume displacement as locked-in delivery schedules reduce impulse purchase frequency. Urban Indian millennials represent the fastest-adopting demographic for this channel shift, bypassing established distribution hierarchies entirely.
Disposable Razor Blades Market Segmentation
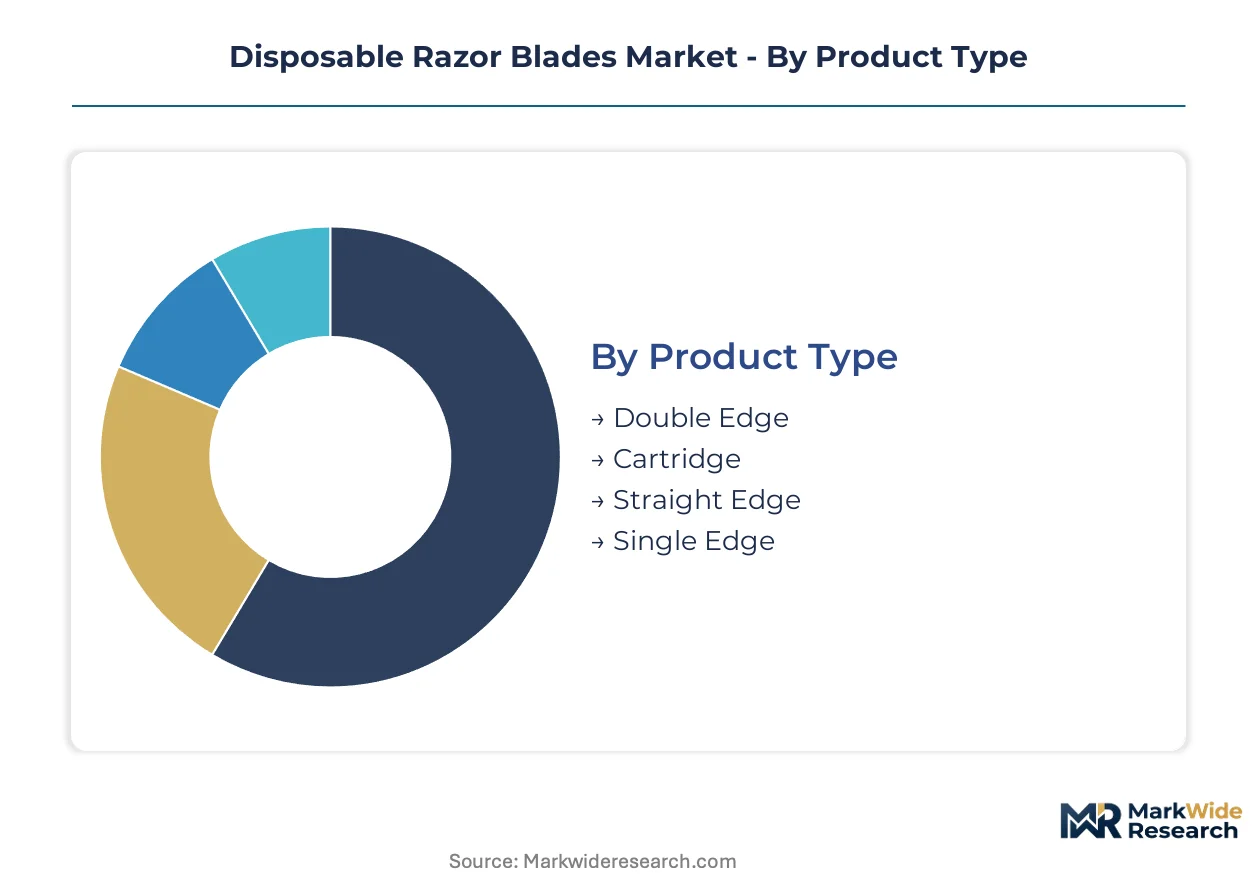
Segmentation in disposable razor blades reveals divergent replacement economics and channel strategies. Cartridge systems generate recurring revenue through locked-in handle platforms, while specialty formats command premium positioning in professional settings.
Product Type:
Replacement cycle velocity separates mass-market convenience from artisanal durability, with subscription models compressing repurchase intervals across formats.
- Cartridge:Multi-blade plastic housings with pivoting heads and lubrication strips dominate household bathroom counters. Indian urban millennials are shifting from single-blade traditions toward cartridge systems, sustained by grooming subscription services that bypass retail markups entirely.
- Double Edge:Precision-ground stainless steel blades in reusable metal handles serve wet-shaving enthusiasts and professional barbers. Turkish, Italian, and Japanese barber-grade establishments drive sustained demand for these formats, valuing edge control and per-blade cost efficiency over convenience.
- Straight Edge:Fixed-blade implements requiring stropping and honing expertise sustain niche professional use in high-end grooming establishments.
- Single Edge:Disposable safety razor formats with guarded blade exposure serve institutional and travel segments where simplicity outweighs performance optimization.
Cartridge dominates installed base. Double Edge is where expansion concentrates among professional and enthusiast segments.
Material:
Corrosion resistance and edge retention properties determine material selection, with coating compatibility emerging as a secondary filter under tightening chemical regulations.
- Stainless Steel:Chromium-alloyed grades resist oxidation in humid bathroom environments while maintaining sub-50 nanometer edge radii. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are accelerating reformulation of hydrophobic coatings for these blades across German and French supply chains.
- Carbon Steel:Higher hardness enables sharper initial edges but demands protective oiling or advanced coatings to prevent corrosion. Japanese Seki and German Solingen grinding clusters concentrate metallurgical expertise for these precision applications.
- Plastic:Handle substrates and guard structures employ glass-filled polypropylene or biodegradable fiber reinforcements to address EU Green Deal disposal mandates.
- Alloy:Cobalt or titanium-enhanced compositions target premium positioning segments where edge longevity justifies material cost premiums.
Stainless Steel anchors volume production. Alloy compositions are climbing the fastest in premium subscription channels.
Customer Type:
Usage intensity and price sensitivity diverge sharply between personal consumers and professional procurement, reshaping packaging and distribution economics.
- Men:Daily facial grooming routines sustain the highest per-capita blade consumption, with cartridge replacement frequencies accelerated by direct-to-consumer subscription locking.
- Women:Body grooming applications favor cartridge systems with flexible heads and wider lubrication strips, though repurchase cycles extend versus facial shaving.
- Barbers:Professional establishments prioritize bulk packaging, sterilization compatibility, and consistent edge geometry across high-volume service schedules.
- Retailers:Drugstore and supermarket buyers negotiate slotting allowances and promotional calendars, with inventory turns slowing as subscription channels capture replenishment demand.
Men drive replacement velocity. Barbers represent the most stable contractual demand pool.
Distribution Channel:
Channel control determines margin capture, with digital-native entrants restructuring traditional wholesale hierarchies through subscription financing.
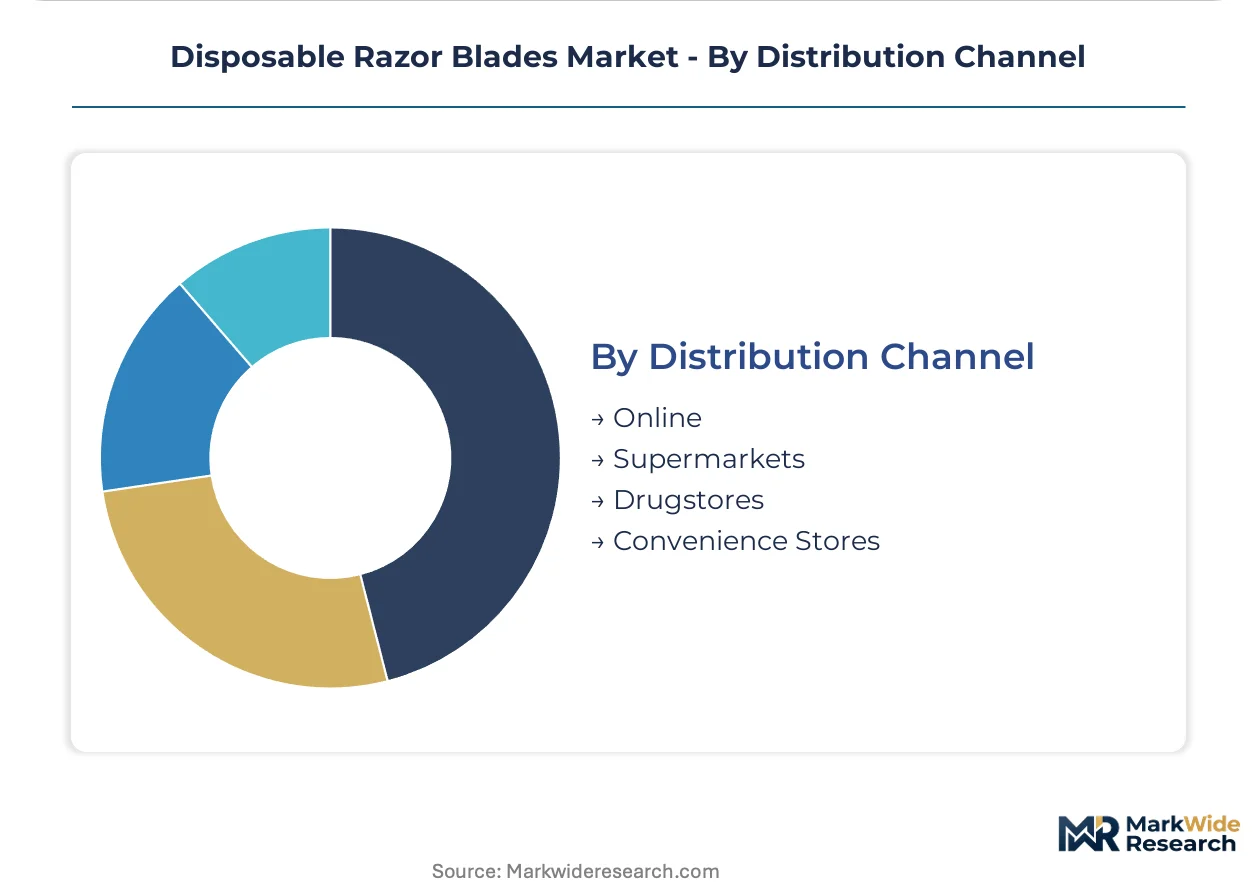
- Online:Direct-to-consumer platforms and grooming subscription services compress retail markups while capturing customer data for personalization. Urban Indian millennials represent the fastest-adopting demographic for this channel shift.
- Supermarkets:Mass-market cartridge displays face volume displacement as locked-in delivery schedules reduce impulse purchase frequency in United States and United Kingdom locations.
- Drugstores:Pharmacy chains retain strength in emergency replenishment and travel-size formats, though blade aisle traffic is thinning.
- Convenience Stores:Premium pricing for single-unit emergency purchases sustains profitability despite low absolute volumes.
Online is expanding most quickly. Supermarkets retain the broadest physical footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are redirecting European manufacturing investment toward compliant coating alternatives. India's BIS certification harmonization is accelerating market access for foreign blade assembly suppliers. Subscription channel tax classifications are creating compliance complexity across multiple jurisdictions.
United States
FDA labeling claim verification requirements extend product launch timelines for cartridge system entrants. Urban male grooming subscription services in New York and Los Angeles are compressing traditional drugstore replenishment cycles. Battery-powered facial trimmers from grooming appliance manufacturers are capturing convenience-oriented users in Midwestern and Southern households.
Germany
Solingen's precision grinding clusters concentrate metallurgical expertise for sub-50 nanometer edge radius control. ECHA enforcement of REACH Annex XVII is compelling reformulation of hydrophobic blade coatings across German supply chains. Bavarian and North Rhine-Westphalian manufacturers are regionalizing supply chains to maintain EU market access.
India
Urban male grooming routines in Mumbai and Delhi are shifting from single-blade traditions toward cartridge systems. BIS certification requirements affect market access for imported blade assemblies. Karnataka and Maharashtra industrial corridors are attracting grooming subscription service operations targeting metropolitan millennials.
Japan
Seki City's grinding heritage sustains demand for precision-ground double-edge formats among wet-shaving enthusiasts. METI standards govern product safety classifications for imported blade systems. Tokyo and Osaka barber-grade establishments drive sustained demand for professional wet-shaving implements.
United Kingdom
Supermarket blade aisles in London and Manchester are experiencing volume displacement from locked-in subscription delivery schedules. REACH compliance costs elevate barrier entry for non-compliant imports. Midlands manufacturing zones are adapting coating processes to satisfy evolving EU Green Deal disposal mandates.
Disposable Razor Blades Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin architectures. The market exhibits tiered concentration with mass-market incumbents defending scale positions against digital-native entrants. Three archetypes dominate: manufacturing-scale conglomerates, subscription-financed direct-to-consumer platforms, and precision-specialist grinding houses. Competitive moves center on M&A for manufacturing capacity and strategic partnerships for coating technology access.
Within the manufacturing-scale tier, Procter & Gamble and Edgewell Personal Care exemplify channel-anchored positions through drugstore and supermarket distribution networks. Harry's occupies a position representing subscription-financed digital-native entry, bypassing traditional retail markups entirely. Dorco represents the precision-specialist archetype with grinding expertise concentrated in Asian manufacturing clusters.
| Leading Market Players |
|---|
| Procter & Gamble |
| Edgewell Personal Care |
| BIC Group |
| Dorco |
| Kai Group |
| Super-Max |
| Lord International |
| Feather Safety Razor |
| Harry's |
| Others |
Supply Flow & Price Mechanics
Solingen and Seki grinding clusters concentrate precision metallurgical expertise for sub-50 nanometer edge radius control, anchoring margin capture in premium cartridge and double-edge formats while mass-market producers compete on coating chemistry efficiency.
Pricing Analysis
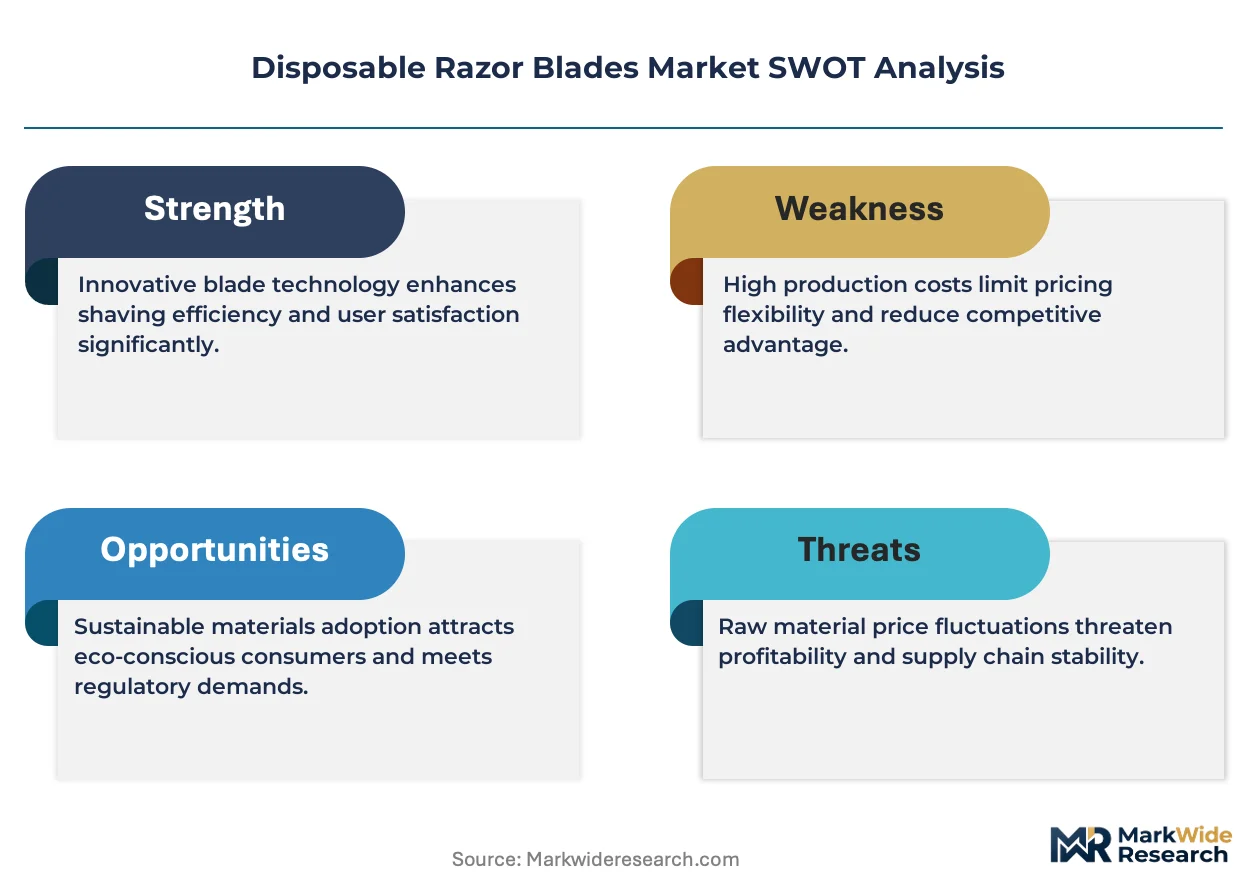
Certification level (FDA-grade for US market entry, REACH-compliant for EU access) creates the primary spread between mass-market and professional-grade blade assemblies. Subscription-based direct-to-consumer models compress per-unit margins but accelerate replacement velocity through locked-in delivery schedules. Pricing pressure stems from electric trimmer substitution in North American convenience segments. Drugstore and supermarket buyers exhibit highest price sensitivity; barber-grade procurement shows lowest sensitivity due to per-blade cost efficiency priorities.
Supply Chain Analysis
Export-control scrutiny on physical vapor deposition equipment limits coating technology transfer to non-allied manufacturing zones. Raw material flows draw from German and Japanese precision grinding clusters, with stainless steel feedstock sourced from South Korean and Chinese metallurgical suppliers. Single-source vulnerability concentrates in Solingen's specialized edge-radius expertise. Distribution runs through direct-to-consumer platforms, drugstore chains, and professional barber supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription channel fragmentation and regulatory material restrictions are splintering unified demand into specialized niches across dermatological formats, biodegradable handle segments, and professional wet-shaving establishments.
For Market Incumbents: Pre-empt coating technology obsolescence by securing atomic layer deposition capacity before REACH Annex XVII restrictions eliminate traditional polymer lubrication strips. Lock in Solingen and Seki grinding partnerships through long-term offtake agreements to defend against precision-skill scarcity. Accelerate biodegradable handle R&D to satisfy EU Green Deal disposal mandates before compliance deadlines harden.
For New Entrants and Emerging Players: Mid-market cartridge systems for Indian urban millennials represent the most penetrable entry point, bypassing established retail hierarchies through digital-native subscription platforms. Specialized dermatological formats for post-chemotherapy and eczema-prone users offer therapeutic positioning with minimal incumbent competition. Barber-grade double-edge supply to Turkish, Italian, and Japanese professional establishments leverages per-blade cost efficiency messaging against convenience-marketed cartridge systems.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed grooming subscription services seeking coating technology access and manufacturing scale. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for BIS certification acceleration in India as inflection signal for foreign assembly supplier consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Adoption | Eliminates polymer lubrication strip dependency ahead of REACH Annex XVII enforcement. |
| Biodegradable Handle Transition | Addresses EU Green Deal mandates through plant-fiber reinforced plastic formulations. |
| Direct-to-Consumer Platform Launch | Bypasses retail markups while capturing urban Indian millennial demand. |
| Precision Grinding Partnership | Secures Solingen or Seki expertise against edge-radius skill scarcity. |
| BIS Certification Investment | Unlocks Indian market access for imported blade assembly suppliers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, FDA 510(k) filings, ECHA restriction proposals, and grooming subscription service financial disclosures. Interviews with brand managers at cartridge system manufacturers, category buyers at drugstore chains, barber supply distributors, coating technology R&D directors, and regulatory affairs specialists provided demand-side and supply-side perspectives. Bottom-up unit economics modeling triangulated against top-down market sizing from import-export statistics.
Forecast inputs include replacement cycle velocity by customer segment, channel shift trajectories from retail to subscription, coating chemistry transition timelines under REACH, and BIS certification penetration rates. Segmentation dimensions span product type (cartridge, double-edge, single-edge, straight edge), material composition, customer archetype, and distribution channel. CAGRs derive from regression analysis of historical replacement patterns projected across the modeling period.
Macroeconomic conditions sit as an overlay; deviation in stainless steel alloy pricing, currency volatility in Indian import markets, or electric grooming appliance substitution rates would shift the trajectory. Cross-checking against customs volume data and subscription service disclosed customer counts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Insoles Market