
 Feminine Hygiene Products Market | 2026-2036
Feminine Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Feminine Hygiene Products Market Analysis
Teenage end users are realigning the category's marketing and packaging priorities, driving brands toward educational content and discrete portability. Procter & Gamble Company leverages its retail shelf presence and media budgets to sustain dominance in mass-market sanitary napkins across North American and European outlets. Kimberly-Clark Corporation anchors its position through institutional contracts with school systems and workplace wellness programs. Ontex Group NV competes on private-label manufacturing scale, supplying retail chains across multiple European markets with cost-optimized production.
Feminine hygiene products encompass absorbent and non-absorbent devices designed for menstrual management, typically constructed from layered cellulose pulp, superabsorbent polymers, nonwoven fabrics, or medical-grade silicone with fluid-locking barriers and breathable backsheet films. These products serve the essential function of collecting or absorbing menstrual flow while maintaining skin integrity and enabling normal daily activity during menstruation. Sanitary napkins occupy the largest revenue pool due to universal familiarity and lowest adoption barrier, though menstrual cups are gaining traction among athletes and sustainability-focused consumers seeking reusable alternatives. Cotton and organic cotton materials command premium shelf positioning as consumers scrutinize pesticide residues and dermatological sensitivity, while synthetic fabrics retain volume leadership in emerging markets where unit cost governs purchase decisions.
The FDA regulates tampon absorbency labeling and fiber composition in the United States, while the EU REACH framework restricts certain chemical additives in synthetic fabrics sold across European member states. India's BIS certification mandates absorbency and hygiene standards for imported and domestically manufactured sanitary products, shaping both local production investments and import compliance costs. Stakeholders must monitor evolving biodegradability mandates and extended producer responsibility schemes, as these frameworks will determine which material technologies and distribution models retain market access across priority geographies.
Market Dynamics
EU REACH chemical safety mandates are forcing wholesale reformulation of synthetic fabric components, while India's rural distribution expansion and government subsidy programs are redrawing volume concentration patterns.
Growth Catalysts
- School-based health programs:Teenage consumers now drive discrete packaging and educational content priorities as menstrual health discussion normalizes in educational institutions across multiple geographies.
- REACH regulation compliance:European chemical safety frameworks are accelerating material innovation investments, pushing manufacturers toward biodegradable alternatives and cleaner supply chains.
- Rural subsidy networks:India's government-backed distribution programs are extending product access to previously unserved populations, creating new volume anchors outside urban centers.
Market Restraints
- Cotton input volatility:Organic cotton fiber costs fluctuate with climate-driven harvest uncertainty, compressing margin structures for premium-positioned brands.
- Superabsorbent polymer concentration:Three chemical suppliers dominate global SAP production, creating vulnerability to price shocks and allocation limits.
- Medical-grade silicone certification:Menstrual cup manufacturers face extended FDA biocompatibility testing timelines that delay market entry by 18-24 months.
Strategic Opportunities
- Biodegradability mandates:Extended producer responsibility schemes emerging in France and Germany will reward early movers with compliant compostable product lines.
- Athletic segment specialization:Menstrual cups designed for high-movement activities are capturing share among competitive sports participants seeking leak-free performance.
- Direct-to-consumer subscription:Digital-native brands bypass retail slotting fees through recurring delivery models, capturing lifetime value from convenience-seeking urban professionals.
Industry Challenges
- Biocompatibility testing capacity:FDA-approved laboratories face 14-month backlogs for novel material submissions, throttling innovation pipelines.
- Legacy ERP integration:Manufacturers adopting batch-level traceability for EU Digital Product Passport compliance struggle with 1990s-era inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feminine Hygiene Products Market |
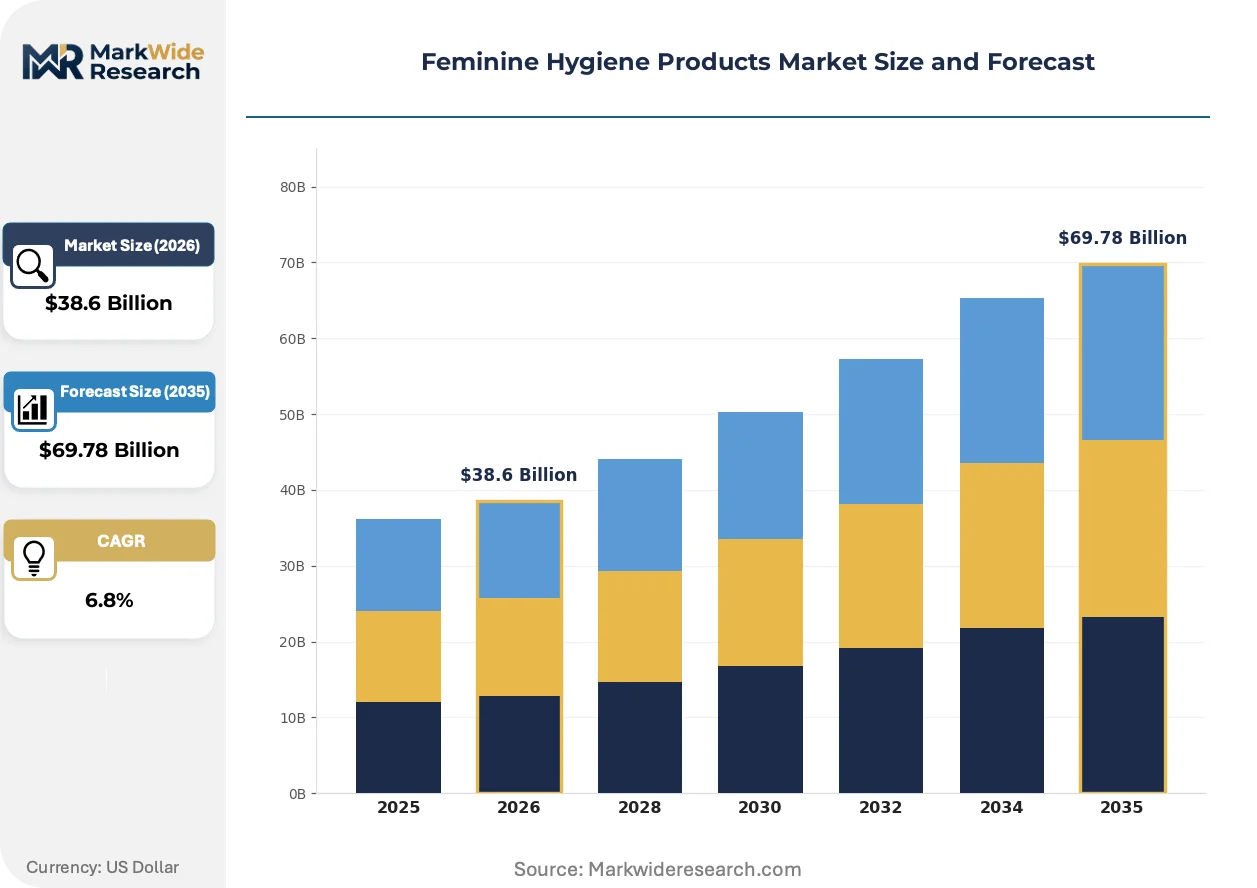
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitary Napkins, Tampons, Menstrual Cups, Panty Liners Material: Cotton, Organic Cotton, Biodegradable Materials, Synthetic Fabrics End User: Women, Teenagers, Athletes, Working Professionals Distribution Channel: Pharmacies, Supermarkets, E-commerce, Convenience Stores |
| Companies Covered | Unicharm Corporation, Ontex Group NV, Procter & Gamble Company, First Quality Enterprises, Kao Corporation, Kimberly-Clark Corporation, Edgewell Personal Care Company, Johnson & Johnson, Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feminine Hygiene Products Market Emerging Trajectories
Material science breakthroughs and regulatory transparency requirements are converging to reshape product architecture and supply chain visibility across the feminine hygiene category.
Smart absorbent core engineering is automating fluid distribution optimization through machine-calibrated fiber layering that adjusts density gradients in real time during production. Athletic wear manufacturers and medical device suppliers are licensing this technology for moisture-management applications beyond menstrual products. The automation of quality consistency is compressing defect rates and reducing manual inspection labor in high-volume facilities.
REACH substance restriction updates are eliminating certain phthalate plasticizers from backsheet films, forcing compounders to validate alternative elastomers under accelerated aging protocols. Manufacturers serving EU member states must reformulate by 2026 or forfeit shelf access across 27 countries. German and French retailers are already demanding pre-certification documentation for new product introductions.
Subscription-based replenishment models are displacing emergency pharmacy purchases among working-age consumers in metropolitan India and Brazil. Urban professionals pre-schedule deliveries through mobile applications, shifting volume from impulse-driven retail to predictable direct channels. This behavioral pivot is most pronounced in São Paulo, Mumbai, and Mexico City where delivery infrastructure supports same-day fulfillment.
Feminine Hygiene Products Market Segmentation
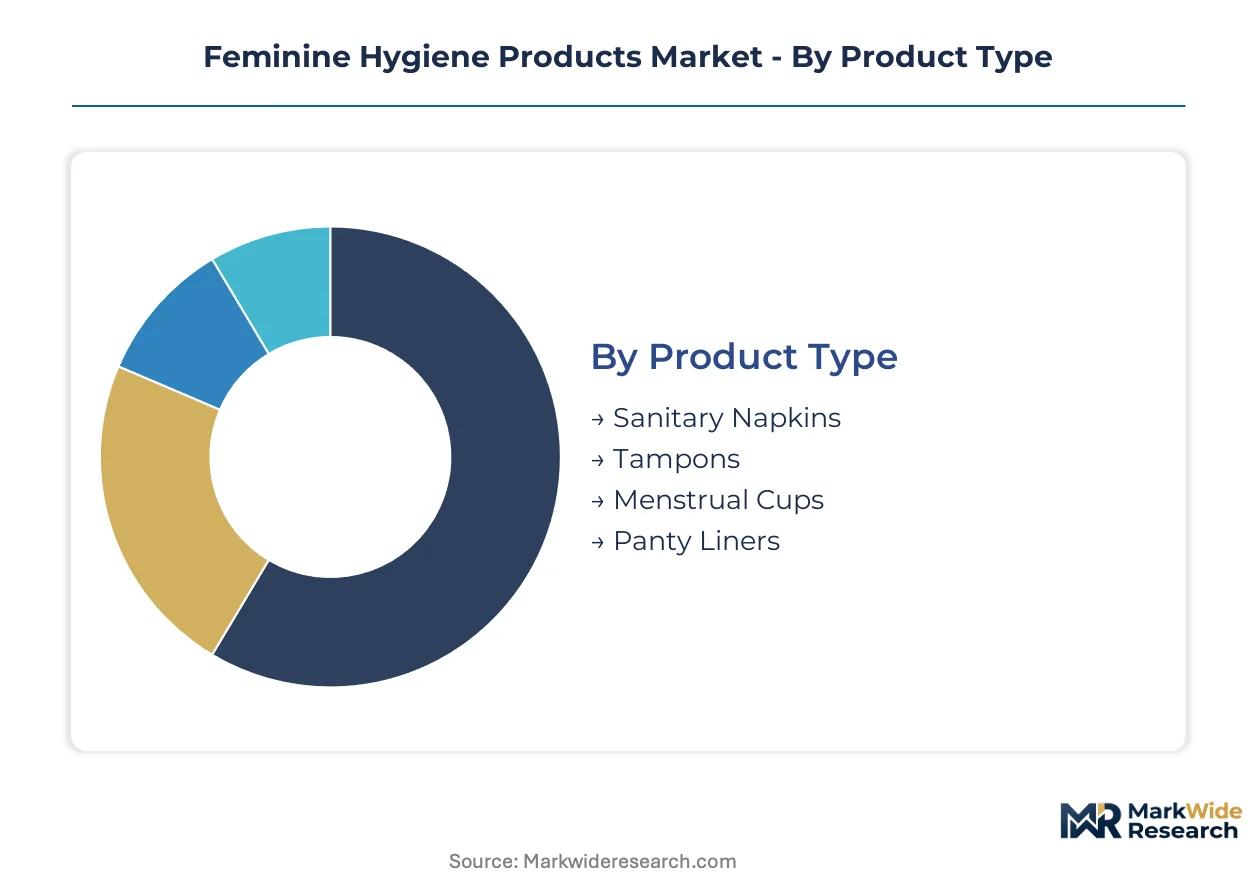
Segmentation in feminine hygiene products reveals how purchasing decisions split across material sensitivity, life stage priorities, and channel convenience. Manufacturers must align formulation investments with distinct user requirements rather than pursuing undifferentiated mass-market positioning.
Product Type:
Usage occasions and comfort preferences differentiate buyers across this category, with familiarity and cultural norms governing initial adoption patterns.
- Sanitary Napkins:Layered cellulose pulp construction with superabsorbent polymer cores and breathable backsheet films provides the lowest adoption barrier for new users. Demand concentrates in India's rural subsidy networks and government school distribution programs, where unit cost and cultural familiarity override performance experimentation.
- Menstrual Cups:Medical-grade silicone devices with fluid-locking barriers offer 8-12 hour wear cycles and reusable lifespans of 5-10 years. Athletes in competitive sports and sustainability-focused consumers in German and French metropolitan areas drive adoption, though FDA biocompatibility testing timelines delay new entrant market entry by 18-24 months.
- Tampons:Rayon or cotton fiber cylinders with applicator or non-applicator formats serve established users seeking discretion and swimming compatibility.
- Panty Liners:Thin absorbent layers for light-flow days or backup protection command impulse purchase placement at pharmacy checkout counters.
Volume sits with sanitary napkins; growth tilts toward menstrual cups.
Material:
Supply chain chemistry and dermatological sensitivity claims create tiered price positioning that separates premium shelf placement from mass-market penetration.
- Synthetic Fabrics:Polypropylene nonwoven topsheets and polyethylene backsheet films dominate high-volume production through cost-optimized extrusion processes. India's BIS certification mandates absorbency standards that synthetic formulations reliably meet, anchoring volume in price-sensitive emerging markets where government subsidy programs govern access.
- Organic Cotton:Pesticide-free fiber cultivation with certified supply chain traceability commands 40-60% price premiums over conventional alternatives. EU REACH substance restrictions on chemical additives accelerate reformulation timelines, with German and French retailers demanding pre-certification documentation for new product introductions by 2026.
- Cotton:Conventional bleached cotton fibers balance absorbency and cost for mid-tier positioning across North American and European pharmacy channels.
- Biodegradable Materials:Compostable plant-based polymers and bamboo fiber alternatives align with France and Germany's emerging extended producer responsibility schemes.
Margin concentrates in organic cotton; regulatory pressure accelerates biodegradable material development fastest.
End User:
Life stage and activity intensity shape product performance requirements, with discrete packaging and educational support needs varying sharply across age cohorts.
- Teenagers:First-time users require instructional content and school-appropriate portability, driving brand investment in educational microsites and subscription starter kits. School-based health programs across multiple geographies normalize menstrual health discussion, expanding this cohort's share of category purchases.
- Working Professionals:Urban professionals in São Paulo, Mumbai, and Mexico City pre-schedule deliveries through mobile applications, shifting volume from emergency pharmacy purchases to predictable direct-to-consumer channels with same-day fulfillment infrastructure.
- Women:General adult population spans diverse income levels and cultural contexts, requiring portfolio breadth from economy to premium tiers.
- Athletes:High-movement activity demands leak-free performance during competition, with menstrual cup manufacturers specializing rim flexibility and suction seal reliability for this segment.
Subscription penetration runs deepest with working professionals; educational content investment targets teenagers most intensively.
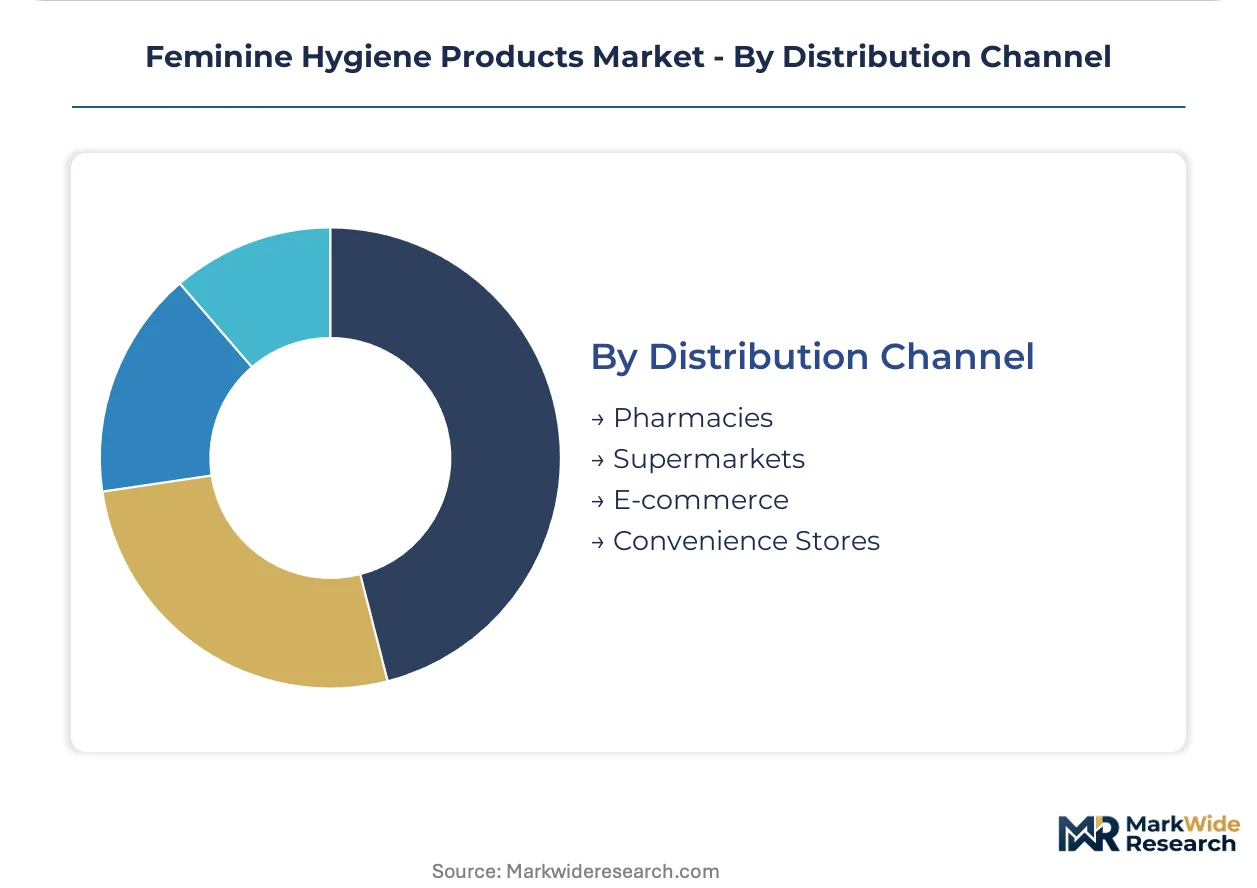
Distribution Channel:
Channel selection reflects purchase urgency, stock-up behavior, and digital infrastructure maturity across metropolitan versus rural geographies.
- E-commerce:Direct-to-consumer subscription models bypass retail slotting fees and capture lifetime value through recurring delivery algorithms. Urban India and Brazil show pronounced behavioral pivots toward mobile application scheduling, with predictable replenishment displacing impulse-driven pharmacy visits.
- Pharmacies:Emergency purchase occasions and pharmacist recommendation influence govern this channel, with discrete bagging protocols and checkout placement optimizing for embarrassment avoidance.
- Supermarkets:Stock-up shopping trips and promotional multi-pack pricing drive volume concentration in developed market suburban locations.
- Convenience Stores:Travel and workplace proximity purchases serve immediate need fulfillment with limited SKU availability and premium unit pricing.
Volume flows through pharmacies; channel shift accelerates fastest through e-commerce subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of feminine hygiene products clusters in manufacturing hubs across Germany, the United States, and India, while consumption growth concentrates in subsidy-enabled rural markets and digitally-connected urban centers. Regulatory divergence between REACH-mandated European reformulation and India's BIS certification creates distinct compliance pathways. Demand fragmentation requires region-specific portfolio strategies rather than standardized global product lines.
United States
FDA absorbency labeling rules and fiber composition standards govern tampon manufacturing, creating compliance costs that favor established producers with dedicated regulatory affairs teams. Teenage consumers through school-based health programs drive educational content investment and discrete packaging innovation. Manufacturing concentrates in Wisconsin and Georgia, where pulp processing infrastructure supports high-volume sanitary napkin output.
Germany
EU REACH substance restrictions on phthalate plasticizers force backsheet film reformulation by 2026, with German retailers demanding pre-certification documentation ahead of deadlines. Extended producer responsibility schemes in France and Germany reward compostable product lines, accelerating biodegradable material adoption. Industrial activity clusters in North Rhine-Westphalia, where chemical compounders validate alternative elastomers under accelerated aging protocols.
India
BIS certification mandates absorbency and hygiene standards for both imported and domestically manufactured products, shaping local production investments and import compliance structures. Government subsidy programs and rural distribution networks extend access to previously unserved populations, creating volume anchors outside urban centers. Manufacturing expansion concentrates in Maharashtra and Gujarat, where domestic brands scale production to meet subsidized demand.
Brazil
ANVISA regulates medical-grade silicone devices including menstrual cups, with biocompatibility testing timelines creating entry barriers for new market participants. Subscription-based replenishment models displace emergency pharmacy purchases among working-age consumers in São Paulo, where same-day delivery infrastructure supports mobile application scheduling. Urban professionals pre-schedule deliveries, shifting volume from impulse-driven retail to predictable direct channels.
Japan
METI standards and PMDA oversight govern product safety claims, with emphasis on dermatological testing documentation for sensitive-skin positioning. Aging demographics and declining birth rates compress the core user base, forcing portfolio diversification into incontinence and light-flow products. Industrial concentration in the Kanto region around Tokyo supports precision manufacturing of ultra-thin absorbent cores for premium-tier export markets.
Feminine Hygiene Products Market Vendor Landscape
Top-tier vendors anchor mass-market retail presence and institutional contracting, while mid-tier specialists compete on private-label scale and material innovation. The market structure reflects consolidation among consumer goods conglomerates alongside fragmentation in sustainable and direct-to-consumer niches. Three archetypes dominate: multinational FMCG houses with media budgets and shelf-space leverage, European private-label manufacturers with cost-optimized production networks, and digital-native brands with subscription infrastructure. Competitive moves center on REACH-compliant material reformulation and direct-to-consumer channel capture.
Within the multinational FMCG tier, Procter & Gamble Company and Kimberly-Clark Corporation exemplify divergent go-to-market strategies. Procter & Gamble leverages retail shelf dominance across North American and European mass-market outlets, while Kimberly-Clark anchors position through institutional contracts with school systems and workplace wellness programs. Ontex Group NV occupies the private-label manufacturing archetype, supplying retail chains across multiple European markets with scale-driven production capabilities. These three entities represent distinct competitive vectors: media-weighted brand building, institutional relationship depth, and manufacturing efficiency for channel partners.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Ontex Group NV |
| Procter & Gamble Company |
| First Quality Enterprises |
| Kao Corporation |
| Kimberly-Clark Corporation |
| Edgewell Personal Care Company |
| Johnson & Johnson |
| Essity AB |
| Others |
Supply Flow & Price Mechanics
EU REACH-mandated reformulation of backsheet films and superabsorbent polymer cores is forcing manufacturers to absorb certification costs or pass them downstream, compressing margins for non-compliant suppliers while rewarding early movers with shelf-access premiums. This regulatory-driven procurement specification shift is redrawing competitive positioning between synthetic fabric suppliers and biodegradable material innovators across European and Indian markets.
Pricing Analysis
Spot inventory availability commands steep discounts from subscription-committed buyers, while emergency pharmacy purchases carry 15-30% premiums over scheduled direct-to-consumer deliveries. Three-tier pricing structure across organic cotton, conventional synthetic, and economy subsidy-grade products separates premium dermatological positioning from mass-market penetration. Cost compression in synthetic tiers is intensifying because superabsorbent polymer suppliers exercise oligopolistic pricing power. Government procurement officers in India's rural subsidy networks exhibit highest price sensitivity; German retailers seeking pre-certified REACH-compliant lines show lowest.
Supply Chain Analysis
FDA biocompatibility certification and EU REACH substance documentation gate entry for menstrual cup silicone suppliers and synthetic fabric compounders, creating 18-24 month qualification timelines that filter out undercapitalized entrants. Manufacturing concentrates in Germany, the United States, and India, with Maharashtra and Gujarat scaling domestic capacity to meet BIS-mandated absorbency standards. Raw material dependencies center on superabsorbent polymers, medical-grade silicone, and organic cotton fiber. Single-source vulnerability runs through SAP production concentration among three chemical suppliers. Distribution runs through pharmacy emergency purchase, supermarket stock-up trips, and e-commerce subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance costs function as a structural moat, with backsheet film reformulation requirements eliminating marginal competitors and consolidating shelf access among pre-certified manufacturers. This cost-of-compliance dynamic favors capitalized incumbents with dedicated regulatory affairs teams over lean digital-native entrants.
For Market Incumbents: Deploy institutional contract depth to lock out subscription-based challengers. Kimberly-Clark's school system and workplace wellness anchoring provides defensive positioning against direct-to-consumer erosion. Capacity addition in Maharashtra and Gujarat secures volume participation in India's subsidy-driven rural expansion. FDA regulatory affairs infrastructure constitutes a transferable asset for menstrual cup line extensions. For New Entrants and Emerging Players: Direct-to-consumer mobile applications in São Paulo, Mumbai, and Mexico City offer the most penetrable white-space, where same-day delivery infrastructure supports subscription capture of working professional demand. Athletic-specialized menstrual cups with competition-optimized rim flexibility target an underserved performance segment. Educational microsite content partnerships with school-based health programs provide go-to-market credibility for teenage user acquisition. For Investors and Strategic Acquirers: The window for entry favors private-label manufacturers with REACH-compliant production lines and established retail chain relationships. Five-to-ten year viability hinges on biodegradable material transition execution ahead of extended producer responsibility scheme implementation. Acquisition target archetype: European compounders with validated alternative elastomer formulations. Signal to watch: FDA biocompatibility testing backlog reduction indicating accelerated innovation pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | BIS and ECHA documentation requirements determine shelf access across 27 EU member states and Indian import channels. |
| Direct-to-Consumer Subscription Launch | Urban professionals in São Paulo and Mumbai pre-schedule deliveries, displacing emergency pharmacy purchase behavior. |
| Athletic Segment Product Specialization | Competitive sports participants demand menstrual cups with leak-free performance during high-movement activity. |
| Rural Distribution Network Expansion | Maharashtra and Gujarat manufacturing scales to meet government subsidy program volume anchors outside urban centers. |
| Biodegradable Product Line Introduction | French and German extended producer responsibility schemes reward compostable plant-based polymer alternatives. |
Methodological Framework
Multi-period observation of regulatory filing timelines, raw material price indices, and subscription platform user acquisition metrics anchored the trend analysis, supplemented by interviews with supply chain planners at retail distributors, regulatory affairs directors at multinational FMCG houses, procurement leads at government subsidy programs, and brand managers at digital-native entrants. Secondary validation drew from FDA 510(k) submission databases, ECHA REACH substance restriction updates, BIS certification registries, Nielsen retail audit data, and customs import records. Bottom-up channel volume estimates and top-down macroeconomic absorption models were triangulated against manufacturer production disclosures.
Input-output matrices mapped superabsorbent polymer feedstock costs, certification expenditure timelines, and channel-specific margin structures across product type, material tier, end user life stage, and distribution format dimensions over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Forecast inputs included school-based health program expansion rates, rural subsidy network penetration curves, and biocompatibility testing backlog durations.
The model holds under stable regulatory enforcement timelines and raw material supplier pricing discipline; deviation in SAP allocation limits, cotton harvest volatility, or REACH substance restriction acceleration would shift volume and value trajectories. Forecasts reflect documented assumptions about subscription adoption elasticity and government procurement continuity. A model refresh is warranted upon material change in FDA testing capacity, EU Digital Product Passport implementation schedules, or India's BIS certification requirement modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Mobile Barber Shop Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Disposable Electric Toothbrushes Market