
 Canada Hair Care Market | 2026-2036
Canada Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hair Care Market Outlook
Clean beauty ingredient transparency is fragmenting traditional formulation pipelines across Canadian hair care manufacturing. L'Oréal S.A. anchors extensive R&D infrastructure in Montreal to accelerate sulfate-free and silicone-alternative development. Procter & Gamble Company leverages mass retail distribution density to sustain volume leadership in shampoo and conditioner replenishment cycles. LUS Brands specializes in direct-to-consumer curly-hair systems, occupying a defensible niche against multinational shelf competition.
Hair care encompasses cleansing, conditioning, coloring, and styling formulations designed to modify fiber surface chemistry, manage porosity, and protect cuticle integrity against thermal and environmental stress. Shampoos and conditioners constitute the mature volume base, while styling products and hair color capture expanding margin pools through premium positioning and professional service attachment. Salon professionals represent the fastest-growing end-user channel as service-based retailing deepens client retention and basket expansion. Natural and organic ingredient types are gaining shelf space in response to consumer scrutiny of synthetic preservative systems.
Health Canada's Cosmetic Ingredient Hotlist and the Canadian Environmental Protection Act shape permissible formulation chemistry and labeling claims for products manufactured or imported into the country. The Competition Bureau enforces advertising standards that restrict unsubstantiated hair growth and repair claims, elevating clinical validation costs for market entrants. Stakeholders must monitor evolving provincial extended producer responsibility frameworks for packaging waste and prepare for potential federal fragrance disclosure mandates that would expose proprietary formulation architectures.
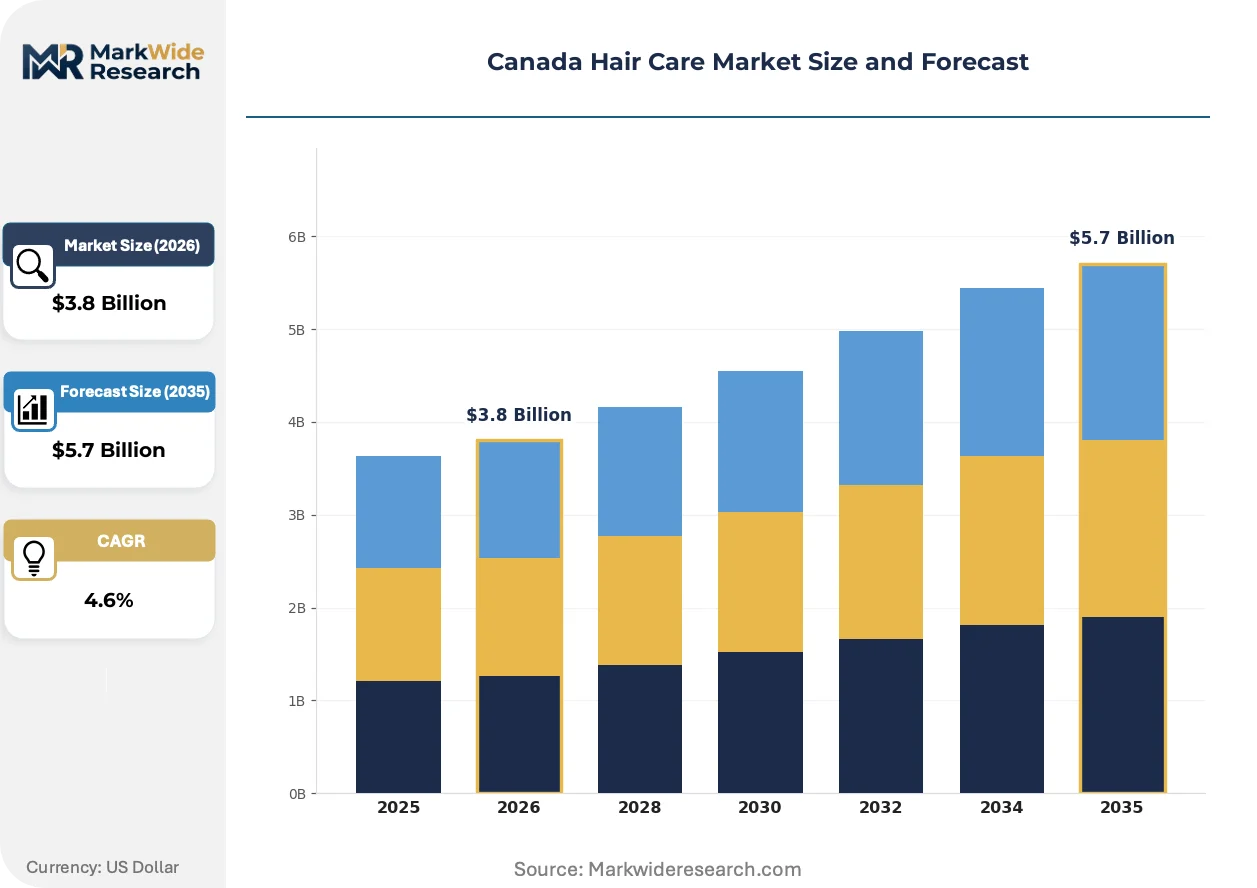
Market Dynamics
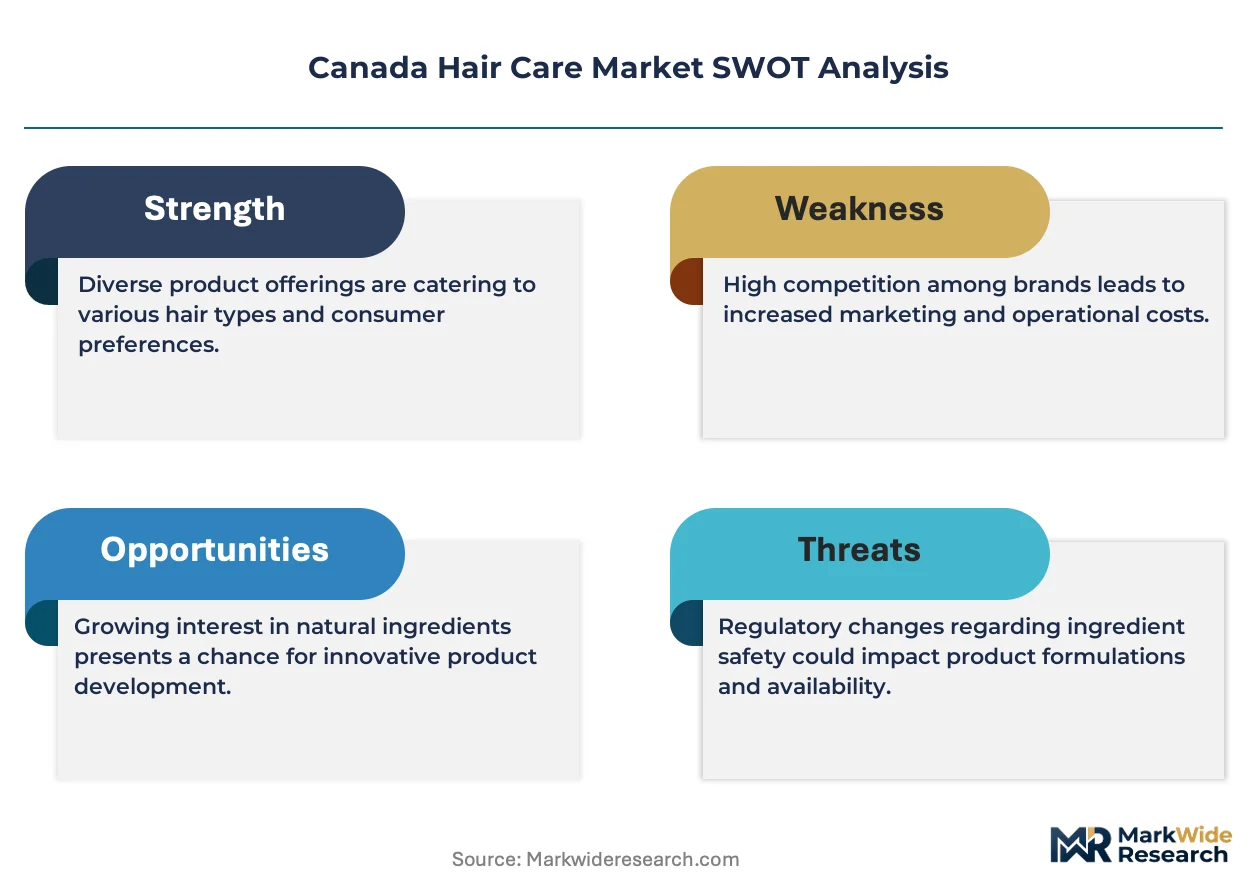
Health Canada's tightening Cosmetic Ingredient Hotlist is forcing wholesale reformulation across Canadian hair care manufacturing, compressing product development timelines while elevating R&D spend for compliance-ready chemistry.
Growth Catalysts
- Scalp treatment service expansion:Salon professionals in Ontario and British Columbia are adding trichology-based services to menus, driving professional-grade product attachment and recurring client visits.
- Clean beauty ingredient mandates:Provincial extended producer responsibility frameworks for packaging waste are accelerating sustainable packaging investments ahead of federal mandates.
- Bond-building technology adoption:Professional stylists are integrating fiber-repair systems into color services, creating premium service tiers with higher per-visit revenue capture.
Market Restraints
- Formaldehyde-releasing preservative phase-outs:Health Canada's Hotlist restrictions are eliminating proven antimicrobial chemistries, forcing costly preservative system redesigns with shorter shelf-life outcomes.
- Specialty silicone supply concentration:Silicone-alternative raw materials for sulfate-free formulations depend on limited North American suppliers, exposing formulators to input volatility.
- Clinical validation requirements:The Competition Bureau's advertising standards enforcement demands substantiated hair growth and repair claims, elevating barrier-to-entry costs for new market participants.
Strategic Opportunities
- Quebec independent retail channel:Montreal's beauty retail cluster remains underpenetrated by direct-to-consumer curly-hair specialists, offering white space for niche positioning.
- Fragrance disclosure preparation:Anticipated federal fragrance disclosure mandates would expose proprietary architectures, creating first-mover advantage for brands with transparent formulation pipelines already built.
- Salon-exclusive distribution models:Professional-only product lines bypass mass retail margin compression while capturing higher loyalty through stylist recommendation authority.
Industry Challenges
- Trichology certification timelines:Salon professionals seeking scalp treatment credentials face extended training periods, slowing service menu rollout and revenue realization.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking for regulatory compliance conflicts with established manufacturing software, requiring middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hair Care Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Styling Products, Hair Color End User: Men, Women, Salon Professionals, Children Distribution Channel: Online Retail, Supermarkets, Beauty Salons, Pharmacies Ingredient Type: Natural, Organic, Synthetic, Herbal |
| Companies Covered | Henkel AG & Co. KGaA, The Estee Lauder Companies Inc., L'Oréal S.A., Sally Beauty Holdings, Inc., Revlon Inc., Procter & Gamble Company, Kao Corporation, LUS Brands, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hair Care Market Strategic Shifts
Reformulation pressure from Health Canada is compressing traditional product development cycles while fragmenting competitive positioning between mass retail efficiency and professional-channel premiumization.
Bond-building chemistry is collapsing the historical separation between color services and repair treatments. Olaplex-type bis-aminopropyl diglycol dimaleate systems enable stylists to bundle lightening with fiber integrity protection, compressing standalone treatment bookings into single-visit premium packages. Toronto's premium salon corridor shows the fastest uptake, with service menus restructuring around damage-prevention positioning rather than damage-repair add-ons.
Health Canada's Cosmetic Ingredient Hotlist updates are eliminating formaldehyde-releasing preservatives from permissible chemistry. The industrial consequence is accelerated R&D migration toward phenoxyethanol and organic acid systems with narrower efficacy windows. Professional color and keratin treatment categories face the steepest compliance costs, with manufacturers absorbing extended stability testing timelines to maintain shelf claims.
Stylists are consolidating product recommendation authority previously fragmented across retail self-selection. Salon professionals in Vancouver and Calgary are replacing client-directed purchasing with prescribed home-care regimens, capturing replenishment revenue through back-bar exclusives. This concentration of purchase decision is most visible in curly-hair and color-maintenance segments, where technical complexity justifies professional gatekeeping over mass-market accessibility.
Canada Hair Care Market Segmentation
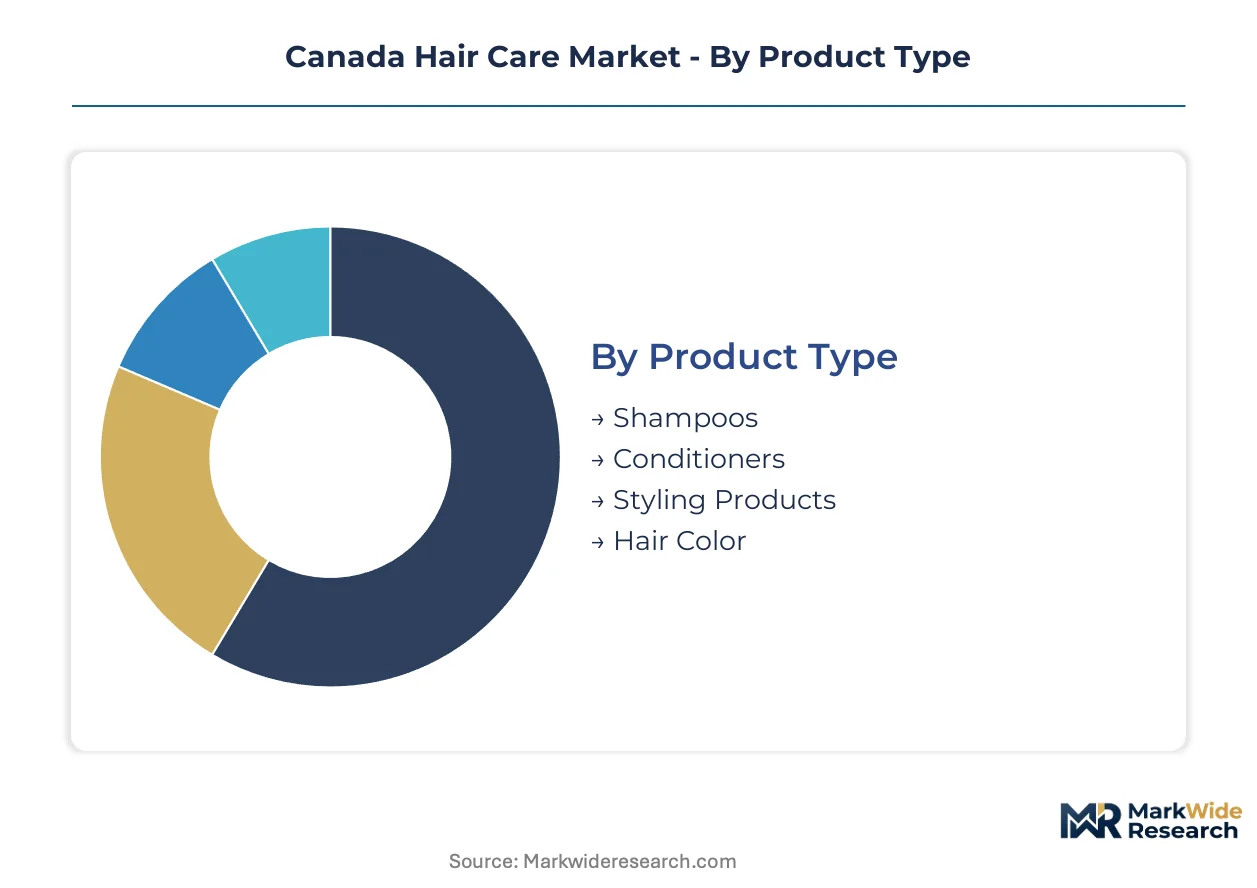
Segmentation reveals how purchase frequency, technical complexity, and channel economics split the Canadian hair care landscape into distinct competitive arenas with diverging margin profiles and regulatory exposure.
Product Type:
Shampoos and conditioners turn over fastest through replenishment cycles, while hair color and styling products move slower but capture higher per-unit margins through premium positioning.
- Shampoos:Surfactant-based cleansing formulations dominate unit volume through frequent replenishment. Toronto's premium salon corridor drives sulfate-free and silicone-alternative demand as stylists prescribe back-bar exclusives.
- Conditioners:Cationic conditioning agents modify fiber surface chemistry to manage porosity and cuticle integrity. Montreal's independent beauty retail cluster shows strongest uptake of bond-building conditioner systems bundled with professional services.
- Styling Products:Polymer-based hold and texture formulations capture margin through premium positioning and seasonal trend cycles.
- Hair Color:Oxidative and direct dye systems carry the steepest regulatory compliance costs under Health Canada's Cosmetic Ingredient Hotlist.
Shampoos anchor the volume base while hair color gains share at the steepest rate through professional service attachment.
End User:
Cost tiers separate mass self-selection from professional gatekeeping, with salon professionals commanding the highest per-transaction value through technical recommendation authority.
- Women:The core addressable market spans daily cleansing through color maintenance and styling complexity. Ontario scalp treatment service expansion targets this segment with trichology-based recurring revenue models.
- Salon Professionals:Licensed stylists function as distribution gatekeepers and formulation influencers. British Columbia bond-building therapy adoption concentrates here, creating premium service tiers with higher per-visit capture.
- Men:Simplified routines concentrate in mass retail channels with lower SKU complexity and faster purchase cycles.
- Children:Mild formulation requirements and tear-free claims impose additional safety testing burdens on manufacturers.
Women dominate absolute spend while salon professionals expand most quickly as service-based retailing deepens client retention.
Distribution Channel:
Geographic concentration shapes channel economics, with urban density favoring salon exclusives and suburban sprawl sustaining mass retail replenishment.
- Beauty Salons:Professional-only lines bypass mass retail margin compression through stylist recommendation authority. Vancouver and Calgary stylists are consolidating purchase decisions previously fragmented across retail self-selection.
- Online Retail:Direct-to-consumer models enable niche positioning without shelf-space competition. Quebec's underpenetrated independent retail cluster offers white space for curly-hair specialists.
- Supermarkets:Mass retail density sustains volume leadership in shampoo and conditioner replenishment cycles.
- Pharmacies:Dermocosmetic positioning and scalp health claims align with pharmacist consultation channels.
Supermarkets anchor the volume base while beauty salons gain share at the steepest rate through prescribed home-care regimens.
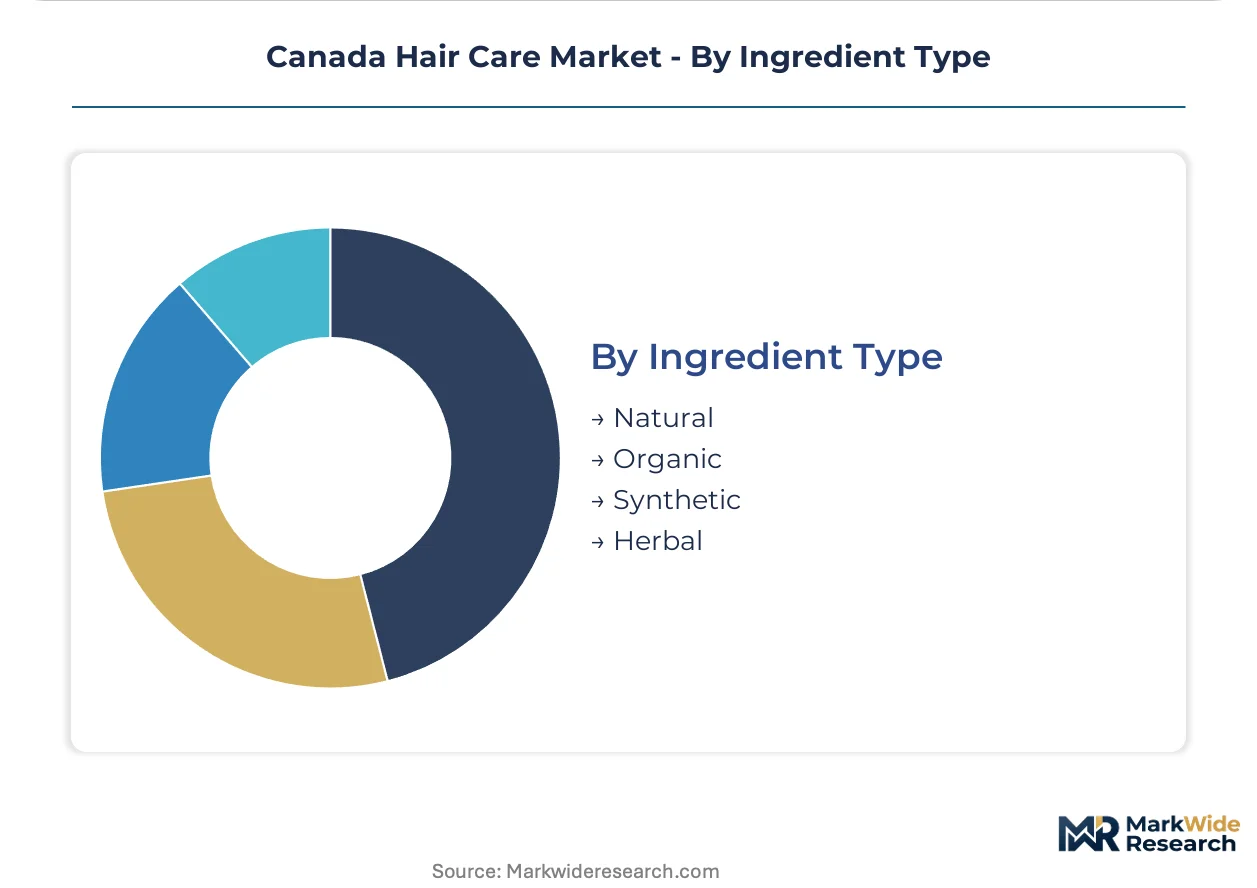
Ingredient Type:
Supply concentration for silicone-alternative raw materials creates input volatility, fragmenting competitive positioning between synthetic efficiency and natural positioning.
- Natural:Plant-derived actives and naturally sourced surfactants respond to consumer scrutiny of synthetic preservative systems. Extended producer responsibility frameworks accelerate sustainable packaging investments.
- Synthetic:Petrochemical-derived conditioning agents and styling polymers face reformulation pressure from Health Canada's Hotlist restrictions on formaldehyde-releasing preservatives.
- Organic:Certified organic supply chains carry premium positioning and third-party verification costs.
- Herbal:Traditional botanical extracts target specific scalp conditions with regional formulation heritage.
Synthetic formulations anchor the volume base while natural ingredient types gain share at the steepest rate through clean beauty shelf space expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Salon professionals and independent beauty retailers concentrate purchasing power in Ontario and Quebec, while western provinces drive service-based revenue expansion through scalp treatment adoption.
Ontario
Toronto's premium salon corridor anchors sulfate-free and silicone-alternative demand as stylists prescribe back-bar exclusives. Health Canada's Cosmetic Ingredient Hotlist compliance costs concentrate manufacturing oversight in provincial industrial zones. The Greater Toronto Area hosts reformulation R&D facilities serving national distribution networks.
Quebec
Montreal's independent beauty retail cluster shows strongest uptake of bond-building conditioner systems bundled with professional services. Provincial extended producer responsibility frameworks accelerate sustainable packaging investments ahead of federal mandates. L'Oréal S.A. anchors extensive R&D infrastructure in Montreal to accelerate clean beauty development.
British Columbia
Vancouver stylists consolidate purchase decisions previously fragmented across retail self-selection through prescribed home-care regimens. The Competition Bureau's advertising standards enforcement elevates clinical validation costs for local market entrants. Bond-building therapy adoption concentrates in Vancouver and Calgary salon networks.
Alberta
Calgary salon professionals expand service menus to include trichology-based scalp treatments driving recurring client visits. Health Canada's formaldehyde-releasing preservative restrictions force costly reformulation timelines for keratin treatment manufacturers. The Calgary-Edmonton corridor shows fastest professional-channel revenue growth.
Canada Hair Care Market Competitive Environment
Channel-controlling players compete with product-specialist players across mass retail and professional-exclusive distribution networks. Mass retail density sustains volume leadership through supermarket and pharmacy replenishment cycles, while salon-exclusive lines bypass margin compression through stylist recommendation authority. Three archetypes dominate: multinational conglomerates with R&D infrastructure, direct-to-consumer specialists occupying defensible niches, and professional-only brands leveraging technical gatekeeping. Competitive moves concentrate on portfolio diversification into clean beauty segments and strategic partnerships with salon distribution networks.
Among multinational conglomerates, L'Oréal S.A. and Procter & Gamble Company represent contrasting scale strategies. L'Oréal S.A. anchors Montreal-based R&D infrastructure serving professional and mass channels simultaneously. Procter & Gamble Company exemplifies mass retail distribution density sustaining volume leadership in replenishment cycles. LUS Brands occupies a direct-to-consumer position against multinational shelf competition, specializing in curly-hair systems without retail intermediaries.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| The Estee Lauder Companies Inc. |
| L'Oréal S.A. |
| Sally Beauty Holdings, Inc. |
| Revlon Inc. |
| Procter & Gamble Company |
| Kao Corporation |
| LUS Brands |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on North American silicone-alternative suppliers determines both premium-tier price spreads and supply chain shape across Canadian hair care manufacturing. Health Canada's Cosmetic Ingredient Hotlist restrictions on formaldehyde-releasing preservatives compress reformulation timelines while elevating input costs for compliant preservative systems.
Pricing Analysis
Cost-plus contracts with phenoxyethanol and organic acid suppliers indexed to specialty chemical benchmarks dominate professional-grade procurement. Price differentiation rests on certification grade under Health Canada's Hotlist compliance tiers and volume scale through salon-exclusive distribution. Pricing pressure intensifies in mass retail shampoo and conditioner segments as Procter & Gamble leverages distribution density. Independent beauty retailers in Montreal show least price sensitivity due to technical complexity premiums for bond-building systems.
Supply Chain Analysis
Upstream feedstock for sulfate-free surfactants draws from limited North American specialty chemical producers concentrated in the United States and Canada. Raw material dependencies center on phenoxyethanol, bis-aminopropyl diglycol dimaleate bond-building actives, and plant-derived cationic conditioning agents. Single-source vulnerability in silicone-alternative supply exposes formulators to input volatility during Health Canada compliance transitions. Distribution runs through dual-channel structures: mass retail supermarket networks for replenishment cycles and salon-exclusive back-bar systems for professional gatekeeping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Health Canada's evolving Cosmetic Ingredient Hotlist creates switching costs that favor incumbents with established compliance infrastructure and R&D absorption capacity.
For Market Incumbents: Pre-empt emerging clean beauty specialists by accelerating Montreal-based R&D infrastructure for silicone-alternative development. Absorb formaldehyde-releasing preservative phase-out costs through vertical integration into phenoxyethanol supply agreements. Consolidate stylist recommendation authority through exclusive back-bar distribution before direct-to-consumer challengers penetrate Quebec's independent retail cluster.
For New Entrants and Emerging Players: Montreal's underpenetrated independent beauty retail cluster represents the most penetrable entry point for curly-hair specialists seeking white space against multinational shelf competition. Scalp treatment service expansion in Ontario offers secondary targeting for trichology-certified professional lines. Deploy subscription-based direct-to-consumer models to bypass mass retail margin compression and capture replenishment revenue through prescribed home-care regimens.
For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors incumbents with established Health Canada compliance infrastructure and Montreal-based R&D assets. Long-term viability across the projection horizon hinges on acquisition targets possessing transparent formulation pipelines ready for anticipated federal fragrance disclosure mandates. Monitor Health Canada Hotlist revision timing as the critical inflection signal for reformulation cost spikes and competitive displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean Beauty Reformulation Pipeline | Health Canada Hotlist compliance accelerates R&D migration toward phenoxyethanol and organic acid preservative systems. |
| Salon-Exclusive Distribution Expansion | Stylist recommendation authority in Vancouver and Calgary consolidates purchase decisions away from retail self-selection. |
| Bond-Building Technology Licensing | Bis-aminopropyl diglycol dimaleate systems enable premium service tier bundling in Toronto's salon corridor. |
| Direct-to-Consumer Curly-Hair Launch | Quebec's independent retail cluster offers defensible niche positioning against mass-market shelf competition. |
| Scalp Treatment Service Certification | Trichology credentials in Ontario and Alberta deepen client retention through recurring visit models. |
Study Parameters
A standing panel of salon professionals, cosmetic chemists, Health Canada regulatory affairs specialists, and independent beauty retail buyers provided ongoing calibration across the study period. Primary interviews with Ontario scalp treatment service providers and Montreal formulation R&D directors combined with secondary validation from Health Canada Cosmetic Ingredient Hotlist publications, Nielsen retail audit data, and provincial extended producer responsibility framework documents. Bottom-up salon service revenue estimates and top-down manufacturer shipment data underwent cross-triangulation to anchor segmentation splits.
Scenario-bracketing around Health Canada Hotlist implementation timing and silicone-alternative supply availability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end-user archetype, distribution channel density, and ingredient certification tier. CAGRs emerged from weighted average growth assumptions applied to replenishment cycle frequencies and professional service attachment rates. Bond-building therapy adoption curves and scalp treatment menu expansion timelines served as industry-specific forecast inputs.
Practitioners should monitor Health Canada Hotlist revision announcements, phenoxyethanol supply contract renewals, and provincial packaging waste mandate progressions for early signals requiring forecast adjustment. Cross-checking against Nielsen retail audit velocity data and salon industry association service revenue benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Bond Multiplier Market
Hair Care
Organic Hair Care Market
Hair Care
Germany Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Hair Extension Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Israel Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Dye Market
Hair Care
Hair Care Appliances Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
United States Hair Care Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Australia Hair Removal Market