
 Japan Hair Care Market | 2026-2036
Japan Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hair Care Market Foresight
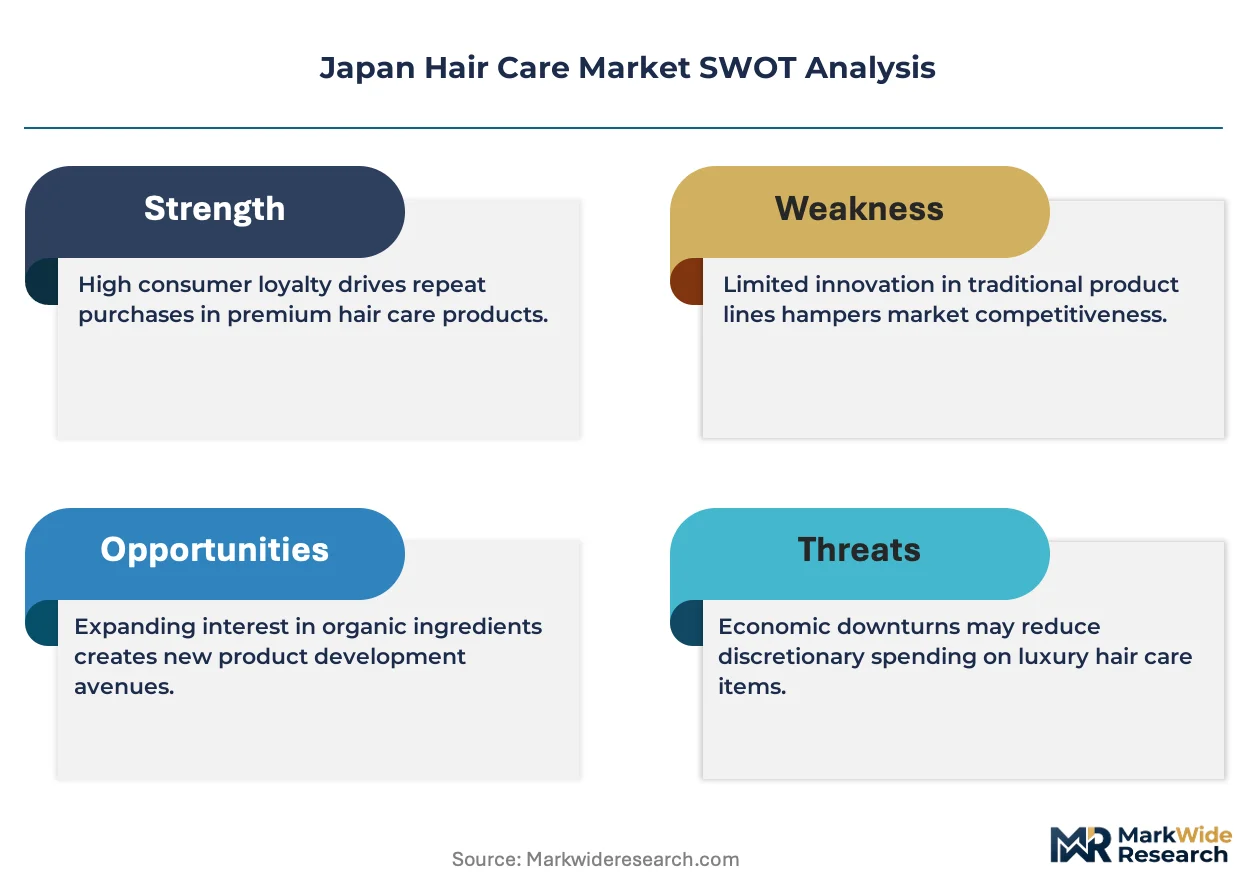
Asset-light salon franchising is narrowing the capital barrier for regional challengers entering Japan's hair care sector. Kao Corporation leverages its integrated supply chain to sustain price competitiveness across mass-market shampoos. Shiseido Co., Ltd. anchors its position through professional salon distribution networks that command premium shelf placement. Milbon Co., Ltd. specializes in high-performance treatment lines that dominate the B2B salon channel nationwide.
Japan hair care encompasses formulations designed to cleanse, condition, protect, and treat human hair and scalp tissue, typically incorporating surfactant bases at pH 4.5–6.0 with active ingredients such as ceramides, amino acids, or medicinal botanical extracts regulated under quasi-drug classifications. The category serves both daily consumer maintenance and professional salon intervention for damage remediation. Shampoos and conditioners constitute the volume foundation, though margin pools concentrate in styling products and specialized treatment segments where technical differentiation commands pricing power. Damage repair applications within the salon channel are expanding fastest as heat styling prevalence and aging-related hair fragility drive professional service attachment rates.
PMDA quasi-drug regulations govern functional claims for hair growth and anti-dandruff formulations, requiring clinical substantiation that extends development timelines and elevates R&D investment thresholds. METI standards and JIS quality specifications further constrain manufacturing practices, particularly for organic and sulfate-free positioning claims that must satisfy labeling accuracy requirements. Stakeholders must monitor evolving interpretation of functional cosmetics boundaries, as regulatory clarity will determine which formulation innovations can migrate from premium niche to mass-market scale.
Market Dynamics
PMDA quasi-drug classification requirements are compressing development timelines for functional hair growth formulations while simultaneously elevating the technical barrier to entry for new market participants.
Growth Catalysts
- Scalp microbiome science:Advances in metagenomic sequencing are enabling targeted probiotic formulations that address specific dysbiosis patterns in aging consumers.
- Tokyo metropolitan density:Concentration of premium salon infrastructure and innovation labs in the greater Tokyo area accelerates product-to-market velocity for professional-grade treatments.
- METI sustainability frameworks:Government-backed circular economy incentives are driving refillable packaging adoption and waterless formulation R&D across mass-market channels.
Market Restraints
- PMDA clinical substantiation costs:The requirement for controlled trials to support hair growth claims extends development cycles and concentrates innovation capacity among well-capitalized incumbents.
- Import dependency for ceramide precursors:Supply concentration in South Korean and Chinese specialty chemical producers exposes formulators to input cost volatility and currency fluctuation risk.
- Technical ceiling in sulfate-free cleansing:Plant-derived surfactants struggle to match the sebum removal efficiency of synthetic alternatives without compromising foam quality.
Strategic Opportunities
- Hokkaido and Tohoku regional penetration:Underdeveloped professional salon networks in northern prefectures present first-mover potential for asset-light franchising models.
- Men's scalp care segment:Stigma reduction around male grooming is opening white space for dedicated anti-aging and density-focused product lines.
- AI-driven personalization:Convergence of scalp diagnostic imaging and machine learning recommendation engines enables subscription-based customized regimen delivery.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in quasi-drug stability testing and botanical extraction standardization is concentrated among retiring professionals with limited knowledge transfer pathways.
- Legacy ERP integration:Mid-tier manufacturers face friction connecting new digital traceability systems to existing inventory management platforms required for PMDA batch tracking mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hair Care Market |
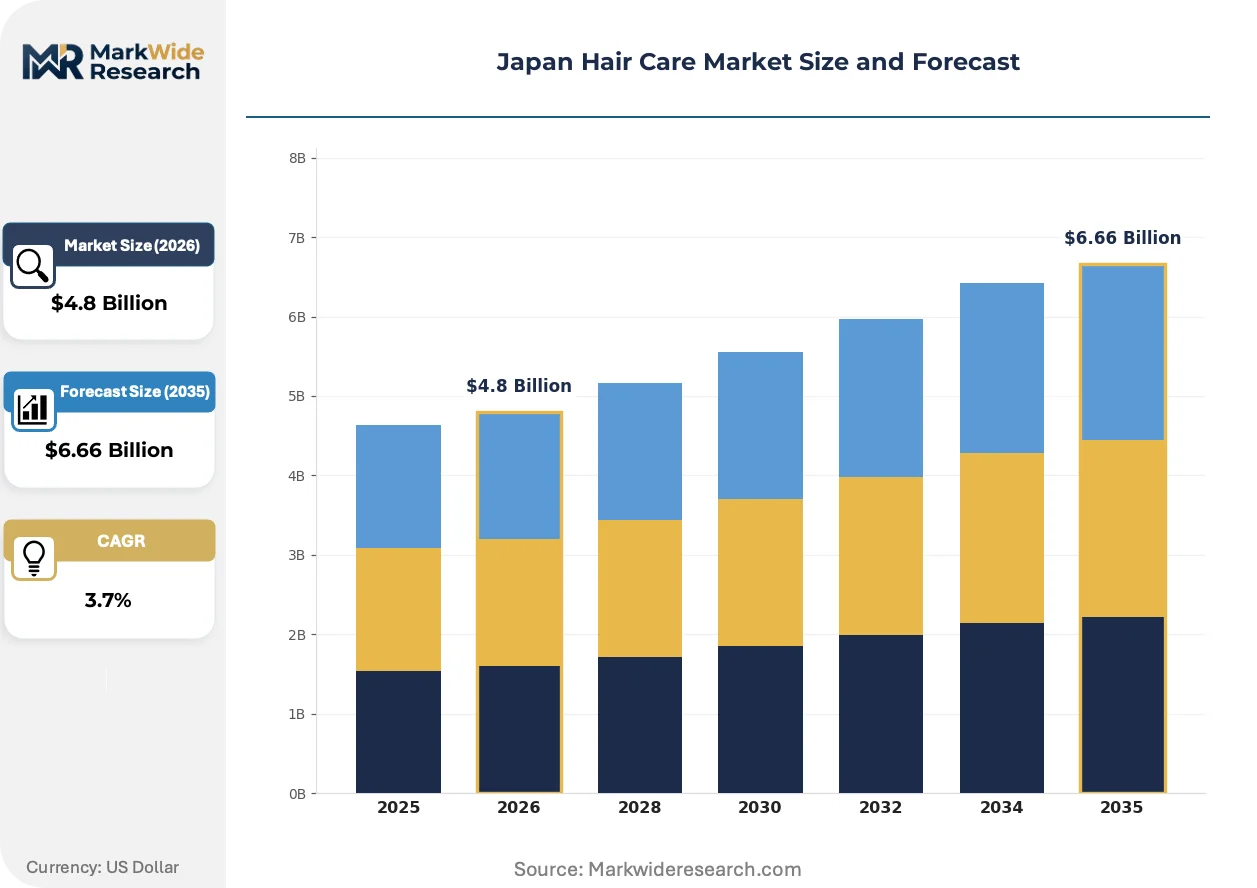
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products Application: Daily Care, Heat Protection, Damage Repair, Color Preservation Formulation: Sulfate-Free, Organic, Moisturizing, Anti-Dandruff Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Salons |
| Companies Covered | Lion Corporation, Hoyu Co., Ltd., Shiseido Co., Ltd., Procter & Gamble Japan, Unilever Japan K.K., Kao Corporation, Milbon Co., Ltd., Arimino Co., Ltd., Mandom Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hair Care Market Shifts & Advancements
Digital scalp diagnostics and bioactive ingredient delivery systems are converging to transform how consumers interact with hair care regimens, shifting value capture from product volume to personalized service attachment.
Encapsulation technology using liposome and niosome carriers is virtualizing the efficacy of traditional leave-in treatments by enabling deeper follicular penetration without heavy residue. Premium salon chains in Osaka and Fukuoka are piloting these systems for damage repair protocols. The technology is virtualizing the boundary between professional service and at-home maintenance, compressing the addressable market for standalone retail conditioners.
PMDA's evolving interpretation of functional cosmetics boundaries is forcing reformulation strategies for brands operating at the quasi-drug threshold. The regulator's tightened scrutiny of botanical extract concentration claims is redirecting R&D investment toward synthetic peptide alternatives. Professional treatment lines targeting hair growth are most affected, with several manufacturers withdrawing borderline claims to avoid mandatory clinical trial requirements.
Subscription-based replenishment models are displacing conventional retail purchasing for core maintenance products in urban prefectures. Direct-to-consumer platforms with AI-powered regimen recommendations are capturing share from drugstore and supermarket channels. This behavioral shift is most visible among consumers aged 35-50 in the Tokyo metropolitan area, where convenience prioritization outweighs price sensitivity for daily-use formulations.
Japan Hair Care Market Segmentation
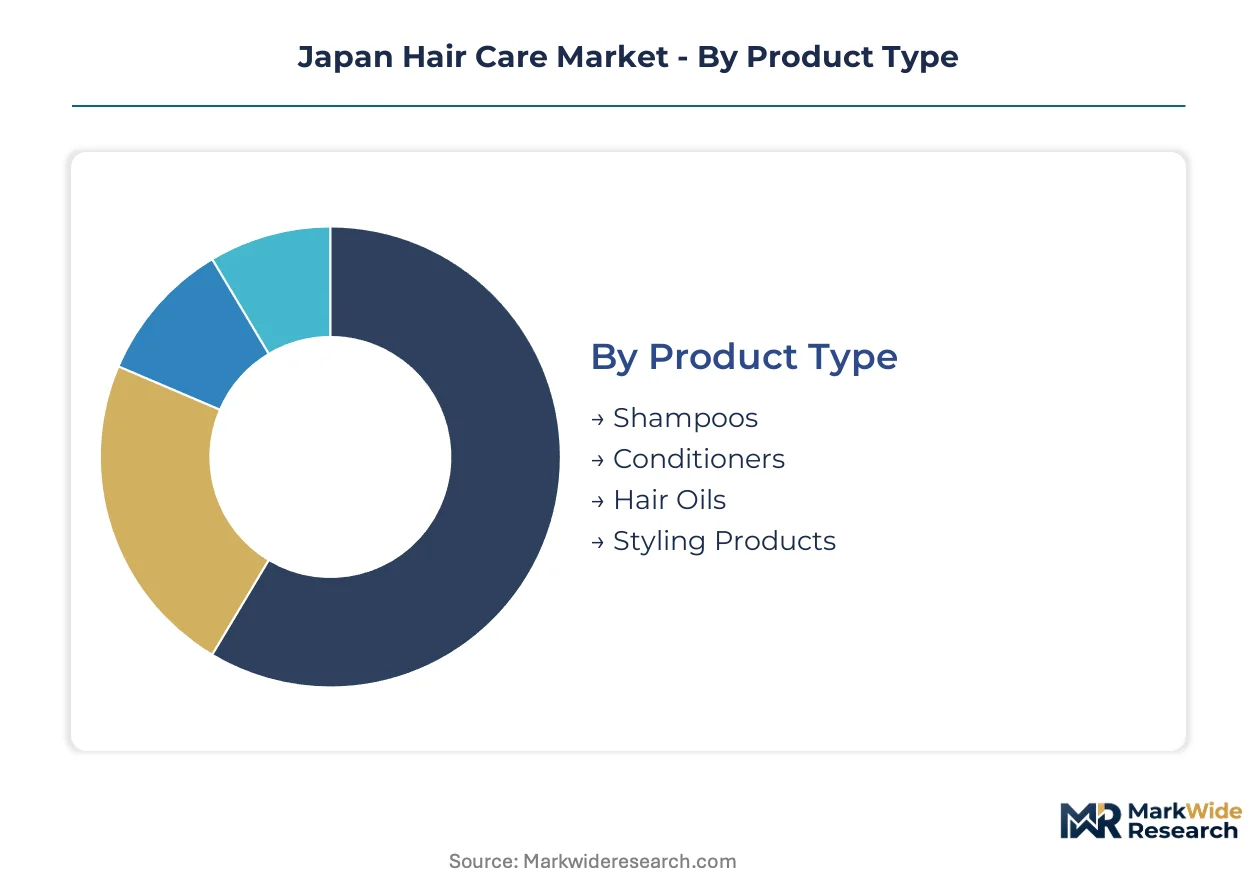
Segmentation in Japan's hair care market reveals how PMDA quasi-drug classifications, salon channel density, and aging demographics fragment demand across distinct technical and commercial profiles. Understanding these divisions exposes where formulation investment concentrates and which channels capture premium margin pools.
Product Type:
After-sales service intensity varies sharply across product types, with salon-dispensed treatments requiring ongoing professional consultation while mass-market shampoos demand minimal post-purchase engagement.
- Shampoos:Surfactant-based cleansing formulations operating at pH 4.5–6.0 constitute the volume foundation of Japan's hair care sector. Demand concentrates in mass-market channels across the greater Tokyo metropolitan area, where refillable packaging innovations and METI sustainability incentives are compressing per-unit packaging costs.
- Conditioners:Cationic conditioning agents and silicone derivatives deliver detangling and cuticle sealing functionality. Damage repair variants within professional salon networks in Osaka and Fukuoka command the highest attachment rates as heat styling prevalence accelerates service dependency.
- Hair Oils:Lightweight ester and botanical oil blends target frizz control and thermal protection for aging consumers experiencing increased hair porosity.
- Styling Products:Polymer-based hold and texturizing formulations span waxes, mousses, and sprays with varying humidity resistance grades.
By volume, shampoos lead. By growth pace, styling products are ahead.
Application:
Application segmentation tracks how Japanese consumers stratify their spending between preventive daily maintenance and reactive intervention as hair aging symptoms intensify.
- Daily Care:Routine cleansing and conditioning regimens form the baseline consumption pattern across all age cohorts. Volume concentrates in drugstore and supermarket channels throughout urban prefectures, where subscription replenishment models are displacing conventional retail purchasing among consumers aged 35-50.
- Heat Protection:Thermal barrier formulations containing silicones and hydrolyzed proteins mitigate styling tool damage. Professional salon attachment in Tokyo and Yokohama drives premium positioning as stylists prescribe product-protocol combinations.
- Damage Repair:Intensive treatments with ceramides, amino acids, and bond-rebuilding actives address structural degradation. This application expands most quickly within the B2B salon channel nationwide.
- Color Preservation:UV filters and antioxidant systems extend artificial color longevity, with demand clustering among metropolitan consumers accessing professional color services.
Daily care dominates absolute volume. Damage repair shows the steepest expansion trajectory.
Formulation:
Formulation choices in Japan reflect the tension between PMDA regulatory pathways and consumer positioning preferences around ingredient provenance and functional claims.
- Sulfate-Free:Plant-derived surfactant alternatives address sensitivity concerns and clean beauty positioning. Technical ceiling in sebum removal efficiency versus synthetic alternatives constrains mass-market penetration despite strong consumer interest.
- Organic:Certified botanical content and restricted synthetic additive profiles satisfy JIS labeling accuracy requirements. METI circular economy frameworks are driving refillable packaging adoption for these premium-positioned lines.
- Moisturizing:Humectant-rich bases with glycerin, hyaluronic acid, and panthenol target aging-related dryness in northern prefectures including Hokkaido.
- Anti-Dandruff:PMDA quasi-drug regulated actives such as zinc pyrithione and ketoconazole require clinical substantiation that elevates R&D investment thresholds and concentrates innovation among well-capitalized incumbents.
Moisturizing formulations lead by volume. Sulfate-free options are gaining share fastest.
Distribution Channel:
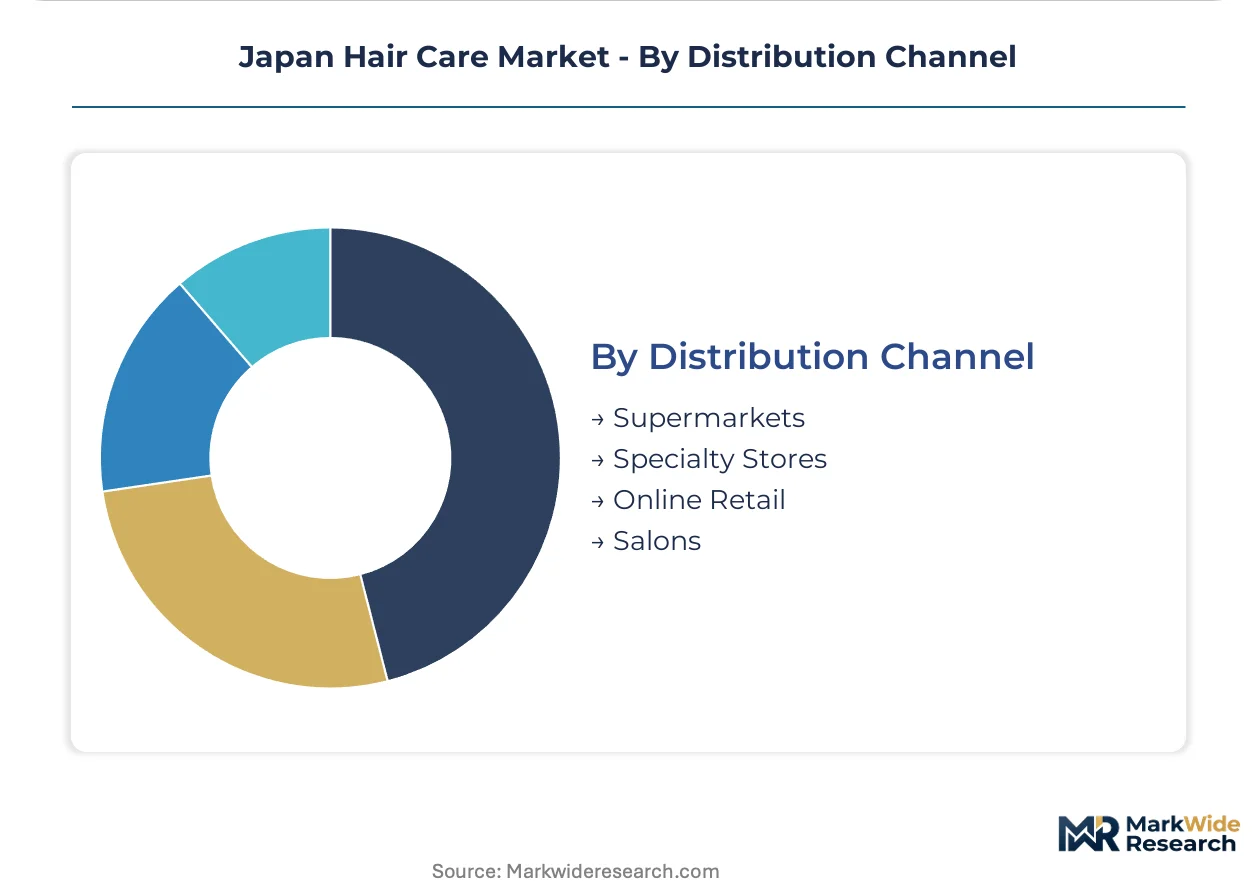
Channel segmentation exposes how digital disruption and salon service integration are reallocating value capture across Japan's hair care supply chain.
- Supermarkets:High-frequency replenishment of mass-market shampoos and conditioners serves price-sensitive household purchasing. Volume concentrates in greater Tokyo metropolitan area retail networks.
- Specialty Stores:Curated assortments with diagnostic consultation support premium and niche brand discovery. Urban prefecture locations capture the highest transaction values.
- Online Retail:Direct-to-consumer platforms with AI-powered regimen recommendations are capturing share from traditional channels. Subscription-based models show strongest traction among 35-50 year old consumers in Tokyo.
- Salons:Professional-only treatment lines and prescribed home maintenance protocols command premium shelf placement. Asset-light franchising models are narrowing capital barriers for regional network expansion in underdeveloped northern prefectures.
Supermarkets maintain volume leadership. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo metropolitan salons extract 40% price premiums over Hokkaido equivalents for identical treatment protocols. Kansai corridor density sustains Osaka as the secondary innovation cluster.
Kanto/Tokyo
Scalp diagnostic imaging adoption and AI-powered regimen personalization concentrate demand here. PMDA regulatory clarity on functional cosmetics boundaries shapes quasi-drug development pathways. Shibuya and Ginza salon networks pilot encapsulation technology for follicular penetration protocols.
Kansai/Osaka
Professional treatment attachment rates accelerate as heat styling prevalence drives damage repair service dependency. METI sustainability frameworks incentivize refillable packaging adoption across mass-market channels. Umeda and Namba retail corridors host premium brand flagship presence.
Chubu/Nagoya
Automotive industry commuter demographics sustain daily-care volume in drugstore and supermarket channels. JIS quality specifications constrain organic and sulfate-free labeling accuracy for regional manufacturers. Sakae district specialty stores curate diagnostic-supported premium discovery experiences.
Kyushu
Aging-related hair fragility expands professional service attachment in Fukuoka metropolitan salons. Import dependency for ceramide precursors exposes formulators to South Korean supplier currency fluctuation risk. Tenjin retail networks capture subscription replenishment traction among 35-50 year old consumers.
Hokkaido and Tohoku
Underdeveloped professional salon infrastructure presents first-mover potential for asset-light franchising models. Moisturizing formulation demand concentrates in northern prefectures addressing climate-related dryness. Sapporo and Sendai urban centers lag Tokyo pricing power by 25-30% for equivalent salon-grade treatments.
Japan Hair Care Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry expertise. The market structure concentrates among well-capitalized incumbents with integrated supply chains and professional distribution networks. Three archetypes dominate: diversified chemical conglomerates with captive R&D, salon-channel specialists with B2B prescription authority, and mass-market fast-moving consumer goods platforms with retail density. Competitive moves center on quasi-drug clinical trial investment and asset-light regional franchising expansion.
Within the diversified chemical conglomerate tier, Kao Corporation and Shiseido Co., Ltd. exemplify integrated supply chain control and professional salon network anchoring respectively. Milbon Co., Ltd. occupies the salon-channel specialist position with B2B treatment line dominance. These three entities represent distinct strategic pathways: manufacturing scale, professional prescription authority, and technical service attachment.
| Leading Market Players |
|---|
| Lion Corporation |
| Hoyu Co., Ltd. |
| Shiseido Co., Ltd. |
| Procter & Gamble Japan |
| Unilever Japan K.K. |
| Kao Corporation |
| Milbon Co., Ltd. |
| Arimino Co., Ltd. |
| Mandom Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in South Korean ceramide precursor production is compressing input costs for Japanese formulators while simultaneously eroding supplier pricing power across the treatment-grade segment. This utilization slack feeds directly into margin expansion for finished goods manufacturers and intensifies competition among specialty chemical suppliers vying for formulation partnerships.
Pricing Analysis
The customization-premium spread between salon-configured treatment protocols and mass-market standard formulations spans roughly 3x at retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under PMDA quasi-drug pathways and vertical integration depth among Kao and Shiseido. Pricing pressure stems from subscription model proliferation in Tokyo metropolitan online channels, where convenience bundling compresses per-unit margins. Mass-market drugstore consumers exhibit highest price sensitivity, while professional salon clients demonstrate lowest elasticity due to prescribed regimen attachment.
Supply Chain Analysis
Japan's export-control regime on advanced encapsulation technology limits cross-border licensing of liposome delivery systems to South Korean and Chinese manufacturers. Geographic supply concentration centers on South Korea for ceramide precursors, China for botanical extract raw materials, and domestic Japanese production for surfactant bases. Raw material dependencies encompass ceramide precursors, probiotic fermentation inputs, and plant-derived surfactants. Single-source vulnerability in South Korean specialty chemical suppliers exposes formulators to currency fluctuation risk. Distribution runs through professional salon networks for premium treatment lines and mass retail for daily maintenance formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's hair care sector is entering a high-growth disruption phase as PMDA regulatory clarity on functional cosmetics boundaries unlocks quasi-drug commercialization pathways previously blocked by clinical substantiation uncertainty.
For Market Incumbents: Pre-empt subscription platform consolidation by acquiring AI-driven personalization engines before direct-to-consumer challengers scale. Defend salon channel control through exclusive encapsulation technology licensing agreements that lock in professional treatment differentiation. Counter emerging digital-native entrants by embedding scalp diagnostic hardware into flagship retail locations. For New Entrants and Emerging Players: Establish a beachhead in Hokkaido and Tohoku asset-light franchising where professional salon infrastructure remains underdeveloped and first-mover premiums persist. Target men's scalp care segments in Fukuoka and Sapporo metropolitan areas where stigma reduction is accelerating faster than incumbent product development cycles. Deploy capital-light digital-first go-to-market models leveraging AI regimen recommendations to bypass traditional retail slotting fees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across direct-to-consumer subscription platforms as customer acquisition costs compress in Tokyo metropolitan density. Long-term viability favors platform integrators with captive AI personalization capabilities over component suppliers facing input cost volatility. Acquisition target archetype: regional salon franchisors with scalable training protocols. Monitor PMDA quasi-drug approval velocity as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | AI-powered subscription models capture share from Tokyo drugstore channels through convenience bundling. |
| Asset-Light Salon Franchising Expansion | Scalable training protocols unlock Hokkaido and Tohoku penetration without capital-heavy real estate commitments. |
| Quasi-Drug Clinical Trial Investment | PMDA-compliant substantiation creates defensible moats for hair growth claims against botanical extract competitors. |
| Encapsulation Technology Licensing | Liposome delivery partnerships with Osaka and Fukuoka salon chains professionalize at-home maintenance boundaries. |
| Sustainability Repositioning | METI circular economy alignment drives refillable packaging adoption across mass-market shampoo lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with salon chain procurement directors, formulation R&D chemists at Kao and Milbon, PMDA regulatory affairs specialists, and specialty chemical distribution managers. Secondary validation drew from METI circular economy framework disclosures, PMDA quasi-drug approval databases, JIS quality specification filings, and customs import records for ceramide precursors. Bottom-up shipment data from professional salon networks was triangulated against top-down retail audit estimates across Tokyo, Osaka, and Fukuoka metropolitan corridors.
Calibration approach anchored volume projections to historical PMDA approval velocity and salon channel expansion rates across prefecture-level density differentials. Segmentation dimensions modeled encompass product type, application intensity, formulation regulatory pathway, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating aging demographic shifts and heat styling prevalence trends. Forecast inputs included scalp diagnostic technology adoption curves and subscription model penetration rates among 35-50 year old urban consumers.
Sensitivities concentrate around PMDA regulatory interpretation shifts for functional cosmetics boundaries and South Korean supplier currency volatility. Forecasts reflect documented assumptions regarding salon franchising scalability and AI personalization technology maturation. Material shifts in PMDA quasi-drug clinical trial requirements or ceramide precursor trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Rice Water Shampoo Market
Hair Care
Hair Dye Market
Hair Care
Australia Hair Removal Market
Hair Care
Brazil Hair Care Market
Hair Care
Australia Hair Care Market
Hair Care
Hair Relaxer Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Edge Tamer Market
Hair Care
Professional Hair Care Products Market
Hair Care
Global Shampoo Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Care Market