
 BB Cushions Market | 2026-2036
BB Cushions Market Size, Share, and Industry Trends Forecast 2026-2036
BB Cushions Market Outlook
The EU REACH regulation is repositioning ingredient sourcing across the BB cushions supply chain as formulators phase out restricted UV filters and silicones. Amorepacific Corporation leverages its Seoul-based R&D campus to develop reef-safe alternatives ahead of compliance deadlines. L'Oréal S.A. anchors European production through its Clichy-sous-Bois facility, which now runs dedicated clean-beauty lines. Estée Lauder Companies differentiates via dermatologist-tested positioning that preempts tightening safety assessments.
BB cushions are portable foundation-delivery systems comprising saturated polyurethane sponges housed in compact cases, typically infused with pigments, humectants, and SPF actives for on-the-go complexion correction. The sponge's pore density, measured at 50-200 microns, controls release rate and finish quality during application. Liquid formulations dominate unit volume due to their blendability and compatibility with diverse skin types, while cream variants capture elevated margin pools among mature consumers seeking fuller coverage. Online shoppers represent the fastest-growing end-user channel as live-commerce platforms collapse discovery-to-purchase cycles.
The US FDA governs sunscreen-active claims under monograph rules, forcing reformulation when new filters lack approved status. South Korea's MFDS maintains stricter cosmetic safety dossier requirements than ASEAN harmonized standards, creating dual-track compliance costs for regional exporters. China's NMPA now mandates animal-test alternatives for imported cosmetics, reshaping entry pathways for Western brands. Stakeholders must monitor divergent SPF labeling regimes as regulatory fragmentation becomes the primary barrier to SKU standardization.
Market Dynamics
SPF-infused formulation mandates and polyurethane sponge supply concentration in East Asian chemical clusters are compressing formulation flexibility while elevating compliance costs for Western entrants.
Growth Catalysts
- REACH Phase-Down of Cyclomethicone:The EU's ECHA restrictions on D4/D5/D6 silicones force formulators toward plant-derived emollients, opening premium positioning for brands with clean-chemistry credentials.
- Live-Commerce Platform Expansion:China's Douyin and South Korea's Naver Shopping Live collapse discovery-to-purchase cycles, accelerating repurchase velocity among digitally native consumers.
- Seoul-Incheon R&D Cluster Density:Concentrated cosmetic science infrastructure enables rapid prototyping of reef-safe UV filters ahead of Hawaii and Palau marine-toxicity bans.
Market Restraints
- Polyurethane Sponge Supply Concentration:Over 70% of cosmetic-grade porous polyurethane originates from Zhejiang and Jiangsu province manufacturers, creating single-source vulnerability.
- FDA Sunscreen Monograph Rigidity:The US regulator's slow approval of new UV filters like Tinosorb S and Uvinul A Plus blocks formulation innovation for American-market SKUs.
- Silicone Price Volatility:Cyclomethicone alternatives derived from squalane or jojoba oil trade at 3-4x synthetic benchmarks, compressing mass-tier margins.
Strategic Opportunities
- Men's Grooming Underpenetration:South Korea's male cosmetics adoption rate exceeds 25% while Western markets sit below 8%, representing whitespace for neutral-toned cushion launches.
- Refillable Compact Systems:France's AGEC anti-waste law mandates recyclable packaging by 2025, rewarding brands with modular case architectures and cartridge subscription models.
- AI Shade-Matching Kiosks:Computer vision deployment in Sephora and Ulta Beauty stores reduces return rates while capturing skin-tone data for regional pigment calibration.
Industry Challenges
- Cross-Regulatory SPF Labeling Friction:The EU's UVA-PF rating, US broad-spectrum claim, and South Korea's PA++++ systems require triple-label SKUs or market-specific production runs.
- Clean-Beauty Certification Timeline:EWG Verified and COSMOS approvals demand 12-18 month dossier preparation, delaying product launches behind trend cycles.
- Legacy ERP Integration:Batch-record systems designed for conventional emulsion manufacturing struggle to capture sponge-saturation process parameters for quality traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BB Cushions Market |
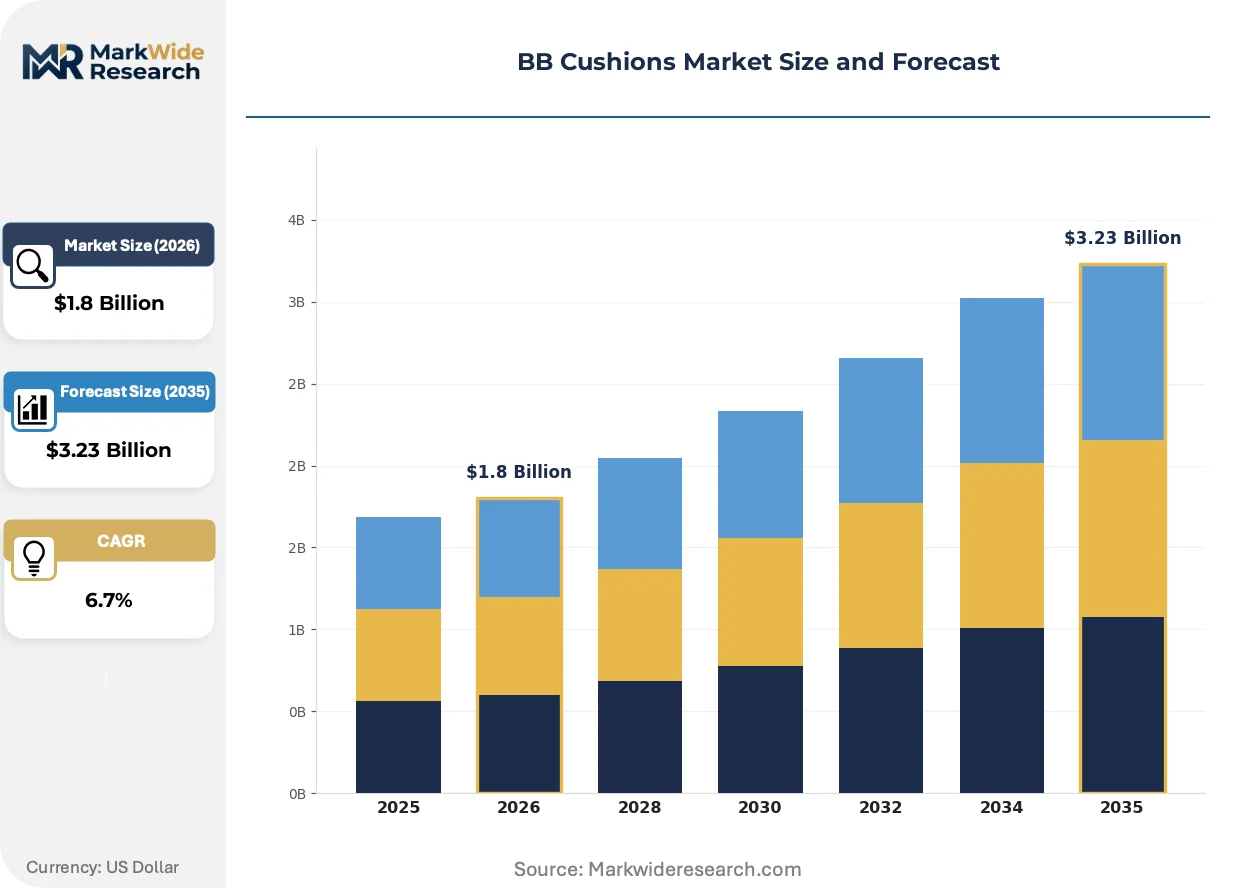
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Cream, Stick, Powder End User: Beauty Enthusiasts, Professional Makeup Artists, Retail Customers, Online Shoppers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Drugstores Price Tier: Premium, Mid-range, Budget, Luxury |
| Companies Covered | Shiseido Company, Christian Dior SE, L'Oréal S.A., Maybelline, Lancome, Clinique Laboratories, Amorepacific Corporation, Beiersdorf, Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BB Cushions Market Strategic Shifts
Biomimetic film-forming polymers and microencapsulated pigment delivery are replacing conventional silicone matrices, while regulatory divergence forces parallel formulation tracks for major export markets.
Microencapsulated titanium dioxide and zinc oxide is decentralizing UV protection architecture away from conventional chemical filters toward physical-mineral hybrids. Sensitive-skin and post-procedure segments in dermatology clinics adopt these systems fastest. The technology is decentralizing R&D investment from large multinationals toward specialized Korean and Japanese ingredient houses with encapsulation expertise.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics are extending to leave-on products, compelling formulators to eliminate synthetic glitter and nylon-12 powder from cushion compacts. The industrial consequence is accelerated qualification of cellulose-derived optical modifiers and mineral-based blurring agents. Premium-positioned brands with EU manufacturing footprints are responding fastest, using compliance as competitive differentiation against import-dependent competitors.
Subscription-based auto-replenishment is capturing loyalty among cushion users with predictable shade and coverage preferences. Direct-to-consumer channels displace traditional department-store counter traffic, particularly among millennial and Gen-Z cohorts. This behavioral shift concentrates most visibly in China's tier-one cities, where Tmall flagship stores now account for the majority of brand-owned revenue.
BB Cushions Market Segmentation
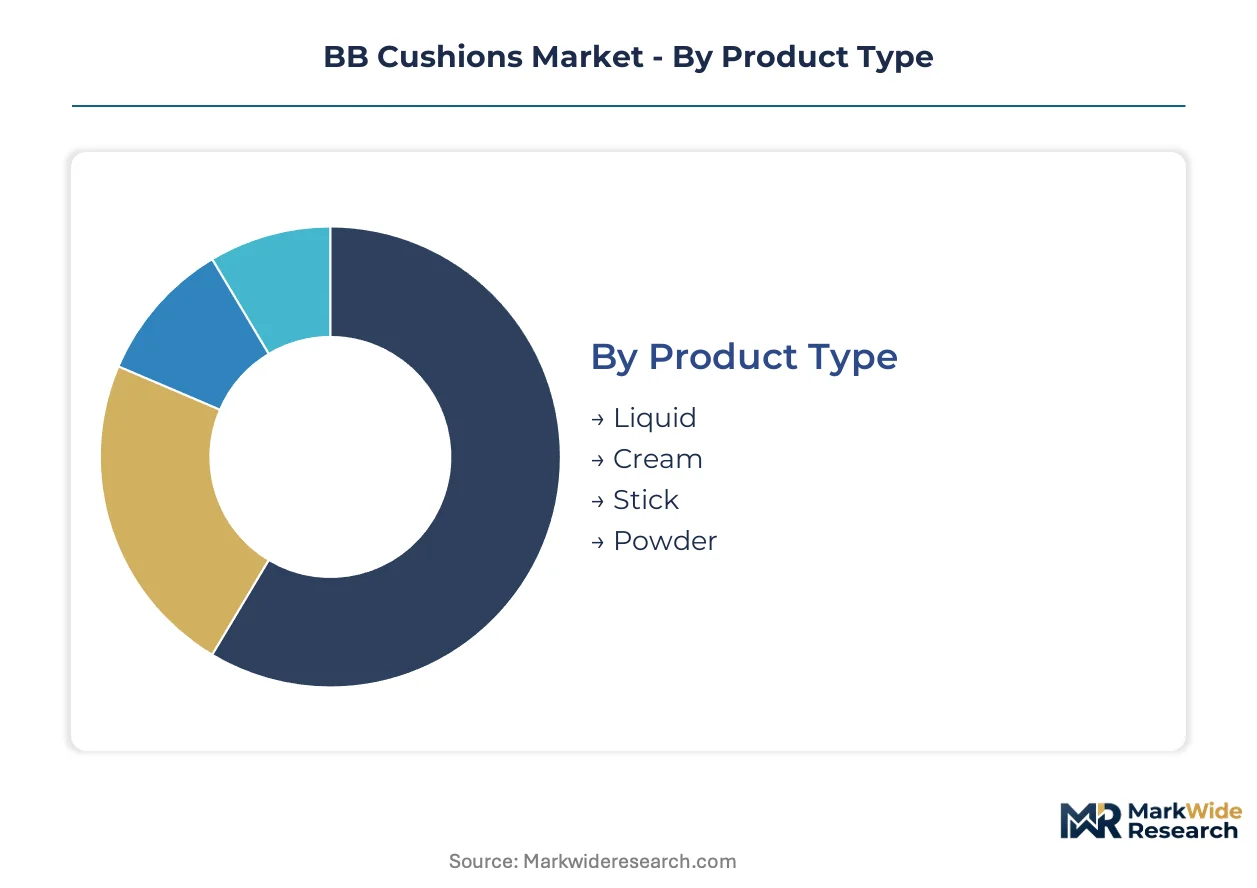
BB cushions command distinct upgrade cycles across formulation types and price tiers, with polyurethane sponge saturation rates and SPF actives driving replacement frequency. Understanding segment boundaries reveals where margin pools concentrate versus where volume scales fastest.
Product Type:
Replacement cycles vary sharply by viscosity class, with liquid formulations demanding refresh every 8-12 weeks versus powder compacts stretching to 20-24 weeks.
- Liquid:Low-viscosity emulsions saturate 50-100 micron polyurethane sponges for blendable, buildable coverage. Demand clusters among South Korea's Seoul-Incheon beauty cluster consumers seeking dewy finishes compatible with humid climates and layered skincare routines.
- Cream:Higher-pigment suspensions deliver fuller coverage for mature skin segments. Professional makeup artists in Los Angeles and New York studios drive adoption for editorial work requiring longevity under hot lighting.
- Stick:Solid balm formats suit travel-heavy users prioritizing portability and TSA compliance.
- Powder:Dry-pressed alternatives appeal to oily-skin demographics in Southeast Asian markets seeking matte control.
Volume placements concentrate in Liquid; the faster expansion belongs to Cream.
End User:
Customer acquisition costs diverge dramatically across professional versus amateur application contexts, reshaping marketing spend allocation.
- Beauty Enthusiasts:High-involvement consumers maintaining 4-6 active cushion SKUs rotate seasonal shades. This segment generates the highest lifetime value through subscription replenishment and limited-edition chase behavior.
- Professional Makeup Artists:Kit-building requirements demand 15-25 shade ranges per artist. Bridal and editorial specialists in Paris and Milan studios prioritize dermatologist-tested positioning for liability-sensitive client work.
- Retail Customers:Counter-assisted purchasers rely on shade-matching services and tactile sponge evaluation before commitment.
- Online Shoppers:Algorithm-driven discovery collapses consideration windows, with live-commerce platforms capturing impulse replenishment.
Beauty Enthusiasts anchor revenue concentration; Professional Makeup Artists climb the fastest as SPF-infused positioning penetrates commercial production.
Distribution Channel:
Channel economics reflect fulfillment infrastructure maturity and return-rate exposure, with sponge damage in transit creating unique logistics costs.
- Online Retail:Direct-to-consumer flagships and marketplace storefronts capture the steepest expansion trajectory as China's Douyin and South Korea's Naver Shopping Live collapse discovery-to-purchase cycles. Auto-replenishment subscriptions lock predictable repurchase.
- Specialty Stores:Sephora and Ulta Beauty locations deploy AI shade-matching kiosks to reduce mismatch returns while capturing skin-tone data for regional pigment calibration.
- Department Stores:Legacy counter models retain prestige-brand presence but face traffic erosion to digital channels.
- Drugstores:Mass-market placement competes on price accessibility with compressed margin structures.
Online Retail commands share gains; Specialty Stores defend margin through experiential differentiation.
Price Tier:
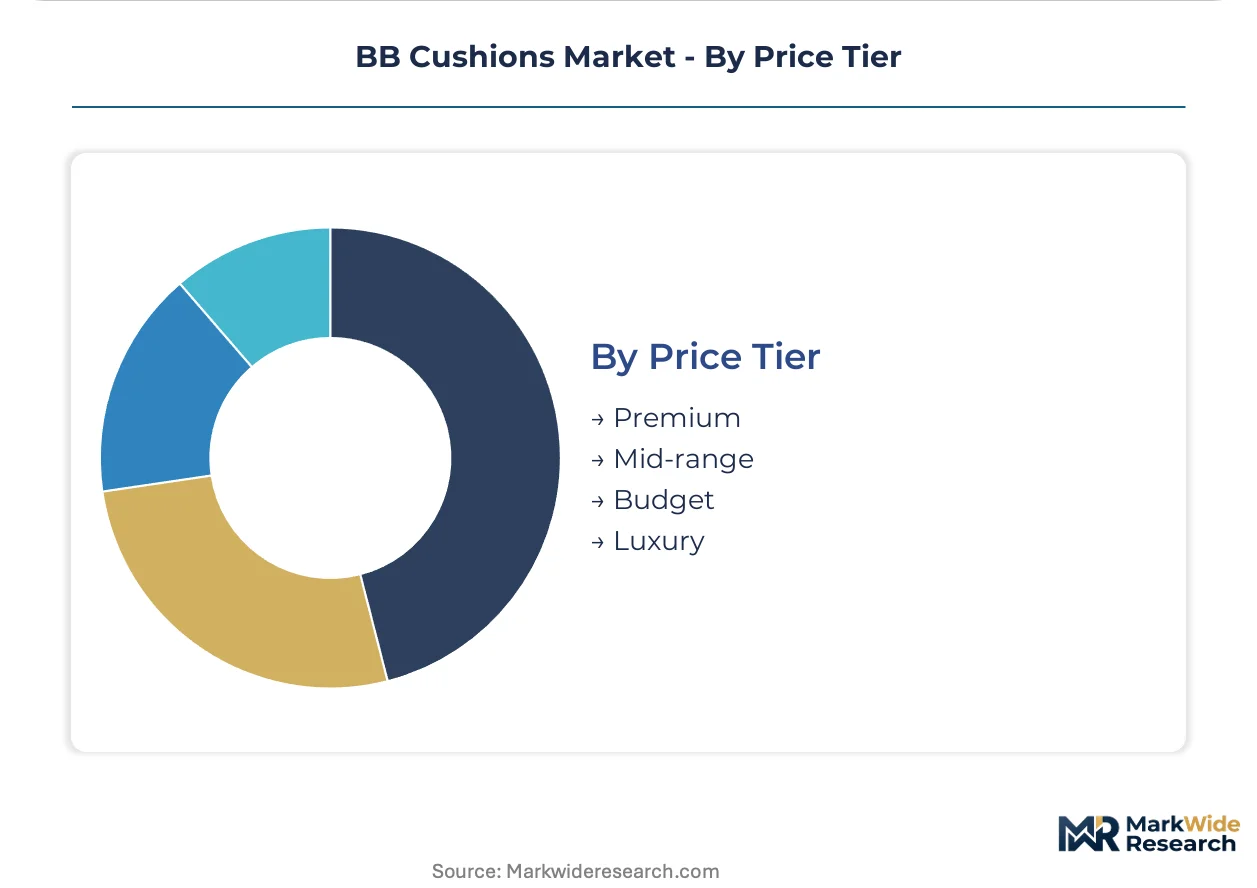
Pricing stratification maps to ingredient sourcing transparency and certification burden, with clean-beauty credentials commanding tier elevation.
- Premium:Mid-to-high positioning incorporates reef-safe UV filters and plant-derived emollients replacing restricted silicones. EU manufacturing footprints leverage REACH compliance as competitive moat against import-dependent competitors.
- Mid-range:Volume leaders balance performance claims with accessible price points, often omitting the costliest clean-certification badges.
- Budget:Price-driven placement concentrates in drugstore and mass-market online channels with simplified sponge architectures.
- Luxury:Ultra-premium tier commands case-weighted positioning and limited-edition artist collaborations, with refillable systems responding to France's AGEC anti-waste mandates.
Mid-range absorbs the heaviest volume; Premium gains share fastest as regulatory compliance reshapes ingredient costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Songdo International Business District anchors the densest concentration of BB cushion R&D infrastructure, with formulation labs and polyurethane sponge testing facilities clustering within the broader Seoul-Incheon corridor.
South Korea
MFDS cosmetic safety dossiers exceed ASEAN harmonized standards, creating compliance complexity for exporters. Seoul's Hongdae district generates viral cushion launches through beauty influencer networks. The Songdo cluster hosts Amorepacific Corporation's flagship R&D campus developing reef-safe UV filter alternatives.
United States
FDA sunscreen monograph rules block Tinosorb S and Uvinul A Plus approvals, constraining formulation innovation for American-market SKUs. Los Angeles bridal studios and New York editorial makeup artists drive professional-grade cushion adoption. Sephora's AI shade-matching kiosks in California and Texas reduce return rates while capturing skin-tone data.
China
NMPA mandates animal-test alternatives for imported cosmetics, reshaping Western brand entry pathways. Shanghai and Beijing tier-one cities concentrate Tmall flagship store revenue through live-commerce platforms. Zhejiang and Jiangsu provinces manufacture over 70% of cosmetic-grade polyurethane sponges, creating single-source supply vulnerability.
France
AGEC anti-waste law mandates recyclable packaging by 2025, rewarding refillable compact architectures. Parisian bridal specialists prioritize dermatologist-tested positioning for liability-sensitive client work. L'Oréal S.A.'s Clichy-sous-Bois facility runs dedicated clean-beauty production lines serving European demand.
Japan
METI standards and PMDA cosmetic regulations maintain stringent ingredient disclosure requirements. Tokyo's Shibuya and Harajuku districts sustain high-velocity cushion replacement cycles among beauty enthusiasts. Osaka-based ingredient houses specialize in microencapsulated titanium dioxide systems for sensitive-skin segments.
BB Cushions Market Competitive Environment
The competitive structure tilts toward diversified beauty conglomerates with captive R&D infrastructure. Consolidation pressures mount as clean-beauty certification timelines and REACH compliance costs favor scaled players with dedicated regulatory affairs teams. Three archetypes dominate: Seoul-based innovation specialists, Paris-New York luxury houses with dermatologist-tested positioning, and mass-market volume leaders with Zhejiang sponge supply partnerships. Geographic expansion through dedicated clean-beauty lines and technology licensing for reef-safe UV filter formulations represent the dominant competitive moves.
Among Asia-Pacific-based innovators, Amorepacific Corporation exemplifies the R&D-intensive archetype with its Songdo campus operations. L'Oréal S.A. and Estée Lauder Companies occupy positions within the diversified multinational tier, leveraging European and North American manufacturing footprints to navigate regulatory fragmentation. These three entities represent contrasting strategic postures: captive innovation, regulatory arbitrage through geographic production distribution, and dermatologist-tested premium positioning.
| Leading Market Players |
|---|
| Shiseido Company |
| Christian Dior SE |
| L'Oréal S.A. |
| Maybelline |
| Lancome |
| Clinique Laboratories |
| Amorepacific Corporation |
| Beiersdorf |
| Estée Lauder Companies |
| Others |
Value Chain & Pricing Dynamics
Beauty enthusiasts and professional makeup artists drive divergent pricing models across the BB cushions market, with the former accepting subscription premiums for auto-replenishment while the latter negotiate bulk kit-building rates. This buyer bifurcation compresses mid-range margins as brands simultaneously fund clean-beauty certification investments and absorb silicone-alternative cost premiums.
Pricing Analysis
SPF performance outcomes anchor value-based pricing tiers, with reef-safe UV filter formulations commanding 3-4x synthetic benchmarks over conventional chemical filters. Three-tier pricing structure across premium, standard, and economy levels separates EU-manufactured clean-beauty credentials from mass-market Zhejiang-sourced alternatives. Cost compression in the budget tier intensifies because polyurethane sponge supply concentration limits formulation flexibility. Professional makeup artists exhibit lowest price sensitivity due to liability-driven dermatologist-tested requirements, while online shoppers in China's tier-one cities chase algorithmic discounts.
Supply Chain Analysis
Freight costs from Zhejiang and Jiangsu provinces to Western distribution centers amplify landed costs for polyurethane sponge-dependent brands. Over 70% of cosmetic-grade porous polyurethane draws from East Asian chemical clusters, with reef-safe UV filter actives and plant-derived emollients as secondary input dependencies. Single-source vulnerability in sponge manufacturing creates structural risk as regional export compliance timelines tighten. Distribution runs through direct-to-consumer flagships and live-commerce platforms, collapsing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor scaled players with captive regulatory affairs teams as REACH compliance costs and clean-beauty certification timelines force smaller formulators toward exit or acquisition. ECHA restrictions on cyclomethicone and divergent SPF labeling regimes accelerate this filtration.
For Market Incumbents: Anchor defensive positioning through backward integration into Seoul-Incheon R&D infrastructure for reef-safe UV filter development. Prioritize modular compact architectures compliant with France's AGEC anti-waste mandates to capture refillable system premiums before 2025 deadlines. The threat of microencapsulated pigment delivery disruption from Osaka-based ingredient houses demands rapid qualification partnerships. For New Entrants and Emerging Players: Enter via men's grooming whitespace in Western markets where adoption rates sit below 8% versus South Korea's 25% benchmark. Target AI shade-matching kiosk deployment in Sephora and Ulta Beauty locations as the most penetrable channel, leveraging computer vision partnerships to reduce return-rate exposure. The go-to-market angle rests on neutral-toned cushion launches with TSA-compliant stick formats for travel-heavy demographics. For Investors and Strategic Acquirers: The window for entry favors mid-tier brands with pending COSMOS or EWG Verified certifications and established Zhejiang sponge supply partnerships. Long-term viability hinges on regulatory arbitrage capabilities across EU, US, and South Korean SPF labeling regimes. Watch NMPA animal-test alternative enforcement as the inflection signal reshaping Western brand entry pathways into China.| Strategic Initiative | Industry Significance |
|---|---|
| Reef-Safe UV Filter R&D Partnership | Amorepacific's Songdo campus accelerates compliance ahead of Hawaii marine-toxicity bans. |
| Refillable Compact Architecture Launch | L'Oréal's Clichy-sous-Bois facility captures France's AGEC mandate premiums. |
| Live-Commerce Platform Integration | Douyin and Naver Shopping Live collapse discovery-to-purchase cycles for Gen-Z cohorts. |
| AI Shade-Matching Kiosk Deployment | Sephora's computer vision systems reduce return rates while capturing skin-tone data. |
| Clean-Beauty Certification Investment | COSMOS and EWG Verified badges command tier elevation amid REACH phase-downs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this BB cushions market analysis. Primary interviews with cosmetic formulators, regulatory affairs specialists at beauty conglomerates, polyurethane sponge procurement managers, and live-commerce platform operators combined with secondary validation from MFDS safety dossiers, ECHA restriction updates, and FDA sunscreen monograph amendments. Bottom-up segmentation modeling and top-down macroeconomic reconciliation triangulated volume and value estimates.
Shipment data reconciliation with formulation cost structures and channel margin analysis framed the quantitative approach across the analysis window. Segmentation dimensions modeled include formulation viscosity class, end-user application context, distribution channel infrastructure maturity, and price tier certification burden. CAGRs derived from replacement cycle velocity analysis, with SPF regulatory divergence and live-commerce penetration as industry-specific forecast inputs.
Revisions become necessary when ECHA extends microplastic restrictions to leave-on cosmetics or when NMPA accelerates animal-test alternative mandates beyond current importer expectations. Forecasts reflect assumptions about polyurethane sponge supply stability and reef-safe UV filter approval timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
India Cosmetics Products Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market