
 Europe Fitness Rings Market | 2026-2036
Europe Fitness Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fitness Rings Market Analytics
Sensor miniaturization is narrowing the performance gap between finger-worn devices and wrist-based trackers across European markets. Oura Health Oy leverages titanium casing and temperature-sensing algorithms to anchor premium positioning in sleep analytics. Samsung Electronics competes through ecosystem integration with Galaxy smartphones and health platforms. Ultrahuman Healthcare Private Limited specializes in metabolic tracking via glucose correlation features, differentiating its ring for biohacker and athletic segments.
Fitness rings are compact wearable devices embedding photoplethysmography (PPG) sensors, accelerometers, and temperature monitors in a ring form factor, typically weighing under 4 grams and operating via low-energy Bluetooth protocols. These devices capture continuous biometric data for sleep staging, recovery metrics, and activity classification without the bulk of smartwatches. Smart rings command the highest margin pools due to advanced sensor fusion and subscription-tier analytics, while sleep monitoring rings represent the fastest-expanding category as European consumers prioritize recovery optimization. Activity tracking rings remain the most mature segment with commoditized hardware and compressed pricing.
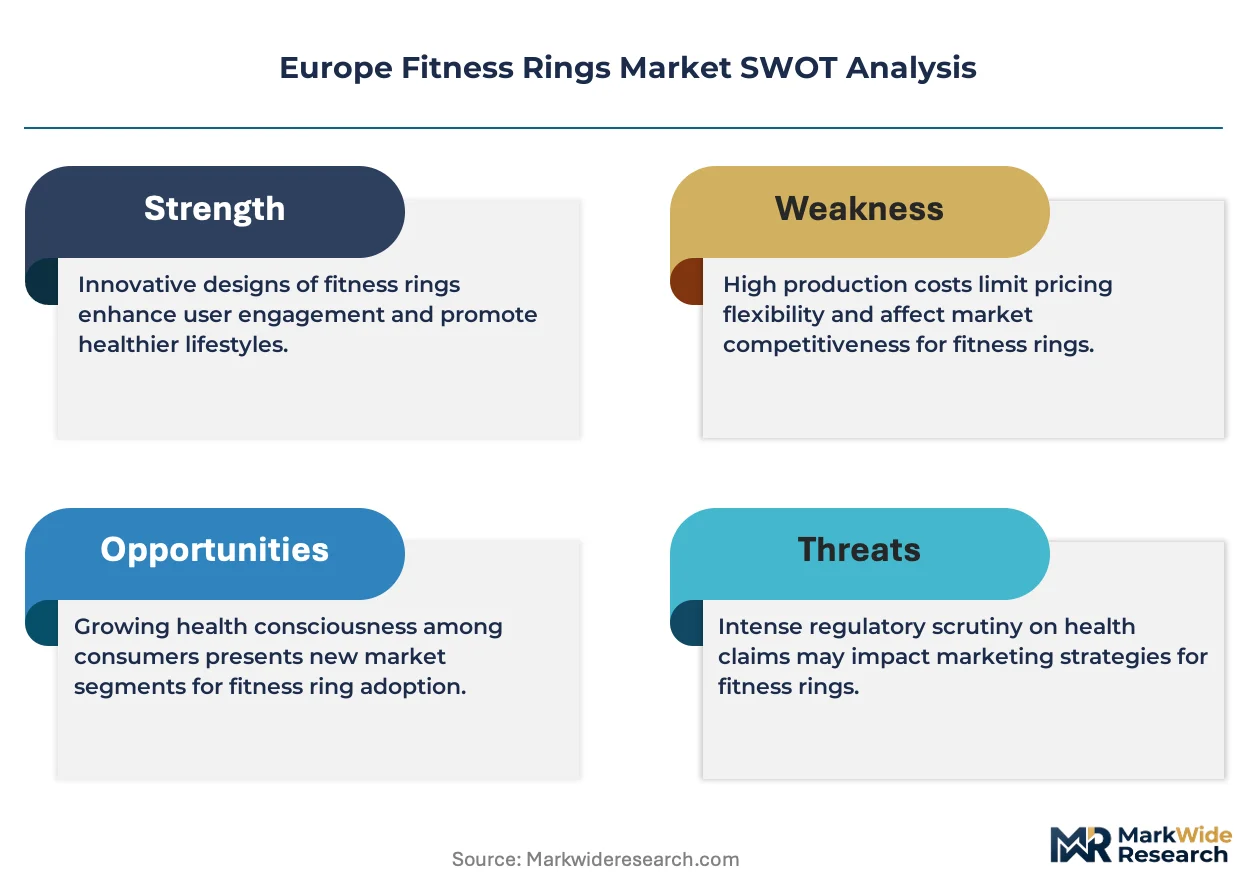
The EU Medical Device Regulation (MDR) and CE marking requirements shape product development timelines and clinical claim substantiation for biometric accuracy. GDPR imposes strict constraints on health data processing, storage localization, and cross-border transfers, directly affecting cloud architecture decisions by device vendors. The ECHA REACH framework governs material safety for metal alloys and ceramic coatings in prolonged skin contact. Stakeholders must weigh regulatory compliance investments against the pace of sensor innovation and shifting consumer expectations for medical-grade accuracy in non-clinical form factors.
Market Dynamics
The EU Medical Device Regulation (MDR) reclassification of biometric wearables is compressing product development timelines while elevating clinical validation requirements for heart rate and blood oxygen accuracy claims across European markets.
Growth Catalysts
- Professional athlete adoption:Sports teams across Germany, France, and the Netherlands are deploying rings for recovery monitoring and load management, creating institutional demand pull.
- GDPR-compliant health data architectures:Vendors investing in EU-localized cloud infrastructure are unlocking enterprise wellness contracts previously blocked by cross-border transfer restrictions.
- Photoplethysmography sensor maturation:Miniaturized PPG modules now deliver clinical-grade pulse oximetry from finger-worn form factors, narrowing the accuracy gap with wrist-based medical devices.
Market Restraints
- Titanium supply concentration:Premium casing alloys rely on sponge titanium flows from Russian and Chinese smelters, exposing margins to geopolitical supply disruptions.
- CE marking clinical trial costs:MDR Class IIa reclassification mandates biocompatibility testing and accuracy validation studies costing €200,000-€500,000 per SKU variant.
- Smartwatch substitution pressure:Apple Watch and Samsung Galaxy Watch ecosystem lock-in reduces addressable market for single-purpose ring devices among mainstream consumers.
Strategic Opportunities
- Spain and Italy wellness tourism:Recovery-tracking rings are penetrating luxury spa and thermal resort segments where sleep optimization commands premium pricing.
- EU AI Act compliance tooling:Biometric algorithm transparency requirements create white space for vendors offering explainable sleep staging and readiness score methodologies.
- Corporate occupational health mandates:Germany's Betriebsärzte (company doctors) are piloting ring-based stress and recovery monitoring for shift workers in manufacturing and logistics.
Industry Challenges
- Biomedical engineering talent scarcity:Firmware developers with photoplethysmography signal processing expertise command 40-60% salary premiums in Helsinki and Berlin labor markets.
- Notified Body backlog:Only 24 EU entities are designated for MDR medical device certification, creating 12-18 month queue delays for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fitness Rings Market |
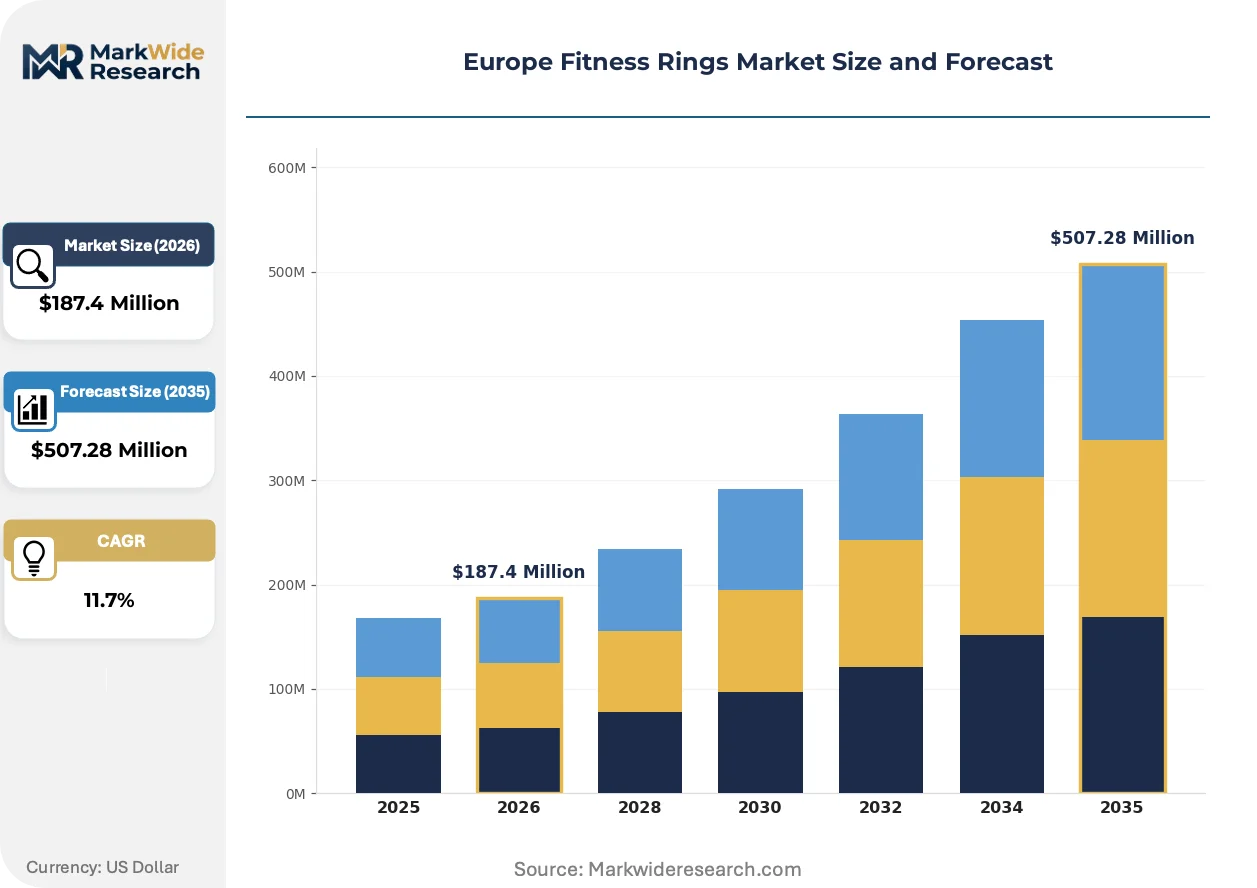
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Activity Tracking Rings, Sleep Monitoring Rings, Wellness Rings End User: Fitness Enthusiasts, Health-Conscious Individuals, Athletes, Casual Users Material: Metal, Silicone, Plastic, Ceramic Distribution Channel: Online Retailers, Specialty Fitness Stores, Department Stores, Direct Sales |
| Companies Covered | Oura Health Oy, Ultrahuman Healthcare Private Limited, Samsung Electronics, Fitbit (Google Inc.), RingConn, Circular, ArcX Technology, Velia Ring, Noise, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fitness Rings Market Evolving Landscape
Sensor fusion architectures and algorithmic transparency requirements are reshaping competitive differentiation in European fitness rings, with vendors racing to embed medical-grade accuracy into sub-4 gram form factors while navigating evolving privacy frameworks.
Multi-wavelength photoplethysmography is digitizing cardiovascular monitoring capabilities previously confined to clinical pulse oximeters. German Bundesliga football clubs and Dutch Olympic training centers are deploying these modules for nocturnal heart rate variability tracking. The technology is digitizing recovery analytics by enabling continuous autonomic nervous system assessment without sleep laboratory infrastructure.
The EU AI Act's high-risk system classification for biometric identification is forcing algorithmic audit trail investments across the vendor base. Manufacturers must now document training data provenance and performance metrics for sleep staging models. Ring vendors targeting occupational health contracts in France and Belgium are prioritizing explainable AI features to satisfy works council scrutiny of automated wellness scoring.
Subscription unbundling is fragmenting the traditional hardware-plus-software bundle. Scandinavian consumers increasingly purchase devices through retail channels while activating analytics tiers via direct-to-consumer monthly plans. This pattern concentrates most visibly in Finland and Sweden, where Oura's domestic brand recognition supports channel-agnostic customer acquisition without carrier or electronics retailer intermediation.
Europe Fitness Rings Market Segmentation
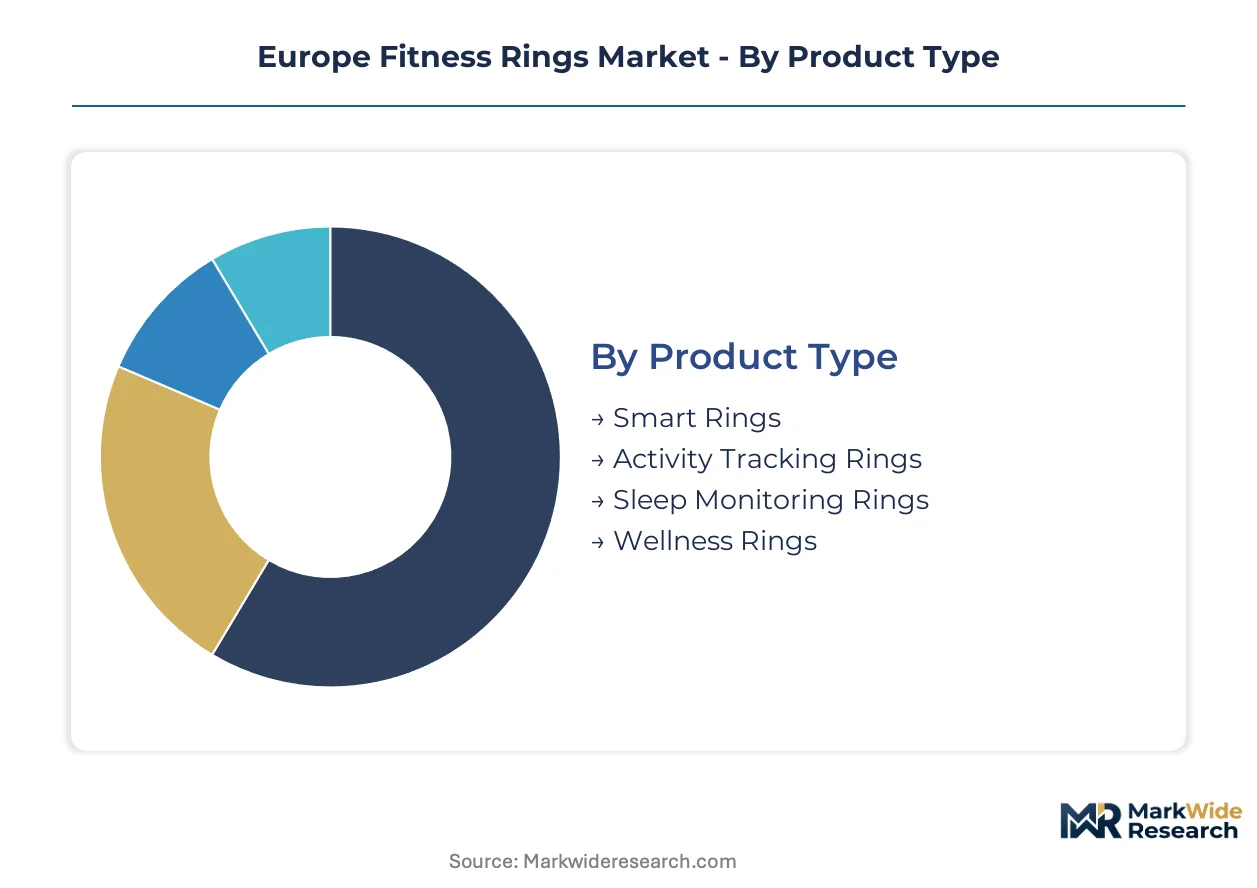
Segmentation in the Europe fitness rings market reveals divergent paths to profitability. Product architecture, user sophistication, material selection, and channel economics each create distinct margin profiles and regulatory exposure zones across Germany, France, and Nordic markets.
Product Type:
Use-case spectrum spans clinical-grade recovery monitoring to lightweight activity logging, with sensor fusion depth determining pricing power and CE marking obligations under MDR.
- Smart Rings:Multi-sensor platforms integrating photoplethysmography, accelerometry, and temperature monitoring in titanium or ceramic housings. Demand concentrates among biohackers and Bundesliga athletic programs in Germany seeking medical-adjacent accuracy without wrist-worn bulk.
- Sleep Monitoring Rings:Specialized nocturnal form factors emphasizing heart rate variability and sleep staging algorithms. Scandinavian consumers in Finland and Sweden drive fastest category expansion as recovery optimization displaces step-counting in wellness priorities.
- Activity Tracking Rings:Stripped-down accelerometer-based devices for step and calorie estimation. Budget positioning in France and Italy faces compression from smartwatch substitution.
- Wellness Rings:Stress and mindfulness-oriented hardware with guided breathing features. Penetrates corporate wellness channels in the Netherlands where occupational health mandates expand.
Established volume favors activity tracking rings; emerging adoption favors sleep monitoring rings.
End User:
Customer archetypes stratify by data literacy, with professional athletes and institutional buyers commanding bespoke firmware while casual users drive retail velocity.
- Athletes:Professional sports teams and Olympic training centers in Germany and the Netherlands requiring load management dashboards and API access for coaching platforms. MDR Class IIa compliance unlocks enterprise contracts blocked by liability concerns.
- Fitness Enthusiasts:Quantified-self practitioners seeking granular recovery metrics and trend visualization. Germany's premium health spending culture supports subscription-tier attachment rates above regional averages.
- Health-Conscious Individuals:Preventive health adopters prioritizing sleep quality and cardiovascular awareness over athletic performance. Spain's wellness tourism sector pilots ring deployments in thermal resort environments.
- Casual Users:Gift purchasers and step-counters with low engagement and high churn. Price sensitivity in Italy and Poland limits margin extraction without carrier subsidy models.
Revenue concentration clusters with athletes and fitness enthusiasts; user base expansion depends on casual user conversion.
Material:
Material selection trades biocompatibility certification burden against perceived durability and skin sensitivity profiles across extended wear scenarios.
- Metal:Titanium and surgical steel alloys dominate premium positioning. ECHA REACH compliance for nickel release testing adds €15,000-€30,000 per SKU validation cycle.
- Ceramic:Zirconia-based formulations offer scratch resistance and hypoallergenic properties. Italian design houses favor ceramic for fashion-forward wellness ring collaborations.
- Silicone:Flexible polymer shells for sport-specific applications and sizing adaptability. Budget tier in France leverages silicone to hit sub-€100 retail price points.
- Plastic:ABS and polycarbonate housings for disposable trial units and pediatric applications. Limited European presence due to environmental regulations and consumer preference for premium materials.
Margin capture concentrates in metal and ceramic; volume accessibility runs through silicone.
Distribution Channel:
Channel mix reflects GDPR data architecture requirements and the collapse of hardware-software bundling across Nordic markets.
- Online Retailers:Amazon and native platforms dominate in Germany and the UK, enabling subscription unbundling where consumers purchase hardware and activate analytics tiers separately.
- Direct Sales:Vendor-owned e-commerce and showroom models in Finland and Sweden. Oura's domestic brand recognition supports channel-agnostic acquisition without electronics retailer intermediation.
- Specialty Fitness Stores:Running and triathlon retailers in the Netherlands and Belgium provide fitting services and coaching integration. High-touch model justifies 25-35% retail margins.
- Department Stores:El Corte Inglés in Spain and Galeries Lafayette in France reach wellness tourists and gift purchasers. Seasonal demand spikes strain inventory planning.
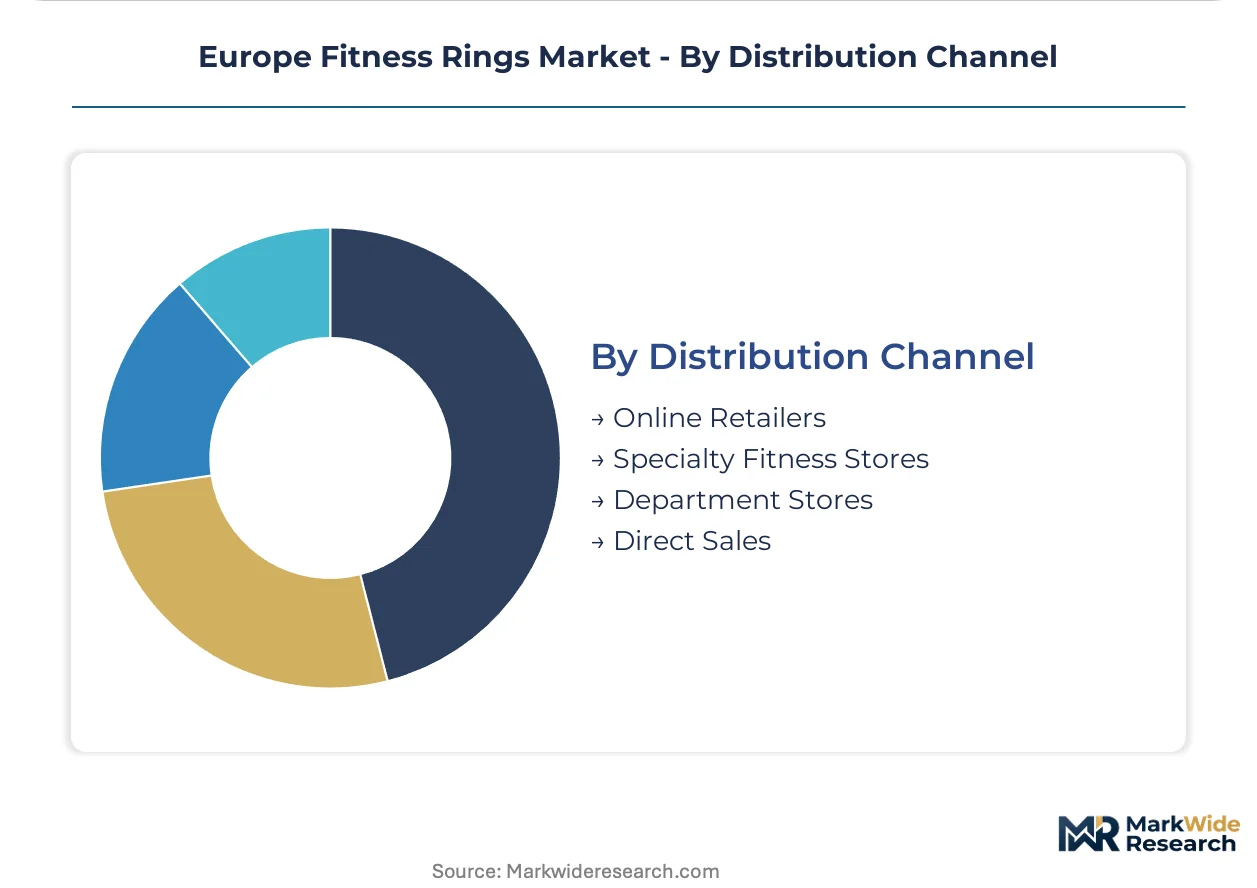
Subscription economics favor online retailers and direct sales; experience differentiation favors specialty fitness stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish manufacturers export titanium-cased smart rings to German sports medicine clinics and Dutch corporate wellness programs, establishing a Baltic-to-Central Europe trade corridor for biometric wearables.
Germany
Bundesliga football clubs and Olympic training centers drive institutional procurement of recovery-monitoring hardware. The EU Medical Device Regulation (MDR) mandates CE marking and clinical validation for heart rate accuracy claims, extending product development timelines. Berlin and Munich host the continent's densest cluster of sports technology integrators, where coaching platforms demand API-accessible biometric data streams.
Netherlands
Corporate occupational health mandates expand demand for stress-tracking wearables among shift workers in manufacturing and logistics. GDPR-compliant cloud architectures unlock enterprise contracts previously blocked by cross-border data transfer restrictions. Eindhoven's health technology corridor anchors firmware development for photoplethysmography signal processing, with Betriebsärzte piloting ring-based recovery programs.
Sweden
Subscription unbundling concentrates visibly here as consumers purchase hardware through retail channels while activating analytics tiers via direct monthly plans. The Swedish Work Environment Authority influences wearable deployment standards for employee wellness programs. Stockholm's quantified-self community drives premium attachment rates for sleep optimization features.
Spain
Wellness tourism operators in thermal resorts pilot recovery-tracking rings for sleep optimization packages targeting premium leisure travelers. The Spanish Agency for Medicines and Health Products (AEMPS) oversees borderline medical device classifications for biometric claims. Catalonia and Andalusia concentrate luxury spa deployments where ring-based sleep analytics command premium pricing.
France
Works council scrutiny of automated wellness scoring pushes vendors toward explainable AI features for occupational health contracts. The Commission nationale de l'informatique et des libertés (CNIL) enforces strict health data processing constraints on employer-sponsored wearable programs. Paris anchors fashion-forward wellness ring collaborations with Italian design houses seeking ceramic form factors.
Europe Fitness Rings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware-software bundles and unbundled subscription tiers. The vendor base stratifies into three layers: ecosystem-integrated electronics conglomerates, dedicated biometric wearable specialists, and component-assembling challengers. Strategic moves center on MDR compliance acceleration and titanium supply security rather than price-based displacement.
Among Nordic-origin specialists, Oura Health Oy exemplifies the premium-tier archetype through domestic brand recognition and channel-agnostic customer acquisition. Samsung Electronics occupies the ecosystem-integrated position, leveraging Galaxy smartphone distribution for ring hardware placement. Ultrahuman Healthcare Private Limited anchors the metabolic-tracking specialization, differentiating through glucose correlation features for biohacker segments.
| Leading Market Players |
|---|
| Oura Health Oy |
| Ultrahuman Healthcare Private Limited |
| Samsung Electronics |
| Fitbit (Google Inc.) |
| RingConn |
| Circular |
| ArcX Technology |
| Velia Ring |
| Noise |
| Others |
Value Network & Pricing Analysis
Titanium sponge supply concentration in Russian and Chinese smelters determines both the premium-to-economy pricing spread across European fitness rings and the geographic shape of component sourcing networks. MDR Class IIa certification costs and REACH biocompatibility testing further compress margin structures for vendors without backward integration into sensor module production.
Pricing Analysis
Current-generation multi-sensor smart rings command three-tier pricing separation between medical-adjacent titanium models, mid-tier ceramic alternatives, and economy silicone variants. Price differentiation rests on CE marking tier and sensor fusion depth, with MDR-validated heart rate accuracy unlocking enterprise contracts at premium attachment rates. Cost compression in the activity-tracking tier intensifies due to Apple Watch ecosystem lock-in, while professional athletic programs in Germany show lowest price sensitivity for recovery-monitoring hardware.
Supply Chain Analysis
Foxconn and Pegatron hold dominant contract-manufacturing capacity for miniaturized PPG sensor integration in Taiwan and Vietnam. Component sourcing draws from Japanese accelerometer foundries, Finnish firmware development clusters, and German precision-machining houses for titanium casing. Single-source vulnerability concentrates in photodiode arrays from South Korean suppliers. Distribution runs through direct-to-consumer channels in Nordic markets and specialty fitness retailers in the Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's fitness ring market sits at a platform-economics inflection where interoperability with coaching dashboards and hospital EMR systems determines vendor survival. Samsung's Galaxy Health ecosystem integration demonstrates how smartphone distribution advantages compound in biometric wearable penetration.
For Market Incumbents: Build regulatory moats through accelerated MDR Class IIa certification pipelines and EU-localized cloud infrastructure investments. Secure titanium sponge offtake agreements with non-Russian suppliers to hedge geopolitical disruption. Defensive consolidation should prioritize firmware teams with photoplethysmography signal-processing expertise in Berlin and Helsinki labor markets. For New Entrants and Emerging Players: Build out metabolic-tracking specialization targeting biohacker segments underserved by recovery-focused incumbents. Spain's wellness tourism thermal resorts and Italy's fashion-forward ceramic collaborations represent penetrable white-space channels. A direct-to-consumer subscription model bypasses electronics retailer margin extraction in price-sensitive Southern European markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive sensor-fusion capabilities and notified body relationships. Long-term viability hinges on algorithmic transparency tooling for EU AI Act compliance. Watch for inflection signals in corporate occupational health procurement velocity among German Betriebsärzte programs and Dutch manufacturing shift-worker deployments.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | CE marking pathway unlocks Bundesliga and Olympic training center contracts blocked by liability frameworks. |
| EU Cloud Localization Investment | GDPR-compliant data architecture enables enterprise wellness contracts previously restricted by cross-border transfer rules. |
| Sensor Fusion R&D Expansion | Multi-wavelength PPG development narrows accuracy gaps with wrist-based medical devices for nocturnal HRV tracking. |
| Titanium Supply Diversification | Non-Russian sponge sourcing defends margin structures against ECHA REACH compliance cost inflation. |
| Explainable AI Feature Development | Algorithmic audit trails satisfy French works council scrutiny and Belgian occupational health procurement standards. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sports medicine clinicians, biomedical firmware engineers, procurement leads at German Bundesliga clubs, notified body certification specialists, and wellness tourism operators in Catalonia. Secondary validation drew from EMA MDR guidance documents, ECHA REACH substance databases, EU AI Act implementation texts, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Calibration anchored volume and value outputs to modeled segmentation across product architecture tiers, end-user sophistication levels, material certification grades, and channel economics patterns. CAGRs were derived from installed base penetration curves and replacement cycle assumptions. Industry-specific forecast inputs included MDR notified body queue dynamics and GDPR cloud infrastructure buildout timelines.
Stress conditions across titanium supply disruption scenarios, MDR reclassification scope expansion, and smartwatch substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sensor miniaturization trajectories and regulatory enforcement intensity. Quarterly review of notified body designation expansions and corporate wellness procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Weight Training Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Personal Exercise Mats Market