
 Synthetic Ice Skating Rink Market | 2026-2036
Synthetic Ice Skating Rink Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Ice Skating Rink Market Insights
Aftermarket service revenue from panel refurbishment and glide-agent reapplication is narrowing as a margin pool, shifting value capture from initial installation toward recurring maintenance contracts. Glice leverages its European manufacturing base to sustain premium positioning in commercial installations. Xtraice competes through extensive distributor networks across Nordic and North American markets. PolyGlide Ice specializes in residential-scale modular systems, occupying a fragmented but expanding consumer segment with lower capital barriers.
Synthetic ice skating rinks consist of interlocking polymer panels—typically ultra-high molecular weight polyethylene or specialized polypropylene composites—engineered with self-lubricating additives to simulate ice glide without refrigeration infrastructure, enabling year-round skating in climates unsuited to natural ice maintenance. The primary commercial purpose centers on eliminating energy-intensive chilling systems while extending operational seasons for venues with space or budget constraints. Modular rinks dominate commercial deployments due to rapid assembly and relocation flexibility, while poured systems retain niche positioning in permanent entertainment venues seeking seamless surface aesthetics. Composite material formulations represent the fastest-evolving segment, with manufacturers integrating ceramic or fluoropolymer additives to reduce friction coefficients and extend panel lifespan under heavy traffic loads.
ASTM International standards govern surface hardness and glide performance benchmarks for synthetic ice products sold in the United States, while the European Committee for Standardization oversees CE marking requirements for polymer-based recreational surfaces under the Construction Products Regulation. REACH compliance from ECHA restricts certain plasticizer chemistries, forcing reformulation among suppliers serving European entertainment venues and municipal buyers. Stakeholders must monitor evolving municipal procurement standards for recycled content mandates, as sustainability criteria increasingly filter into public-sector rink specifications across multiple jurisdictions.
Market Dynamics
Ultra-high molecular weight polyethylene formulation advances are compressing performance gaps with natural ice, redirecting procurement decisions across municipal recreation departments toward polymer-based installations that eliminate refrigeration infrastructure entirely.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on legacy plasticizer chemistries are accelerating reformulation investments among European compounders, producing self-lubricating additive packages that extend panel lifespan under heavy traffic loads.
- Suburban municipality procurement:North American municipal recreation departments are expanding year-round public programming budgets to include synthetic rink installations, driven by operational cost reductions versus seasonal natural ice maintenance.
- Modular panel systems:Rapid-assembly interlocking designs are enabling venue operators to reconfigure rink dimensions between programming blocks, capturing incremental rental revenue from multi-use entertainment complexes.
Market Restraints
- Petrochemical feedstock volatility:UHMWPE resin prices fluctuate with ethylene monomer supply conditions, compressing manufacturer margins and creating quote validity challenges for project-based municipal tenders.
- European compounder concentration:Specialty polymer additive production clusters in Germany and the Netherlands, exposing buyers to single-source risk for ceramic and fluoropolymer glide-enhancing formulations.
- Glide coefficient ceiling:Current UHMWPE formulations plateau within 10 percent of natural ice friction benchmarks, limiting expansion into elite training facility segments where performance authenticity remains non-negotiable.
Strategic Opportunities
- Residential consumer segment:Modular backyard rink systems present underpenetrated demand among North American suburban households seeking low-capital entry points for private skating access.
- Recycled content mandates:Municipal procurement standards across multiple US states are embedding minimum post-consumer polymer requirements, creating first-mover advantage for manufacturers with circular material certification.
- Entertainment complex convergence:Synthetic rinks are integrating with augmented reality projection systems and automated skate rental kiosks, enabling Nordic commercial venues to differentiate through immersive experience layering.
Industry Challenges
- Installation technician certification:Proper panel alignment and glide-agent application require specialized training that outpaces current vocational program output, creating project timeline risk for seasonal installation windows.
- ASTM surface hardness compliance:Testing protocol variability between third-party laboratories generates certification delays, particularly for composite formulations integrating experimental ceramic additives.
- Aftermarket service unbundling:Panel refurbishment and glide-agent reapplication contracts require distinct sales capabilities from initial installation teams, forcing organizational restructuring among historically product-centric suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Ice Skating Rink Market |
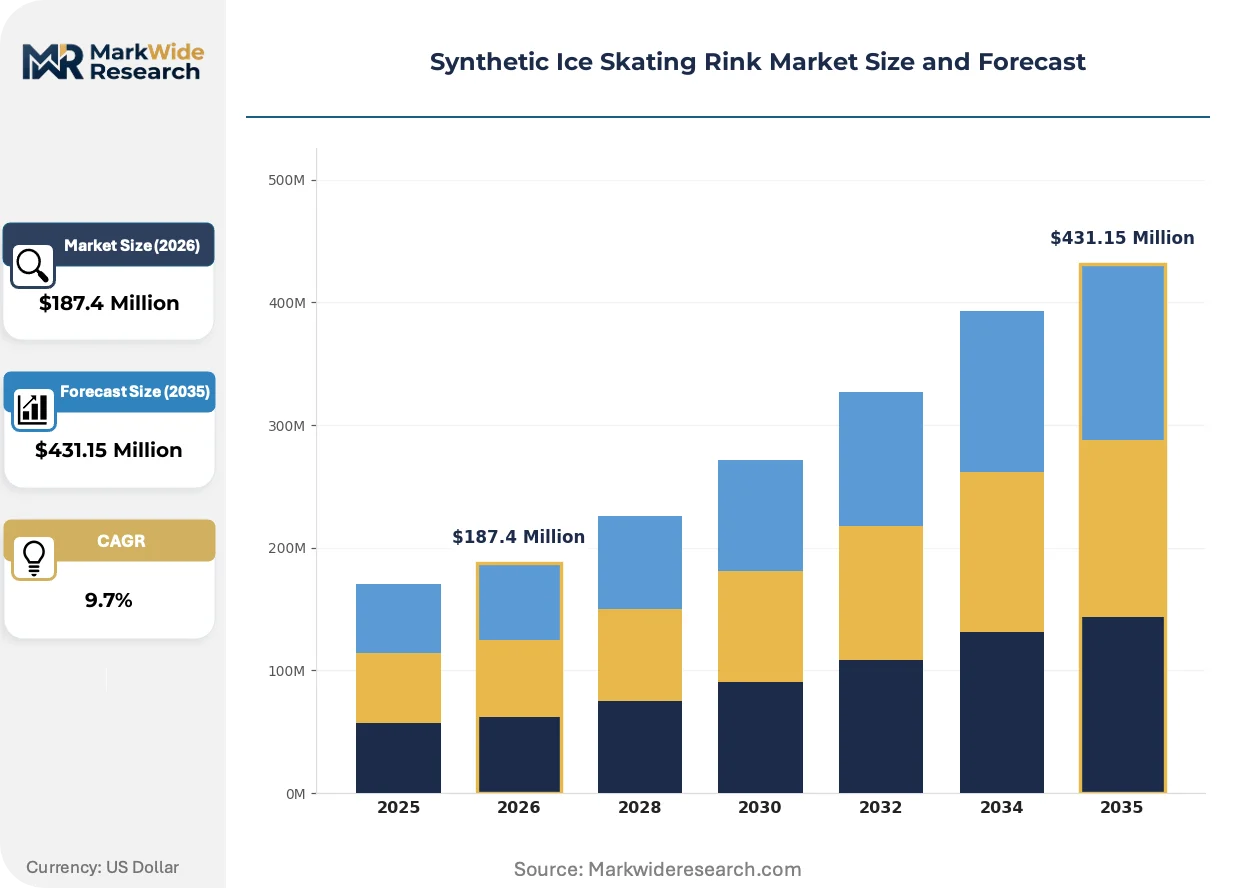
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Rinks, Portable Rinks, Poured Rinks, Pre-Fabricated Rinks Application: Recreational Use, Professional Training, Competitive Sports, Events End User: Sports Clubs, Entertainment Venues, Schools, Residential Users Material: Polyethylene, Polypropylene, PVC, Composite Materials |
| Companies Covered | Glice, Xtraice, PolyGlide Ice, KwikRink Synthetic Ice, Global Synthetic Ice, HockeyShot, SmartRink, Synthetic Ice Solutions, D1 Backyard Rinks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Ice Skating Rink Market Trends and Innovations
Material science breakthroughs and procurement digitization are restructuring how synthetic ice specifications travel from compounders to end-users, compressing traditional specification cycles while elevating performance verification requirements.
Self-lubricating polymer formulations are migrating from standard UHMWPE base resins toward composite structures integrating fluoropolymer microspheres and ceramic particulates. Municipal buyers in Germany and the United States are piloting these advanced formulations for high-traffic public installations. The technology is migrating from premium commercial entertainment venues toward mid-tier municipal deployments as manufacturing scale reduces unit panel costs.
REACH restrictions enforced by ECHA are eliminating certain phthalate-based plasticizers from polymer formulations serving European entertainment venues. Compounders are accelerating bio-based lubricant additive development to maintain glide performance under tightened chemical safety thresholds. Nordic commercial complexes are responding fastest, embedding reformulation compliance into long-term maintenance contracts to lock in supplier relationships ahead of mandate expansion.
Municipal procurement departments are consolidating synthetic rink specifications into centralized digital platforms that standardize performance benchmarks across multiple vendor submissions. Traditional distributor-led specification processes are compressing toward direct manufacturer engagement for technical validation. This pattern is most visible across United States suburban municipalities where recreation department budgets operate under centralized county-level purchasing authority.
Synthetic Ice Skating Rink Market Segmentation
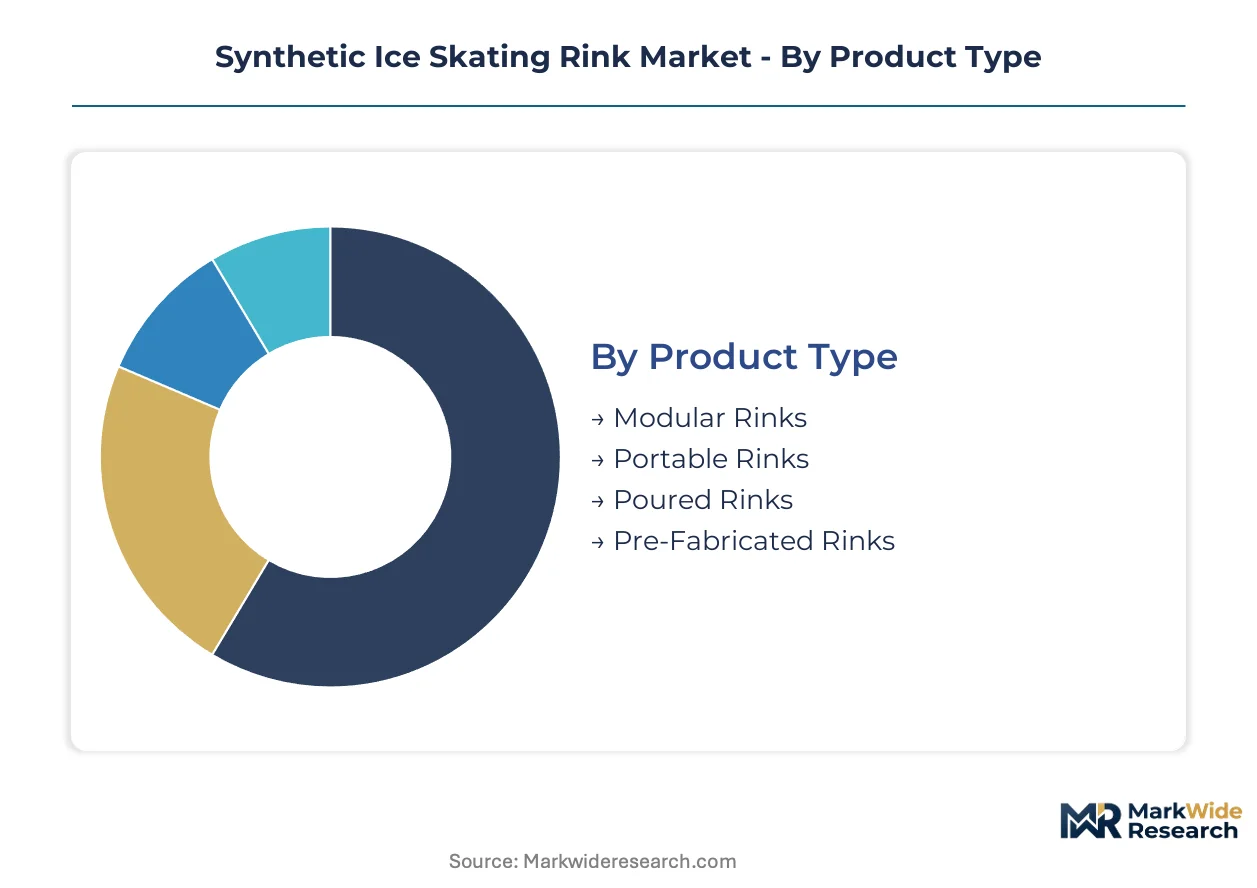
Synthetic ice rink procurement varies sharply by installation permanence and user sophistication, with each segment demanding distinct service intensity levels from glide-agent replenishment to panel refurbishment cycles. Material formulation and application context determine margin durability across the value chain.
Product Type:
After-sales service intensity peaks with permanent installations requiring scheduled refurbishment, while portable systems demand rapid-response logistics networks for deployment support.
- Modular Rinks:Interlocking UHMWPE panels enable rapid assembly and dimensional reconfiguration between programming blocks. Municipal recreation departments across Germany and the United States favor these systems for year-round public programming flexibility. Panel refurbishment contracts and glide-agent reapplication schedules generate recurring revenue streams that now rival initial installation margins.
- Portable Rinks:Lightweight panel systems designed for temporary deployment at seasonal events and touring exhibitions. Nordic commercial entertainment complexes deploy these for pop-up installations at shopping centers and festival grounds, with demand concentrated in Sweden and Finland where winter tourism extends into shoulder seasons. Logistics coordination and rapid assembly technician availability constrain expansion velocity.
- Poured Rinks:Seamless polymer surfaces applied as liquid formulations that cure in place. Permanent entertainment venues in the Netherlands and Belgium select these for aesthetic continuity across large surface areas.
- Pre-Fabricated Rinks:Factory-assembled subsections requiring minimal on-site joining. Schools and residential users in suburban United States municipalities favor these for predictable installation timelines.
Modular rinks hold the largest share; momentum sits with portable systems.
Application:
Performance authenticity requirements stratify procurement budgets, with competitive applications demanding formulation precision that recreational contexts can relax.
- Recreational Use:Public skating sessions and family entertainment center deployments prioritize operational cost reduction over elite glide coefficients. Municipal buyers in the United States and Germany dominate procurement volume, driven by elimination of refrigeration infrastructure and extended operational seasons.
- Professional Training:Elite athlete facilities require glide performance within tight tolerances of natural ice friction benchmarks. Current UHMWPE formulations plateau within 10 percent of natural ice standards, limiting penetration into this segment where performance authenticity remains non-negotiable.
- Competitive Sports:Tournament-grade installations subject to heavy traffic loads and precise dimensional standards. REACH-compliant additive packages from European compounders are migrating into these specifications.
- Events:Temporary installations for corporate functions, holiday exhibitions, and promotional activations. Rental revenue models dominate, with logistics efficiency determining supplier selection.
Recreational use commands the greatest volume; professional training exhibits the steepest expansion trajectory as formulation advances compress performance gaps.
End User:
Capital availability and technical sophistication diverge sharply across user categories, with institutional buyers demanding comprehensive maintenance contracts that residential users forgo.
- Sports Clubs:Multi-sport facilities seeking year-round ice access without seasonal shutdown costs. German and United States suburban municipalities fund these installations through consolidated recreation department budgets.
- Entertainment Venues:Commercial complexes integrating synthetic rinks with augmented reality projection systems and automated rental kiosks. Nordic operators in Sweden, Norway, and Finland lead experience-layering innovation.
- Schools:Educational institutions prioritizing capital efficiency and student safety. Pre-fabricated systems with rapid installation timelines dominate procurement.
- Residential Users:Backyard installations for private family access. PolyGlide Ice and similar specialists serve this fragmented segment with modular systems featuring lower capital barriers.
Entertainment venues generate the highest per-site revenue; residential users are gaining share fastest as modular system costs decline.
Material:
Formulation chemistry determines glide coefficient, panel lifespan, and regulatory compliance burden across jurisdictions.
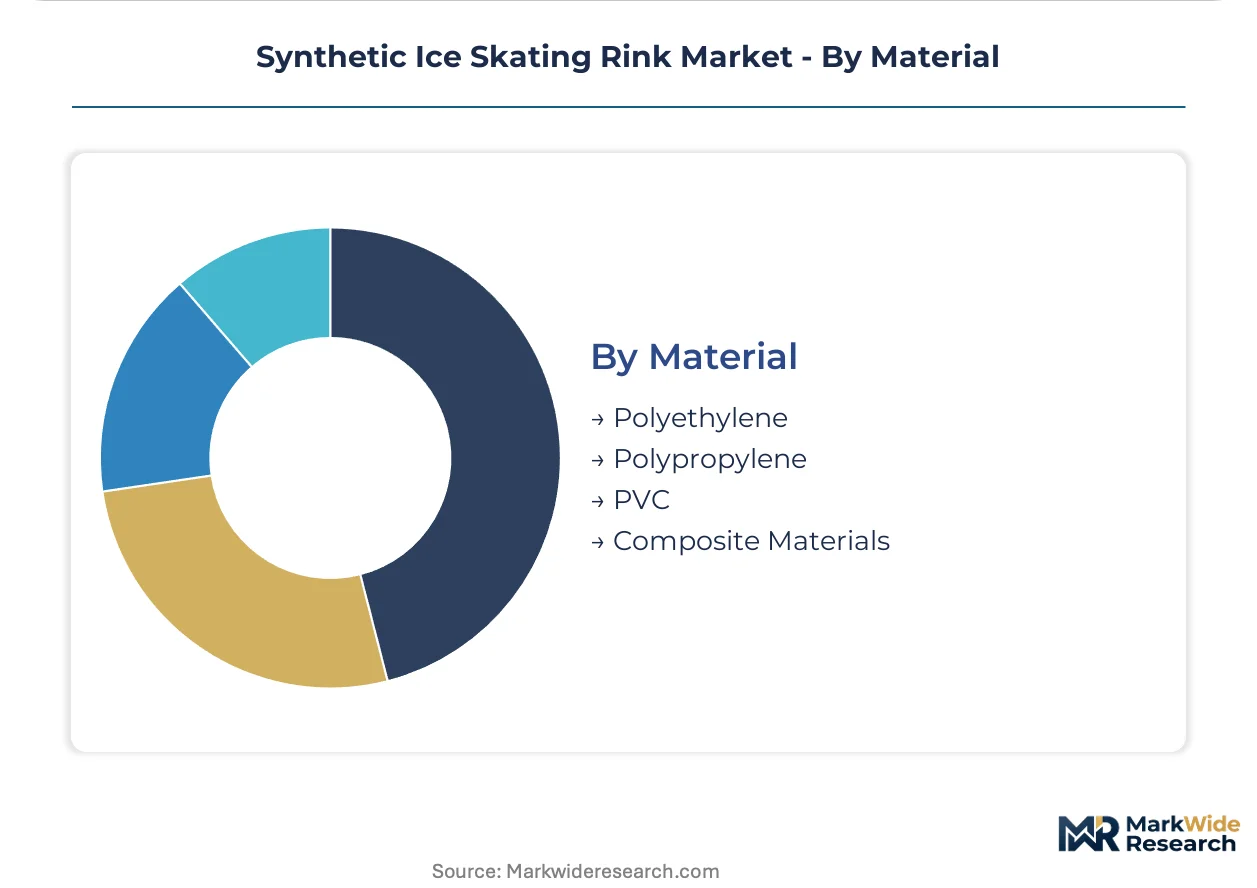
- Polyethylene:Ultra-high molecular weight formulations from European compounders in Germany and the Netherlands now deliver glide coefficients approaching natural ice benchmarks. REACH restrictions enforced by ECHA are accelerating reformulation investments to eliminate legacy plasticizers.
- Polypropylene:Lower-density alternatives for cost-sensitive applications where maximum glide performance is secondary to capital efficiency. Limited penetration in high-traffic commercial installations.
- PVC:Legacy formulations facing regulatory pressure from ECHA restrictions on phthalate-based plasticizers. European entertainment venues are phasing out these chemistries.
- Composite Materials:Ceramic and fluoropolymer additive integration represents the fastest-evolving segment. Municipal buyers in Germany and the United States are piloting these advanced formulations for high-traffic public installations.
Polyethylene maintains dominant share; composite materials are climbing the fastest as manufacturing scale reduces unit panel costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across procurement contexts: municipal buyers in Germany and the United States exhibit high price sensitivity driven by budget accountability, while Nordic commercial entertainment complexes absorb premium pricing for experience-layered installations.
United States
Suburban municipalities dominate procurement volume through consolidated county-level recreation department budgets. EPA procurement guidelines increasingly influence municipal specifications for recreational surface materials. Installation clusters concentrate in Midwest states where seasonal ice access gaps drive year-round programming demand.
Germany
Municipal recreation departments prioritize REACH-compliant formulations from domestic compounders to preempt regulatory retrofit costs. ECHA enforcement timelines are accelerating panel replacement cycles in Bavarian public venues. Manufacturing gravity centers on North Rhine-Westphalia polymer additive specialists supplying ceramic-enhanced glide formulations.
Sweden
Commercial entertainment complexes lead experience-layering innovation, integrating synthetic rinks with augmented reality projection systems. Swedish Chemicals Agency alignment with REACH restricts legacy plasticizer imports from non-EU suppliers. Stockholm and Gothenburg anchor Nordic pop-up installation logistics networks serving winter tourism extensions.
Netherlands
Permanent entertainment venues in Amsterdam and Rotterdam specify poured polymer systems for seamless surface aesthetics. CE marking requirements under the Construction Products Regulation govern polymer-based recreational surface approvals. Rotterdam port infrastructure facilitates UHMWPE resin import efficiency for domestic compounding operations.
Canada
Hockey training facilities drive demand for glide performance approaching natural ice benchmarks. Health Canada guidelines for recreational surface materials influence provincial procurement standards. Ontario and Quebec municipalities pilot modular systems for extended shoulder-season public programming.
Synthetic Ice Skating Rink Market Competitive Landscape
Capability concentration sits with European compounders mastering ceramic and fluoropolymer additive integration; scale advantage sits with North American distributors leveraging extensive municipal procurement networks. The vendor base organizes around three archetypes: formulation specialists commanding premium pricing through material science differentiation, modular system fabricators competing on installation velocity, and residential-scale specialists capturing consumer segments with reduced capital barriers. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into adjacent recreational surface categories.
Within the formulation-specialist tier, Glice and Xtraice exemplify divergent geographic positioning strategies. Glice anchors premium commercial installations through its European manufacturing footprint, while Xtraice occupies a position emphasizing Nordic and North American market penetration through distributor network density. PolyGlide Ice sits within the residential-scale specialist archetype, representing the fragmented consumer segment where modular system cost reduction is reshaping competitive entry thresholds.
| Leading Market Players |
|---|
| Glice |
| Xtraice |
| PolyGlide Ice |
| KwikRink Synthetic Ice |
| Global Synthetic Ice |
| HockeyShot |
| SmartRink |
| Synthetic Ice Solutions |
| D1 Backyard Rinks |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Dutch compounders for ceramic-enhanced glide formulations compresses both margin structures and procurement timelines, forcing tiered pricing separation between REACH-certified premium panels and standard polyethylene alternatives while concentrating supply chain risk in North Rhine-Westphalia additive production clusters.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture, with panel refurbishment and glide-agent reapplication schedules generating recurring revenue that rivals initial installation margins. Three-tier pricing structure separates premium composite formulations with fluoropolymer microspheres from standard UHMWPE and economy-grade polypropylene alternatives. Cost compression in the residential segment intensifies as PolyGlide Ice and backyard specialists drive modular system prices downward. Municipal recreation departments in Germany and the United States exhibit the highest price sensitivity due to consolidated county-level budget accountability, while Nordic commercial entertainment complexes absorb premium pricing for experience-layered installations.
Supply Chain Analysis
Ethylene monomer feedstock volatility anchors pricing instability, with UHMWPE resin costs fluctuating alongside petrochemical benchmark movements. Manufacturing gravity centers on Germany, the Netherlands, and Belgium for specialty additive compounding, while panel fabrication distributes across North American fabricators serving municipal procurement channels. REACH compliance from ECHA restricts legacy plasticizer imports, creating regulatory chokepoints for non-European suppliers. Distribution runs through manufacturer-direct engagement for technical validation, compressing traditional distributor-led specification processes in United States suburban municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with residential-scale modular systems, as backyard demand from North American suburban households creates niches beneath incumbent commercial focus.
For Market Incumbents: Pre-empt residential specialist encroachment by acquiring backyard rink distribution capabilities or launching sub-branded consumer lines with reduced capital barriers. Defend municipal contract positions through REACH-compliant formulation certification and embedded maintenance contract structures. Ceramic additive R&D investment remains the priority lever against performance-gap closure threats from emerging composite specialists. For New Entrants and Emerging Players: Pursue portable rink logistics networks in Sweden and Finland, where winter tourism extensions create pop-up installation demand underserved by incumbent permanent-installation focus. Target event rental revenue models with rapid-response assembly technician pools. Direct-to-entertainment-venue sales bypasses consolidated municipal procurement gatekeepers. For Investors and Strategic Acquirers: ECHA mandate expansion reshapes the acquisition landscape toward REACH-certified compounders with bio-based lubricant additive pipelines. Long-term viability favors formulation specialists over pure-play fabricators as material science differentiation intensifies. Watch for recycled content mandate adoption across multiple United States states as inflection signal for circular-material-certified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | Bio-based lubricant additive development locks in European entertainment venue contracts ahead of mandate expansion. |
| Residential Distribution Channel Buildout | Backyard rink specialist acquisition captures suburban household demand with lower capital entry thresholds. |
| Ceramic Additive Manufacturing Scale-Up | Fluoropolymer microsphere integration reduces unit panel costs for mid-tier municipal deployments. |
| Aftermarket Service Capability Expansion | Panel refurbishment and glide-agent reapplication contracts generate recurring revenue rivaling installation margins. |
| Recycled Content Certification Program | Post-consumer polymer mandates in United States municipal procurement create first-mover specification advantage. |
Research Methodology
Desk research of polymer additive patent filings, ECHA regulatory submissions, and municipal procurement databases preceded structured interviews with UHMWPE compounder technical directors, municipal recreation department procurement officers, commercial entertainment venue operations managers, and synthetic rink installation technician training program administrators. Secondary validation drew from customs trade data for UHMWPE resin imports, ASTM International standard development records, and SEC filings from recreational surface material suppliers. Bottom-up panel shipment estimates triangulated against top-down municipal budget allocation analysis.
Forecast assumptions held fixed the current REACH enforcement timeline and ethylene monomer supply conditions while varying municipal procurement digitization velocity and residential consumer adoption curves across the analysis window. Segmentation modeling incorporated product type, application context, end-user category, and material formulation chemistry dimensions. CAGRs derived from panel unit economics and service contract renewal rate trajectories, with glide coefficient improvement curves and recycled content mandate adoption schedules as industry-specific sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing or municipal recreation budget allocations would shift the trajectory. Forecasts reflect documented assumptions about ceramic additive manufacturing scale and ECHA enforcement consistency. Cross-checking against European compounder order book disclosures and United States county-level procurement platform data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Soccer Gear Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Cleat Market
Sports Equipment
Golf Bags Market
Sports Equipment
Kneeboard Market
Sports Equipment
Hydration Belt Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Surfboard Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Equestrian Equipment Market