
 Grapeseed Oil Market | 2026-2036
Grapeseed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Grapeseed Oil Market Intelligence
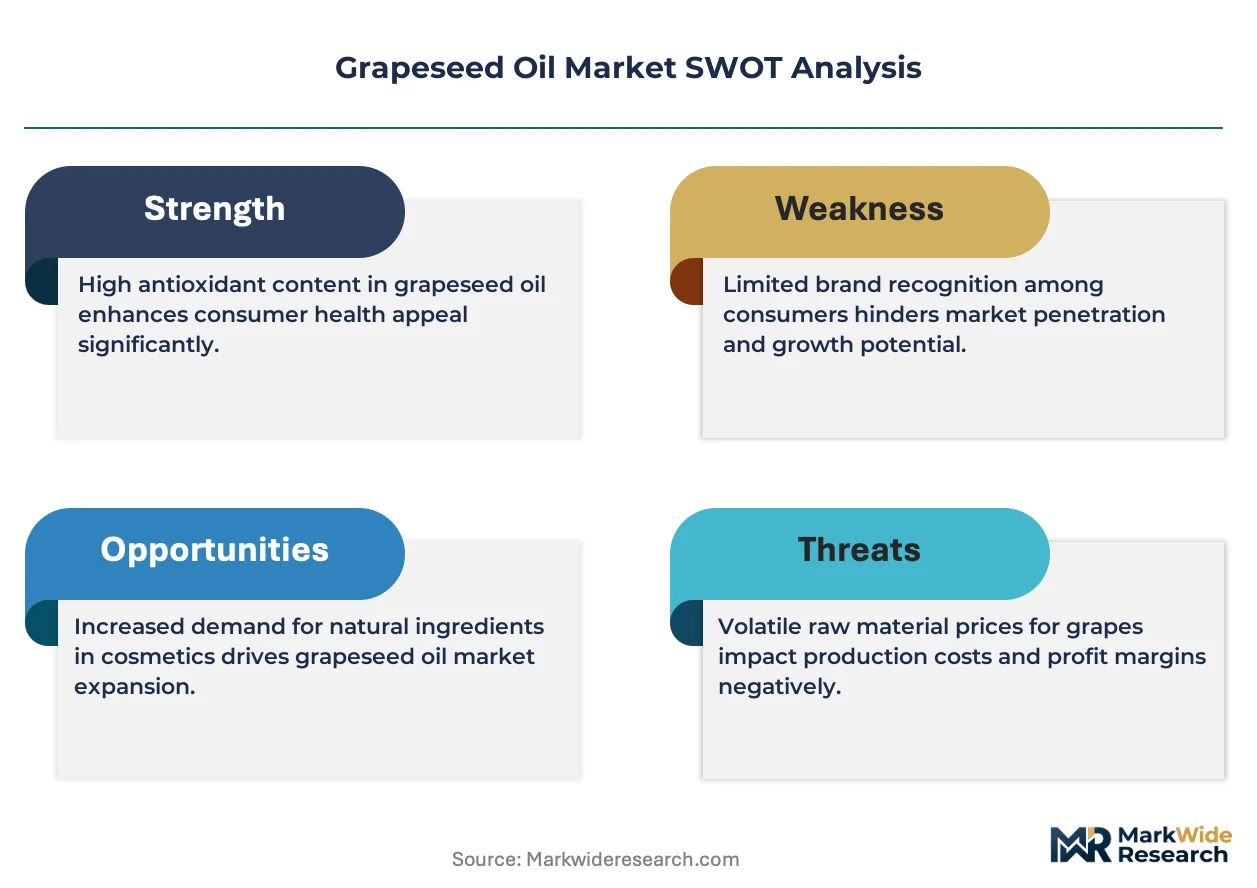
The premium cold-pressed segment is consolidating against commodity refined grades as extraction method becomes the primary price differentiator. Tampieri leverages vertical integration from wine cooperatives to secure Italian feedstock volumes. Gustav Heess Oleochemische Erzeugnisse GmbH anchors Central European pharmaceutical-grade supply through solvent-free processing infrastructure. BORGES AGRICULTURAL & INDUSTRIAL EDIBLE OILS, S.A.U. dominates Iberian bulk exports with controlled temperature logistics across Mediterranean ports.
Grapeseed oil is a fixed oil extracted from Vitis vinifera seeds, typically containing 60-76% linoleic acid, 12-20% oleic acid, and 6-10% palmitic acid, with a smoke point of 216°C for refined grades that enables high-heat culinary applications. Cold-pressed variants retain higher polyphenol content at 50-100 ppm, positioning them for cosmeceutical formulations where oxidative stability commands premium positioning. The cosmetics application segment leads value generation due to tocopherol concentration and lightweight skin absorption properties, while pharmaceutical firms drive specification tightening around residual hexane thresholds below 25 ppm.
EFSA standards for novel food ingredients and REACH registration requirements for extraction solvents shape European product compliance costs and market entry barriers. The FDA's GRAS affirmation for grapeseed oil in food applications under 21 CFR 182.50 provides US market access, though California Proposition 65 warnings for trace contaminants create state-level labeling complexity. Stakeholders must monitor tightening EU MDR requirements for cosmetic ingredient traceability alongside emerging state-level bioactive content disclosure mandates in North American jurisdictions.
Market Dynamics
Wine industry co-location patterns in Mediterranean Europe are concentrating feedstock access among vertically integrated processors, while cold-pressed extraction infrastructure investments are widening the performance gap between premium and commodity grades.
Growth Catalysts
- EU F-Gas Regulation:Compliance mandates for extraction solvent recovery are accelerating capital deployment into mechanical pressing systems that bypass fluorinated gas dependencies entirely.
- Cosmeceutical formulation demand:Lightweight absorption properties and tocopherol concentration are pulling pharmaceutical-grade specifications into mainstream skincare manufacturing pipelines.
- France-Italy-Spain feedstock clustering:Proximity to wine cooperatives secures seed supply chains with transport cost advantages that compound extraction margin structures.
Market Restraints
- Hexane residual thresholds:REACH registration requirements for extraction solvents below 25 ppm are elevating refining capital intensity and compliance documentation burdens.
- Seed supply seasonality:Annual wine harvest cycles concentrate raw material availability into narrow procurement windows that compress working capital efficiency.
- Sunflower oil substitution:Comparable linoleic acid profiles at lower price points are capturing cost-sensitive foodservice volume in Central European markets.
Strategic Opportunities
- California Proposition 65 compliance services:Trace contaminant disclosure mandates are creating advisory revenue streams for testing laboratories and certification consultancies.
- Pharmaceutical-grade solvent-free processing:Supercritical CO2 extraction convergence with tocopherol stabilization protocols opens contract manufacturing contracts for API adjuvant applications.
- Gourmet restaurant direct procurement:Finishing oil specifications are bypassing traditional distribution tiers through chef-owned cooperative purchasing platforms.
Industry Challenges
- Polyphenol retention technician scarcity:Cold-press operation expertise sits concentrated among Mediterranean equipment specialists with limited training program scale.
- EU MDR cosmetic ingredient traceability:Batch-level documentation systems require ERP reconfiguration timelines that extend 18-24 months for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grapeseed Oil Market |
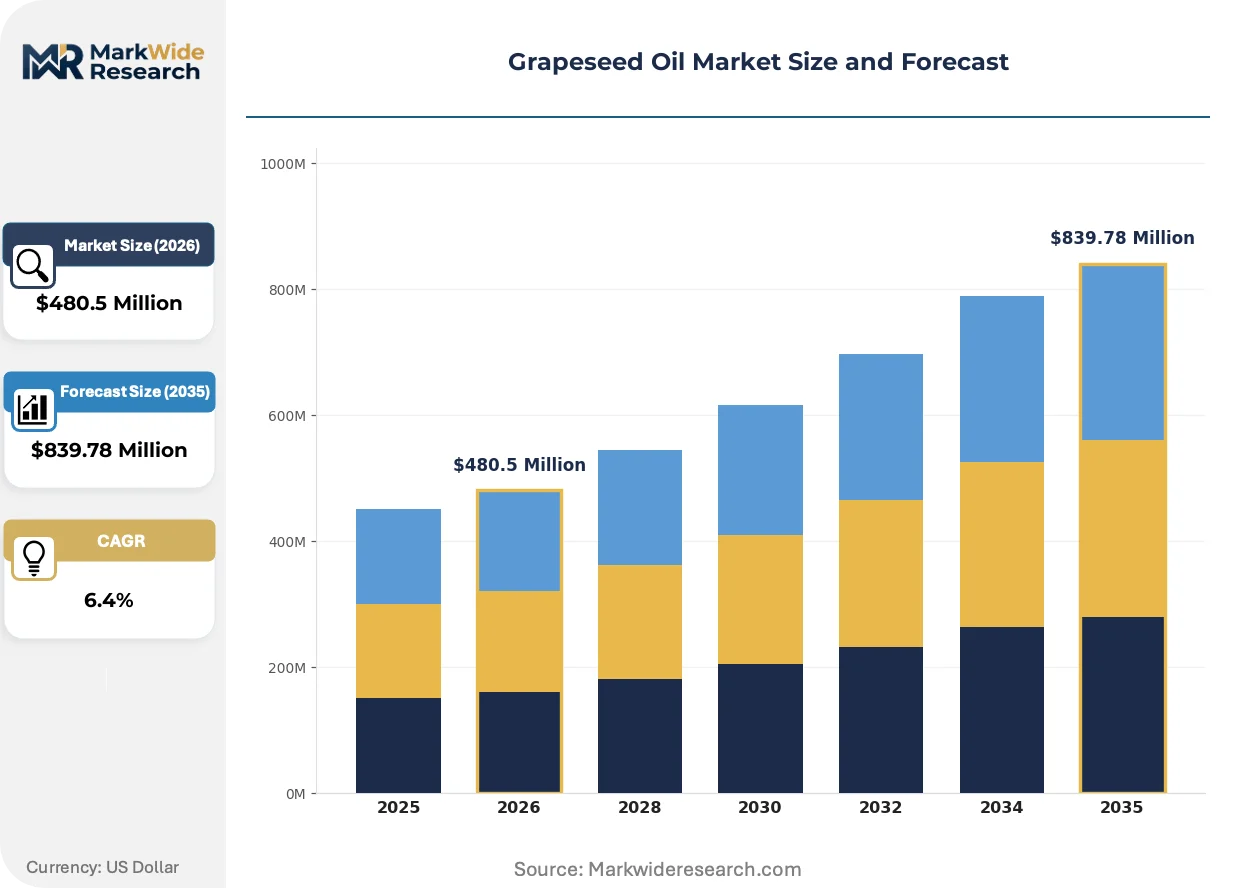
| Market Size in 2026 | $480.5 Million |
| Market Size in 2035 | $839.78 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Cold-Pressed, Organic, Unrefined, Virgin Application: Cooking, Cosmetics, Pharmaceuticals, Baking, Salad Dressings Packaging Type: Glass Bottles, PET Bottles, Tin Cans, Plastic Pouches, Bulk Containers End User: Food Processing Units, Personal Care Manufacturers, Pharmaceutical Firms, Gourmet Restaurants |
| Companies Covered | Tampieri, Salute Santé, Mediacovrac, OLITALIA S.R.L., Oleificio Salvadori, Alvinesa Natural Ingredients, Gustav Heess Oleochemische Erzeugnisse GmbH, Henan Province Kunhua Biological Technology Co., Ltd., BORGES AGRICULTURAL & INDUSTRIAL EDIBLE OILS, S.A.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grapeseed Oil Market Strategic Shifts & Innovations
Extraction methodology is becoming the primary axis of competitive differentiation as buyers segregate procurement portfolios between performance-grade cold-pressed volumes and cost-optimized refined alternatives.
Supercritical CO2 extraction infrastructure is consolidating around pharmaceutical-grade contract manufacturers seeking solvent-free tocopherol concentration for cosmeceutical formulations. European skincare laboratories are adopting these systems at accelerated capex cycles to secure EFSA-compliant novel food ingredient pathways. The technology is consolidating premium positioning away from traditional hexane-based refiners unable to fund comparable equipment transitions.
REACH registration requirements for food-contact extraction solvents are tightening residual threshold enforcement across EU member state competent authorities. Refiners face reformulation timelines compressed by ECHA evaluation schedules that prioritize hexane alternatives in safety dossier reviews. Central European processors are responding with accelerated mechanical pressing retrofits to preempt authorization sunset clauses.
Chef-driven procurement collectives are disintermediating traditional edible oil distributors in North American metropolitan markets. Gourmet restaurants in New York and San Francisco are forming direct purchasing agreements with Italian and Spanish cooperatives, compressing margin capture for conventional import brokers. This channel shift concentrates volume among processors with controlled temperature logistics capabilities across Mediterranean port infrastructure.
Grapeseed Oil Market Segmentation
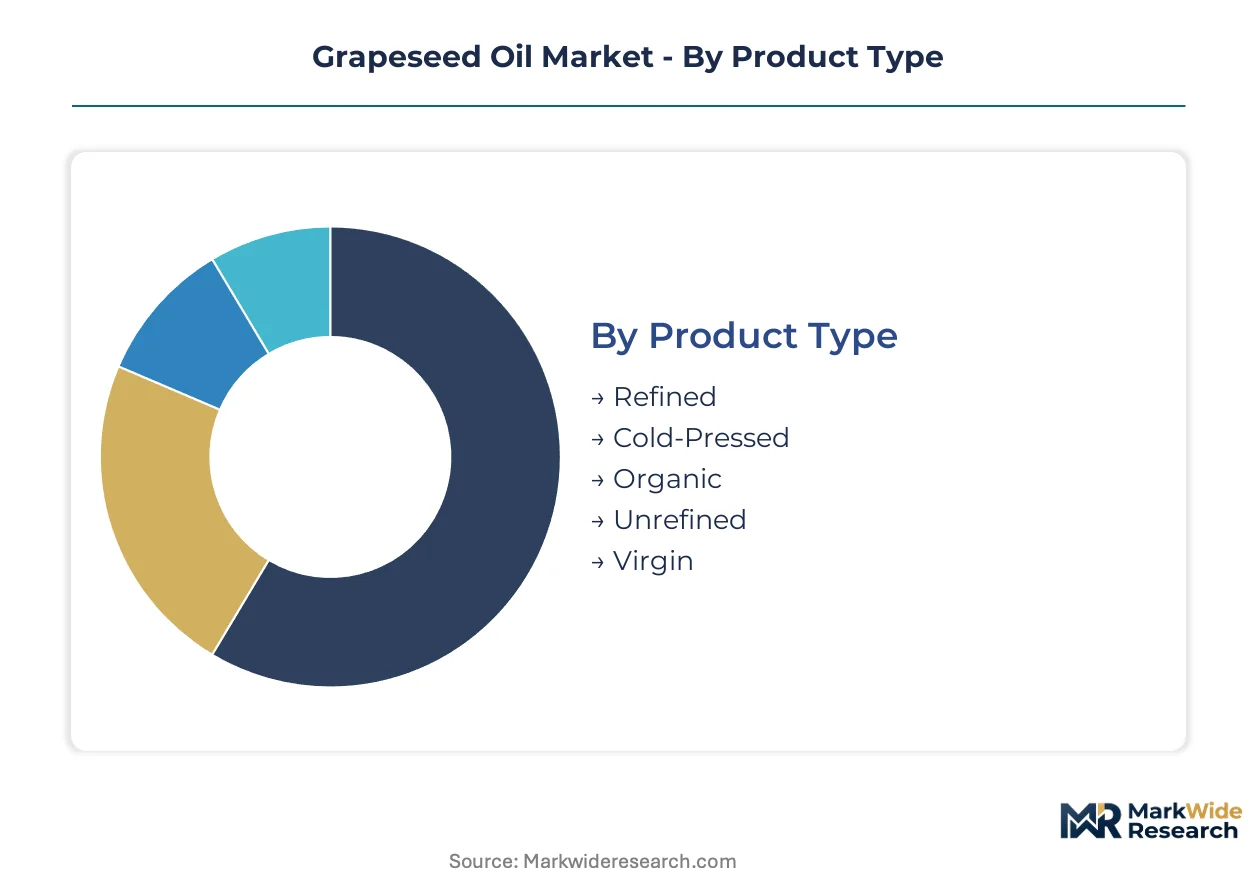
Extraction methodology and end-use specifications fragment procurement patterns across the Grapeseed Oil Market. Buyers discriminate primarily by thermal tolerance thresholds for culinary applications versus polyphenol retention requirements in cosmeceutical formulations.
Product Type:
Cold-pressed variants command price premiums through mechanical extraction that preserves heat-sensitive bioactives, while refined grades compete on smoke point performance and cost efficiency.
- Cold-Pressed:Mechanical pressing at temperatures below 40°C retains 50-100 ppm polyphenol content. Demand concentrates in French and Italian gourmet restaurants sourcing finishing oils through chef cooperatives, constrained by limited Mediterranean equipment specialist capacity for technician training.
- Refined:Solvent extraction followed by degumming and deodorization yields 216°C smoke points suitable for high-heat frying. Food processing units in Spain and California bulk procurement favor this grade for cost-sensitive volume applications, though REACH hexane residual thresholds below 25 ppm elevate refining capital intensity.
- Organic:Certified feedstock from pesticide-free vineyards commands certification premiums in German and Austrian natural cosmetics manufacturing.
- Unrefined:Partial filtration retains seed particulates and stronger flavor profiles for artisanal bakery applications in Italian regional markets.
- Virgin:Single-press extraction without subsequent processing meets EFSA novel food ingredient standards for direct consumption labeling.
Volume sits with Refined; growth tilts toward Cold-Pressed.
Application:
End-use performance requirements split demand between thermal stability for food processing and dermal absorption rates for topical formulations.
- Cosmetics:Lightweight skin absorption and tocopherol concentration position grapeseed oil as a carrier base in cosmeceutical serums. European skincare laboratories in France and Switzerland drive supercritical CO2 extraction adoption to secure EFSA-compliant solvent-free supply chains for premium facial oil formulations.
- Cooking:Neutral flavor profile and high smoke point utility anchor foodservice procurement in North American metropolitan markets. California and New York restaurant groups source directly from Mediterranean cooperatives, bypassing traditional import distributors through temperature-controlled logistics agreements.
- Pharmaceuticals:API adjuvant applications require batch-level documentation systems under EU MDR cosmetic ingredient traceability mandates, extending ERP reconfiguration timelines 18-24 months for contract manufacturers.
- Baking:Emulsification properties in laminated dough production attract French and Belgian industrial bakery procurement.
- Salad Dressings:Gourmet retail bottling in Italian and Spanish markets emphasizes origin labeling from specific wine cooperative partnerships.
Cosmetics captures value concentration; Cooking maintains volume dominance.
Packaging Type:
Light and oxygen exposure sensitivity dictates material selection across distribution channel requirements.
- Glass Bottles:UV protection and premium positioning anchor gourmet retail and cosmeceutical dispensing. Italian and Spanish exporters prioritize amber glass for trans-Mediterranean shipping to California and New York direct procurement platforms.
- Bulk Containers:Stainless steel totes and flexitanks enable food processing unit procurement at scale, with controlled atmosphere specifications for linoleic acid oxidation prevention during Atlantic transit.
- PET Bottles:Lightweight logistics cost reduction targets mass-market retail distribution in Central European supermarkets.
- Tin Cans:Traditional culinary packaging persists in French and Spanish regional brand loyalty segments.
- Plastic Pouches:Flexible format adoption accelerates in foodservice portion-control applications.
Bulk Containers handle procurement volume; Glass Bottles expand fastest through premium channel migration.
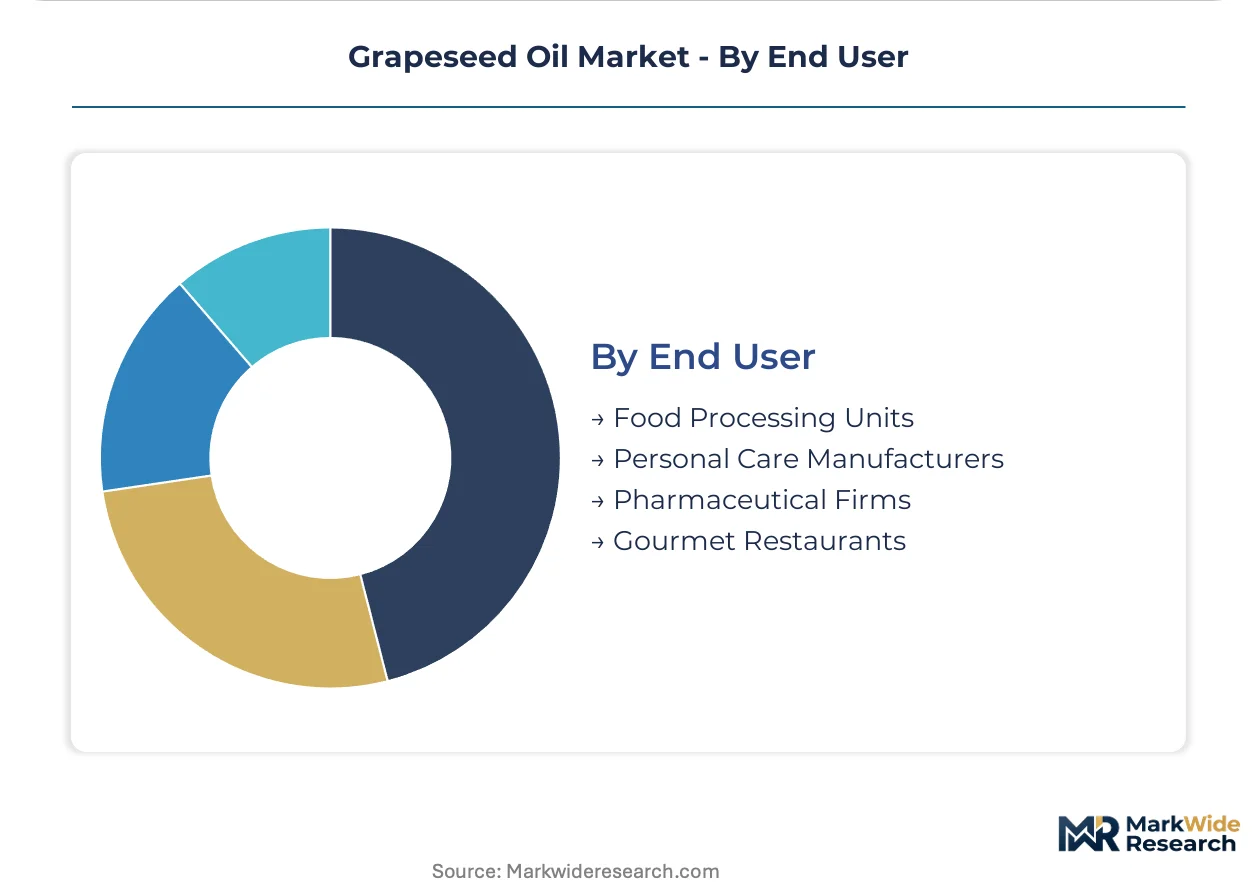
End User:
Specification stringency and documentation requirements stratify buyer power across value chain positions.
- Personal Care Manufacturers:Pharmaceutical-grade solvent-free processing specifications pull supercritical CO2 extraction investment. Swiss and French formulators batch-test tocopherol stability protocols for cosmeceutical serum applications, consolidating contract manufacturing relationships with equipment-upgraded processors.
- Food Processing Units:High-volume refined grade procurement concentrates in Spanish and California olive oil blending facilities, where grapeseed oil extends product lines with polyunsaturated fat positioning.
- Gourmet Restaurants:Chef-driven cooperative purchasing in San Francisco and New York demands cold-pressed finishing oils with harvest-date traceability, disintermediating conventional edible oil distributors.
- Pharmaceutical Firms:Residual hexane thresholds and REACH registration documentation elevate supplier qualification barriers for API adjuvant applications.
Food Processing Units absorb volume share; Personal Care Manufacturers drive margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bordeaux anchors European grapeseed oil production through its dense clustering of wine cooperatives and cold-pressing facilities that supply gourmet restaurants across France and export markets.
France
Gourmet restaurant procurement in Paris and Lyon drives cold-pressed grade premiums. EFSA novel food ingredient standards shape extraction compliance costs for processors seeking direct consumption labeling. Bordeaux wine cooperatives supply feedstock to mechanical pressing facilities along the Garonne corridor.
Italy
Chef-driven cooperative purchasing in Milan and Rome concentrates demand for virgin-grade finishing oils with harvest-date traceability. REACH registration requirements for extraction solvents elevate refining documentation burdens for hexane-based processors. Piedmont and Tuscany wine regions anchor vertically integrated supply chains from vineyard to bottling.
Spain
Bulk refined grade procurement for food processing units dominates volume through Catalan and Andalusian olive oil blending facilities. EU F-Gas Regulation compliance accelerates mechanical pressing retrofits to bypass fluorinated gas dependencies. Valencia and Barcelona ports enable controlled temperature logistics for trans-Mediterranean exports.
United States
California Proposition 65 warning requirements for trace contaminants create state-level labeling complexity that elevates testing service demand. FDA GRAS affirmation under 21 CFR 182.50 provides federal market access for food applications. San Francisco and New York restaurant groups form direct procurement agreements with Mediterranean cooperatives, disintermediating traditional import distributors.
Germany
Pharmaceutical-grade solvent-free specifications pull supercritical CO2 extraction investment from Swiss and French formulators into Central European contract manufacturing. ECHA evaluation schedules prioritize hexane alternatives in safety dossier reviews, compressing refiner reformulation timelines. Baden-Württemberg processors anchor pharmaceutical-grade supply through solvent-free processing infrastructure.
Grapeseed Oil Market Key Industry Players
Premium-margin players sit above commodity-margin players across extraction methodology and certification grade. The market structure fragments between vertically integrated Mediterranean wine cooperative processors and specialized Central European pharmaceutical-grade refiners. Three archetypes dominate: mechanical cold-press specialists serving gourmet foodservice, solvent-free supercritical CO2 operators targeting cosmeceutical formulators, and bulk refined grade exporters leveraging port logistics scale. Competitive moves concentrate on backward integration into wine cooperative feedstock agreements and supercritical extraction capacity expansion.
Within the premium cold-press tier, Tampieri represents Italian vertical integration from wine cooperatives, while Gustav Heess Oleochemische Erzeugnisse GmbH exemplifies Central European pharmaceutical-grade positioning through its German GmbH structure. BORGES AGRICULTURAL & INDUSTRIAL EDIBLE OILS, S.A.U. anchors Iberian bulk export scale through its Spanish S.A.U. corporate form and controlled temperature logistics capabilities across Mediterranean ports.
| Leading Market Players |
|---|
| Tampieri |
| Salute Santé |
| Mediacovrac |
| OLITALIA S.R.L. |
| Oleificio Salvadori |
| Alvinesa Natural Ingredients |
| Gustav Heess Oleochemische Erzeugnisse GmbH |
| Henan Province Kunhua Biological Technology Co., Ltd. |
| BORGES AGRICULTURAL & INDUSTRIAL EDIBLE OILS, S.A.U. |
| Others |
Cost & Logistics Intelligence
Backward integration into wine cooperative feedstock agreements anchors supply security and pricing power for Mediterranean processors, compressing margin capture for distributors lacking upstream control. This structural choice locks in raw material access during narrow harvest windows while enabling cold-pressed grade premiums that commodity refiners cannot replicate.
Pricing Analysis
Yield-based pricing anchors extraction method premiums, with cold-pressed variants commanding three-to-five-fold multiples over refined grades due to polyphenol retention and gourmet restaurant procurement. Certification grade and volume scale drive differentiation, as EFSA novel food ingredient compliance and organic vineyard sourcing stratify price bands. Cost compression in refined grades intensifies from sunflower oil substitution in Central European foodservice. Food processing units exhibit highest price sensitivity, while Swiss and French cosmeceutical formulators absorb premiums for solvent-free supercritical CO2 supply.
Supply Chain Analysis
Seed recovery from wine crush operations creates circular feedstock flows that concentrate procurement leverage among Bordeaux, Piedmont, and La Rioja cooperative processors. France, Italy, and Spain anchor supply, with annual harvest seasonality compressing working capital efficiency into narrow procurement windows. Hexane residual thresholds under REACH registration elevate refining capital intensity and documentation burdens. Tariff exposure on trans-Mediterranean bulk shipments threatens margin structures for Iberian exporters. Distribution runs through controlled temperature logistics across Barcelona and Valencia port infrastructure, with direct chef cooperative purchasing disintermediating traditional import brokers in San Francisco and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive feedstock agreements with wine cooperatives to secure harvest-window procurement leverage and cold-pressed capacity expansion.
For Market Incumbents: Deploy mechanical pressing retrofit investments to preempt REACH authorization sunset clauses for hexane-based extraction. Consolidate technician training programs with Mediterranean equipment specialists to address polyphenol retention expertise scarcity. Sunflower oil substitution in Central European foodservice threatens refined grade volume; defend position through gourmet restaurant direct procurement platforms in North American metropolitan markets. For New Entrants and Emerging Players: EU F-Gas Regulation compliance mandates in Europe open a window for mechanical pressing infrastructure deployment that bypasses fluorinated gas dependencies entirely. Target pharmaceutical-grade solvent-free processing contracts with Swiss and French cosmeceutical formulators seeking supercritical CO2 extraction capacity. California Proposition 65 trace contaminant disclosure services offer advisory revenue entry with testing laboratory partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade contract manufacturing platforms with EFSA-compliant solvent-free processing infrastructure. Long-term viability hinges on supercritical CO2 extraction convergence with tocopherol stabilization protocols for API adjuvant applications. Monitor ECHA evaluation schedules prioritizing hexane alternatives in safety dossier reviews as inflection indicator for refiner consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wine Cooperative Feedstock | Captive seed supply from Bordeaux and Piedmont cooperatives secures harvest-window procurement leverage against seasonal compression. |
| Supercritical CO2 Extraction Capacity Expansion | Solvent-free processing infrastructure opens EFSA-compliant pharmaceutical-grade contracts with Swiss cosmeceutical formulators. |
| Direct Procurement Platform Development | Chef cooperative purchasing in San Francisco and New York disintermediates traditional import brokers and captures gourmet restaurant premiums. |
| REACH Hexane Alternative Reformulation | Mechanical pressing retrofits preempt ECHA authorization sunset clauses and secure EU market access for refined grade exporters. |
| California Proposition 65 Compliance Services | Trace contaminant testing and certification advisory creates recurring revenue streams from state-mandated disclosure requirements. |
Research Approach
Multi-period observation of extraction method adoption rates, feedstock pricing volatility, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with cold-press equipment specialists, wine cooperative procurement managers, cosmeceutical formulators, and Mediterranean port logistics operators. Secondary validation drew from EFSA novel food ingredient filings, ECHA REACH registration databases, FDA GRAS affirmation records under 21 CFR 182.50, and EU F-Gas Regulation implementation reports. Bottom-up volume triangulation across extraction methodology segments converged with top-down value estimates from gourmet restaurant procurement platforms and pharmaceutical-grade contract manufacturing pipelines.
Segment-weighting approaches applied differential growth assumptions across cold-pressed, refined, organic, and virgin grades, with extraction method and end-use application as primary stratification dimensions. CAGRs were derived from trend extrapolation of procurement volume shifts between food processing units and personal care manufacturers, calibrated against supercritical CO2 extraction capacity expansion timelines and mechanical pressing retrofit investment cycles throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 extraction scale-up would alter the outlook for solvent-free grade penetration in pharmaceutical applications. Forecasts reflect assumptions around EU MDR cosmetic ingredient traceability implementation timelines and ECHA hexane alternative prioritization in safety dossier reviews. Practitioners should monitor EFSA novel food ingredient standard revisions and California Proposition 65 substance list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vegan Baking Ingredients Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Durian Powder Market
Ingredients
Apple Extract Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Global Malt Ingredients Market
Ingredients
Fish Peptones Market
Ingredients
Global Amaranth Oil Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Modified Maize Starch Market
Ingredients
Egg Free Premix Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Sunflower Oil Market
Ingredients
India Olive Oil Market