
 Japanese Curry Market | 2026-2036
Japanese Curry Market Size, Share, and Industry Trends Forecast 2026-2036
Japanese Curry Market Insights
The Japanese curry market is decoupling into two distinct tiers: artisanal roux blocks with single-origin spice sourcing versus mass-produced liquid curry competing on shelf stability and unit economics. House Foods Corporation leverages its vertically integrated spice procurement to sustain premium positioning in specialty retail channels. S&B Foods Inc anchors the commodity segment through dominant convenience store distribution and standardized production scale.
Japanese curry denotes a roux-thickened stew of spiced vegetables and proteins, typically built from a base of turmeric, coriander, cumin, and fenugreek with a wheat-flour fat roux providing viscosity and umami depth; it serves as both a home-cooked staple and an industrial foodservice component. Ready-to-eat formats lead volume growth as time-constrained households shift from scratch cooking, while curry roux retains the largest margin pool through brand loyalty and repeat purchase cycles. Liquid curry competes aggressively in foodservice channels where speed of preparation determines operator preference.
Japan's Consumer Affairs Agency enforces strict Food Labeling Act standards on allergen disclosure and calorie claims, while METI oversees manufacturing facility certifications that constrain small-scale import access. These frameworks elevate compliance costs for foreign entrants but reinforce domestic incumbents with established quality control infrastructure. Stakeholders must monitor evolving clean-label expectations and potential revisions to additive disclosure rules that could reshape formulation strategies.
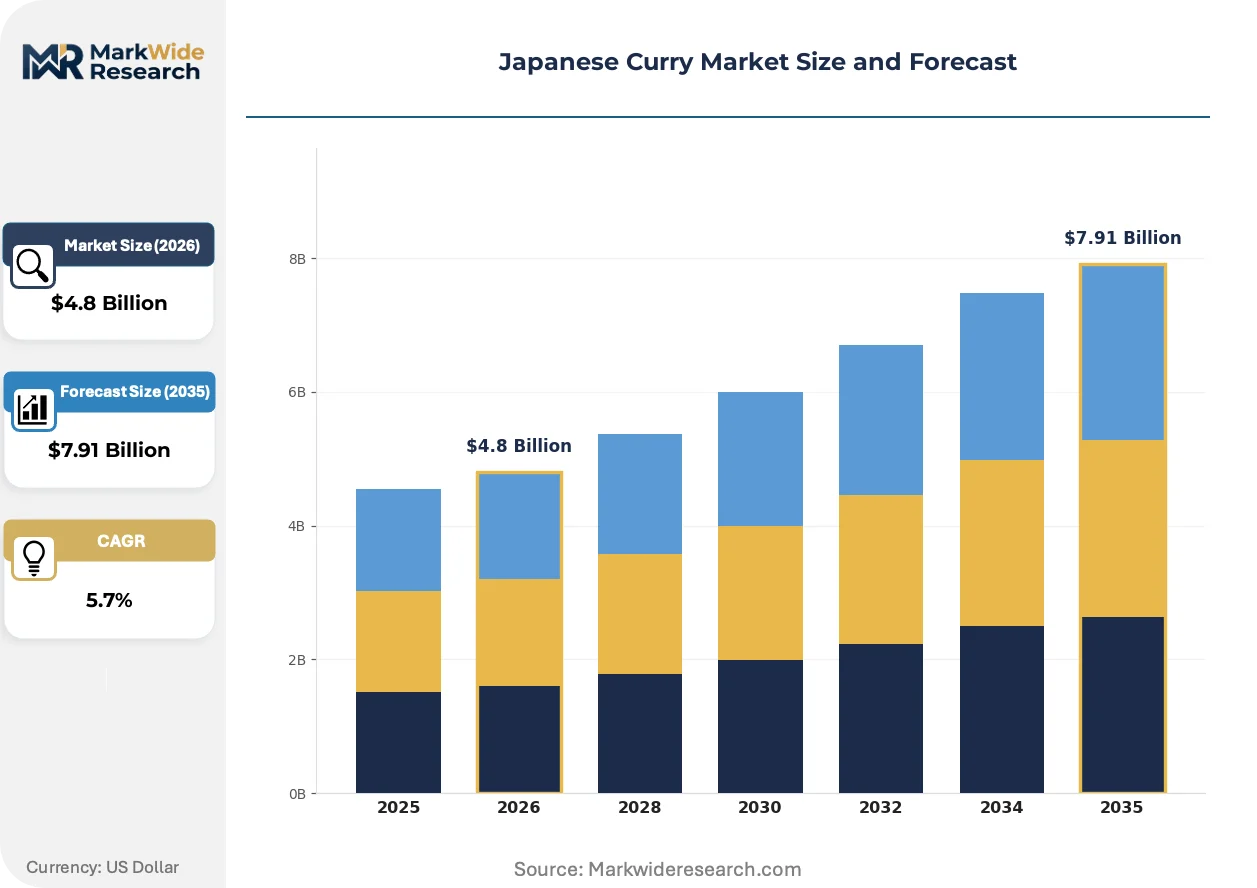
Market Dynamics
Japan's Food Labeling Act enforcement is compressing formulation cycles as manufacturers reformulate roux bases to eliminate ambiguous additive declarations while preserving shelf stability.
Growth Catalysts
- Single-person household expansion:Tokyo and Osaka metropolitan areas drive demand for single-serve ready-to-eat curry pouches that eliminate portioning waste.
- Clean-label ingredient sourcing:METI facility certification programs reward domestic spice procurement with streamlined additive disclosure pathways.
- Foodservice automation:Liquid curry formats integrate with automated rice dispensers in convenience stores and railway kiosks.
Market Restraints
- Wheat flour input volatility:Domestic wheat procurement depends on Ministry of Agriculture import quotas that fluctuate with currency exchange rates.
- Spice supply concentration:Turmeric and fenugreek sourcing clusters in specific Indian agricultural zones, exposing processors to monsoon disruption.
- Allergen labeling friction:Consumer Affairs Agency mandates for wheat and dairy disclosure limit cross-category formulation flexibility.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Rural prefectures outside Kanto and Kansai corridors show lower curry roux household penetration.
- Plant-based protein convergence:Soy and pea protein isolates combine with traditional roux bases to capture flexitarian households.
- Direct-to-pantry subscription channels:Monthly curry kit deliveries bypass conventional retail slotting fees.
Industry Challenges
- Clean-label reformulation timelines:Removing hydrolyzed protein flavor enhancers while maintaining umami depth extends R&D cycles.
- Legacy equipment retrofitting:Continuous retort systems require capital outlay to process lower-acidity clean-label formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japanese Curry Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Curry, Curry Roux, Curry Powder, Ready-to-Eat End User: Households, Restaurants, Food Services, Retailers Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Stores Flavor Profile: Spicy, Mild, Sweet, Rich |
| Companies Covered | House Foods Corporation, S&B Foods Inc, Glico Corporation, Ajinomoto Co Inc, Nissin Foods Holdings Co Ltd, Otafuku Sauce Co Ltd, Kikkoman Corporation, Kagome Co Ltd, Meiji Holdings Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japanese Curry Market Trends and Innovations
Formulation transparency and format portability are reshaping competitive advantage in Japanese curry, with manufacturers racing to reconcile clean-label demands with industrial-scale production economics.
Retort pouch technology is consolidating shelf-stable curry production around flexible packaging that reduces shipping weight and warehouse footprint. Major convenience store chains and railway foodservice operators are adopting these pouches for ambient storage compatibility. The shift is compressing demand for traditional canned curry formats.
Japan's Consumer Affairs Agency is tightening enforcement of calorie claim substantiation under Food Labeling Act amendments. Manufacturers must now verify nutritional declarations through third-party testing. Premium roux brands with established laboratory relationships are adapting faster than commodity liquid curry producers.
Time-constrained households are fragmenting purchase occasions across multiple channels rather than consolidating weekly grocery trips. Drugstore chains and online specialty retailers capture incremental curry roux volume that supermarkets previously dominated. This pattern concentrates in Tokyo's 23 wards where delivery density supports rapid fulfillment.
Japanese Curry Market Segmentation
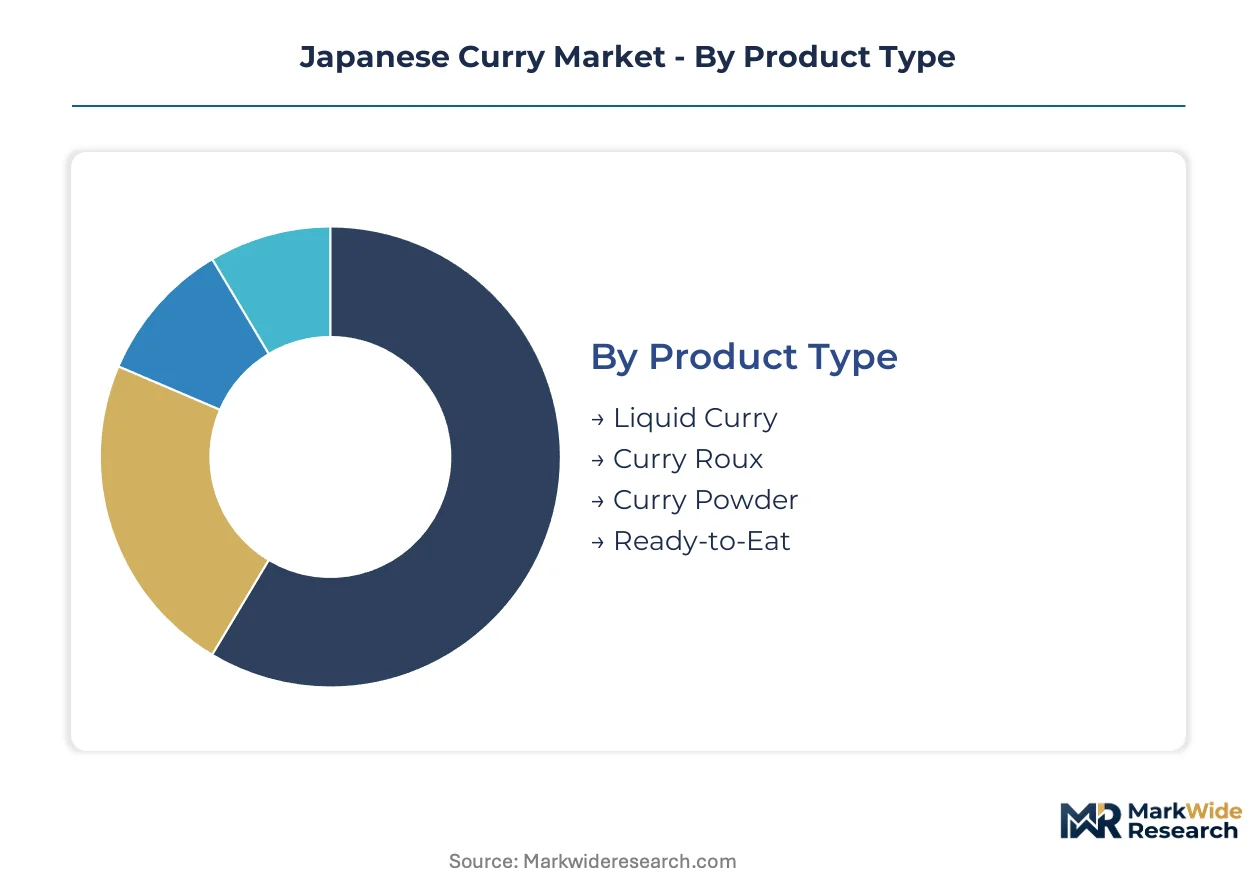
Segmentation in the Japanese curry market reveals how format choices determine channel access and margin capture. Product architecture and end-user requirements create distinct competitive arenas with diverging technical specifications and regulatory exposure.
Product Type:
Standalone formats function as complete meal solutions while embedded variants require preparation infrastructure, creating divergent customer acquisition economics and repeat purchase patterns.
- Liquid Curry:Pre-thickened sauce format optimized for foodservice speed-of-service requirements. Demand concentrates in railway kiosks and automated convenience store dispensers across Tokyo and Osaka metropolitan corridors where labor constraints favor pour-and-serve operations.
- Curry Roux:Solid fat-flour-spice blocks requiring stovetop dissolution and protein integration. Household penetration peaks in suburban prefectures where scratch cooking traditions persist and METI facility certifications support clean-label positioning.
- Curry Powder:Dehydrated spice blends for custom formulation flexibility. Specialty retailers in Kanto region capture enthusiast demand seeking turmeric-forward or fenugreek-dominant profiles.
- Ready-to-Eat:Retort-pouched complete meals with rice and sauce components. Single-person households in dense urban wards drive adoption through drugstore and online subscription channels.
Curry roux leads volumes today; ready-to-eat formats are gaining share fastest.
End User:
Cost tier stratification separates premium ingredient sourcing for direct consumption from commodity-grade procurement for institutional volume.
- Households:Primary demand driver with bifurcated purchase behavior between weekend scratch cooking and weekday convenience solutions. Tokyo's 23 wards show highest per-capita spending on premium roux blocks.
- Restaurants:Independent operators and chain concepts requiring consistent flavor replication at scale. Foodservice liquid curry procurement emphasizes portion cost control over ingredient provenance.
- Food Services:Institutional catering, corporate cafeterias, and school lunch programs with strict calorie claim substantiation requirements under Consumer Affairs Agency enforcement.
- Retailers:Private-label development and category management decisions by supermarket and convenience store chains with direct supplier qualification oversight.
Households dominate absolute spend; food services show steepest expansion trajectory.
Distribution Channel:
Geography determines fulfillment economics, with urban density enabling channel formats impractical in rural prefectures.
- Online:Direct-to-pantry subscription models and specialty retailer platforms. Monthly curry kit deliveries bypass conventional slotting fees and capture data on flavor preference evolution.
- Supermarkets:Traditional weekly shopping consolidation with dominant shelf space for established roux brands. Hokkaido and Tohoku penetration lags Kanto-Kansai corridors.
- Convenience Stores:24-hour ambient storage compatibility with retort pouch formats. Railway-adjacent locations in Osaka and Tokyo prioritize grab-and-go ready-to-eat SKUs.
- Specialty Stores:Spice merchants and regional food halls offering single-origin turmeric and artisanal roux blocks. Premium positioning depends on METI certification display.
Supermarkets retain volume leadership; online channels are expanding most quickly.
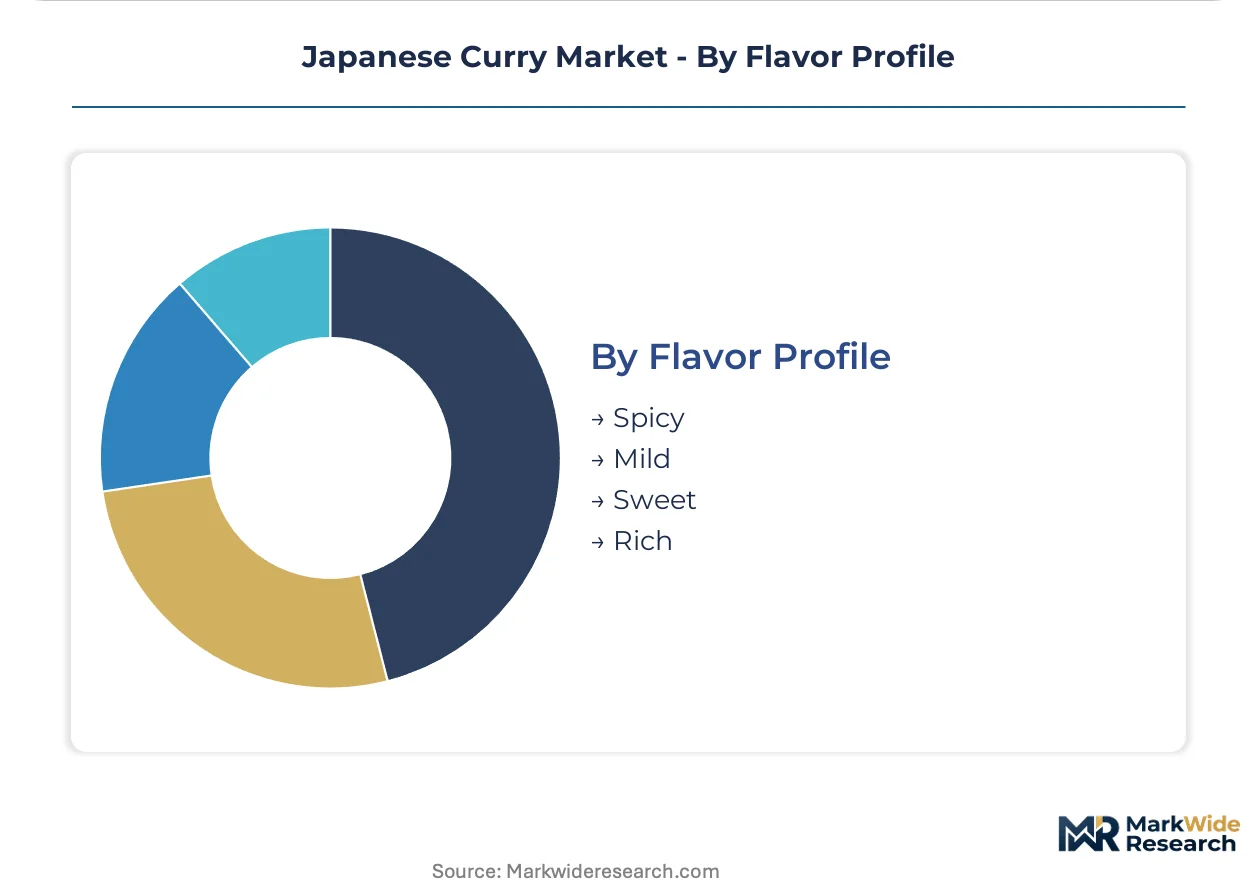
Flavor Profile:
Maturity gradients separate established mass-market preferences from emerging niche formulations targeting dietary restriction compliance.
- Spicy:Chili-forward heat levels with capsaicin concentration measured in Scoville-equivalent labeling. Younger demographics in urban centers drive demand for intensified profiles.
- Mild:Reduced chili oil content with enhanced turmeric and coriander presence. Family households with children and institutional foodservice specifications favor this segment.
- Sweet:Caramelized onion and fruit puree integration characteristic of Hokkaido regional style. Distinct from other profiles through elevated sugar content requiring specific calorie claim substantiation.
- Rich:Extended roux cooking with butter and cream additions for viscosity depth. Premium positioning in specialty retail with higher per-unit pricing and lower velocity.
Mild profiles anchor mass-market volumes; spicy variants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food processing workforce clusters concentrate in Japan's metropolitan manufacturing belts, with curry production expertise anchored in Kanto and Kansai industrial corridors. Domestic talent pools in flavor chemistry and retort engineering sustain competitive differentiation against import competition.
Kanto/Tokyo
Single-person households in Tokyo's 23 wards drive per-capita spending on premium roux blocks and ready-to-eat pouches. METI facility certifications streamline additive disclosure for manufacturers based in Saitama and Chiba prefectures. Kawasaki industrial zones host continuous retort systems processing clean-label formulations for convenience store distribution.
Kansai/Osaka
Osaka's foodservice density supports liquid curry procurement for automated rice dispenser networks. The Consumer Affairs Agency's calorie claim enforcement operates through regional offices in Kyoto. Sakai manufacturing corridors concentrate wheat-flour roux production with backward integration into domestic spice blending.
Chubu/Nagoya
Nagoya's logistics infrastructure enables just-in-time distribution to retail chains across central Japan. The region's METI-certified facilities benefit from streamlined allergen labeling pathways. Toyota-adjacent industrial zones supply packaging materials for retort pouch formats.
Hokkaido
Rural prefectures show lower curry roux household penetration, creating whitespace for subscription channel expansion. Local wheat cultivation under Ministry of Agriculture quotas supports regional sourcing claims. Sapporo metropolitan area concentrates foodservice demand for sweet-profile curry variants.
Kyushu
Fukuoka's port facilities handle spice imports from Indian agricultural zones. Regional manufacturers leverage METI certification for clean-label positioning in specialty retail. Kumamoto and Kagoshima prefectures develop plant-based protein curry variants targeting flexitarian demographics.
Japanese Curry Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's curry market structure. The vendor base consolidates around vertically integrated spice processors and commodity-scale liquid curry fabricators. Three archetypes dominate: integrated spice-to-shelf conglomerates, specialized roux block artisans, and foodservice-focused liquid format suppliers. Competitive moves center on backward integration into turmeric and fenugreek sourcing, plus retort equipment retrofitting for clean-label production.
Within the integrated tier, House Foods Corporation and S&B Foods Inc exemplify divergent scale strategies, with the former representing premium positioning through specialty retail channels and the latter anchoring mass-market convenience store distribution. Glico Corporation occupies a position bridging household and foodservice segments. These three players illustrate how Japanese curry competition stratifies between provenance-driven artisanal formats and unit-economics-driven liquid production.
| Leading Market Players |
|---|
| House Foods Corporation |
| S&B Foods Inc |
| Glico Corporation |
| Ajinomoto Co Inc |
| Nissin Foods Holdings Co Ltd |
| Otafuku Sauce Co Ltd |
| Kikkoman Corporation |
| Kagome Co Ltd |
| Meiji Holdings Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Japan's clean-label additive disclosure mandates under the Consumer Affairs Agency gate qualified supply access and premium-tier pricing power, forcing manufacturers to absorb METI certification costs or surrender shelf positioning to compliant domestic incumbents. Wheat flour import quotas and single-origin spice procurement requirements tether cost structures to Ministry of Agriculture policy cycles and Indian monsoon patterns.
Pricing Analysis
The bundled ingredient-provenance service split separates premium roux blocks with METI-certified domestic spice sourcing from unbundled commodity liquid curry competing on unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label certification depth and retail channel slotting investment. Cost compression in the economy tier is intensifying because convenience store chains are consolidating procurement around private-label liquid formats. Households in Tokyo's 23 wards show lowest price sensitivity for artisanal roux, while institutional foodservice buyers drive hard volume discounts.
Supply Chain Analysis
Regional distribution centers in Saitama and Chiba prefectures operate hub-and-spoke patterns feeding Tokyo-Osaka metropolitan corridors with retort-pouched ready-to-eat formats. Turmeric and fenugreek sourcing clusters in Maharashtra and Gujarat agricultural zones, exposing processors to monsoon disruption and currency fluctuation. Wheat flour procurement draws from Ministry of Agriculture import quotas tied to exchange rate volatility. Single-source vulnerability concentrates in Indian spice corridors. Distribution runs through convenience store ambient storage networks and drugstore subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japanese curry market functions as a stable compounder where single-person household expansion in dense urban wards generates predictable repeat purchase velocity across premium and convenience tiers.
For Market Incumbents: Anticipate clean-label reformulation deadlines by retrofitting continuous retort systems for lower-acidity formulations before Consumer Affairs Agency enforcement tightens. Deepen backward integration into Sichuan pepper and domestic wasabi cultivation to differentiate from turmeric-dependent competitors. Lock specialty retail shelf space through METI certification display investments.
For New Entrants and Emerging Players: The price-point gap between House Foods premium positioning and S&B commodity scale creates whitespace for mid-tier clean-label challengers. Target Hokkaido and Tohoku prefectures where curry roux penetration lags Kanto-Kansai corridors. Pursue direct-to-pantry subscription channels to bypass supermarket slotting fees and capture flavor preference data.
For Investors and Strategic Acquirers: Roll-up economics work for regional artisanal roux specialists because METI certification infrastructure creates barriers that favor scaled compliance platforms over fragmented local producers. Five-to-ten year viability hinges on clean-label transition completion. Acquire targets with existing laboratory relationships for calorie claim substantiation. Monitor Consumer Affairs Agency additive disclosure rule revisions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Consumer Affairs Agency enforcement rewards early METI certification adopters with streamlined disclosure pathways. |
| Backward Integration into Spice Sourcing | Captive supply of turmeric and fenugreek insulates margins from Indian monsoon volatility and currency swings. |
| Retort Equipment Retrofitting | Continuous system upgrades enable lower-acidity clean-label production without sacrificing shelf stability. |
| Direct-to-Pantry Subscription Launch | Monthly curry kit deliveries bypass convenience store slotting fees and build proprietary demand data assets. |
| Hokkaido Distribution Expansion | Rural prefecture underpenetration offers volume growth outside saturated Tokyo-Osaka corridors. |
Research Methodology
Bottom-up household and foodservice demand modeling reconciled against top-down spice import and wheat procurement tracking forms the analytical core of this study. Primary interviews with curry roux brand managers, convenience store category buyers, METI certification auditors, and restaurant procurement officers combined with secondary validation from Japan Customs trade statistics, Consumer Affairs Agency labeling enforcement records, and Ministry of Agriculture wheat quota disclosures. Triangulation across these sources calibrated volume estimates and pricing tier distributions.
Historical trendline analysis of curry roux and ready-to-eat format sales established baseline growth patterns extended across the analysis window. Segmentation modeling captured product type splits, end-user bifurcation between household and foodservice, distribution channel evolution, and flavor profile preference shifts. CAGRs derived from fitted growth curves incorporating single-person household demographic projections and clean-label adoption rates. Forecast inputs included METI facility certification pipeline data and convenience store automated dispenser deployment schedules.
Caveats apply where Consumer Affairs Agency additive disclosure revisions or Ministry of Agriculture wheat quota adjustments could materially shift the outlook. Forecasts reflect documented assumptions about clean-label transition timelines and spice supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Frangipani Extract Market