
 Gourmand Fragrance Market | 2026-2036
Gourmand Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Gourmand Fragrance Market Foresight
Scent-layering subscription services is restructuring how consumers discover and repurchase gourmand fragrances, shifting revenue from single-unit sales to recurring engagement models. Tom Ford leverages its private blend architecture to sustain ultra-premium positioning across vanilla and tobacco gourmand variants. MUGLER anchors its market presence through the Angel franchise, which dominates the patchouli-caramel segment with decades of brand equity. Sol de Janeiro competes on Brazilian-inspired gourmand body mists, extending its Cheirosa scent ecosystem from skincare into standalone fragrance.
Gourmand fragrance denotes olfactory compositions built around edible accords—vanilla, chocolate, caramel, praline, and roasted nuts—typically achieved through synthetic molecules like ethyl maltol or natural absolutes, with concentrations ranging from 15% to 30% in eau de parfum formats designed for 6- to 10-hour wear profiles. Eau de Parfum leads value generation due to higher concentration premiums and gifting suitability, while Scented Oils represent the fastest-expanding sub-category as consumers seek alcohol-free, skin-friendly alternatives. The unisex segment captures rising demand as gender-neutral marketing displaces traditional feminine-masculine segmentation, particularly among Gen-Z purchasers.
IFRA standards govern allergen thresholds and ingredient prohibitions across formulations sold in Europe and adopted voluntarily by major houses worldwide, while the EU REACH framework mandates full supply chain transparency on synthetic aroma chemicals. The FDA exercises post-market surveillance over cosmetic fragrance labeling through the Fair Packaging and Labeling Act, though pre-approval requirements remain minimal compared to pharmaceutical oversight. Stakeholders must monitor tightening state-level fragrance disclosure laws in California and New York, as these jurisdictions often pioneer mandates that cascade into national retail compliance obligations.
Market Dynamics
The gourmand fragrance sector is undergoing structural recalibration as IFRA and EU REACH mandates force reformulation of legacy accords, while synthetic biology startups disrupt traditional supply chains for edible aroma molecules.
Growth Catalysts
- EU REACH transparency mandates:Full supply chain disclosure requirements are accelerating clean-label innovation among European formulators, creating competitive differentiation for compliant houses.
- South Korean K-beauty expansion:Seoul-based brands are exporting gourmand body mists and layering systems into Southeast Asian markets, establishing new consumption rituals.
- Ethyl maltol biosynthesis:Fermentation-derived alternatives to petroleum-based sugar accords are reducing carbon intensity while securing volume for mass-market launches.
Market Restraints
- Natural vanilla absolute scarcity:Madagascar crop volatility and extraction labor costs concentrate supply risk among three dominant agricultural processors.
- IFRA 51st Amendment allergen thresholds:Restricted coumarin and benzyl benzoate limits in fine fragrance concentrations are forcing portfolio-wide reformulation investments.
- Synthetic musk substitution pressure:Environmental persistence concerns around polycyclic musks are accelerating R&D costs for compliant fixative alternatives.
Strategic Opportunities
- Scent-layering subscription channels:Direct-to-consumer discovery platforms are capturing recurring revenue from Gen-Z purchasers seeking curated gourmand portfolios.
- Brazilian gourmand body mist exports:Cheirosa-inspired formats are penetrating Middle Eastern duty-free retail, where alcohol-free concentrations meet cultural preferences.
- California SB 312 fragrance disclosure:Pioneering state-level ingredient transparency laws are creating first-mover advantage for preemptively compliant national brands.
Industry Challenges
- Perfumer training pipeline gaps:Specialized expertise in edible accord balancing and regulatory-compliant reformulation is concentrated among retiring master perfumers.
- Cross-border certification complexity:Divergent IFRA adoption timelines between Europe, the United States, and Asian markets are fragmenting global launch synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gourmand Fragrance Market |
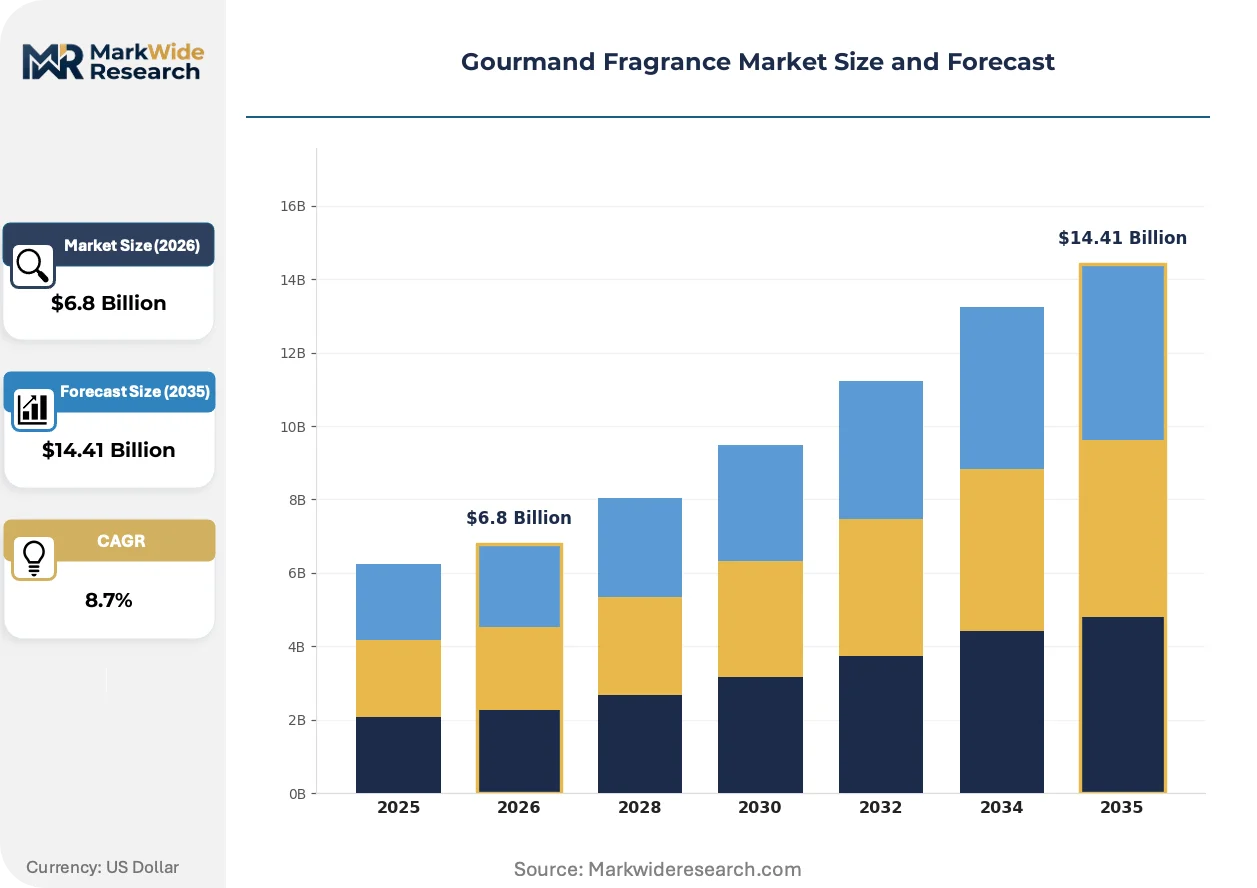
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Scented Oils, Body Mist Ingredient: Vanilla, Chocolate, Caramel, Nuts Consumer Type: Females, Males, Unisex, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Duty-Free Shops |
| Companies Covered | Tom Ford, Coach, MUGLER, Billie Eilish, Dolce&Gabbana, Gucci, Miu Miu, Sol de Janeiro, Burberry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gourmand Fragrance Market Shifts & Advancements
Synthetic biology and precision fermentation are disrupting century-old extraction dependencies, while regulatory fragmentation and subscription commerce are reshaping how gourmand fragrances reach end consumers.
Precision fermentation of vanillin and lactone molecules is automating the production of formerly scarce natural-identical accords. Niche perfumery houses in France and the United States are integrating these biosynthetic materials into ultra-premium launches, collapsing the traditional cost barrier between natural and synthetic positioning.
EU REACH substance restriction updates are compelling fragrance houses to phase out legacy synthetic musks and polycyclic aromatics. The regulatory pressure is accelerating investment in biodegradable fixative research, with eau de parfum concentrations above 20% facing the most complex compliance timelines.
Scent-layering discovery platforms are displacing traditional department store sampling as the primary trial mechanism for millennial and Gen-Z purchasers. Subscription boxes curated by algorithmic preference mapping are capturing fragrance discovery budgets in South Korea and the United States, compressing repurchase cycles from seasonal to monthly frequency.
Gourmand Fragrance Market Segmentation
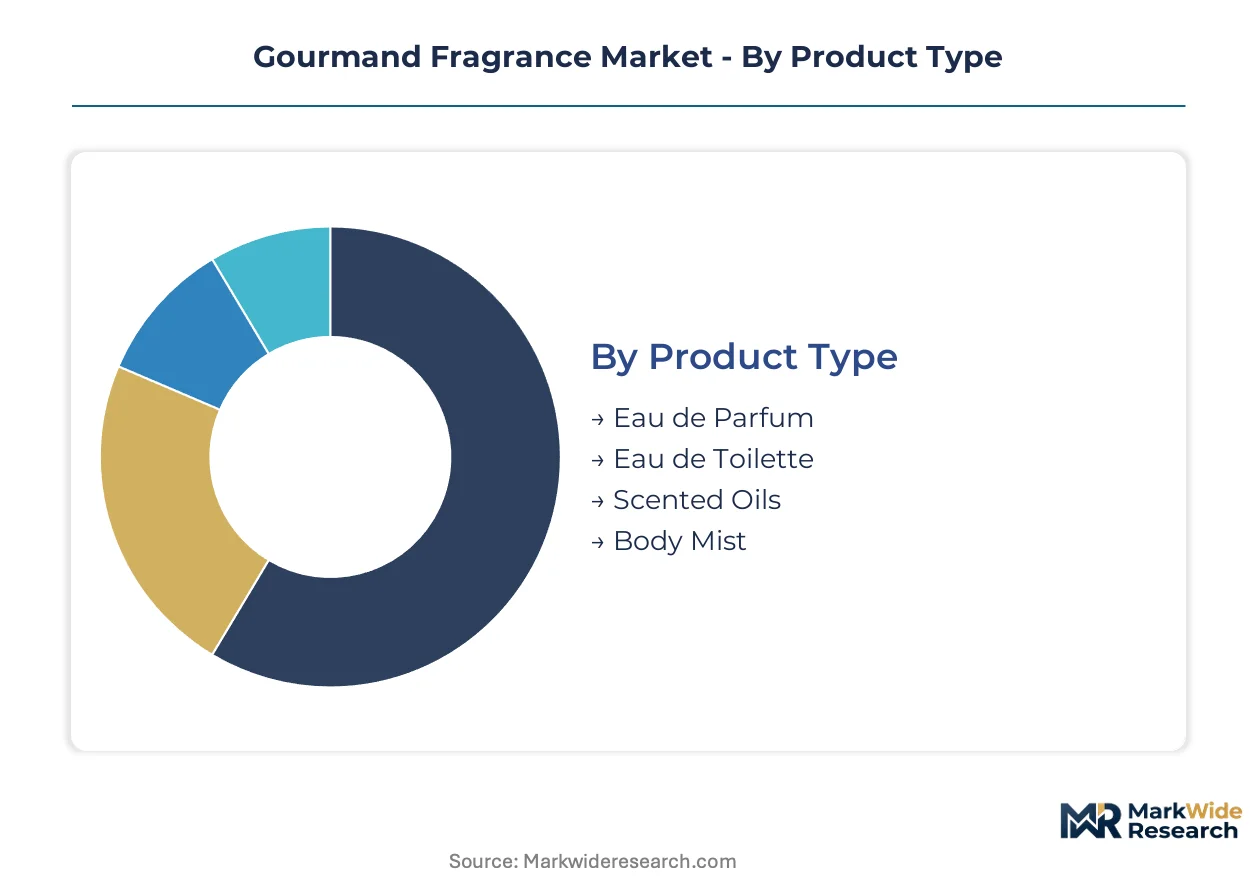
Gourmand fragrance segmentation reveals how concentration levels, edible accord profiles, and distribution architecture shape purchasing behavior. Manufacturers calibrate formulation intensity and channel strategy to match distinct consumer rituals across demographics.
Product Type:
Concentration specifications determine wear duration, price positioning, and regulatory classification across the value chain.
- Eau de Parfum:15-30% aromatic concentration delivers 6-10 hour longevity through higher absolute loading. Demand concentrates in France and the United States for gifting occasions and premium self-purchase, where IFRA 51st Amendment allergen thresholds are forcing reformulation investments in legacy vanilla-caramel portfolios.
- Scented Oils:Alcohol-free formats use jojoba or fractionated coconut oil as carrier bases, appealing to sensitive-skin consumers and cultural markets with alcohol restrictions. South Korean K-beauty brands are driving fastest expansion through layering systems and subscription discovery channels targeting Gen-Z purchasers.
- Eau de Toilette:5-15% concentration balances accessibility with daily wear practicality, dominating mass-market retail in European pharmacy chains.
- Body Mist:3-5% concentration in spray formats extends fragrance into post-shower and athletic use cases, with Brazilian-inspired Cheirosa variants penetrating Middle Eastern duty-free retail.
Mature deployment sits with Eau de Parfum. Newer deployment is concentrated in Scented Oils.
Ingredient:
Edible accord chemistry governs raw material sourcing strategy and biosynthetic substitution timelines.
- Vanilla:Madagascar Bourbon and Tahitian varietals supply natural absolute, while fermentation-derived vanillin collapses cost barriers. Supply risk concentrates among three agricultural processors facing Madagascar crop volatility, accelerating precision fermentation adoption by French niche houses.
- Caramel:Ethyl maltol and furaneol molecules create burnt-sugar profiles through synthetic or biosynthetic pathways. Seoul-based formulators are integrating caramel accords into K-beauty body mist exports across Southeast Asian markets.
- Chocolate:Cocoa absolute and synthetic pyrazines replicate dark and milk chocolate facets, with EU REACH transparency mandates accelerating clean-label innovation.
- Nuts:Praline, hazelnut, and almond accords rely on pyrazine chemistry and natural absolute extraction, facing IFRA restrictions on benzyl benzoate in fine fragrance concentrations.
Volume leadership belongs to vanilla. Climbing the fastest are nut-derived profiles in unisex positioning.
Consumer Type:
Gender positioning and age targeting determine marketing architecture and retail channel selection.
- Unisex:Gender-neutral bottle design and accord balancing displace traditional feminine-masculine segmentation. Gen-Z purchasers in the United States and South Korea drive demand through algorithmic subscription curation and scent-layering discovery platforms.
- Females:Patchouli-caramel and vanilla-gourmand structures dominate heritage franchise maintenance, with decades of brand equity concentrated in European and North American department store channels.
- Males:Tobacco-vanilla and rum-gourmand variants expand masculine fragrance boundaries, with private blend architectures sustaining ultra-premium positioning.
- Children:Hypoallergenic, low-concentration formats with simplified accord structures address parental safety concerns, with distribution concentrated in European pharmacy and North American specialty retail.
Established share rests with female-targeted formulations. Steepest expansion trajectory is occurring in unisex classification.
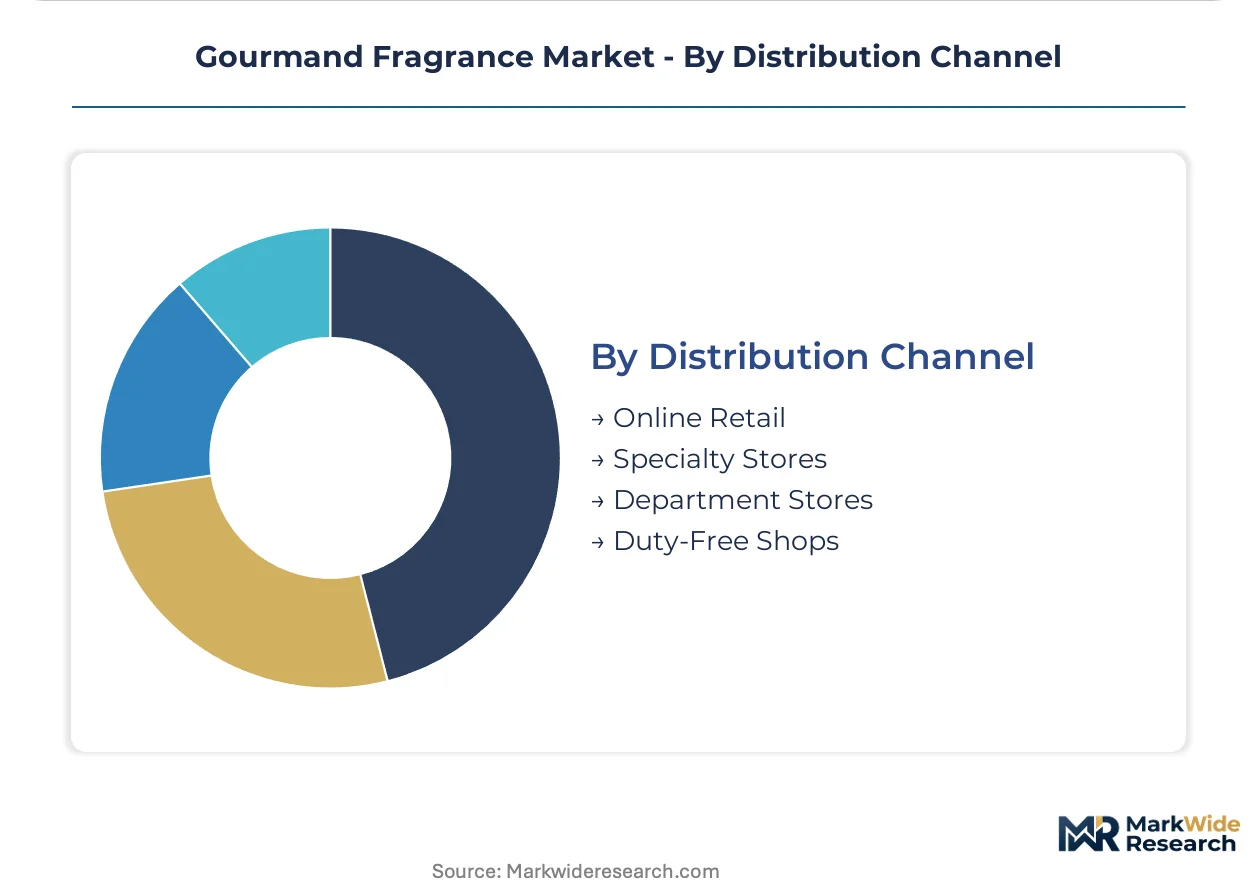
Distribution Channel:
Channel selection determines discovery mechanics, repurchase frequency, and margin capture architecture.
- Online Retail:Direct-to-consumer platforms and algorithmic curation compress repurchase cycles from seasonal to monthly frequency. Subscription boxes in South Korea and the United States capture fragrance discovery budgets through scent-layering portfolios.
- Specialty Stores:Niche perfumery houses in France leverage olfactory consultation and limited-edition drops to sustain ultra-premium positioning for vanilla and tobacco gourmand variants.
- Department Stores:Counter-based sampling and gifting infrastructure maintain relevance for Eau de Parfum concentrations, though traffic erosion is shifting investment toward experiential activation.
- Duty-Free Shops:Travel retail captures impulse purchase and discovery occasions, with alcohol-free body mist formats meeting cultural preferences in Middle Eastern and Asian airport corridors.
Traditional strength resides in department stores. Gaining share fastest is online retail through recurring engagement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors gourmand fragrance innovation through its concentration of heritage perfumery houses and niche ateliers. The city's Rue Saint-Honoré and Marais districts host formulation laboratories that supply edible-accord expertise to global luxury brands.
United States
New York and Los Angeles drive unisex gourmand adoption through algorithmic subscription platforms and scent-layering discovery services. The FDA exercises post-market surveillance under the Fair Packaging and Labeling Act, with California's SB 312 pioneering ingredient disclosure mandates that cascade into national retail compliance. Brooklyn-based independent perfumers are reformulating vanilla-caramel portfolios to meet tightening state-level allergen thresholds.
France
Grasse and Paris sustain global leadership in edible-accord formulation and ultra-premium positioning. EU REACH transparency mandates and IFRA 51st Amendment allergen restrictions are accelerating clean-label innovation among formulators in the Provence-Alpes-Côte d'Azur cluster. Niche houses along the Côte d'Azur are integrating precision-fermentation vanillin into limited-edition launches.
South Korea
Seoul's K-beauty brands are exporting gourmand body mists and layering systems across Southeast Asian markets. The MFDS regulates cosmetic fragrance safety, while Seoul-based formulators lead alcohol-free scented oil innovation for sensitive-skin consumers. Gangnam district retailers are capturing Gen-Z discovery budgets through monthly subscription curation.
Brazil
São Paulo and Rio de Janeiro inspire Cheirosa-format gourmand body mists that penetrate Middle Eastern duty-free retail. ANVISA oversees cosmetic fragrance registration, with Brazilian brands leveraging cultural preferences for alcohol-free concentrations. São Paulo-based exporters are establishing presence in Dubai and Abu Dhabi airport corridors.
United Kingdom
London's specialty retailers and department store channels maintain relevance for Eau de Parfum gifting occasions. The UK operates under retained EU REACH regulations post-Brexit, with the Health and Safety Executive enforcing substance restriction compliance. Mayfair-based niche perfumers are sourcing biosynthetic ethyl maltol for sustainable caramel accord portfolios.
Gourmand Fragrance Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the gourmand fragrance sector. Fragrance houses with captive formulation laboratories and raw material processing capabilities face pressure from brands that outsource manufacturing to specialized compounders. The market structures around three archetypes: heritage luxury houses with decades of brand equity, celebrity-fronted labels leveraging parasocial engagement, and Brazilian-inspired body mist specialists. Dominant competitive moves include portfolio diversification into scent-layering ecosystems and strategic partnerships with synthetic biology suppliers for sustainable edible-accord molecules.
Within the heritage luxury tier, Tom Ford and Gucci exemplify ultra-premium positioning through private blend architectures and decades of accumulated brand equity. Sol de Janeiro occupies a distinct position as the anchor for Brazilian gourmand formats, extending its Cheirosa scent ecosystem from skincare into standalone fragrance categories.
| Leading Market Players |
|---|
| Tom Ford |
| Coach |
| MUGLER |
| Billie Eilish |
| Dolce&Gabbana |
| Gucci |
| Miu Miu |
| Sol de Janeiro |
| Burberry |
| Others |
Supply & Pricing Matrix
Master perfumer concentration in Grasse and Paris creates labor-cost differentials that widen spreads between ultra-premium private blends and mass-market body mists. EU REACH compliance investments and Madagascar vanilla absolute scarcity feed cost compression pressures through mid-tier Eau de Parfum portfolios.
Pricing Analysis
Wear-duration value anchors pricing architecture across concentration tiers, with 6-10 hour longevity commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates heritage house private blends from K-beauty body mists and pharmacy-channel Eau de Toilette. Price differentiation rests on IFRA 51st Amendment certification tiers and biosynthetic ingredient sourcing. Pricing pressure stems from ethyl maltol fermentation scale-up enabling mass-market parity with natural absolutes. Gen-Z subscription purchasers exhibit highest price sensitivity, while gifting-segment buyers in France and the United States absorb premium markups with minimal elasticity.
Supply Chain Analysis
Freight cost volatility from Madagascar to European compounding centers amplifies vanilla absolute price instability. Supply concentrates among three agricultural processors in Madagascar, precision fermentation facilities in France and the United States, and Seoul-based K-beauty formulators. Raw material dependencies center on Bourbon vanilla pods, petroleum-derived aroma chemicals, and jojoba carrier oils. Single-source vulnerability in Madagascar crop harvests threatens natural-accord portfolios. Distribution runs through duty-free airport corridors for discovery formats, direct-to-consumer platforms for subscription replenishment, and department store counters for gifting concentrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into biosynthetic aroma chemical production has become the decisive vertical-integration race, with fermentation-derived vanillin and ethyl maltol offering cost stability against agricultural commodity swings.
For Market Incumbents: Extend proprietary scent-layering ecosystems to capture recurring subscription revenue and reduce customer acquisition costs. Deepen captive formulation laboratory capabilities in Grasse to accelerate IFRA-compliant reformulation timelines. Consolidate precision fermentation partnerships to secure volume for mass-market gourmand launches before synthetic biology startups achieve scale. For New Entrants and Emerging Players: California SB 312 in the United States opens a window for preemptive ingredient disclosure compliance that cascades into national retail advantage. Target alcohol-free scented oil formats in Middle Eastern duty-free corridors where cultural preferences align with product architecture. Penetrate Southeast Asian markets through Seoul-inspired layering systems and algorithmic curation platforms. Pursue white-label manufacturing partnerships with Brazilian body mist specialists to bypass capital-heavy captive production. For Investors and Strategic Acquirers: The window for entry favors niche perfumery houses with IFRA-compliant formulation archives and established ultra-premium positioning. Synthetic biology suppliers with fermentation-derived edible accord pipelines present acquisition targets as traditional extraction economics deteriorate. Watch for Madagascar crop failure signals as inflection indicators that would accelerate biosynthetic substitution timelines and reward early precision fermentation investors.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biosynthetic vanillin from Ginkgo Bioworks collapses cost barriers between natural and synthetic positioning. |
| Scent-Layering Subscription Launch | Algorithmic curation platforms in Seoul and New York compress repurchase cycles from seasonal to monthly frequency. |
| IFRA 51st Amendment Compliance Investment | Reformulation of legacy patchouli-caramel portfolios protects European market access for heritage houses. |
| Middle Eastern Duty-Free Expansion | Alcohol-free Cheirosa-format body mists meet cultural preferences in Dubai and Abu Dhabi airport corridors. |
| Clean-Label Transparency Program | EU REACH substance disclosure mandates create competitive differentiation for preemptively compliant formulators. |
Research Methodology
Multi-period observation of Madagascar vanilla harvest yields, IFRA amendment adoption timelines, and K-beauty export volumes anchored the trend analysis, supplemented by interviews with master perfumers in Grasse, regulatory affairs directors at European fragrance houses, procurement leads at South Korean cosmetics conglomerates, and subscription platform operators in New York and Seoul. Secondary validation drew from ECHA REACH substance databases, IFRA standards documentation, MFDS cosmetic safety filings, and customs trade records for aroma chemical imports. Bottom-up triangulation across formulation cost structures and top-down validation against retail channel revenue flows ensured analytical coherence.
Input-output matrices mapped aromatic concentration levels, edible accord chemistry, and distribution architecture against consumer willingness-to-pay across the analysis window. Segmentation dimensions modeled included product concentration tier, ingredient biosynthetic versus extraction origin, gender positioning, and channel discovery mechanism. CAGRs derived from compounding annual volume and value movements across these intersecting dimensions. Forecast inputs incorporated precision fermentation capacity buildout schedules and EU REACH substance restriction phase-in timelines.
The model assumes a particular technology adoption path for precision fermentation of vanillin and lactone molecules; alternative pathways for synthetic biology scale-up would alter the outlook for natural-synthetic cost parity. Forecasts reflect assumptions regarding Madagascar agricultural stability, IFRA harmonization across European and Asian markets, and Gen-Z subscription retention rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Global Luxury Perfumes Market