
 Reed Diffusers Market | 2026-2036
Reed Diffusers Market Size, Share, and Industry Trends Forecast 2026-2036
Reed Diffusers Market Analytics
Private-label fragrance manufacturing is narrowing as specialty houses reclaim margin pools through direct-to-consumer channels. Diptyque anchors its position through Parisian atelier heritage and controlled retail distribution. Reckitt Benckiser Group PLC leverages mass-market logistics to sustain volume leadership in standard diffuser formats. NEST New York differentiates through seasonal collection velocity and hospitality partnerships.
Reed diffusers are passive home fragrance systems comprising a vessel, perfumed oil base, and porous fiber reeds that draw liquid upward via capillary action for continuous evaporation without heat or electricity. The typical oil formulation combines fragrance concentrate with dipropylene glycol or alcohol carriers at ratios engineered for 30-90 day scent longevity. Standard diffusers dominate residential volume while eco-friendly variants using biodegradable reeds and plant-derived solvents command premium positioning. Decorative diffusers in ceramic and hand-blown glass vessels capture elevated margin pools through gifting occasions. The hospitality end-user segment shows structural expansion as hotels deploy signature scent programs for brand differentiation.
REACH governs fragrance chemical registration and safety documentation across European supply chains, while EPA oversight applies to volatile organic compound emissions in US-manufactured formulations. FDA regulations classify diffuser oils as cosmetic or household products depending on therapeutic claims, shaping label compliance burdens. California's Proposition 65 warning requirements create additional state-level formulation constraints for national brands. Stakeholders must monitor evolving fragrance allergen disclosure mandates and biobased solvent certifications to anticipate reformulation costs and premium positioning opportunities.
Market Dynamics
REACH disclosure mandates on fragrance allergens are forcing wholesale reformulation across European supply chains, compressing legacy oil bases while accelerating plant-derived solvent adoption.
Growth Catalysts
- Hospitality scent branding:Boutique hotel chains deploy signature ambient programs to differentiate guest experience, creating sustained bulk procurement contracts for custom formulations.
- California Proposition 65:Warning label requirements for volatile organic compounds push national brands toward cleaner bases, inadvertently elevating consumer trust in compliant products.
- Capillary fiber engineering:Advanced porous reed materials extend evaporation control to 90+ days, reducing replacement frequency and improving lifetime value metrics for residential users.
Market Restraints
- Dipropylene glycol price volatility:Petrochemical feedstock fluctuations compress margins on standard oil formulations, particularly affecting mass-market producers without captive solvent supply.
- European supply concentration:Specialty fragrance houses cluster in Grasse and Paris regions, creating bottleneck risk for complex custom scent development.
- Electric diffuser substitution:Ultrasonic and heat-based alternatives capture convenience-seeking urban consumers, especially in space-constrained apartments.
Strategic Opportunities
- Biobased certification premiums:USDA BioPreferred and EU Ecolabel pathways enable pricing power for reed systems using fermented alcohol carriers and cellulose reeds.
- Direct-to-consumer subscription:Refill models bypass retail margin capture, with seasonal scent curation locking in predictable recurring revenue.
- Wellness therapeutic positioning:FDA cosmetic-household boundary navigation allows aromatherapy-adjacent claims, opening pharmacy and spa channels previously inaccessible.
Industry Challenges
- Fragrance chemist scarcity:Formulation expertise combining stability engineering with olfactory science concentrates in legacy European ateliers, constraining R&D scaling.
- Multi-jurisdiction compliance timelines:Parallel EPA VOC, REACH dossier, and state-level warning requirements extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reed Diffusers Market |
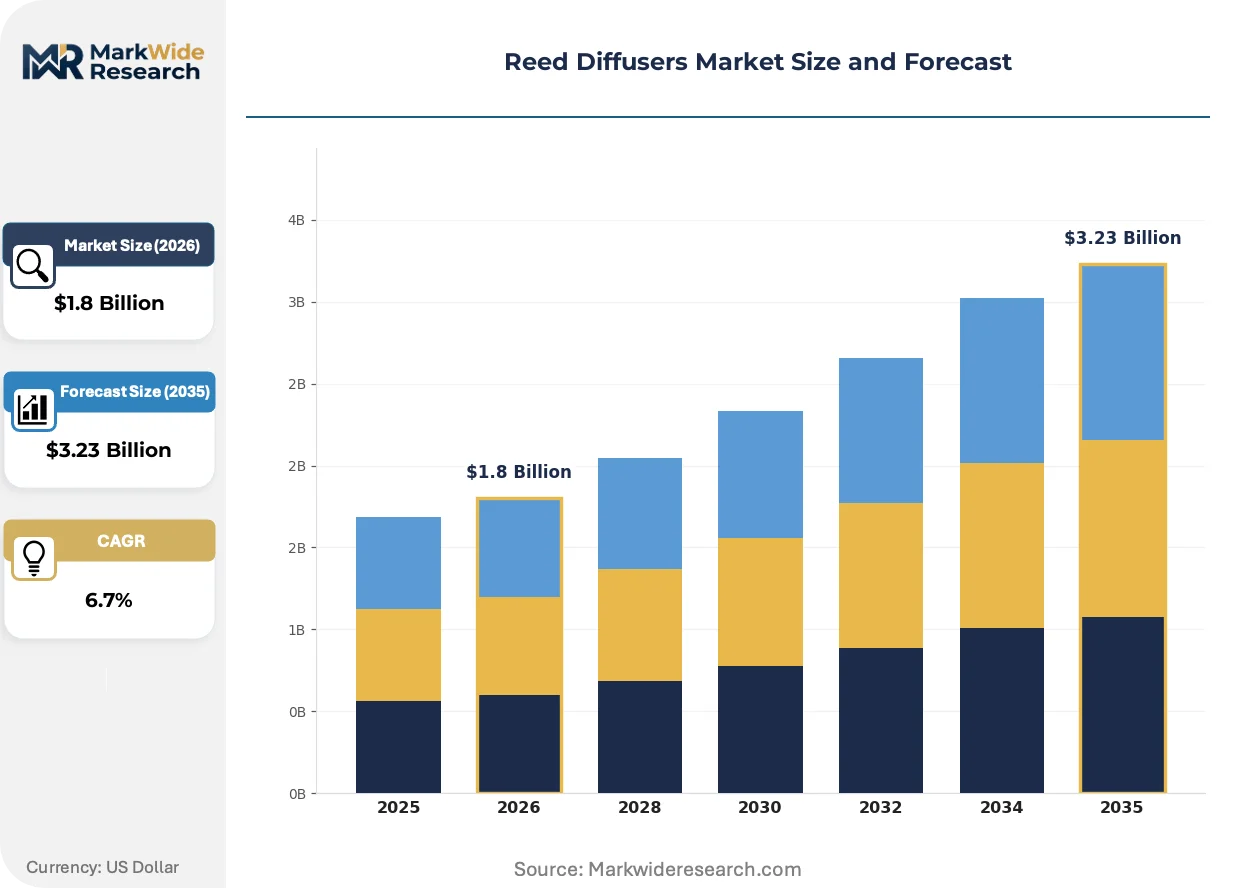
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Diffusers, Decorative Diffusers, Eco-Friendly Diffusers, Electric Diffusers End User: Residential, Commercial, Hospitality, Healthcare Material: Glass, Plastic, Wood, Metal Fragrance Type: Citrus, Floral, Spicy, Herbal |
| Companies Covered | Diptyque, Voluspa, Reckitt Benckiser Group PLC, Seda France, P. F. Candle Co., Yankee Candle Company, NEST New York, Bath & Body Works, Jo Malone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reed Diffusers Market Evolving Landscape
Formulation chemistry and scent delivery mechanisms are undergoing simultaneous transformation, with sustainability mandates and precision engineering converging to redefine product architecture.
Alcohol-fermented bases derived from agricultural waste streams are collapsing the cost premium previously attached to plant-derived solvents. Mid-market manufacturers in the United States and Germany adopt these bases at scale for 2024-2025 product lines, eroding the historical two-tier pricing structure between synthetic and natural-positioned offerings.
REACH Annex XVII expansions on fragrance allergen labeling impose granular disclosure thresholds, compelling reformulation of complex multi-note scents. European manufacturers face the steepest compliance burden, with luxury houses accelerating investment in synthetic biology to replicate prohibited natural extracts.
Urban residential buyers increasingly favor non-electric alternatives as energy costs and outlet scarcity reshape apartment design. Compact vessel formats with extended longevity claims capture preference in Tokyo, New York, and London micro-units, displacing plug-in systems in sub-400 square foot dwellings.
Reed Diffusers Market Segmentation

Reed diffuser segmentation reveals divergent margin architectures across passive and powered systems. Product format selection dictates raw material sourcing, regulatory pathway, and channel economics for manufacturers.
Product Type:
Cost tier stratification separates mass-market commodity formats from premium-positioned artisanal systems.
- Standard Diffusers:Vessel-reed-oil configurations using dipropylene glycol carriers and synthetic fiber reeds dominate unit economics through high-volume production. Procurement concentrates in US big-box retail and European drugstore chains where replacement frequency drives recurring purchase behavior.
- Decorative Diffusers:Hand-blown glass, ceramic, and sculpted vessels transform functional objects into gifting category anchors. Parisian ateliers and Murano glassworks supply limited-edition vessels to hospitality procurement teams seeking signature visual identity.
- Eco-Friendly Diffusers:Fermented alcohol bases and cellulose reeds target USDA BioPreferred and EU Ecolabel certification pathways.
- Electric Diffusers:Ultrasonic and heat-assisted systems compete on convenience in space-constrained urban apartments.
Standard Diffusers hold installed capacity. Eco-Friendly Diffusers is rotating up the share rankings.
End User:
Application context determines formulation complexity, scent longevity requirements, and contract structure.
- Residential:Individual consumers prioritize 60-90 day longevity claims and seasonal scent rotation in living spaces and bedrooms. Tokyo, New York, and London micro-unit dwellers favor compact non-electric formats as outlet scarcity reshapes apartment design.
- Commercial:Office and retail deployments emphasize low-maintenance systems with neutral scent profiles compatible with open-plan environments.
- Hospitality:Boutique hotel chains deploy signature ambient programs through bulk custom formulation contracts. Grasse-based fragrance houses capture sustained procurement relationships through exclusive scent development and controlled distribution.
- Healthcare:Wellness-adjacent positioning navigates FDA cosmetic-household boundary for spa and clinic channel access.
Hospitality commands premium contract values. Residential is expanding most quickly through direct-to-consumer refill subscriptions.
Material:
Supply concentration for vessel substrates shapes regional manufacturing footprints and margin capture.
- Glass:Borosilicate and soda-lime vessels from Murano, Czech Republic, and Chinese manufacturing clusters enable decorative premium positioning. Hand-blown production concentrates artisanal capacity in Italian and French supply basins.
- Plastic:PET and acrylic injection molding supports mass-market cost structures with limited design differentiation.
- Wood:Bamboo and hardwood vessels and reed holders target biobased certification premiums.
- Metal:Aluminum and brass vessels command elevated price points in gifting and hospitality segments.
Glass holds installed capacity. Wood is climbing the fastest on sustainability positioning.
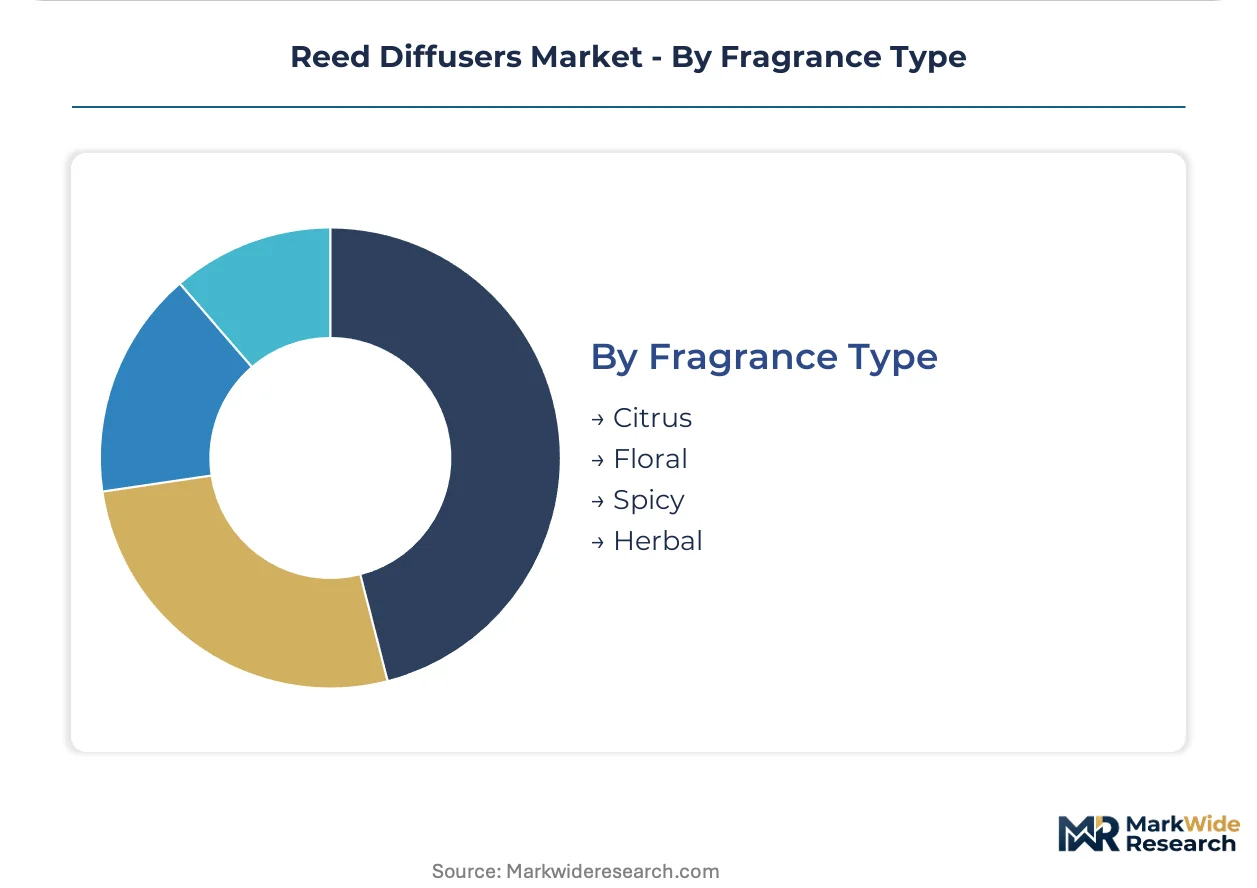
Fragrance Type:
Olfactory family selection drives reformulation complexity under tightening allergen disclosure mandates.
- Citrus:Limonene and citral-rich formulations face REACH Annex XVII labeling thresholds, compelling synthetic biology replication of prohibited natural extracts. Italian and Spanish citrus groves supply conventional concentrate to mass-market blenders.
- Floral:Rose, jasmine, and lavender bases dominate residential gifting occasions through association with relaxation and hospitality. Grasse-based extraction facilities and Indian jasmine cultivation regions supply premium natural concentrates.
- Spicy:Cinnamon, clove, and ginger profiles target seasonal collection velocity in North American and European winter markets.
- Herbal:Eucalyptus, sage, and rosemary formulations align with wellness therapeutic positioning for pharmacy and spa channel expansion.
Floral holds installed capacity. Herbal is gaining share fastest on wellness channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty fragrance houses cluster in France's Grasse region and Paris basin, while mass-market manufacturing concentrates in Chinese industrial zones and US distribution hubs. This bifurcation creates distinct supply architectures for premium artisanal and high-volume commodity segments.
United States
Urban residential demand concentrates in New York, Los Angeles, and Chicago micro-units where outlet scarcity favors non-electric formats. EPA oversight of volatile organic compound emissions shapes national formulation standards. California's Proposition 65 warning requirements create additional compliance layers for brands distributing across state lines.
France
Grasse-based ateliers supply complex custom scents to hospitality procurement teams seeking signature ambient programs. REACH Annex XVII expansions on fragrance allergen labeling impose granular disclosure thresholds on European manufacturers. Parisian design houses control limited-edition vessel production through relationships with Murano glassworks.
Germany
Fermented alcohol bases derived from agricultural waste streams scale through mid-market manufacturing facilities in 2024-2025 product cycles. ECHA enforcement of REACH dossier requirements extends product launch timelines for reformulated oil bases. Cologne and Hamburg distribution clusters serve as entry points for private-label brands targeting EU drugstore chains.
China
Manufacturing capacity for standard vessel-reed-oil configurations concentrates in Zhejiang and Guangdong provinces serving export markets. The country's national chemical safety regulator imposes parallel documentation requirements for fragrance concentrate imports. Shenzhen logistics hubs enable direct-to-consumer fulfillment for subscription refill models targeting North American buyers.
United Kingdom
London-based hospitality procurement teams source signature scent programs from Grasse suppliers through established trade relationships. Post-Brexit alignment with REACH standards maintains formulation continuity for EU-exporting domestic brands. Manchester and Birmingham distribution centers handle volume throughput for mass-market retail partnerships.
Reed Diffusers Market Competitive Landscape
Parisian heritage houses and mass-market conglomerates split the market into distinct margin architectures. Specialty fragrance ateliers capture premium positioning through controlled retail distribution and limited-edition releases. Mass-market players sustain volume leadership through big-box retail penetration and seasonal collection velocity. Competitive moves concentrate on direct-to-consumer channel development and biobased certification acquisition.
Within the heritage atelier tier, Diptyque exemplifies controlled scarcity through Parisian provenance and exclusive retail placement. Reckitt Benckiser Group PLC occupies the scale-driven mass-market position with logistics infrastructure supporting high-volume distribution. NEST New York represents the hospitality-partnership archetype, anchoring seasonal collection strategies and signature scent program development.
| Leading Market Players |
|---|
| Diptyque |
| Voluspa |
| Reckitt Benckiser Group PLC |
| Seda France |
| P. F. Candle Co. |
| Yankee Candle Company |
| NEST New York |
| Bath & Body Works |
| Jo Malone |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII allergen disclosure mandates compressing legacy formulation margins determine both the premium commanded by compliant plant-derived bases and the geographic consolidation of European fragrance chemistry expertise. This regulatory chokepoint simultaneously elevates pricing power for Grasse-based ateliers with reformulation capabilities while forcing mass-market producers toward costlier biobased alternatives or exit from EU distribution.
Pricing Analysis
REACH compliance dictates the pricing tier structure across the reed diffuser market, separating premium-positioned European heritage houses from cost-pressured mass-market competitors. Price differentiation hinges on certification tier—USDA BioPreferred and EU Ecolabel pathways enable margin capture—and brand heritage anchored in Grasse or Paris provenance. Pricing pressure intensifies in standard diffuser segments as fermented alcohol bases erode the historical cost gap with synthetic carriers. Residential consumers in urban micro-units show highest price sensitivity, while hospitality procurement teams prioritize scent exclusivity over unit economics.
Supply Chain Analysis
Petrochemical feedstock volatility in dipropylene glycol and synthetic fiber reed production anchors upstream cost instability for mass-market manufacturers. Raw material sourcing draws from Chinese injection molding clusters for plastic vessels, Italian and French glassworks for decorative premium formats, and agricultural waste stream processors in Germany and the United States for fermented alcohol carriers. Single-source vulnerability concentrates in Grasse-based fragrance concentrate supply for complex custom scents. Distribution runs through big-box retail partnerships for volume tiers and controlled direct-to-consumer channels for heritage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reed diffuser market sits in a cyclical recovery phase driven by hospitality sector reinvestment in signature ambient programs following pandemic-era operational disruptions.
For Market Incumbents: Insulate margin pools by accelerating backward integration into fermented alcohol production and securing captive cellulose reed supply before biobased certification demand peaks. Reckitt Benckiser Group PLC and mass-market conglomerates face substitution risk from electric diffuser convenience; counter through extended longevity claims and subscription refill lock-in. Prioritize EPA VOC pre-compliance to capture California Proposition 65 positioning ahead of national brand competitors. For New Entrants and Emerging Players: Pursue white-space opportunity in healthcare-adjacent wellness positioning, where FDA cosmetic-household boundary navigation opens pharmacy and spa channels with limited incumbent saturation. Target direct-to-consumer subscription models in Tokyo, New York, and London micro-unit segments where outlet scarcity favors non-electric formats. Launch through seasonal scent curation partnerships with boutique hotel chains seeking agile supplier relationships outside Grasse atelier networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-market manufacturers with biobased certification pathways and hospitality contract books. Long-term viability across the projection horizon rests on reformulation agility under tightening REACH and state-level disclosure mandates. Acquisition targets should demonstrate synthetic biology capabilities for allergen-free natural extract replication. Monitor ECHA enforcement patterns as the inflection signal for compliance cost acceleration and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Certification Acquisition | USDA BioPreferred and EU Ecolabel pathways unlock pricing power in premium residential and hospitality segments. |
| Direct-to-Consumer Subscription Launch | Refill models bypass retail margin capture and establish predictable recurring revenue in urban micro-unit markets. |
| Backward Integration into Fermented Alcohol | In-house production of agricultural waste-derived carriers collapses cost premiums previously attached to plant-based positioning. |
| Hospitality Signature Scent Partnership | Exclusive custom formulation contracts with boutique hotel chains anchor sustained bulk procurement and brand differentiation. |
| Synthetic Biology R&D Investment | Replication capabilities for REACH-restricted natural extracts preserve complex multi-note scent portfolios under tightening allergen disclosure. |
Research Methodology
A standing panel of fragrance house formulation directors, hospitality procurement managers, retail category buyers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH dossier filings, EPA VOC emission databases, customs records for fragrance concentrate trade flows, and SEC disclosures from publicly traded consumer goods conglomerates. Bottom-up triangulation across product format volumes and top-down reconciliation against end-user segment spending patterns anchored value estimates.
Scenario-bracketing around regulatory enforcement intensity and hospitality sector capital expenditure cycles shaped the analytical framework across the projection horizon. Segmentation modeling captured product type stratification, end-user application context, material substrate sourcing, and fragrance family reformulation complexity. CAGRs derived from elasticity-adjusted demand curves incorporating outlet scarcity trends in urban residential markets and signature scent program adoption curves in boutique hotel chains.
Sensitivities concentrate around REACH Annex XVII expansion timing, dipropylene glycol feedstock volatility, and electric diffuser substitution rates in space-constrained apartments. Forecasts reflect assumptions on biobased certification adoption velocity and hospitality contract renewal patterns. Cross-checking against Circana retail audit data and hotel industry capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market