
 Service Delivery Automation (SDA) Market | 2026-2036
Service Delivery Automation (SDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Service Delivery Automation (SDA) Market Intelligence
Direct enterprise sales channels is reconfiguring as vendor-customer relationships in service delivery automation. UiPath leverages its partner ecosystem to sustain platform stickiness across Fortune 500 accounts. Automation Anywhere Inc. anchors its position through cloud-native architecture designed for distributed workforce orchestration. IBM Corporation competes by embedding SDA capabilities within broader hybrid cloud consulting engagements.
Service Delivery Automation encompasses software platforms that orchestrate IT and business processes through robotic process automation, artificial intelligence, and machine learning algorithms executing rule-based and cognitive tasks with minimal human intervention. These systems integrate with enterprise service management frameworks to resolve incidents, deploy changes, and allocate resources across hybrid infrastructure environments. Cloud-based deployment models capture the fastest expansion as organizations prioritize elastic scaling and reduced capital overhead, while on-premises installations retain dominance in regulated sectors where data sovereignty governs architecture decisions. Workflow automation solutions command the deepest margin pools due to their direct linkage to measurable operational expenditure reduction.
The EU AI Act imposes risk-tiered compliance obligations on automated decision systems deployed within European member states, compelling vendors to embed explainability and human oversight mechanisms. HIPAA in the United States constrains how SDA platforms handle protected health information, shaping product roadmaps for healthcare-focused system integrators. ISO standards for IT service management provide the baseline certification that procurement teams require for vendor qualification. Stakeholders must evaluate how emerging algorithmic accountability frameworks will reshape platform architecture requirements and customer onboarding protocols.
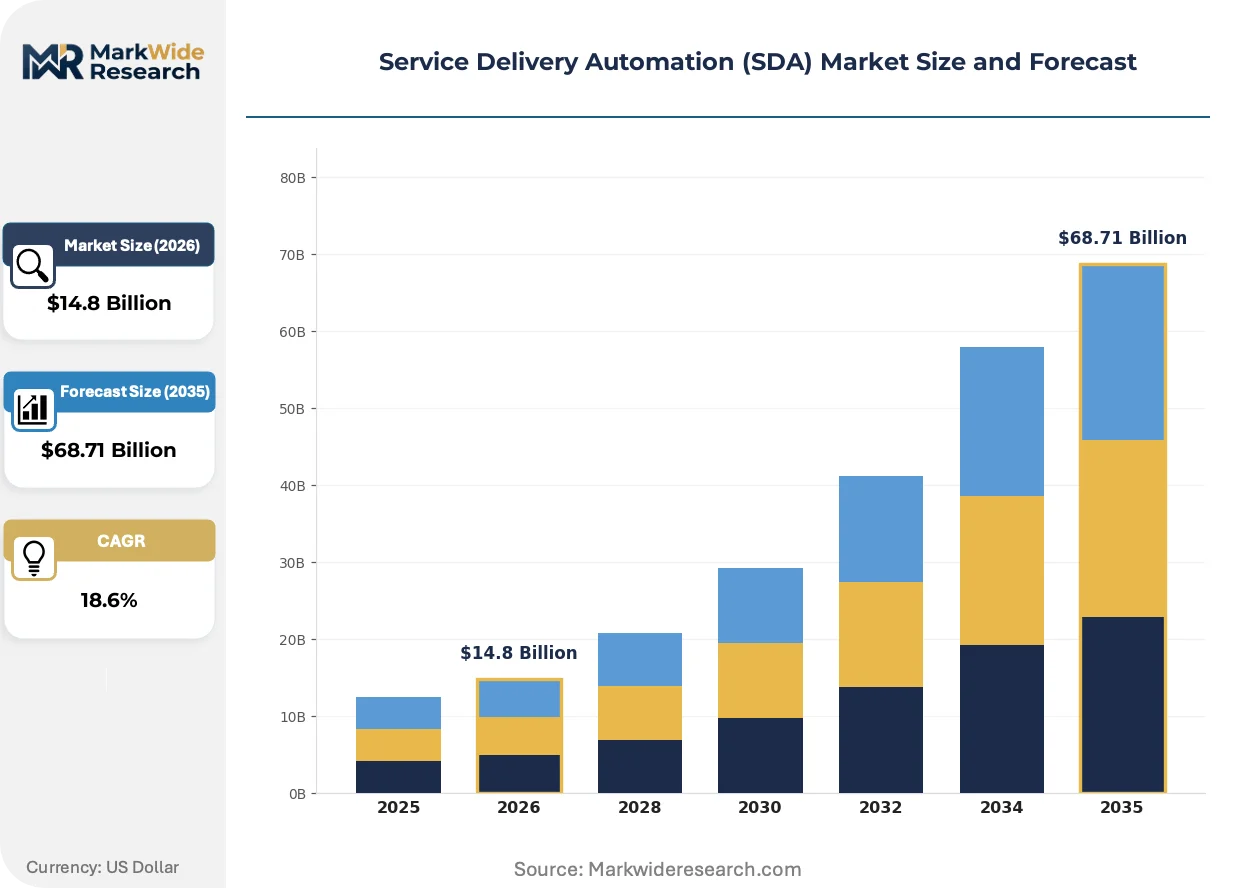
Market Dynamics
The EU AI Act's risk-tiered compliance obligations are forcing platform vendors to rebuild architecture around explainability and human oversight, compressing deployment timelines for automated decision systems across European financial services and healthcare sectors.
Growth Catalysts
- Process Orchestration Convergence:Workflow automation platforms that unify robotic process automation with machine learning inference engines are capturing enterprise IT budgets previously fragmented across point solutions.
- Germany's Industrial Automation Corridor:Manufacturing conglomerates along the Rhine-Ruhr and Stuttgart regions are deploying governed automation platforms to synchronize shop-floor robotics with enterprise resource planning systems.
- GDPR-Driven Data Sovereignty:The regulation's cross-border transfer restrictions are compelling multinationals to adopt on-premises or regional cloud SDA deployments rather than centralized global instances.
Market Restraints
- Specialized Talent Scarcity:The shallow pool of engineers capable of integrating machine learning models with legacy enterprise service management frameworks inflates implementation costs and extends project timelines.
- Technical Debt Burden:Decades-old IT service management platforms in incumbent enterprises resist API-native integration, forcing expensive middleware layers that erode automation ROI.
- Algorithmic Accountability Uncertainty:Emerging liability frameworks for autonomous decision systems create legal exposure that slows procurement cycles in regulated sectors.
Strategic Opportunities
- United Kingdom Fintech Hubs:London and Manchester payment processors represent underpenetrated demand for real-time transaction monitoring automation that complies with Financial Conduct Authority operational resilience requirements.
- ISO 20022 Migration:The financial messaging standard's adoption is creating replacement demand for legacy payment automation infrastructure across European correspondent banking networks.
- Edge-Cloud Hybrid Architectures:Convergence of containerized automation runtimes with 5G low-latency connectivity is enabling new use cases in predictive field service dispatch for industrial equipment.
Industry Challenges
- Multi-Vendor Integration Complexity:Enterprises stitching together automation platforms from competing vendors face API incompatibility and conflicting orchestration semantics that degrade end-to-end process visibility.
- Change Management Resistance:IT operations teams accustomed to ticket-based workflows resist ceding control to autonomous incident resolution systems, requiring sustained organizational transformation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Delivery Automation (SDA) Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Network Orchestration, Incident Management, Change Management, Workflow Automation, Resource Scheduling, Service Monitoring Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services Application Area: Telecommunications, IT Service Management, Financial Services, Manufacturing, Public Sector, Energy & Utilities End User Industry: Service Providers, Enterprises, System Integrators, Government Agencies, Consulting Firms |
| Companies Covered | UiPath, Automation Anywhere Inc., IBM Corporation, Blue Prism, Xerox Corporation, NICE Ltd, IPsoft Inc., Pegasystems Inc., Celaton Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Delivery Automation (SDA) Market Strategic Shifts & Innovations
Generative AI capabilities are being embedded into service delivery platforms, shifting competitive advantage toward vendors that can translate natural language process descriptions directly into executable automation workflows without intermediate coding layers.
Intelligent document processing engines that extract structured data from unstructured inputs are digitizing claims handling and invoice reconciliation in insurance and healthcare sectors. Mid-market enterprises are adopting these tools through low-code configuration interfaces rather than custom development. The compression of implementation timelines is digitizing what previously required six-month professional services engagements into self-service deployments completed in weeks.
The EU AI Act's prohibited practices list and high-risk system registration requirements are reshaping product roadmaps for vendors serving European customers. Platform providers must now embed technical documentation generation and conformity assessment workflows directly into their development pipelines. Healthcare automation deployments in France and Germany face the steepest compliance burden due to overlapping medical device regulation and AI system classification.
Enterprise buyers are consolidating vendor relationships around platforms that bundle automation development, execution, and governance rather than maintaining separate tools for each function. System integrators that previously resold point solutions are repositioning as managed automation service providers. This consolidation is most advanced in the United Kingdom's financial services sector, where operational resilience mandates favor single-vendor accountability for critical business process automation.
Service Delivery Automation (SDA) Market Segmentation
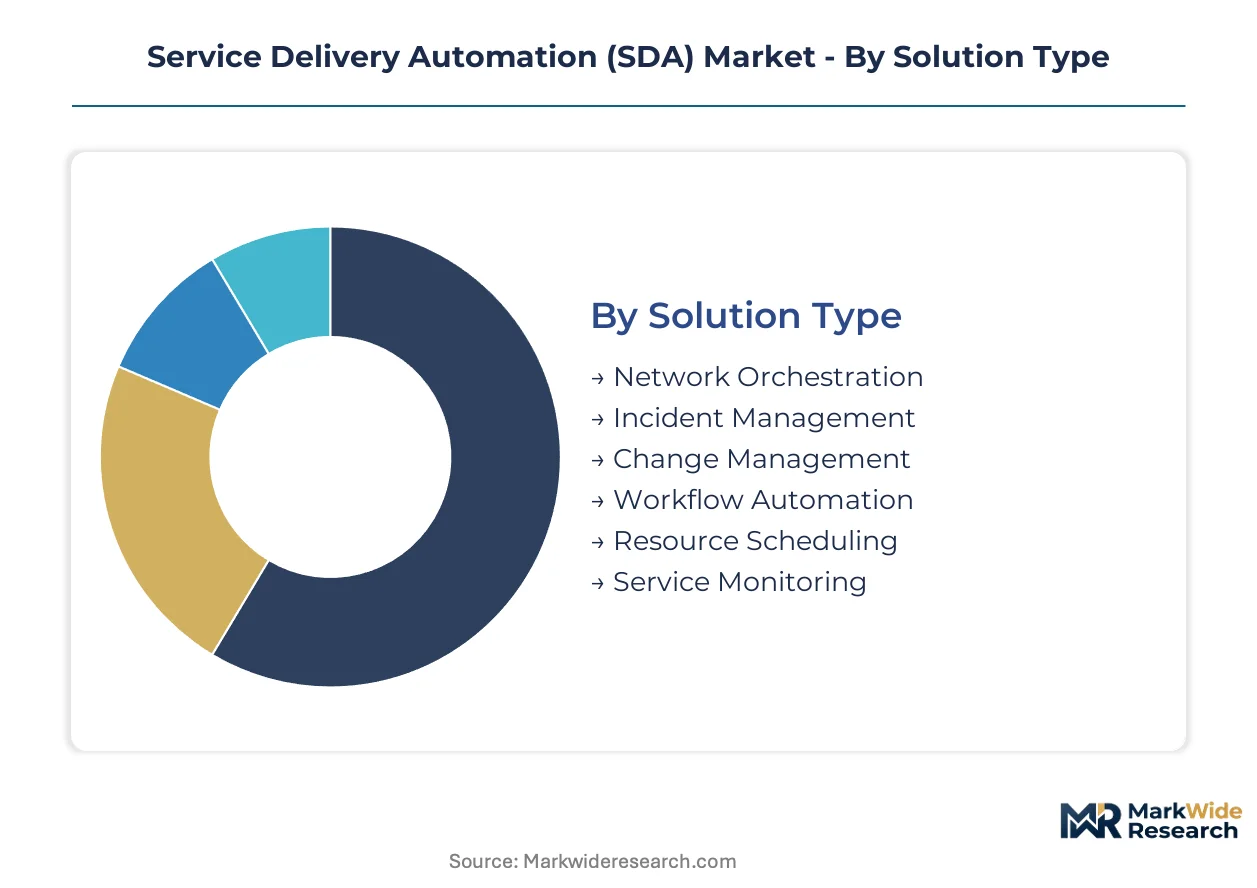
Service delivery automation platforms fragment across multiple technical and commercial dimensions, with solution architecture, deployment constraints, and industry compliance requirements shaping procurement patterns. Understanding these segment boundaries reveals where platform vendors concentrate R&D investment and where system integrators capture implementation margins.
Solution Type:
Functional specialization spans the full incident-to-resolution lifecycle, from reactive network stabilization through predictive resource allocation.
- Workflow Automation:Platforms orchestrating multi-step business processes through configurable rule engines and API connectors. Financial services procurement teams in Frankfurt and London prioritize these tools for regulatory reporting workflows where audit trails are mandatory.
- Incident Management:Systems that ingest monitoring alerts, correlate events, and trigger automated remediation playbooks. Telecommunications operators across Germany's industrial corridor deploy these for 5G network fault isolation where mean-time-to-repair directly impacts service level agreements.
- Network Orchestration:Software-defined controllers that provision virtual network functions and balance traffic loads.
- Change Management:Platforms enforcing approval gates and automated testing pipelines before production deployment.
- Resource Scheduling:Algorithms optimizing technician dispatch and infrastructure capacity allocation.
- Service Monitoring:Real-time dashboards and threshold-based alerting for hybrid cloud infrastructure.
The dominant share belongs to Workflow Automation, while Incident Management is closing the gap fastest.
Deployment Model:
Architecture decisions reflect data sovereignty mandates, capital constraints, and internal IT maturity rather than pure technical preference.
- Cloud-Based:Elastic infrastructure with consumption-based pricing and automatic patch management. GDPR's cross-border transfer restrictions limit adoption among EU healthcare providers handling patient records.
- On-Premises:Dedicated hardware installations within customer data centers providing complete data control. Germany's federal agencies mandate this model for classified systems under national cybersecurity frameworks.
- Hybrid:Workload distribution across private infrastructure and public cloud with unified orchestration.
- SaaS:Multi-tenant platforms with rapid feature deployment and minimal IT overhead.
- Managed Services:Third-party operation of automation infrastructure with outcome-based pricing.
Cloud-Based deployments command the widest customer base, though Hybrid architectures are expanding most quickly as enterprises balance agility with compliance.
Application Area:
Industry-specific compliance and operational complexity determine platform customization requirements and sales cycle duration.
- Financial Services:Real-time transaction monitoring, fraud detection automation, and regulatory reporting. The EU AI Act's high-risk system classification drives demand for explainable automation in Paris and Amsterdam trading operations.
- IT Service Management:Ticket routing, knowledge base automation, and service level agreement enforcement. United Kingdom enterprises consolidate legacy ITSM tools here to meet Financial Conduct Authority operational resilience deadlines.
- Telecommunications:Network provisioning, customer onboarding, and billing reconciliation.
- Manufacturing:Shop-floor integration with enterprise resource planning and predictive maintenance.
- Public Sector:Citizen service portals and inter-agency data exchange automation.
- Energy & Utilities:Grid monitoring, outage response, and demand forecasting.
Financial Services retains the deepest penetration, yet IT Service Management is gaining share fastest as hybrid workforces strain legacy support models.
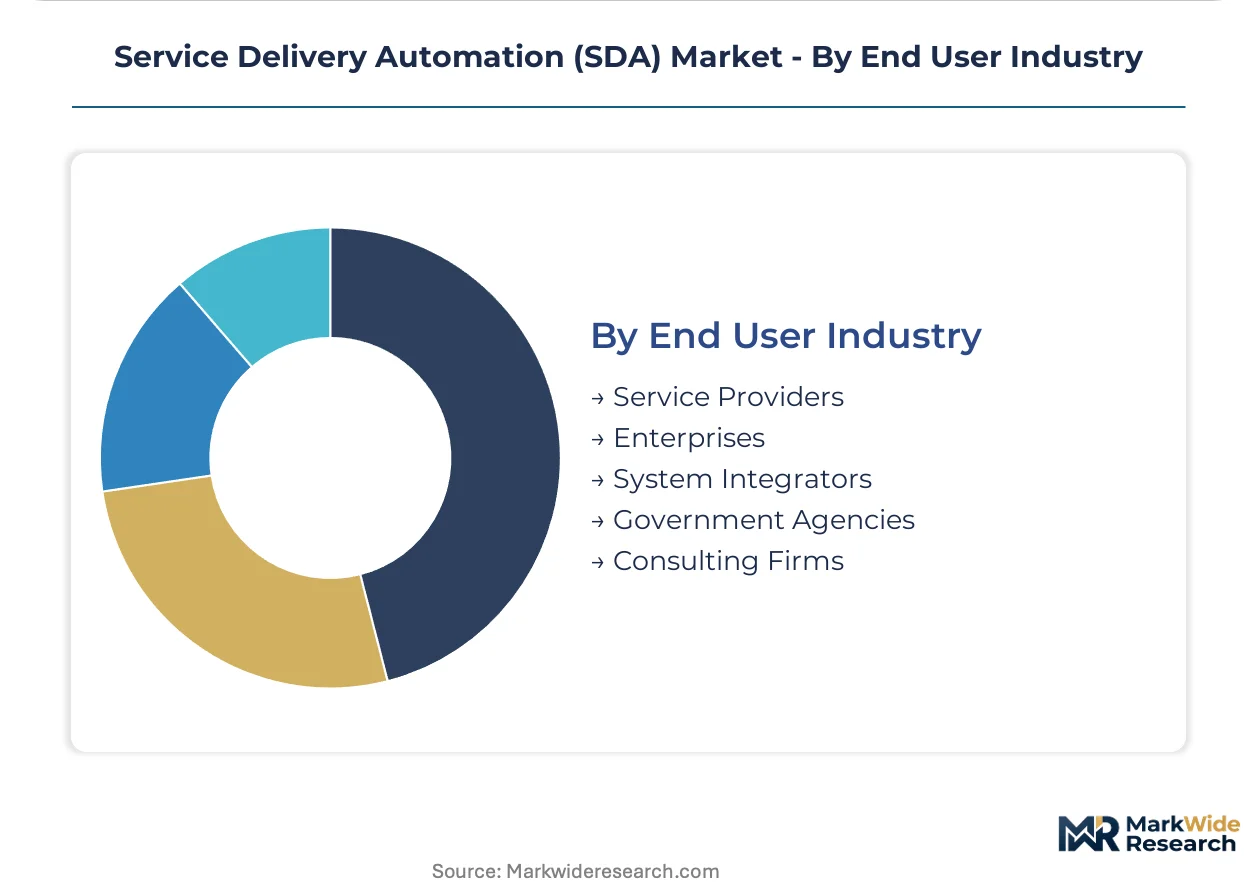
End User Industry:
Buyer sophistication and implementation scale vary sharply across organizational types, from transactional procurement to strategic transformation programs.
- Enterprises:Large organizations with dedicated automation centers of excellence and multi-year platform roadmaps. German automotive conglomerates in Stuttgart deploy governed automation platforms integrating supplier ecosystems with just-in-sequence production.
- Service Providers:Outsourced IT and business process operators competing on cost-to-serve metrics. These buyers prioritize workforce orchestration tools that maintain margins across distributed delivery centers.
- System Integrators:Implementation partners reselling platforms with professional services bundles.
- Government Agencies:Public sector buyers with rigid procurement frameworks and security clearance requirements.
- Consulting Firms:Advisory practices embedding automation into broader digital transformation engagements.
Enterprises dominate current deployment value, though Service Providers are scaling fastest as outsourcing contracts incorporate automation guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation corridors command 15-20% pricing premiums over equivalent deployments in Southern European markets, reflecting tighter compliance engineering requirements and deeper integration with legacy manufacturing systems.
Germany
Rhine-Ruhr manufacturing conglomerates and Stuttgart automotive clusters drive demand for governed automation platforms synchronizing shop-floor robotics with enterprise resource planning. The national cybersecurity framework mandates on-premises installations for classified federal systems. Baden-Württemberg's automotive suppliers deploy just-in-sequence production automation integrating tiered supplier ecosystems.
United Kingdom
London and Manchester payment processors generate underpenetrated demand for real-time transaction monitoring automation. Financial Conduct Authority operational resilience deadlines accelerate consolidation of legacy IT service management tools. The capital's fintech hubs favor single-vendor accountability for critical business process automation.
France
Paris trading operations and healthcare networks face overlapping EU AI Act high-risk system classification and medical device regulation. ANSM and CNIL compliance requirements steepen platform architecture burdens. Île-de-France insurance carriers digitize claims handling through intelligent document processing engines.
United States
HIPAA constrains protected health information handling in healthcare-focused system integrators, shaping product roadmaps for hybrid cloud deployments. FDA oversight of software-as-medical-device intersects with automation platforms in diagnostic workflows. Greater Boston's healthcare technology corridor and Silicon Valley enterprise software clusters anchor North American demand.
India
Bangalore and Hyderabad service provider delivery centers compete on cost-to-serve metrics through workforce orchestration tools. RBI guidelines on digital payment infrastructure drive automation in banking back-office operations. Karnataka's technology parks host outsourcing contracts incorporating automation performance guarantees.
Service Delivery Automation (SDA) Market Key Industry Players
Platform-native specialists and legacy systems integrators split the market between cloud-native architecture and embedded consulting engagements. Consolidation pressure favors vendors bundling development, execution, and governance functions. Three archetypes dominate: pure-play automation platforms, hybrid cloud consultancies, and managed service providers repositioning from system integration. Geographic expansion through regional data center deployment and strategic partnerships with system integrators represent the dominant competitive vectors.
Within the pure-play tier, UiPath exemplifies platform stickiness strategies leveraging partner ecosystems across Fortune 500 accounts. Automation Anywhere Inc. occupies a position emphasizing cloud-native architecture for distributed workforce orchestration. IBM Corporation anchors the hybrid cloud consultancy archetype by embedding SDA capabilities within broader transformation engagements. These three representations illustrate how vendor origin and corporate structure shape competitive positioning without determining specific market outcomes.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere Inc. |
| IBM Corporation |
| Blue Prism |
| Xerox Corporation |
| NICE Ltd |
| IPsoft Inc. |
| Pegasystems Inc. |
| Celaton Limited |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure providers in the United States and Ireland concentrate upstream compute capacity, directing margin pools toward workflow automation vendors that bundle governance tooling with execution engines. German industrial buyers absorb 15-20% premiums for configured-to-order deployments that synchronize with legacy manufacturing execution systems.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from enterprise-configured deployments. Subscription-based pricing with consumption-scaled tiers dominates, though project-based professional services retain share in regulated sectors. Price differentiation hinges on ISO 27001 certification tier and geographic data residency requirements. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler infrastructure commoditizes base compute. Healthcare providers in France and Germany exhibit lowest price sensitivity due to overlapping EU AI Act and medical device compliance burdens.
Supply Chain Analysis
Extended payment terms from system integrators to platform vendors now stretch 90-120 days, with supply-chain finance facilities bridging working capital gaps. Software development concentrates in the United States, India, and Ireland, while specialized ML engineering talent clusters in Germany and the United Kingdom. Raw material dependencies include GPU accelerators, cloud storage infrastructure, and proprietary training datasets. Single-source vulnerability around NVIDIA H100 supply creates procurement risk for inference-heavy deployments. Distribution runs through direct enterprise sales with partner-led implementation in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock enterprise buyers into orchestration platforms that embed deeply across hybrid infrastructure. Regulatory entrenchment compounds this advantage as compliance engineering requirements steepen with each EU AI Act enforcement wave.
For Market Incumbents: Insulate platform stickiness by embedding explainability documentation generators directly into development pipelines, addressing EU AI Act technical file requirements before competitors retrofit. Acquire specialized intelligent document processing firms in France and Germany to preempt margin erosion from pure-play IDP vendors. Vertical integration into edge-cloud orchestration runtimes captures 5G-enabled field service automation demand.
For New Entrants and Emerging Players: Manchester and Birmingham payment processors represent underpenetrated demand for real-time transaction monitoring that satisfies Financial Conduct Authority operational resilience mandates. Target mid-market insurance carriers in Île-de-France with low-code claims automation configured for ANSM medical device data handling. Partner with Germany's Mittelstand system integrators to bypass direct competition with UiPath's Fortune 500 partner ecosystem.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native automation platforms with embedded governance tooling and existing EU AI Act conformity assessment workflows. Long-term viability favors vendors that compress implementation timelines from months to weeks through generative AI-assisted configuration. Monitor ISO 20022 migration completion across European correspondent banking networks as inflection indicator for replacement demand in payment automation infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying RPA, ML inference, and governance tooling captures IT budgets previously fragmented across point solutions. |
| Geographic Expansion | Regional data center deployment in Frankfurt and Amsterdam satisfies GDPR cross-border transfer restrictions for healthcare providers. |
| Acquisition of Specialist Firm | Intelligent document processing targets in France digitize claims handling for ANSM-regulated insurance carriers. |
| Strategic Partnership | System integrator alliances in Baden-Württemberg embed just-in-sequence automation into automotive supplier ecosystems. |
| Product Launch | Generative AI-assisted workflow configuration reduces professional services dependency for mid-market buyers. |
Research Approach
The analysis maps workflow automation, incident management, network orchestration, and change management platforms, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with automation center-of-excellence leads and system integrator practice heads combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU AI Act implementation guidance. Bottom-up deployment sizing triangulated against top-down IT services market estimates.
Assumptions held fixed include GDPR enforcement continuity and EU AI Act high-risk system classification scope, while cloud adoption curves and 5G infrastructure rollout timing were varied across sensitivity scenarios. Segmentation modeled deployment model, organization size, vertical compliance complexity, integration architecture, and regional regulatory cluster. CAGRs derived from installed base expansion rates and replacement demand timing. Industry-specific inputs included ISO 20022 migration schedules and Financial Conduct Authority operational resilience deadline clustering.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capital expenditure cycles or cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and hyperscaler capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Dropshipping Automation Software Market
Automation
Distribution Automation Solutions Market
Automation
Global Form Automation Software Market
Automation
Global Warehouse Execution System Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Automation-As-A-Service Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Global Remote Monitoring and Control Market
Automation
IoT Home Automation Market
Automation
Hyperautomation Market
Automation
Parcel Sorting System Market
Automation
Database Automation Market
Automation
AR Automation Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Computer Numerical Control Market
Automation
Self Bag Drop Machine Market