
 Sound Effects Services Market | 2026-2036
Sound Effects Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sound Effects Services Market Insights
Los Angeles is narrowing its capacity gap with London as post-production sound stages multiply across both cities. Skywalker Sound leverages its Marin County complex to sustain premium theatrical mixing dominance. Abbey Road Studios anchors high-end music and film scoring workflows through its historic London facility. Boom Post competes aggressively in UK television drama with specialized Foley and dialogue editing operations.
Sound effects services encompass the creation, manipulation, and integration of non-musical audio elements into visual media, typically delivered at 48 kHz/24-bit resolution for broadcast and theatrical exhibition, with spatial formats requiring object-based metadata for immersive playback systems. Post production commands the largest revenue share as streaming catalogs balloon, while sound design for video games records the fastest expansion as AAA titles adopt dynamic audio engines. Foley retains stable margins in premium film despite labor intensity, and field recording grows through nature documentary commissioning and proprietary library licensing to corporate clients.
FCC broadcast standards in the United States and EBU loudness guidelines across Europe enforce strict dynamic range and true-peak limits that shape deliverable specifications and hardware investment. GDPR compliance in European territories affects how client project data and performer recordings circulate across international production networks. Stakeholders must weigh middleware integration capabilities against native engine compatibility as game audio pipelines fragment across proprietary and third-party tools.
Market Dynamics
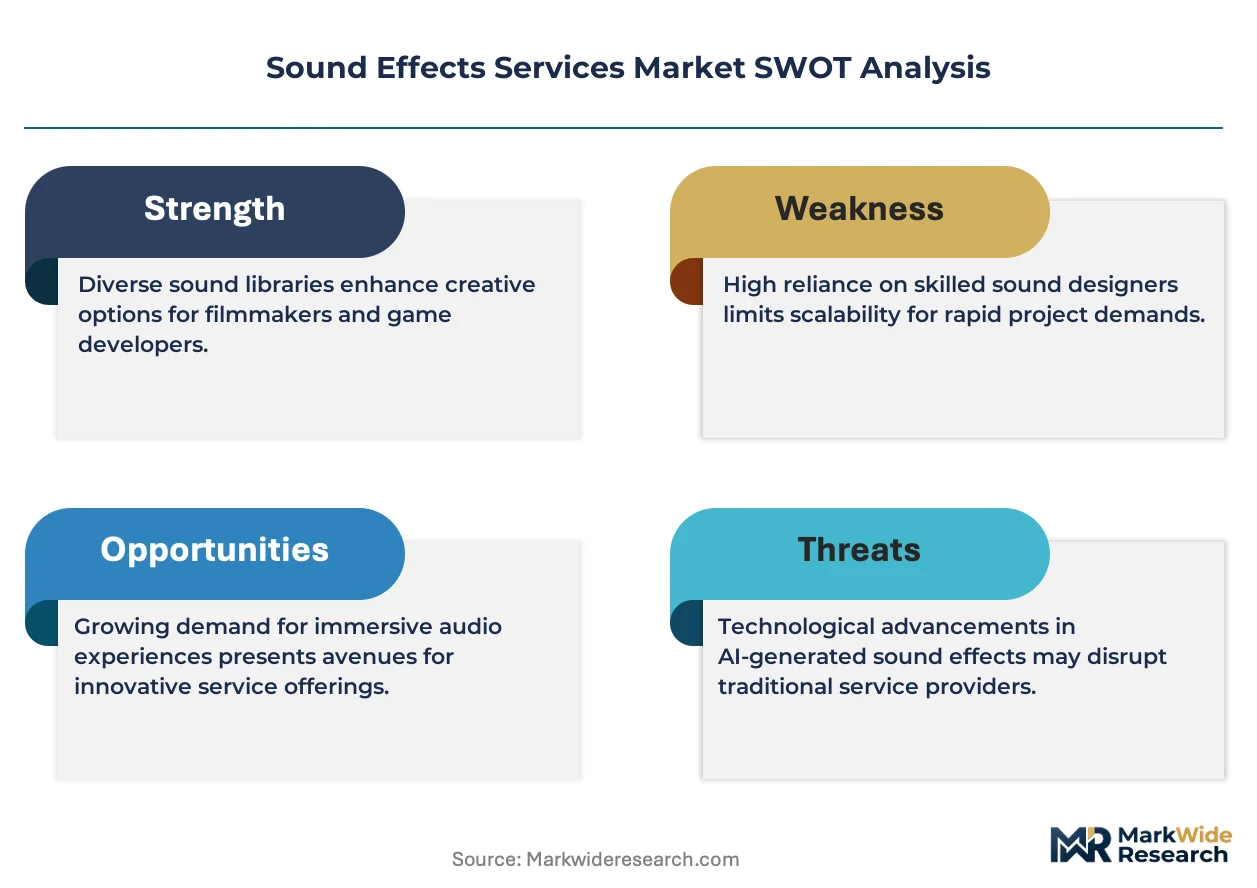
Dolby Atmos and spatial audio standards are collapsing the traditional stereo-to-surround upgrade cycle, forcing facilities to retool for object-based metadata workflows before amortizing prior 5.1 investments.
Growth Catalysts
- Streaming Original Content:Netflix, Amazon Prime Video, and Disney+ commission bespoke sound design for exclusive series, creating sustained demand for premium post-production capacity in Los Angeles and London.
- FCC Broadcast Standards:United States loudness regulations (CALM Act implementation) mandate precise true-peak limiting, driving hardware refresh cycles among broadcast-focused facilities.
- AAA Game Audio Engines:Middleware platforms like Wwise and FMOD enable dynamic audio rendering, expanding contract work for interactive sound design beyond linear media.
Market Restraints
- Specialized Hardware Concentration:Premium monitor controllers and AD/DA conversion from manufacturers clustered in Germany and California create supply vulnerability for smaller facilities.
- Union Labor Cost Structures:Motion Picture Editors Guild rates in Los Angeles inflate theatrical Foley budgets compared to non-union alternatives in emerging production centers.
- Physical Space Requirements:Acoustic isolation standards for theatrical mixing stages limit facility expansion in dense urban cores where real estate costs peak.
Strategic Opportunities
- India Post-Production Hubs:Mumbai and Chennai facilities serve Bollywood and international clients at cost structures 40-60% below Western equivalents, attracting overflow work from streaming platforms.
- Proprietary Library Licensing:Field recording specialists monetize exclusive nature, urban, and mechanical sound collections through subscription models to corporate video departments and game developers.
- Spatial Audio for Music:Apple Music and Tidal spatial audio mandates create crossover demand from music mixing engineers seeking theatrical facility partnerships.
Industry Challenges
- Immersive Audio Talent Pipeline:Object-based mixing expertise remains concentrated among senior theatrical re-recording mixers, constraining facility scaling.
- Middleware Fragmentation:Game audio pipelines split across proprietary engines (Unreal Audio, Unity) and third-party tools, forcing sound designers to maintain multiple certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sound Effects Services Market |
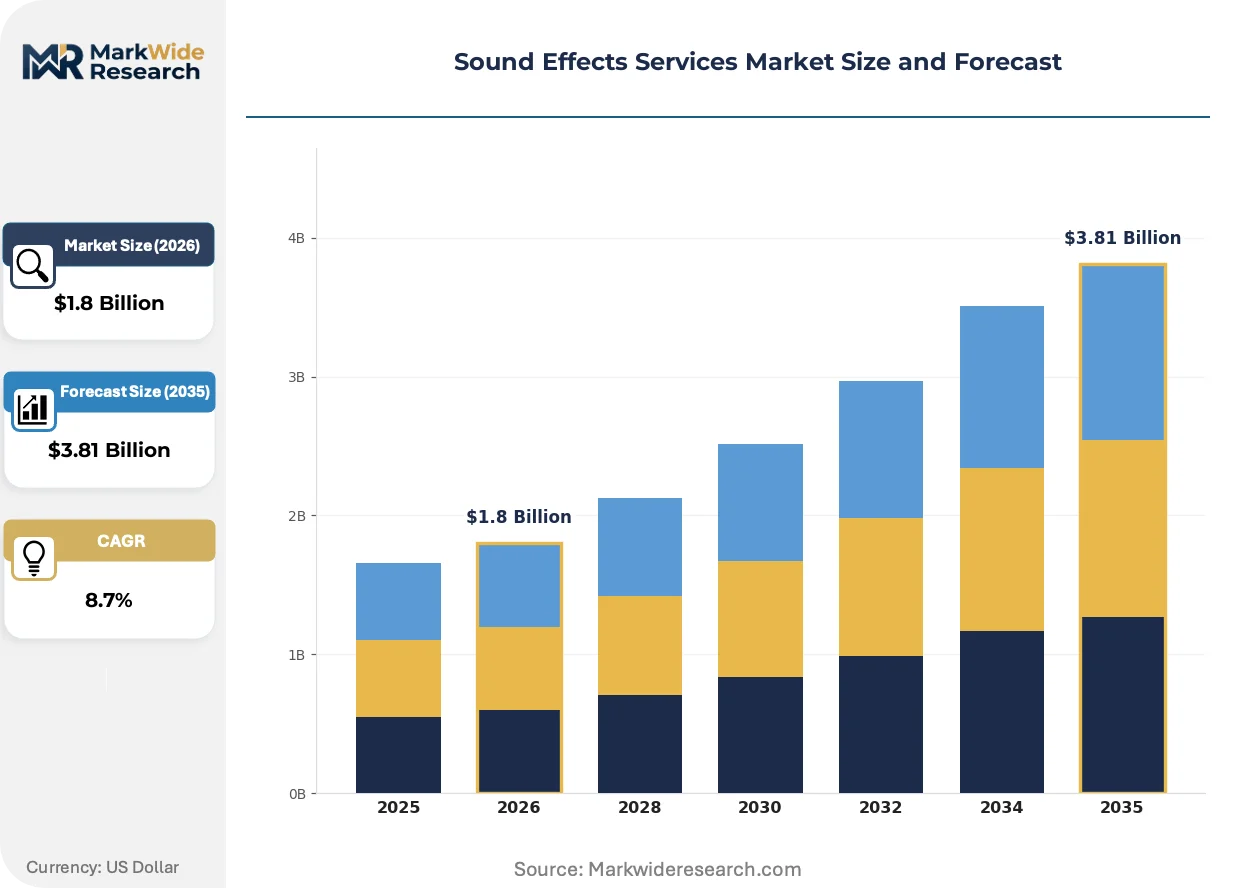
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Post Production, Foley, Sound Design, Field Recording Application: Film, Video Games, Advertising, Television Industry Vertical: Entertainment, Media, Education, Corporate Technology: Digital Audio Workstations, Middleware, Plugin Effects, Recording Equipment |
| Companies Covered | Bang Zoom! Studios, Pinewood Studios Audio, Skywalker Sound, Boom Post, 344 Audio, Formosa Group, Abbey Road Studios, Halo Post Production, Deluxe Media, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sound Effects Services Market Trends and Innovations
Generative audio tools and real-time rendering engines are compressing production timelines while elevating technical complexity requirements for sound designers across film, television, and interactive media.
AI-assisted dialogue cleanup and automated Foley generation is collapsing the cost structure for mid-budget productions, enabling streaming platforms to internalize post-production functions previously outsourced to independent facilities. Independent filmmakers and regional television producers adopt these tools fastest, compressing the addressable market for traditional service providers in the sub-$5 million budget tier.
GDPR compliance protocols in European territories impose strict data residency requirements on cloud-based collaboration platforms, forcing facilities to segment project storage across regional servers. Post-production houses in London and Berlin now maintain separate infrastructure stacks for EU and non-EU clients. Facilities serving international co-productions absorb the highest compliance overhead, passing costs through to producers or accepting margin compression.
Subscription-based asset libraries are displacing perpetual license models for sound effects procurement, altering cash flow patterns for independent creators and small post houses. Splice, Pro Sound Effects, and similar platforms capture recurring revenue from users who previously purchased one-time collections. Freelance sound designers in North America and Western Europe show the fastest migration to subscription tools, prioritizing breadth over ownership in tight-deadline environments.
Sound Effects Services Market Segmentation
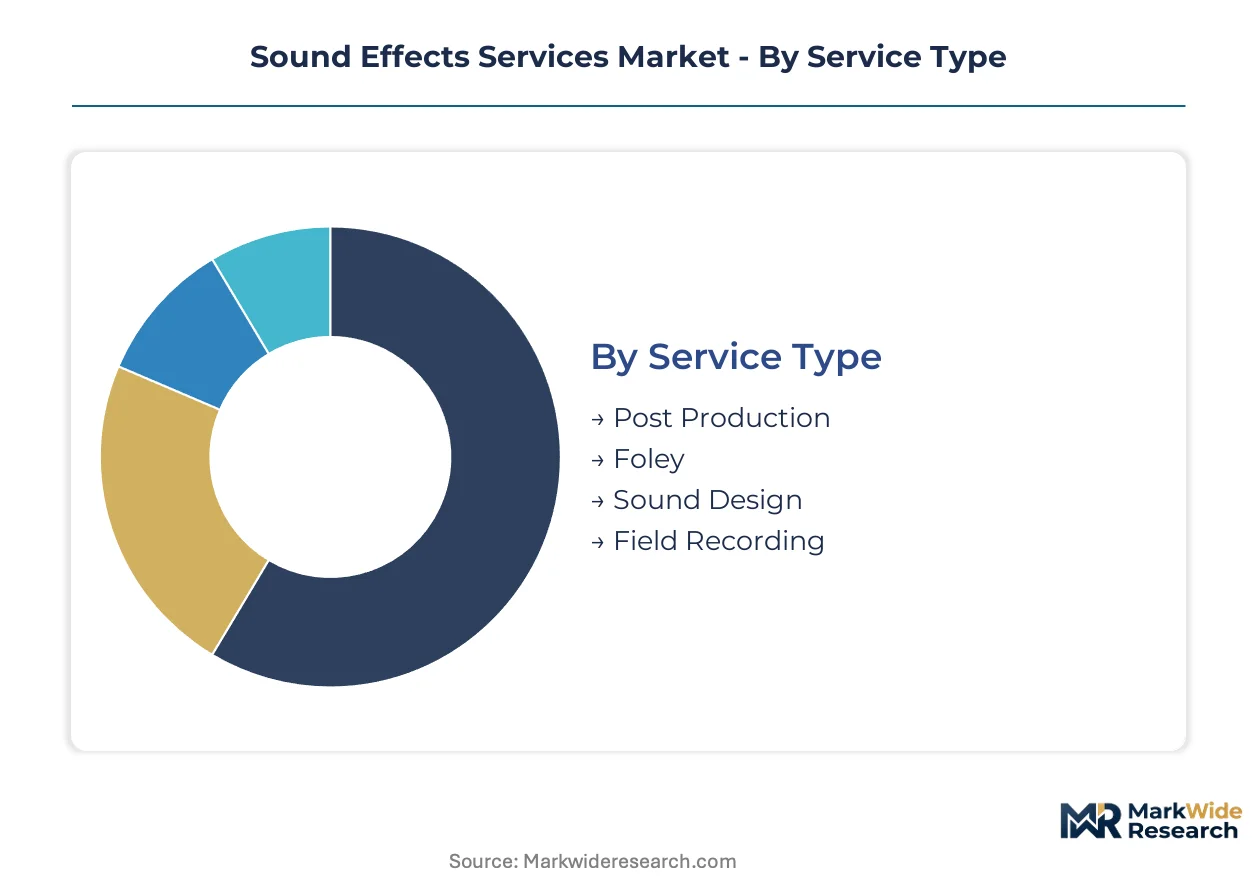
Sound effects services fragment across four dimensions that shape procurement patterns and margin structures. Each segmentation axis reveals distinct competitive dynamics and technical requirements that facilities must address.
Service Type:
Cost tier differentiation separates labor-intensive theatrical work from scalable digital workflows.
- Post Production:Theatrical mixing, dialogue editing, and final deliverable preparation at 48 kHz/24-bit resolution for broadcast and exhibition. Streaming platforms in the United States and United Kingdom sustain premium capacity utilization at Skywalker Sound and Abbey Road Studios.
- Sound Design:Creation of bespoke audio assets through synthesis, sampling, and manipulation for narrative emphasis. AAA game studios in California and Washington state drive demand for adaptive, engine-integrated soundscapes.
- Foley:Performance-based sound replacement capturing footfalls, props, and body movements in specialized recording pits.
- Field Recording:Location capture of environmental, mechanical, and natural sound elements for proprietary library development.
Post production commands the established base. The steepest expansion runs through sound design.
Application:
Volume concentration varies sharply across content formats with diverging technical specifications and budget profiles.
- Film:Theatrical exhibition requiring Dolby Atmos and spatial audio compliance with object-based metadata workflows. Los Angeles and London facilities dominate premium theatrical mixing for major studio releases.
- Video Games:Interactive audio with dynamic rendering through middleware platforms. North American and Japanese publishers drive fastest growth as open-world titles expand ambient sound complexity.
- Television:Episodic content with accelerated turnaround schedules and standardized deliverable packages.
- Advertising:Compressed production windows with regional broadcast compliance requirements.
Film retains the revenue anchor position. Video games gain share fastest as interactive media budgets expand.
Industry Vertical:
Customer type determines contract structure, with entertainment buyers prioritizing creative control and corporate clients emphasizing licensing efficiency.
- Entertainment:Studio and streaming platform commissioning of original content with bespoke asset ownership terms.
- Media:Broadcast network and publisher procurement for news, documentary, and branded content.
- Corporate:Internal video departments and training content producers utilizing subscription library models.
- Education:Institutional licensing for curriculum development and student production facilities.
Entertainment verticals absorb the majority of premium service capacity. Corporate procurement climbs fastest as in-house video production expands.
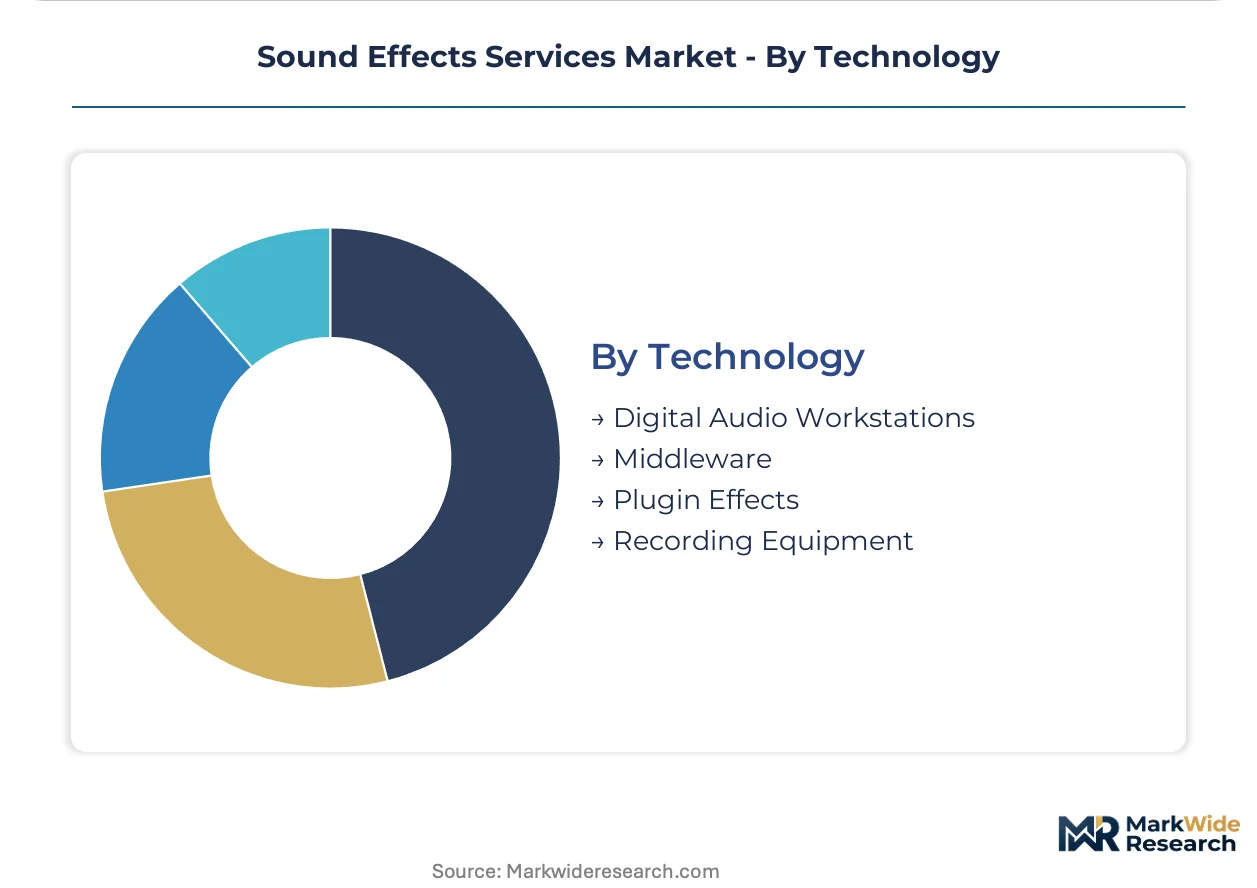
Technology:
Supply concentration in hardware manufacturing shapes facility investment cycles and vendor lock-in patterns.
- Digital Audio Workstations:Core production environments from Avid, Apple, and Steinberg with proprietary session formats. Professional facilities in Germany and California standardize on interoperable workflows.
- Middleware:Audio engines enabling real-time rendering and dynamic mixing for interactive applications.
- Plugin Effects:Software-based processing tools for spatialization, dynamics, and creative sound manipulation.
- Recording Equipment:Microphones, preamplifiers, and conversion hardware with supply chains concentrated in German and Japanese manufacturing.
Digital Audio Workstations anchor facility infrastructure. Middleware adoption accelerates most quickly as game audio pipelines fragment across engine ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadcast standards in the United States anchor the regulatory framework that shapes deliverable specifications across the sound effects services industry. The CALM Act implementation mandates precise true-peak limiting, driving hardware refresh cycles among broadcast-focused facilities nationwide.
United States
Netflix, Amazon Prime Video, and Disney+ commission bespoke sound design for exclusive series, creating sustained demand for premium post-production capacity. FCC loudness regulations enforce strict dynamic range limits that shape facility investment decisions. Los Angeles facilities narrow their capacity gap with London as post-production sound stages multiply across both cities.
United Kingdom
EBU loudness guidelines across Europe enforce dynamic range and true-peak limits that complement domestic procurement patterns. GDPR compliance affects how client project data and performer recordings circulate across international production networks. Abbey Road Studios anchors high-end music and film scoring workflows through its historic London facility.
India
Mumbai and Chennai facilities serve Bollywood and international clients at cost structures significantly below Western equivalents, attracting overflow work from streaming platforms. The country's national media regulator shapes broadcast compliance requirements for domestic content. Post-production hubs in Maharashtra and Tamil Nadu expand capacity to capture regional language film and television demand.
Germany
Premium monitor controllers and AD/DA conversion from manufacturers clustered in Germany and California create supply concentration for European facilities. EBU guidelines align with domestic technical standards for theatrical and broadcast exhibition. Berlin and Munich post-production houses maintain separate infrastructure stacks for EU and non-EU clients to manage data residency requirements.
Japan
AAA game studios in California and Washington state drive fastest growth, while Japanese publishers expand open-world title development requiring complex ambient sound design. METI industrial policy supports creative industries infrastructure investment. Tokyo and Osaka facilities specialize in anime production workflows with distinct technical specifications for domestic and export markets.
Sound Effects Services Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium theatrical mixing and spatial audio expertise clusters among heritage facilities with decades of institutional knowledge, while volume-driven episodic television and corporate content flows to mid-scale operators with standardized workflow templates. Three archetypes dominate: heritage theatrical houses, television-focused boutiques, and game-audio specialists. Competitive moves center on middleware certification partnerships and proprietary library licensing arrangements.
Within the heritage theatrical tier, Skywalker Sound and Abbey Road Studios exemplify facilities where object-based mixing expertise and historic brand equity sustain premium positioning. Boom Post occupies a position among UK television drama specialists, competing through focused Foley and dialogue editing operations. These three anchors demonstrate how geographic clustering in Los Angeles, London, and Marin County reinforces competitive differentiation through proximity to entertainment financing and talent networks.
| Leading Market Players |
|---|
| Bang Zoom! Studios |
| Pinewood Studios Audio |
| Skywalker Sound |
| Boom Post |
| 344 Audio |
| Formosa Group |
| Abbey Road Studios |
| Halo Post Production |
| Deluxe Media |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese manufacturers for premium AD/DA conversion hardware determines both pricing tier spreads and supply chain shape across the sound effects services industry. Facilities absorbing tariff exposure between the United States and these manufacturing clusters face compressed margins that propagate through project-based quotations and subscription library rates.
Pricing Analysis
Geographic price spreads separate Los Angeles theatrical mixing from Mumbai episodic work by margins exceeding forty percent. Three-tier pricing structure across premium theatrical, standard broadcast, and economy digital tiers reflects union labor cost differentials and facility certification levels. Cost compression in mid-budget tiers intensifies as AI-assisted tools enable streaming platforms to internalize post-production functions. Corporate video departments exhibit highest price sensitivity; major studio theatrical releases show lowest.
Supply Chain Analysis
Tariff exposure between the United States and Germany dominates supply chain risk for monitor controller and conversion hardware procurement. Manufacturing concentrates in Germany, Japan, and California, with facilities drawing from specialized microphone producers in Austria and Denmark. Single-source vulnerability runs through proprietary DSP chipsets from discrete semiconductor foundries. Distribution runs through authorized dealer networks serving post-production clusters in Los Angeles, London, and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sound effects services function as a service-attach opportunity where proprietary library licensing and middleware certification subscriptions expand faster than hardware sales. Recurring revenue layers from subscription asset access and ongoing spatial audio format support outpace transactional project fees.
For Market Incumbents: Insulate premium theatrical positioning through exclusive partnerships with streaming platforms for Dolby Atmos original content. Deepen backward integration into field recording operations to control proprietary asset supply. Counter AI-assisted tool substitution by embedding senior mixer expertise into non-displaceable creative judgment workflows. For New Entrants and Emerging Players: Pursue spatial audio certification partnerships with Apple Music and Tidal as the most penetrable entry vector. Target corporate video departments in North America and Western Europe with subscription library models displacing perpetual licenses. Anchor go-to-market strategy through middleware integration credentials for Unity and Unreal Audio pipelines. For Investors and Strategic Acquirers: Heritage theatrical houses with object-based mixing expertise and historic facility assets represent the priority acquisition archetype. Long-term viability hinges on exclusive content volume commitments from streaming platforms and spatial audio mandate adoption across music distribution. Watch middleware certification concentration among senior re-recording mixers as the inflection signal for facility scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Certification Partnership | Wwise and FMOD credentials unlock AAA game audio contract access from California and Washington publishers. |
| Proprietary Library Licensing | Exclusive nature and urban sound collections generate recurring revenue from corporate video and game developer subscriptions. |
| Spatial Audio Infrastructure Investment | Dolby Atmos mixing stage retooling captures theatrical and music crossover demand from Apple Music mandates. |
| Regional Hub Expansion | Mumbai and Chennai facility capacity additions attract Bollywood and international streaming overflow at cost-advantaged structures. |
| GDPR-Compliant Data Architecture | Separate EU and non-EU server stacks enable London and Berlin facilities to serve international co-productions without compliance penalties. |
Research Methodology
Initial hypotheses were tested against primary input from theatrical re-recording mixers, post-production facility executives, streaming platform audio commissioning leads, and game audio directors at AAA studios and refined through secondary validation. Re-recording mixers at heritage facilities in Los Angeles, London, and Marin County provided workflow and capacity utilization perspectives. Secondary sources included FCC broadcast compliance filings, EBU technical documentation, streaming platform content spend disclosures, and middleware certification program records. Bottom-up facility capacity modeling triangulated against top-down streaming content investment estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed service type, application format, industry vertical, and technology platform with regional regulatory cluster overlays. CAGRs derived from facility capacity expansion trajectories, streaming original content commissioning patterns, and interactive audio engine adoption curves. Middleware penetration rates and spatial audio format mandate timing served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in streaming platform content budgets and theatrical exhibition recovery patterns would shift the trajectory. Forecasts reflect documented assumptions regarding Dolby Atmos adoption velocity and union labor rate stability. Material shifts in AI-assisted tool capability or immersive audio talent pipeline expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Social TV Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
In Flight Entertainment Market
Digital Media
Middle East Gaming Market
Digital Media
North America Photographic Services Market
Digital Media
VFX Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Anime Streaming Tool Market
Digital Media
Online Movie Market
Digital Media
Digital Distribution Market
Digital Media
Naruto Around Market
Digital Media
India Webtoons Market
Digital Media
Mobile Entertainment Market
Digital Media
Adult Entertainment Market
Digital Media
Volumetric Video Market