
 Animation Services Market | 2026-2036
Animation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Animation Services Market Insights
Buyer concentration among streaming platforms is pivoting as Netflix, Disney+, and Amazon Prime Video commission original animated content directly from studios rather than licensing finished films. Walt Disney Animation Studios leverages its century-old character library to sustain theatrical-event releases alongside streaming exclusives. Pixar Animation Studios anchors premium family entertainment through technological leadership in ray-traced rendering. DreamWorks Animation competes across both feature film and episodic series production with diversified output deals.
Animation services encompass the design, production, and post-processing of moving image content through frame-by-frame manipulation, digital modeling, or motion capture workflows, typically rendered at 24 frames per second for cinematic distribution. The primary commercial purpose spans entertainment content, brand communication, interactive media, and immersive training simulations. 3D animation commands the largest share of production budgets due to asset reusability across sequels and spin-offs, while motion graphics grows fastest as brands demand short-form video for social platforms. Gaming sector demand concentrates in real-time engine pipelines where Unreal Engine and Unity reduce pre-rendered asset costs.
The Federal Communications Commission shapes content distribution rules for broadcast and streaming animation in the United States, while Japan's Agency for Cultural Affairs administers media arts promotion funds that subsidize domestic studios. The EU Audiovisual Media Services Directive imposes domestic content quotas that streaming services must fill with European animation productions. Stakeholders must monitor how generative AI training data regulations in multiple jurisdictions reshape copyright frameworks for character design and voice synthesis.
Market Dynamics
Streaming platform buyer concentration is restructuring commissioning power, with direct-to-studio production mandates bypassing traditional licensing intermediaries and compressing development-to-delivery cycles.
Growth Catalysts
- Japan's Agency for Cultural Affairs media arts subsidies:Domestic studios receive production grants that lower upfront capital barriers for original IP development.
- Real-time engine pipelines:Unreal Engine and Unity adoption reduces pre-rendered asset costs across gaming and virtual production workflows.
- South Korean tax incentive zones:Government-backed creative industry funds attract international co-production investments into Seoul and Busan clusters.
Market Restraints
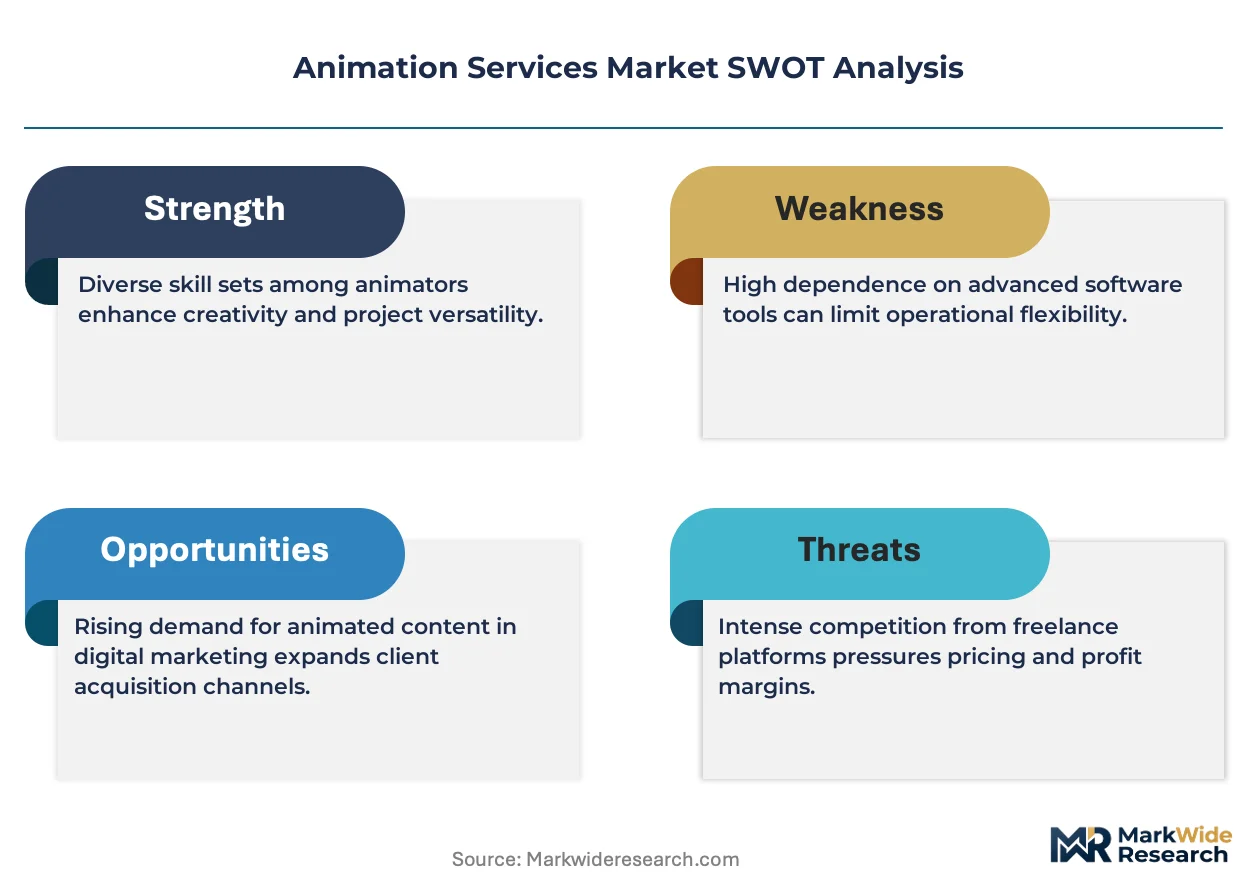
- Render farm energy costs:GPU-intensive ray-traced rendering exposes studios to electricity price volatility in European and North American data center markets.
- Voice synthesis training data restrictions:Emerging copyright frameworks in multiple jurisdictions create legal friction for AI-assisted dubbing and character voice generation.
- Specialized talent scarcity:Technical artists proficient in USD pipeline architecture and real-time shading command premium compensation that inflates fixed production overhead.
Strategic Opportunities
- EU Audiovisual Media Services Directive quotas:Streaming services must fill 30% domestic content requirements with European animation, creating guaranteed demand for regional studios.
- Immersive training simulation:Defense and healthcare sectors commission interactive 3D content for procedural rehearsal beyond entertainment applications.
- Motion capture volume services:Stage-based performance capture facilities in Eastern Europe and Southeast Asia offer cost arbitrage for Western feature productions.
Industry Challenges
- USD pipeline standardization gaps:Interoperability between Maya, Houdini, and Blender workflows creates asset translation friction and version control failures.
- Generative AI output ownership:Unclear copyright assignment for machine-assisted character design and background generation triggers contractual disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation Services Market |
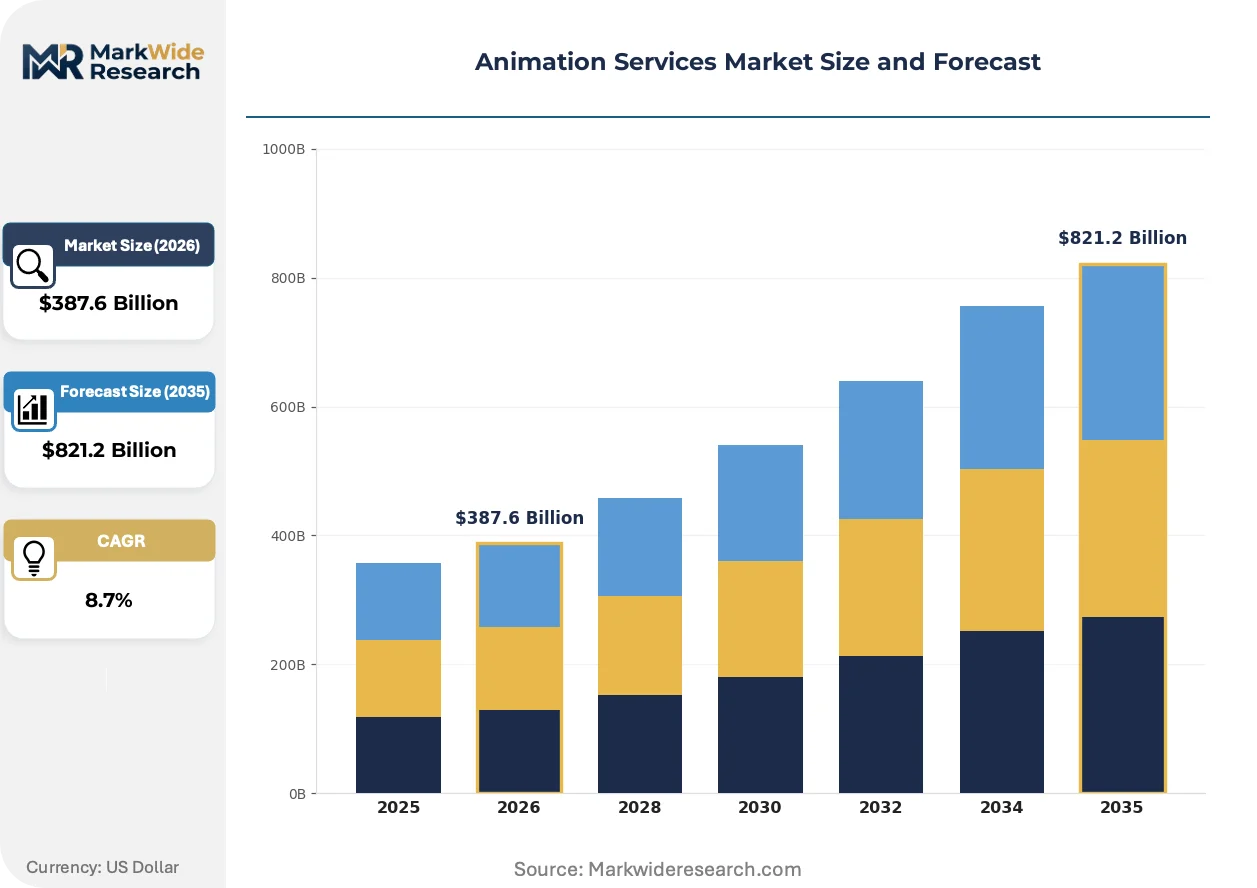
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 2D Animation, 3D Animation, Motion Graphics, Stop Motion Industry Vertical: Entertainment, Advertising, Education, Gaming End User: Enterprises, SMEs, Freelancers, Non-Profits Delivery Mode: Online Streaming, DVD, Television Broadcast, Mobile Apps |
| Companies Covered | Walt Disney Animation Studios, Pixar Animation Studios, DreamWorks Animation, Sony Pictures Animation, Warner Bros. Animation, Illumination Entertainment, Studio Ghibli, Toei Animation, Framestore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation Services Market Trends and Innovations
Production technology is compressing traditional animation pipelines while regulatory pressure on training data reshapes IP frameworks. Demand patterns are fragmenting across platforms, formats, and interactive applications.
AI-assisted inbetweening and automated lip-sync is overtaking manual frame interpolation in television series production. Mid-tier studios adopt these tools to maintain episode throughput against streaming platform delivery mandates. The structural consequence is workforce compression in entry-level cel animation roles.
The EU AI Act's transparency requirements for generative systems impose documentation burdens on studios deploying machine learning for asset generation. Production houses must maintain training data provenance records for regulatory audit. European animation services are responding by segregating AI-assisted and fully manual production lines to preserve copyright clarity.
Commissioning patterns now favor short-form episodic series over feature-length theatrical releases. Streaming platforms order eight-to-twelve episode seasons with rapid renewal decisions, replacing the traditional pilot-to-series development cycle. This behavioral shift is most visible in adult-oriented animation targeting platform subscriber retention metrics.
Animation Services Market Segmentation
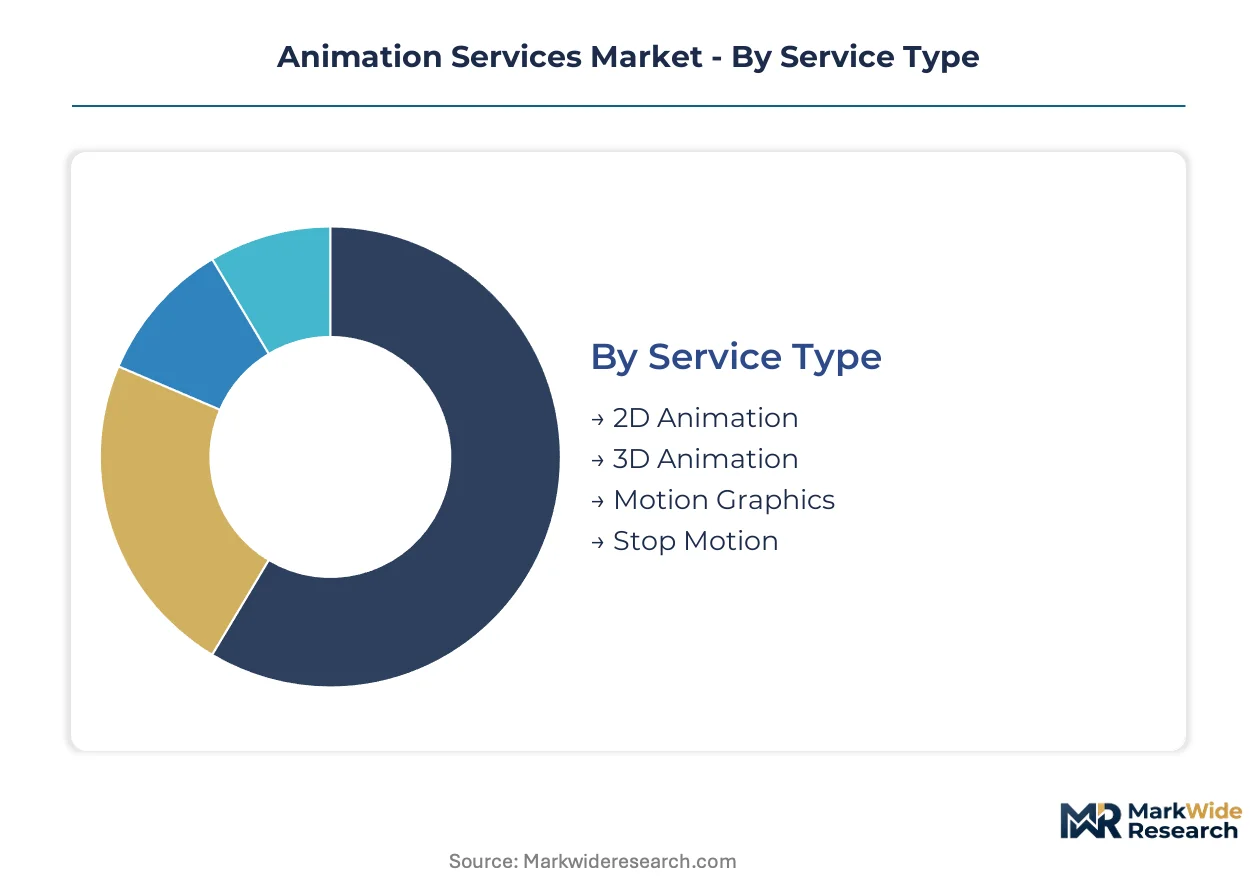
Animation services fragment across technical methodology, commercial application, and distribution infrastructure. Each segmentation axis reveals distinct procurement patterns, capability requirements, and margin structures that shape vendor positioning.
Service Type:
Technical sophistication and asset reusability differentiate production methodologies across studio pipelines.
- 3D Animation:Digital modeling, rigging, and ray-traced rendering workflows generate reusable character assets across sequels and spin-offs. Feature film studios in the United States and Japan concentrate spending here, driven by theatrical distribution economics and merchandise licensing potential.
- 2D Animation:Frame-by-frame illustration and vector-based workflows dominate television series production. South Korean studios and Southeast Asian service providers capture volume demand from streaming platforms seeking cost-efficient episodic output.
- Motion Graphics:Short-form animated content for brand communication and social media advertising.
- Stop Motion:Physical puppet manipulation with incremental frame photography for premium artistic projects.
Mature deployment sits with 3D Animation. Newer deployment is concentrated in Motion Graphics.
Industry Vertical:
End-use application determines production budget scale, timeline flexibility, and IP ownership terms.
- Entertainment:Feature films, series, and streaming content commanding the largest production budgets. Netflix, Disney+, and Amazon Prime Video commissioning patterns favor eight-to-twelve episode seasons with rapid renewal cycles over traditional pilot development.
- Gaming:Real-time engine pipelines using Unreal Engine and Unity for interactive character animation and cinematic cutscenes. Demand concentrates among AAA publishers and mobile game developers in Japan and South Korea.
- Advertising:Brand campaigns and commercial spots requiring rapid turnaround and platform-agnostic formatting.
- Education:Instructional content and training simulations for institutional and corporate learning management systems.
Entertainment absorbs the highest absolute spending. Gaming exhibits the steepest expansion trajectory as real-time rendering bridges production and interactivity.
End User:
Organizational scale dictates procurement modality, from enterprise retained production agreements to individual project-based contracting.
- Enterprises:Major studios, broadcast networks, and platform operators with captive animation divisions or long-term vendor relationships. These buyers negotiate direct-to-studio production mandates that bypass traditional licensing intermediaries.
- SMEs:Mid-tier production houses, regional broadcasters, and specialized content studios accessing animation services through project-based contracts.
- Freelancers:Independent creators and small collectives utilizing cloud-based collaboration tools and asset marketplaces.
- Non-Profits:Educational institutions, museums, and advocacy organizations commissioning animation for public interest communication.
Enterprise procurement dominates premium segment revenue. SME activity is expanding fastest as platform democratization lowers technical barriers.
Delivery Mode:
Distribution infrastructure shapes technical specifications, compression standards, and territorial rights packaging.
- Online Streaming:Platform-exclusive distribution via subscription video-on-demand services. The EU Audiovisual Media Services Directive mandates 30% domestic content quotas that streaming services must fill with European animation productions.
- Television Broadcast:Linear distribution through cable, satellite, and free-to-air networks subject to national content regulations.
- Mobile Apps:Short-form and interactive content distributed through iOS and Android ecosystems.
- DVD:Physical media distribution for collector editions and institutional library acquisition.
Broadcast infrastructure represents mature deployment. Streaming distribution is gaining share fastest as platform subscriber metrics drive commissioning decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streaming platform commissioning power concentrates in three national markets where government incentives and established studio infrastructure intersect. Production investment flows toward jurisdictions offering tax relief, skilled technical labor pools, and co-production treaty access.
United States
Netflix, Disney+, and Amazon Prime Video drive demand through direct-to-studio production mandates. The FCC shapes content distribution rules for broadcast and streaming animation. Los Angeles anchors theatrical-feature production while Atlanta and Vancouver service houses capture episodic series volume.
Japan
Domestic studios receive production grants from the Agency for Cultural Affairs that lower upfront capital barriers for original IP development. METI administers media arts promotion funds subsidizing feature and television animation. Tokyo's Suginami ward hosts dense studio clusters where Toei Animation and Studio Ghibli maintain legacy production facilities.
South Korea
Government-backed creative industry funds attract international co-production investments into Seoul and Busan clusters. Tax incentive zones reduce effective production costs for foreign commissioners. Pangyo Techno Valley houses real-time engine specialists serving gaming and virtual production workflows.
United Kingdom
Framestore and other London-based houses leverage co-production treaties with European and Asian partners. The UK Film Tax Relief provides animation-specific expenditure credits. Manchester and Bristol emerging as secondary hubs for children's television and advertising motion graphics.
France
The EU Audiovisual Media Services Directive mandates 30% domestic content quotas that streaming services must fill with European animation. CNC subsidies support original French-language productions. Paris and Annecy maintain festival-driven development pipelines linking independent creators to platform buyers.
Animation Services Market Competitive Landscape
United States producers anchor the premium theatrical tier; Japanese and South Korean specialists hold episodic and service-based positions. Market structure exhibits concentration at the feature-film apex with fragmentation across television and advertising segments. Three archetypes dominate: legacy studios with century-old character libraries, technology-led render houses, and volume-oriented service providers. Consolidation proceeds through selective acquisition of specialist boutiques; platform direct-commissioning bypasses traditional licensing intermediaries.
Within the legacy studio tier, Walt Disney Animation Studios and Pixar Animation Studios exemplify integrated production-distribution models where century-old character libraries sustain theatrical-event releases alongside streaming exclusives. DreamWorks Animation occupies a diversified position spanning both feature film and episodic series production with output deals across multiple platforms. These entities represent the premium-capability anchor points against which mid-tier houses and regional specialists calibrate service offerings.
| Leading Market Players |
|---|
| Walt Disney Animation Studios |
| Pixar Animation Studios |
| DreamWorks Animation |
| Sony Pictures Animation |
| Warner Bros. Animation |
| Illumination Entertainment |
| Studio Ghibli |
| Toei Animation |
| Framestore |
| Others |
Pricing and Supply Chain Analysis
Render farm energy costs cascade through animation production tiers, with GPU-intensive ray-traced rendering in Los Angeles and Vancouver studios commanding premium pricing that South Korean and Southeast Asian service providers undercut through government-subsidized data center zones.
Pricing Analysis
Volume-driven episodic series production splits from premium theatrical margins, with streaming platform mandates compressing per-minute budgets while feature films retain project-based licensing premiums. Three-tier pricing structure across premium, standard, and economy levels reflects talent density, with technical artists proficient in USD pipelines capturing wage premiums that inflate fixed overhead. Cost compression in mid-tier television animation intensifies because AI-assisted inbetweening tools reduce manual frame labor. SME production houses exhibit highest price sensitivity, while enterprise platform operators with captive animation divisions absorb cost volatility through retained production agreements.
Supply Chain Analysis
EU Audiovisual Media Services Directive domestic-content quotas reshape sourcing patterns, compelling Netflix and Amazon Prime Video to commission from European studios to satisfy 30% local requirements. Production capacity concentrates in the United States, Japan, and South Korea, with raw material dependencies spanning specialized GPU hardware from NVIDIA supply chains, motion capture volume infrastructure, and proprietary rendering software licenses. Single-source vulnerability sits with concentrated talent pools for USD pipeline architecture and real-time shading expertise. Distribution runs through direct-to-studio production mandates that bypass traditional licensing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's training-data provenance requirements erect compliance barriers that favor studios with segregated AI-assisted and manual production lines, creating sustainable moats against undercapitalized competitors.
For Market Incumbents: Extend platform-exclusive output deals to lock streaming renewal cycles before competitor entry, while acquiring motion capture volume facilities in Eastern Europe to arbitrage Western labor costs. Generative AI output ownership disputes threaten IP portfolios; invest in segregated production line certification to preserve copyright clarity under emerging regulatory frameworks.
For New Entrants and Emerging Players: Launch via immersive training simulation contracts targeting defense and healthcare sectors, where procurement sits outside entertainment buyer concentration. Adult-oriented episodic animation for subscriber retention metrics represents the most penetrable white-space, with eight-to-twelve episode season formats enabling rapid portfolio buildout before theatrical-feature competition.
For Investors and Strategic Acquirers: South Korean government creative industry fund announcements are the leading indicator that international co-production investment flows will accelerate. Five-to-ten year viability favors studios with established real-time engine pipelines bridging gaming and virtual production workflows. Monitor EU AI Act enforcement actions as the signal for which European animation houses will capture mandated domestic-content quota demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Production Line Segregation | EU AI Act compliance preserves copyright clarity for character design and voice synthesis assets. |
| Motion Capture Volume Acquisition | Eastern European and Southeast Asian facilities offer cost arbitrage against Los Angeles labor rates. |
| Real-Time Engine Pipeline Investment | Unreal Engine and Unity adoption bridges gaming cinematics with virtual production workflows. |
| EU Domestic Content Quota Positioning | CNC subsidies and 30% streaming mandates guarantee demand for French-language productions. |
| Immersive Simulation Capability Buildout | Defense and healthcare sectors commission interactive 3D content beyond entertainment applications. |
Research Methodology
Multi-period observation of streaming platform commissioning patterns, government subsidy disbursements, and real-time engine adoption rates anchored the trend analysis, supplemented by interviews with animation studio production executives, streaming platform content acquisition leads, technical artists specializing in USD pipelines, and motion capture facility operators. Secondary validation drew from FCC content distribution filings, Japan Agency for Cultural Affairs media arts fund disclosures, EU Audiovisual Media Services Directive implementation reports, and SEC filings from publicly traded entertainment conglomerates. Bottom-up project pipeline enumeration and top-down platform budget allocation estimates were triangulated to cross-verify market sizing.
Segment-weighting across service type, industry vertical, and delivery mode dimensions structured the analytical framework, with 3D animation, 2D animation, and motion graphics production methodologies modeled separately. Gaming sector real-time engine adoption and streaming episodic series renewal velocity served as industry-specific forecast inputs. CAGRs were derived from production volume trajectory analysis combined with per-project budget elasticity estimates across the projection horizon.
The model assumes a particular technology adoption path for AI-assisted rendering tools; alternative pathways for generative AI training data regulation would alter the outlook for workforce compression and copyright assignment clarity. Forecasts reflect assumptions about sustained streaming platform subscriber growth and continued government incentive program stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Asia-Pacific Animation Market
Digital Media
Europe Online Video Platform Market
Digital Media
Music Rights Management Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Global Streaming Media Device Market
Digital Media
Europe Online Gambling Market
Digital Media
Digital Media Market
Digital Media
Naruto Around Market
Digital Media
US Automatic Content Recognition Market
Digital Media
China Webtoons Market
Digital Media
Video Wall Market
Digital Media
Digital Media Production Software Market
Digital Media
Global ACGN Market
Digital Media
Japan Webtoons Market
Digital Media
Online Entertainment Market
Digital Media
Pro AV Market