
 White Pigment Market | 2026-2036
White Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
White Pigment Market Analytics
Asset-light leasing arrangements for titanium dioxide slurry production is fragmenting competitive access to coastal coating clusters. Tronox Limited leverages backward integration into mineral sands to sustain feedstock security across chloride and sulfate routes. KRONOS Worldwide Inc. anchors its position through specialized sulfate-process grades for architectural coatings. BASF SE competes by controlling dispersion technology that reduces customer milling costs.
White pigments are inorganic colorants, primarily titanium dioxide (TiO2) with refractive indices exceeding 2.5, manufactured through chloride or sulfate processes to deliver opacity, brightness, and UV stability in finished goods. Their primary commercial purpose centers on scattering visible light and protecting substrates from photodegradation across protective, decorative, and functional applications. Titanium dioxide dominates value pools due to its unmatched hiding power, while zinc oxide captures growing share in cosmetic and pharmaceutical formulations where photocatalytic safety requirements are tightening. The coatings vertical remains the largest demand sink, though plastics compounding for masterbatch applications is expanding fastest as thin-wall packaging specifications multiply.
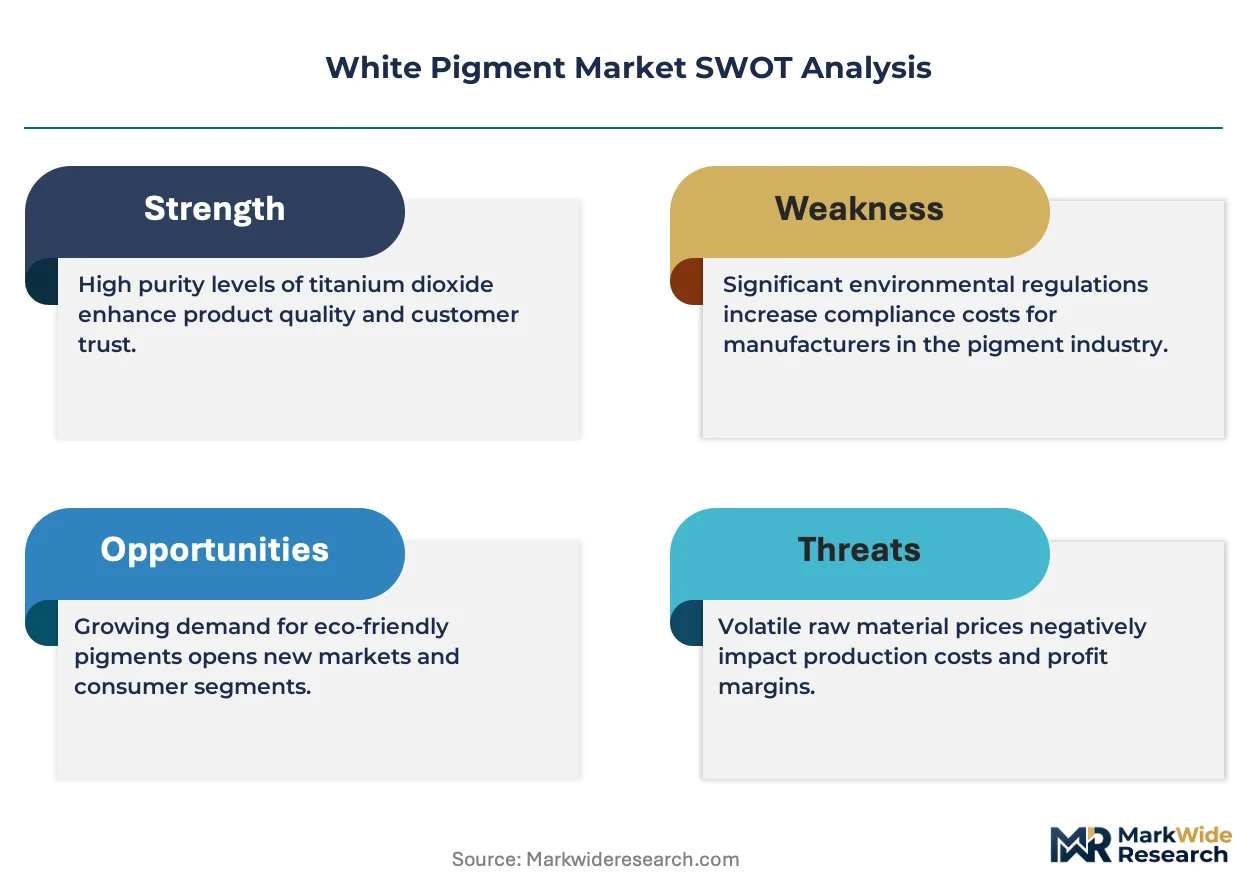
EPA emission standards for titanium dioxide manufacturing shape capital allocation toward pollution control and process closure in US production corridors. REACH registration requirements and the EU F-Gas Regulation constrain chloride-route expansion and favor sulfate-process investments with lower fluorinated byproduct profiles. China's MEE enforcement of dual carbon goals is redirecting capacity toward cleaner chloride technology. Stakeholders must monitor regulatory divergence between jurisdictions to align process technology bets with where compliance costs will concentrate.
Market Dynamics
Chloride-route titanium dioxide capacity is concentrating in coastal zones with integrated mineral sands access, compressing sulfate-process margins in landlocked production corridors. Feedstock security now dictates competitive positioning more than pigment quality differentiation.
Growth Catalysts
- Automotive refinish specification tightening:OEM certification standards for high-durability coatings are mandating rutile-grade TiO2 with superior chalk resistance. Refinish shops in Germany and Japan are upgrading pigment specifications to meet warranty compliance.
- REACH F-Gas Regulation:The EU constraint on fluorinated byproducts from chloride production is accelerating sulfate-process retrofits with closed-loop acid recovery. This regulatory friction is redirecting investment toward cleaner sulfate technology in European production corridors.
- India plastics compounding scale-up:Domestic masterbatch production for flexible packaging converters is absorbing sulfate-grade TiO2 volumes previously exported. BIS certification requirements for food-contact plastics are tightening pigment purity standards.
Market Restraints
- Feedstock concentration risk:Chloride-route ilmenite and rutile supply concentrates with Australian and South African mineral sands operators. Geographic concentration creates vulnerability to shipping disruptions through the Cape of Good Hope.
- Sulfate-process waste acid liability:Ferrous sulfate byproduct disposal costs in landlocked Chinese and European production zones are eroding process economics. Environmental remediation bonds now exceed 15% of replacement capital for legacy sulfate facilities.
- Zinc oxide substitution in cosmetics:Photocatalytic safety requirements under FDA and EMA guidance are displacing nano-TiO2 in sun care and pharmaceutical applications. Zinc oxide with surface coatings is capturing formulation share where skin penetration concerns dominate.
Strategic Opportunities
- Indonesia packaging converter build-out:Domestic thin-wall injection molding for food service is scaling without established masterbatch supply chains. Local TiO2 slurry production with asset-light leasing could capture converter procurement before incumbent pigment houses establish distribution.
- China dual carbon protocol alignment:MEE enforcement of carbon intensity targets is creating preferential permitting for chloride-route capacity with integrated renewable power. Cleaner production credentials are becoming a procurement filter for multinational coatings buyers.
- Digital color matching platforms:Cloud-based spectrophotometry and AI-driven formulation tools are compressing technical service requirements. Pigment suppliers with integrated digital tools can reduce customer laboratory staffing and accelerate specification approval.
Industry Challenges
- Process chemistry expertise scarcity:Chloride-route operations require specialized metallurgical and corrosion engineering skills that aging workforces in US and European production corridors no longer possess. University programs have shifted toward materials science, neglecting extractive process fundamentals.
- Legacy sulfate facility environmental compliance:Retrofitting 1970s-era plants with MEE-equivalent emission controls demands capital allocation that competes with greenfield chloride investments. Asset retirement obligations are accelerating in jurisdictions with strict soil and groundwater liability frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Pigment Market |
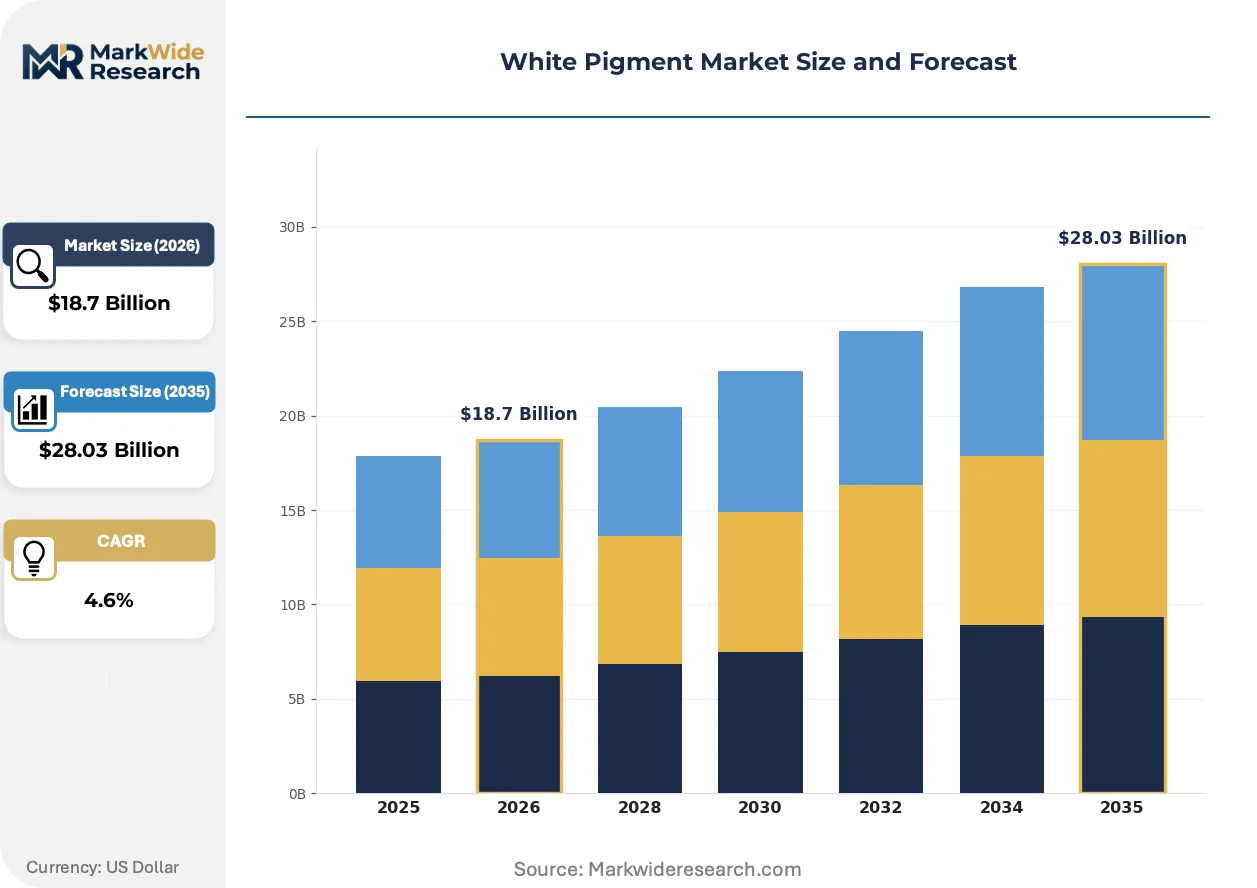
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Zinc Oxide, Lithopone, Calcium Carbonate Industry Vertical: Coatings, Plastics, Paper, Cosmetics Form: Powder, Liquid, Paste, Emulsion End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | The Chemours Company, Tronox Limited, KRONOS Worldwide Inc., Venator Materials PLC, BASF SE, LANXESS, Sudarshan Chemical Industries Limited, Cathay Industries Group, Clariant International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Pigment Market Evolving Landscape
Digital tools are compressing technical service models while regulatory divergence between chloride and sulfate process jurisdictions is fragmenting capacity investment. Feedstock integration strategies are separating sustainable suppliers from merchant market dependents.
Surface-engineered nano-TiO2 with photocatalytic self-cleaning functionality is virtualizing maintenance cost structures in architectural coatings. Building facade applicators in Japan and South Korea are specifying these grades for high-rise structures where access for cleaning is prohibitively expensive. The technology is virtualizing traditional five-year recoating cycles into fifteen-year maintenance intervals, compressing volume demand per square meter of coated surface.
China's MEE enforcement of dual carbon goals is redirecting permitting priority toward chloride-route capacity with captive renewable power integration. Sulfate-process expansions in inland provinces face extended environmental impact review timelines. Domestic coatings manufacturers are responding by consolidating procurement contracts with chloride-route suppliers holding verified carbon intensity certifications.
Masterbatch compounders are consolidating procurement through direct mill relationships, bypassing traditional pigment distribution channels. Large European and North American plastics processors are negotiating annual volume contracts with sulfate-grade specialists for just-in-time slurry delivery. This channel compression is most visible in Germany's automotive interior supply chain, where compounders demand technical service co-location at their production facilities.
White Pigment Market Segmentation
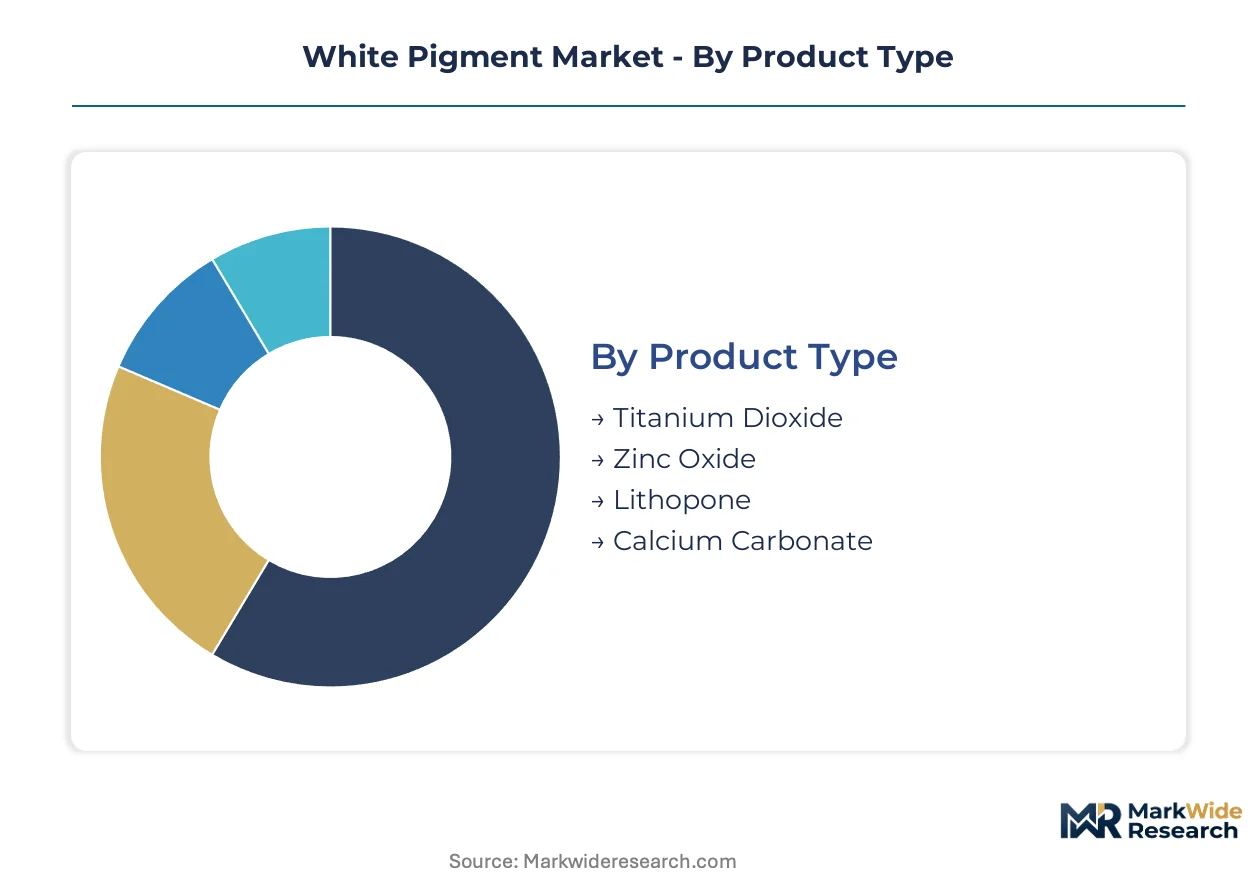
White pigment procurement patterns diverge sharply across product chemistries and downstream applications. Formulation requirements from coatings OEMs versus cosmetics compounders create distinct specification hierarchies that reshape supplier priorities.
Product Type:
Use-case spectrum spans industrial opacity demands to pharmaceutical photocatalytic safety requirements.
- Titanium Dioxide:Rutile and anatase crystalline forms manufactured via chloride or sulfate processes deliver refractive indices above 2.5 for unmatched hiding power. Automotive refinish shops in Germany and Japan are mandating rutile grades with superior chalk resistance under tightening OEM certification standards.
- Zinc Oxide:Surface-coated variants with controlled particle size distribution address photocatalytic safety concerns in dermal applications. FDA and EMA guidance on skin penetration is accelerating displacement of nano-TiO2 in sun care and pharmaceutical formulations where zinc oxide now dominates.
- Lithopone:Co-precipitated zinc sulfide and barium sulfate composite provides cost-effective opacity in interior architectural coatings.
- Calcium Carbonate:Ground and precipitated grades serve as extenders and TiO2 spacers in paper coating and filler applications.
The dominant share belongs to Titanium Dioxide, while Zinc Oxide is closing the gap fastest.
Industry Vertical:
Customer technical sophistication ranges from specification-driven OEMs to price-sensitive commodity buyers.
- Coatings:Protective and decorative formulations demand TiO2 with precise dispersibility and durability profiles. Automotive refinish specification tightening in Germany and Japan is compressing supply chains toward certified rutile-grade suppliers.
- Plastics:Masterbatch compounding for thin-wall packaging requires sulfate-grade TiO2 with controlled heat stability. India's domestic plastics compounding scale-up is absorbing sulfate-grade volumes previously exported.
- Paper:Coating and filler applications prioritize brightness and opacity at lowest cost per unit area.
- Cosmetics:Photocatalytic safety requirements under FDA guidance are reshaping pigment selection toward surface-coated zinc oxide.
Coatings retains the largest value pool, though Plastics is expanding most quickly as packaging specifications multiply.
Form:
Supply chain economics favor fluid delivery where customer milling infrastructure is limited.
- Powder:Standard dry pigment requiring customer-side dispersion equipment and milling capacity.
- Liquid:Pre-dispersed slurry forms reduce customer processing costs and accelerate specification approval.
- Paste:High-solids concentrates for specific coating and ink applications.
- Emulsion:Water-based dispersions for latex systems and environmentally formulated products.
Powder dominates volume shipments, while Liquid is gaining share fastest among coastal coating clusters.
End User:
Channel structure fragments between direct mill relationships and traditional distribution networks.
- Manufacturers:Coatings and plastics producers with in-house formulation laboratories and volume procurement leverage.
- Contractors:Application specialists in automotive refinish and architectural sectors with specification influence.
- Retailers:Consumer-facing channels for DIY coatings and cosmetic products.
- Distributors:Traditional pigment merchants facing compression from direct mill contracting.
Manufacturers command the dominant procurement volume, while Distributors are losing ground fastest to direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive refinish shops in Germany and Japan concentrate procurement of certified rutile-grade titanium dioxide, while plastics compounders in India and packaging converters in Indonesia drive sulfate-grade absorption.
China
Coatings manufacturers in Shanghai and Guangdong provinces are consolidating procurement contracts with chloride-route suppliers holding verified carbon intensity certifications. MEE enforcement of dual carbon goals redirects permitting priority toward capacity with captive renewable power integration. Sulfate-process expansions in inland provinces face extended environmental impact review timelines.
United States
EPA emission standards shape capital allocation toward pollution control in Gulf Coast production corridors. Chloride-route operations require specialized metallurgical engineering skills that aging workforces in Texas and Louisiana no longer possess. Houston-area pigment terminals face feedstock security pressures from Cape of Good Hope shipping disruptions.
Germany
REACH F-Gas Regulation constraints on fluorinated byproducts accelerate sulfate-process retrofits with closed-loop acid recovery. Automotive OEM certification standards mandate rutile-grade TiO2 with superior chalk resistance for warranty compliance. Masterbatch compounders in Bavaria negotiate direct mill relationships bypassing traditional distribution channels.
India
Domestic plastics compounding scales to serve flexible packaging converters in Maharashtra and Gujarat. BIS certification requirements for food-contact plastics tighten pigment purity standards. Sulfate-grade TiO2 volumes previously exported now absorb into local masterbatch production for thin-wall specifications.
Indonesia
Domestic thin-wall injection molding for food service scales without established masterbatch supply chains. Local TiO2 slurry production with asset-light leasing captures converter procurement before incumbent pigment houses establish distribution. Jakarta and Surabaya coating clusters fragment competitive access through coastal terminal arrangements.
White Pigment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structures around backward-integrated mineral sands operators and dispersion-technology specialists. Three archetypes dominate: feedstock-secure chloride-route producers, sulfate-process grade specialists, and digital-integrated service providers. Capacity expansion and direct mill contracting represent the dominant competitive moves.
Within the feedstock-secure tier, Tronox Limited and The Chemours Company exemplify backward integration strategies. KRONOS Worldwide Inc. occupies a position among sulfate-process specialists serving architectural coatings demand. These three entities anchor the competitive structure while specialty chemical houses including BASF SE and Clariant International AG represent dispersion-technology and surface-engineering capabilities. The archetype mix reflects divergent bets on process chemistry, regulatory compliance positioning, and customer technical service models.
| Leading Market Players |
|---|
| The Chemours Company |
| Tronox Limited |
| KRONOS Worldwide Inc. |
| Venator Materials PLC |
| BASF SE |
| LANXESS |
| Sudarshan Chemical Industries Limited |
| Cathay Industries Group |
| Clariant International AG |
| Others |
Value Network & Pricing Analysis
Cape of Good Hope shipping disruptions determine both the premium commanded by chloride-route rutile grades and the geographic clustering of coastal slurry terminals. Feedstock security premiums now separate procurement tiers more sharply than pigment quality differentials alone.
Pricing Analysis
Cost-plus contracts indexed to Australian mineral sands benchmarks dominate long-term chloride-route procurement. Three-tier pricing structure across premium rutile-certified, standard sulfate-grade, and economy lithopone tiers reflects certification status and feedstock integration depth. Cost compression in standard sulfate grades intensifies because ferrous sulfate disposal liabilities now exceed 15% of replacement capital. Commodity buyers in interior architectural coatings exhibit highest price sensitivity, while automotive refinish shops in Germany and Japan show lowest sensitivity due to warranty compliance mandates.
Supply Chain Analysis
Contract manufacturing concentration rests with Tronox Limited and The Chemours Company for chloride-route capacity, while KRONOS Worldwide Inc. anchors sulfate-process supply. Geographic supply concentrates in Australia, South Africa, and China for mineral sands feedstock, with downstream processing clustering in Texas, Shanghai, and Hamburg. Raw material dependencies draw from ilmenite, rutile, and synthetic titanium slag. Single-source vulnerability runs through Cape of Good Hope shipping lanes for Australian feedstock. Distribution runs through direct mill relationships that bypass traditional pigment merchants, particularly in Germany's automotive interior supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against zinc oxide displacement in cosmetic and pharmaceutical applications where photocatalytic safety requirements tighten.
For Market Incumbents: Insulate rutile-grade positioning through backward integration into mineral sands and MEE-aligned carbon intensity certifications for China procurement. Chloride-route producers must secure captive renewable power integration before sulfate-process retrofits capture regulatory preference. Feedstock security, not quality differentiation, now anchors margin defense. For New Entrants and Emerging Players: Indonesia's thin-wall packaging converter build-out represents the most penetrable entry point, with local slurry production via asset-light leasing capturing procurement before incumbents establish distribution. India's domestic masterbatch scaling offers second-mover absorption of sulfate-grade volumes. Technical service co-location at compounder facilities provides the essential go-to-market angle. For Investors and Strategic Acquirers: REACH F-Gas Regulation reshapes the acquisition landscape toward sulfate-process assets with closed-loop acid recovery in European corridors. Long-term viability favors feedstock-integrated chloride-route capacity with verified carbon credentials over merchant-market-dependent sulfate specialists. Watch MEE enforcement intensity in China coastal provinces as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sands | Tronox Limited's captive feedstock security insulates against Cape route disruptions. |
| Closed-Loop Acid Recovery Retrofit | Sulfate-process investments with REACH F-Gas alignment capture European regulatory preference. |
| Asset-Light Slurry Leasing | Coastal terminal arrangements fragment competitive access in Indonesia packaging clusters. |
| Carbon Intensity Certification | MEE-aligned credentials become procurement filters for multinational coatings buyers. |
| Direct Mill Relationship Consolidation | Bavarian masterbatch compounders bypass traditional distribution channels for just-in-time delivery. |
Research Methodology
A spread of perspectives from chloride-route plant managers, coatings procurement leads at automotive OEMs, masterbatch compounders in India, mineral sands trading desks, and technical R&D directors converged on the working assumptions. Secondary validation drew from customs trade data, SEC 10-K filings, MEE enforcement bulletins, and REACH registration databases. Bottom-up volume estimates triangulated against top-down value projections across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use vertical, delivery form, and regional production hub cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Key forecast inputs incorporated BIS certification timelines for Indian food-contact plastics and EPA emission standard compliance costs for US Gulf Coast facilities.
Macroeconomic conditions sit as an overlay; deviation in construction spending patterns and automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock shipping lane stability. Quarterly review of MEE carbon intensity audit results and Cape of Good Hope freight rate indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Color Retention Agents Market