
 North America B2B Air Care Market | 2026-2036
North America B2B Air Care Market Size, Share, and Industry Trends Forecast 2026-2036
North America B2B Air Care Market Analytics
Buyer fragmentation across boutique hotel chains and co-working operators is repositioning procurement patterns toward flexible service contracts rather than bulk equipment purchases. Procter & Gamble leverages its institutional supply agreements to sustain shelf presence in major hospitality distributors. S.C. Johnson & Son Inc. anchors the commercial odor control segment through specialized formulations for healthcare and fitness environments. Henkel AG & Co. KGaA competes on industrial-grade applications with concentrated chemistry for manufacturing facilities.
North America B2B air care encompasses electrically powered and passive systems designed to modify indoor atmospheric conditions through particulate filtration, volatile compound neutralization, or moisture regulation, typically operating at airflow rates between 100 and 1,200 cubic feet per minute for commercial deployments. These systems serve primarily to maintain occupant comfort, protect equipment integrity, and ensure compliance with workplace air quality standards across leased and owned commercial properties. Air fresheners lead product type revenue due to low capital requirements and recurring consumable purchases, while IoT Integration represents the fastest-expanding technology dimension as facility managers seek remote monitoring capabilities. HEPA Filters occupy the mature core of the technology stack with stable replacement cycles, whereas activated carbon applications concentrate margin pools in industrial odor control where specification requirements command premium pricing.
The U.S. EPA regulates volatile organic compound content through 40 CFR Part 59, while California Air Resources Board rules impose stricter formulation ceilings than federal baselines, and OSHA indoor air quality guidelines shape employer liability exposure across commercial workplaces. These frameworks collectively push manufacturers toward low-emission chemistries and documented compliance certifications for institutional buyers. Stakeholders must monitor pending state-level amendments to VOC thresholds and assess whether connected system investments align with evolving facility management procurement criteria.
Market Dynamics
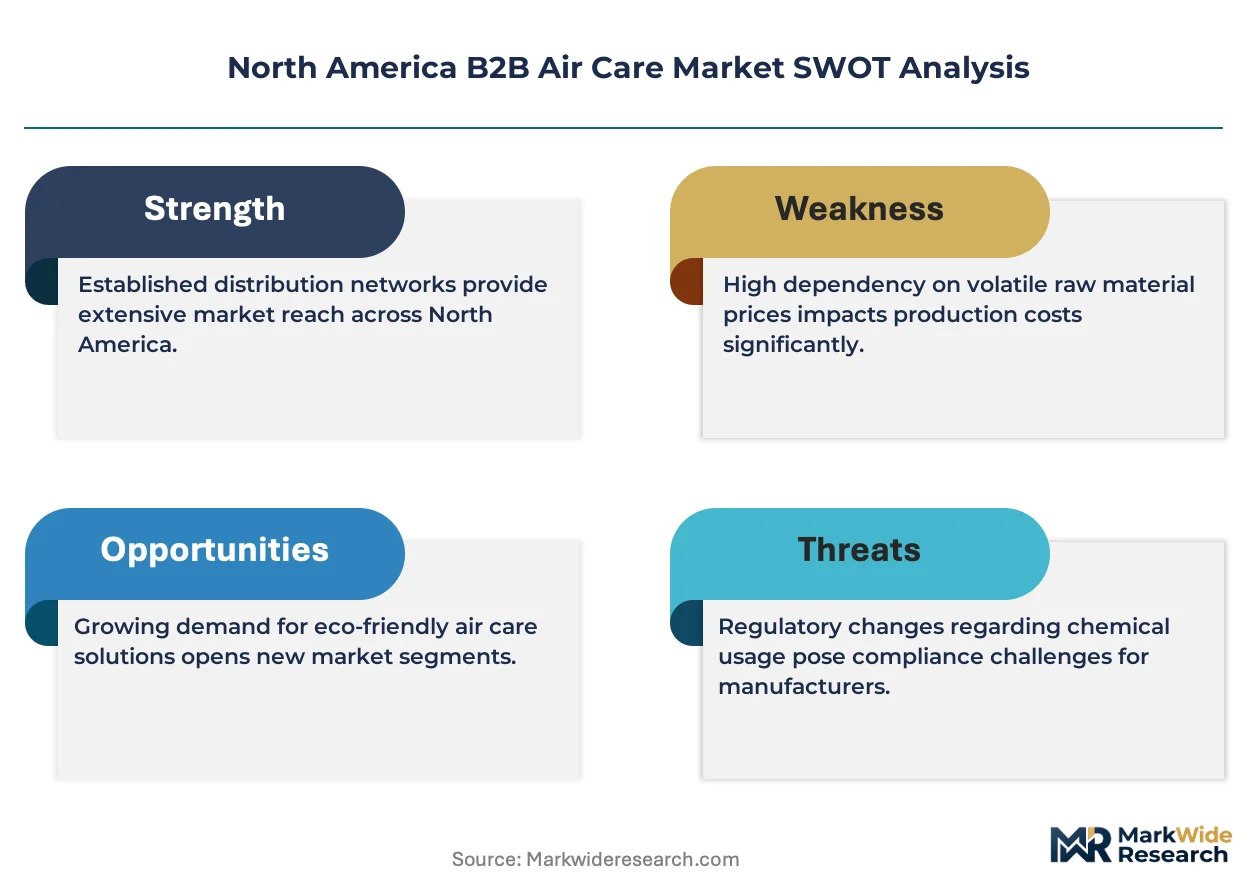
Connected air care systems are restructuring procurement relationships across North American commercial real estate, as facility managers demand remote diagnostics and predictive maintenance capabilities that compress traditional equipment replacement cycles.
Growth Catalysts
- California Air Resources Board VOC ceilings:Stricter state-level formulation limits are accelerating R&D investment in low-emission chemistries that qualify for premium institutional contracts.
- Hospitality sector sensor deployment:Hotel operators are integrating air quality monitoring into guest experience management platforms, creating recurring revenue streams for system providers.
- Sun Belt construction velocity:Warehouse and hotel development across Texas, Florida, and Arizona is generating concentrated bulk orders for humidity control and odor management infrastructure.
Market Restraints
- Petrochemical feedstock volatility:Concentrated supply of fragrance compounds and polymer housings exposes manufacturers to margin compression during energy price spikes.
- Canadian provincial regulatory fragmentation:Divergent VOC thresholds between Ontario, Quebec, and British Columbia complicate cross-border product standardization for multi-location buyers.
- Activated carbon sourcing concentration:Dependence on specialized carbon suppliers for industrial odor control creates specification risk during supply disruptions.
Strategic Opportunities
- Mexico manufacturing corridor expansion:Nearshoring of automotive and electronics production is creating demand for industrial-grade air filtration in Baja California and Querétaro.
- U.S. EPA Safer Choice certification:Federal procurement preference for certified products opens institutional channels for compliant formulation providers.
- IoT-HEPA convergence:Integration of particle sensors with filter replacement algorithms enables subscription-based service models for multi-site facility operators.
Industry Challenges
- Connected system cybersecurity protocols:Facility managers lack standardized frameworks for securing networked air quality devices against breach risks.
- Cross-jurisdictional compliance documentation:Suppliers must maintain parallel certification tracks for OSHA workplace guidelines, EPA emission rules, and state-level chemical registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America B2B Air Care Market |
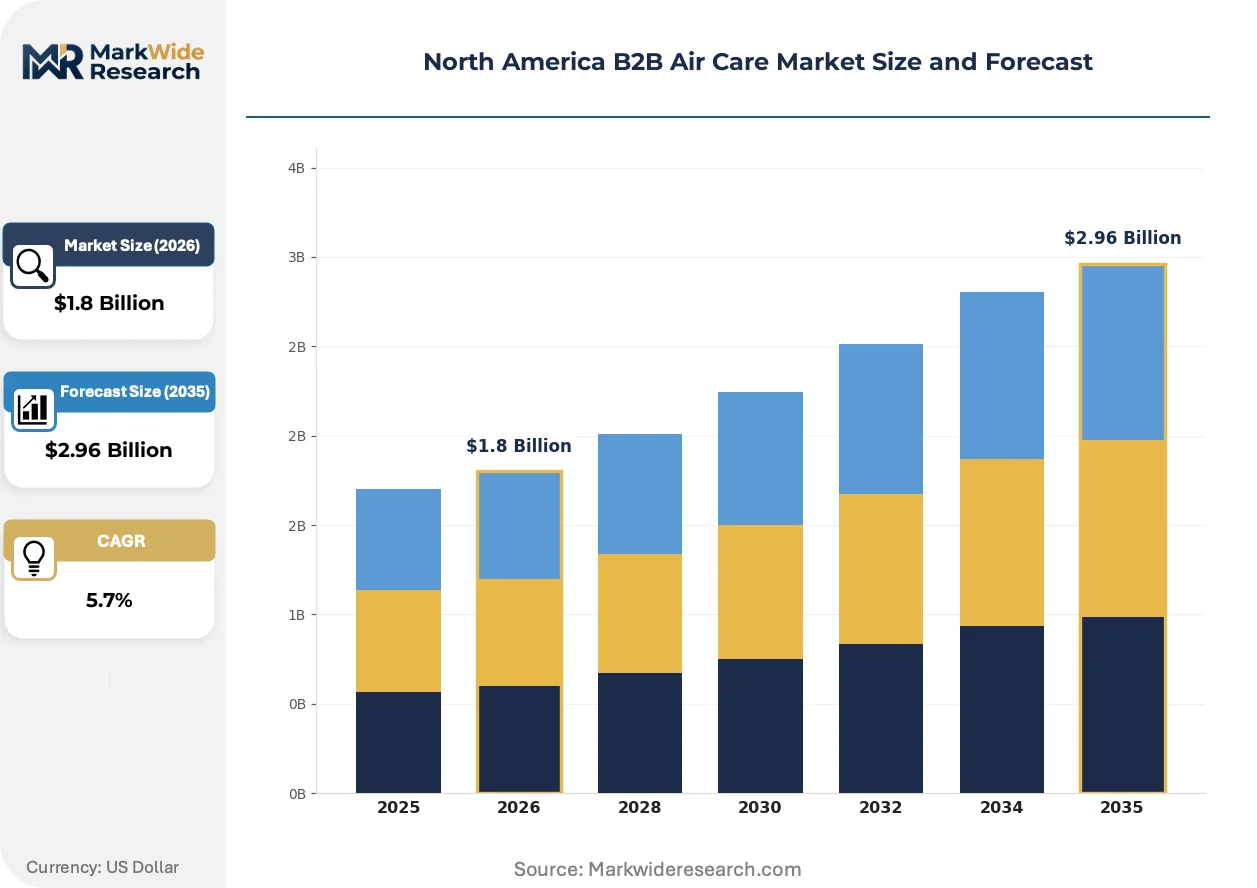
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Air Fresheners, Humidifiers, Dehumidifiers End User: Commercial Spaces, Industrial Facilities, Hospitality, Healthcare Application: Indoor Air Quality, Odor Control, Humidity Control, Air Filtration Technology: HEPA Filters, Activated Carbon, UV-C Light, IoT Integration |
| Companies Covered | Rexair LLC, Procter & Gamble, S.C. Johnson & Son Inc., Henkel AG & Co. KGaA, Reckitt Benckiser Group PLC, CAR-FRESHNER, BEAUMONT PRODUCTS, INC., WD-40 Company, Air Delights, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America B2B Air Care Market Evolving Landscape
Electrochemical sensing and machine learning diagnostics are redefining how commercial buildings manage atmospheric conditions, shifting value capture from hardware sales toward continuous monitoring services.
IoT-enabled air quality monitors are overtaking standalone equipment in new commercial construction. These systems transmit particulate and VOC data to centralized building management platforms. Property technology teams in Class A office towers and extended-stay hotel chains are prioritizing sensor density over passive dispenser coverage. The shift is compressing capital equipment margins while expanding recurring software revenue pools.
The U.S. EPA Safer Choice program is tightening eligibility criteria for commercial cleaning and air care products. Formulators must now document full supply chain transparency for fragrance ingredients. Healthcare and education procurement officers are restricting vendor lists to certified suppliers, forcing reformulation investments among legacy chemical providers.
Service unbundling is fragmenting traditional distributor relationships. Boutique hotel chains and co-working operators now contract directly with regional service firms for equipment maintenance and consumable replenishment. This bypasses national distribution networks that historically controlled shelf placement. The pattern is most pronounced in secondary U.S. metropolitan markets where local facility management specialists have built sensor installation capabilities.
North America B2B Air Care Market Segmentation
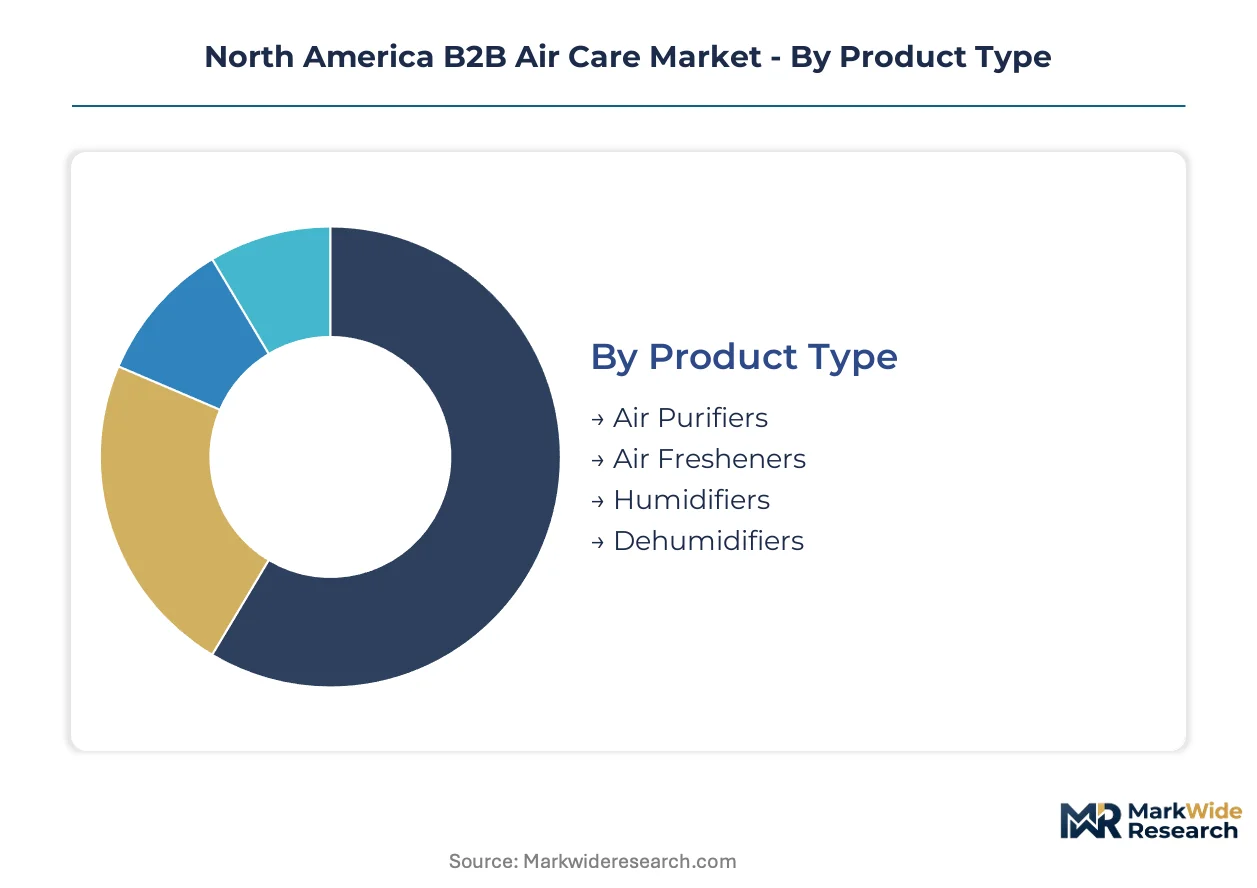
North America B2B air care procurement divides across four distinct category hierarchies, each carrying unique compliance burdens that shape vendor qualification and pricing power. Facility managers navigate overlapping certification requirements from EPA, OSHA, and state-level regulators when matching product specifications to building codes.
Product Type:
EPA Safer Choice certification and California Air Resources Board VOC thresholds apply differentially across equipment categories, with electrically powered systems facing additional FCC emissions testing for connected variants.
- Air Purifiers:Multi-stage filtration systems incorporating HEPA media and pre-filters, typically specified at 300-600 CFM for open commercial floorplates. Demand concentrates in Sun Belt office construction across Texas and Florida, where new HVAC infrastructure creates bundled procurement opportunities with humidity control systems.
- Air Fresheners:Passive dispensers and aerosol systems delivering fragrance compounds at controlled release rates, commanding recurring consumable revenue streams. Procurement patterns favor flexible service contracts over equipment purchases among boutique hotel chains and co-working operators seeking minimal capital deployment.
- Humidifiers:Evaporative and ultrasonic systems maintaining 40-60% relative humidity for equipment protection and occupant comfort.
- Dehumidifiers:Refrigeration-cycle or desiccant-based moisture extraction units specified for warehouse and archival storage environments.
Leading the category by volume: Air Fresheners. Growing fastest: Air Purifiers.
End User:
Customer scale determines procurement channel access, with national hospitality chains leveraging institutional supply agreements while fragmented operators source through regional service firms.
- Commercial Spaces:Class A office towers and retail complexes requiring continuous particulate management for tenant retention. Sun Belt markets in Arizona and Nevada drive replacement cycles as lease rollover accelerates building upgrade investments.
- Industrial Facilities:Manufacturing plants and distribution centers with OSHA-mandated ventilation requirements for process emissions and worker protection. Activated carbon specifications dominate where solvent-based operations generate concentrated odor loads.
- Hospitality:Hotels, resorts, and extended-stay properties integrating air quality monitoring into guest experience platforms.
- Healthcare:Hospitals and outpatient clinics requiring HEPA filtration at 99.97% efficiency for infection control protocols.
Dominant by procurement value: Commercial Spaces. Expanding most quickly: Hospitality.
Application:
Functional use cases align with distinct regulatory frameworks, with odor control facing the most stringent chemical disclosure requirements under EPA and state-level registries.
- Indoor Air Quality:Comprehensive particulate and gas-phase contaminant management through integrated filtration and ventilation strategies. Demand clusters in Canadian commercial real estate as provincial energy codes tighten mechanical system performance standards.
- Odor Control:Targeted neutralization of malodorous compounds through absorption, chemical reaction, or masking technologies. Industrial specifications in Baja California and Querétaro manufacturing corridors command premium pricing for specialized activated carbon formulations.
- Humidity Control:Moisture regulation for equipment integrity and mold prevention in climate-vulnerable geographies.
- Air Filtration:Particulate capture through mechanical media for workplace compliance and occupant health protection.
Largest application segment: Indoor Air Quality. Steepest expansion trajectory: Odor Control.
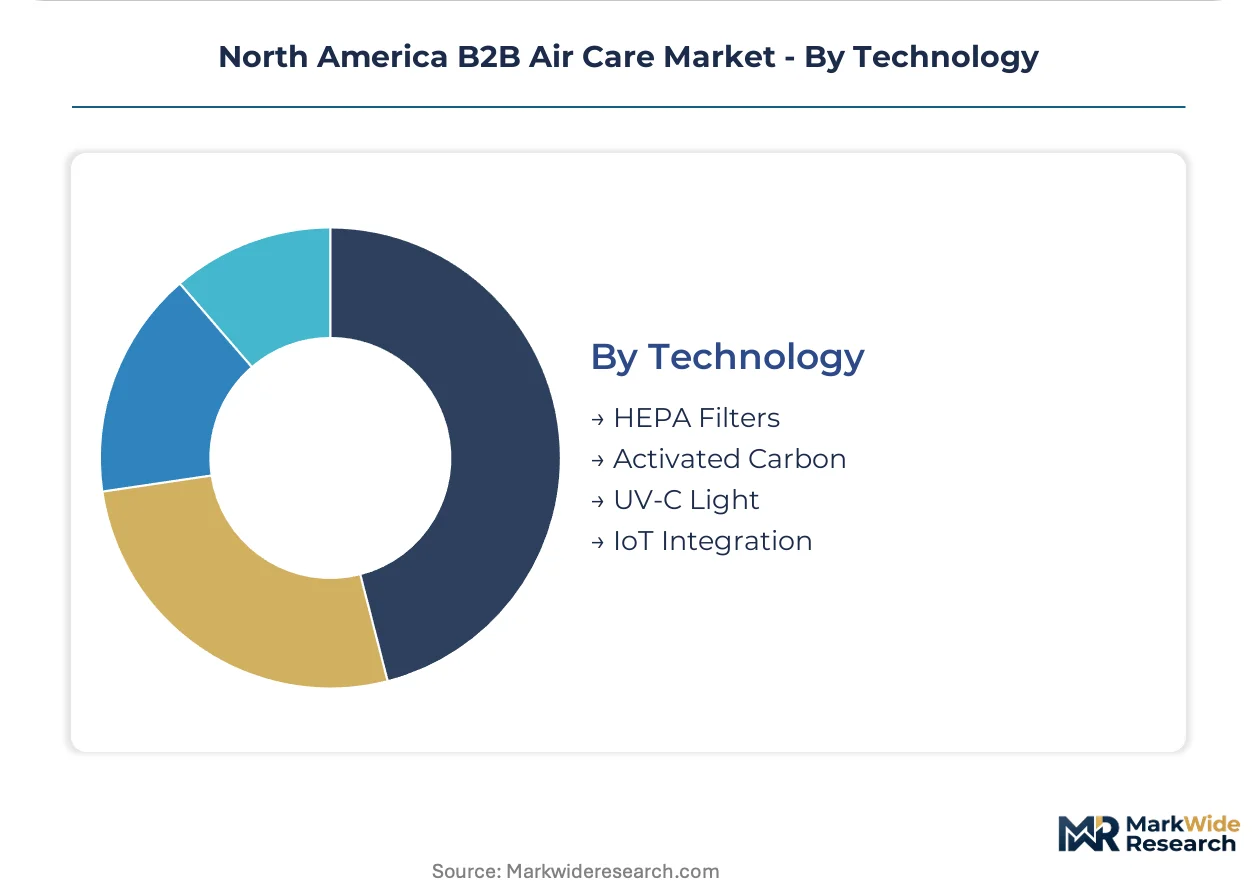
Technology:
Technology selection determines both capital intensity and service revenue potential, with connected systems enabling subscription-based replacement algorithms that displace traditional distributor relationships.
- HEPA Filters:Fibrous media capturing 0.3-micron particles at 99.97% efficiency, representing the mature core of commercial filtration with predictable 6-12 month replacement cycles. Stable demand across healthcare and education procurement channels sustains manufacturer margin pools despite commodity pricing pressure.
- IoT Integration:Sensor networks transmitting particulate, VOC, and humidity data to centralized building management platforms. Hotel operators in the United States and Canada prioritize deployment density for guest experience differentiation, compressing equipment margins while expanding software recurring revenue.
- Activated Carbon:Porous media for gas-phase contaminant adsorption in industrial and commercial odor applications.
- UV-C Light:Germicidal irradiation systems for pathogen inactivation in healthcare and foodservice environments.
Highest installed base: HEPA Filters. Gaining share fastest: IoT Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration across North America tilts heavily toward the United States, where hospitality chains and warehouse operators drive bulk equipment orders. Canada and Mexico present divergent growth profiles shaped by distinct regulatory frameworks and industrial development patterns.
United States
Hospitality construction in Texas, Florida, and Arizona generates concentrated demand for humidity control and odor management systems. EPA 40 CFR Part 59 governs VOC content in commercial formulations, pushing manufacturers toward low-emission chemistries. Dallas-Fort Worth and Phoenix hotel developments are bundling air care procurement with HVAC infrastructure upgrades.
Canada
Provincial regulatory fragmentation between Ontario, Quebec, and British Columbia complicates cross-border standardization for multi-location buyers. Health Canada guidelines intersect with provincial energy codes to tighten mechanical system performance requirements. Toronto commercial real estate is accelerating replacement cycles as lease rollover drives building upgrade investments.
Mexico
Nearshoring of automotive and electronics production is creating demand for industrial-grade air filtration in Baja California and Querétaro. Federal environmental standards operate alongside state-level industrial emissions rules. Tijuana and Querétaro manufacturing corridors command premium pricing for specialized activated carbon formulations in solvent-based operations.
North America B2B Air Care Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected system architectures and subscription service models. The vendor base spans institutional chemical suppliers, specialized odor control formulators, and industrial filtration equipment fabricators. Three archetypes dominate: legacy consumer brands with institutional supply agreements, industrial chemistry specialists with concentrated formulations, and facility service firms unbundling traditional distribution relationships. Competitive moves center on IoT-HEPA convergence for predictive maintenance revenue and EPA Safer Choice certification for federal procurement access.
Among legacy institutional suppliers, Procter & Gamble, S.C. Johnson & Son Inc., and Henkel AG & Co. KGaA represent distinct positioning archetypes. Procter & Gamble exemplifies the consumer-to-commercial extension model through hospitality distributor relationships. S.C. Johnson & Son Inc. occupies a specialized position in healthcare and fitness environment formulations. Henkel AG & Co. KGaA anchors the industrial-grade segment with manufacturing facility applications.
| Leading Market Players |
|---|
| Rexair LLC |
| Procter & Gamble |
| S.C. Johnson & Son Inc. |
| Henkel AG & Co. KGaA |
| Reckitt Benckiser Group PLC |
| CAR-FRESHNER |
| BEAUMONT PRODUCTS, INC. |
| WD-40 Company |
| Air Delights, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned regional service firms and private-equity-rolled-up facility management specialists now control downstream pricing discipline, compressing margins for legacy manufacturers while creating captive demand for consumable replenishment contracts across Sun Belt hospitality corridors.
Pricing Analysis
Volume concentrates in air freshener consumables while margins pool in IoT-enabled subscription tiers. Three-tier pricing structure separates EPA Safer Choice-certified formulations from standard commercial grades and economy private-label alternatives. Price differentiation hinges on certification tier and after-sales sensor maintenance bundling. Pricing pressure stems from petrochemical feedstock volatility squeezing fragrance compound costs. Boutique hotel chains exhibit highest price sensitivity; healthcare procurement officers show lowest.
Supply Chain Analysis
Freight costs from activated carbon suppliers in Southeast Asia and coconut shell processors in Sri Lanka elevate landed costs for industrial odor control specifications. Manufacturing concentrates in China for electronic sensor components, Mexico for assembly operations, and the United States for formulated consumables. Raw material dependencies span polymer housings, HEPA media, and specialized fragrance compounds. Single-source vulnerability runs through Malaysian activated carbon suppliers. Distribution runs through institutional hospitality distributors and unbundled regional service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Activated carbon sourcing concentration props pricing power for specialized industrial formulations, constraining volume expansion until alternative supply corridors mature.
For Market Incumbents: Deepen backward integration into fragrance compound synthesis to offset petrochemical volatility exposure. Secure EPA Safer Choice certification for core formulations to defend federal procurement access against emerging low-emission competitors. Expand sensor installation capabilities in Texas and Florida through acquisitions of regional facility service firms. For New Entrants and Emerging Players: Capture the unbundled service contract white space among co-working operators and boutique hotel chains in secondary U.S. metropolitan markets. Target Mexico's Baja California manufacturing corridor with industrial-grade activated carbon specifications. Pursue direct-to-facility-manager go-to-market models bypassing national distributor networks. For Investors and Strategic Acquirers: IoT-HEPA convergence patent filings are the leading indicator that subscription revenue pools will consolidate around predictive maintenance algorithms. Long-term viability favors vertically integrated players controlling both sensor hardware and consumable chemistry. Acquisition targets include regional facility service firms with dense Sun Belt customer relationships. Watch California Air Resources Board VOC threshold amendments as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-HEPA Convergence Development | Enables predictive filter replacement algorithms that convert capital sales into recurring software revenue streams. |
| EPA Safer Choice Certification Investment | Unlocks federal procurement preference and healthcare sector vendor qualification requirements. |
| Regional Service Firm Acquisition | Captures unbundled distribution relationships and direct facility manager access in Sun Belt growth corridors. |
| Activated Carbon Supply Diversification | Reduces specification risk from Southeast Asian sourcing concentration for industrial odor control applications. |
| Low-Emission Chemistry R&D Expansion | Anticipates California and New York state-level VOC threshold tightening ahead of federal baseline adjustments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facility management directors, hospitality procurement officers, industrial plant engineers, and fragrance compound suppliers. Bottom-up triangulation against EPA 40 CFR Part 59 compliance databases, California Air Resources Board formulation registries, and hospitality construction permit records validated demand estimates.
Granularity-level modeling deployed separate frameworks for equipment categories versus consumable chemistry, with technology adoption curves calibrated to building automation integration rates across the projection horizon. Segmentation dimensions spanned product type, end-user vertical, application function, and technology architecture. CAGRs derived from replacement cycle analysis and new construction velocity in Sun Belt corridors. Forecast inputs incorporated HVAC infrastructure upgrade bundling patterns and state-level regulatory amendment probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility and Canadian provincial regulatory fragmentation. Forecasts reflect documented assumptions about connected system penetration rates and hospitality construction velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Humidifiers Market
Household Items
Qatar Gas Hobs Market
Household Items
Cookware Market
Household Items
Drain Cleaners Market
Household Items
Barbecue Grill Market
Household Items
Smart Drying Racks Market
Household Items
Portable Steamers Market
Household Items
Washing Machine Cleaner Market
Household Items
Drinkware Accessories Market
Household Items
Dishwasher Tablets Market
Household Items
Hand Dryer Market
Household Items
Commercial Lawnmower Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Window Rain Guards Market
Household Items
Innerspring Mattresses Market
Household Items
Japan Faucets Market