
 Wax Removal Aids Market | 2026-2036
Wax Removal Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Removal Aids Market Analytics
China is reshaping supply dynamics through expanded chemical manufacturing capacity for surfactant-based formulations. Prestige Consumer Healthcare sustains broad retail distribution across North American pharmacy chains. Eosera specializes in biotechnology-derived ear care solutions with clinically tested active ingredients. GlaxoSmithKline PLC leverages its pharmaceutical heritage to anchor prescription-adjacent positioning in professional channels.
Wax removal aids comprise topical formulations—sprays, gels, creams, and wipes—engineered with emulsifying agents, cerumenolytics, or gentle solvents to soften and dislodge accumulated cerumen or surface wax deposits without mechanical trauma. These products serve household, automotive, industrial, and personal care applications where controlled wax dissolution prevents obstruction, corrosion, or hygiene compromise. Sprays and gels capture the dominant margin pool due to higher per-unit pricing and repeat purchase frequency in consumer channels, while wipes expand fastest among travel-format and on-the-go personal care segments. The automotive and industrial application cluster remains mature, with demand tethered to maintenance cycles rather than discretionary purchasing.
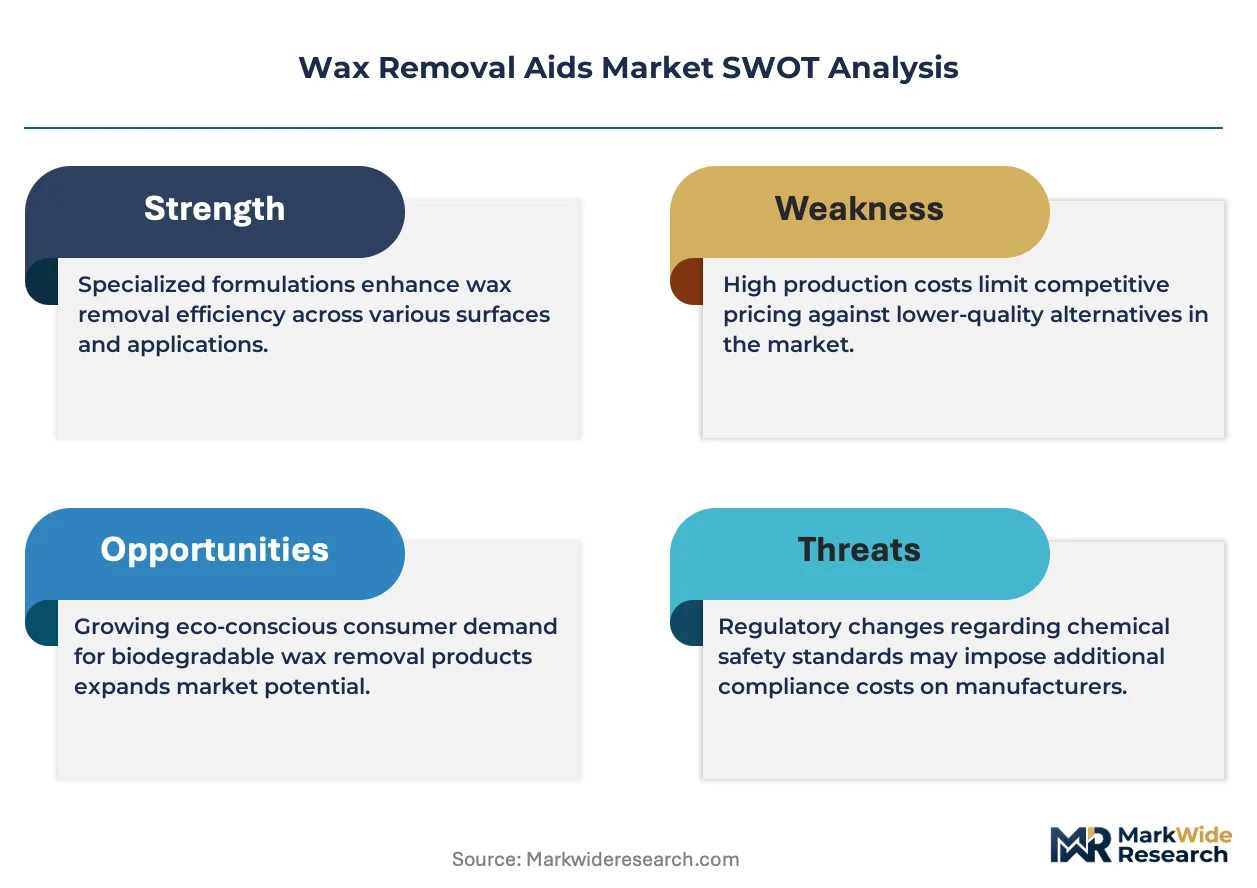
FDA regulates otic drug-device combinations through stringent safety and efficacy benchmarks, while EPA monitors volatile organic compound limits in solvent-based formulations. The EU REACH framework and RoHS directives constrain chemical composition for products entering European markets. Stakeholders must monitor evolving classification thresholds that could reclassify cerumenolytic formulations from cosmetics to medical devices, altering compliance burdens and channel access requirements.
Market Dynamics
The wax removal aids market faces mounting pressure from FDA's evolving classification criteria for otic drug-device combinations, which threatens to reclassify established cosmetic formulations as regulated medical devices and fundamentally alter channel economics.
Growth Catalysts
- REACH compliance migration:European chemical safety standards are compelling manufacturers to reformulate with biodegradable surfactants, opening premium positioning for compliant producers.
- At-home wellness prioritization:Consumers are embedding ear hygiene into daily personal care rituals, expanding repeat purchase frequency for spray and gel formats.
- Solvent substitution chemistry:Water-based cerumenolytic technologies are displacing volatile organic compound formulations ahead of EPA emission limits.
Market Restraints
- API supply concentration:Bulk surfactant production clusters in eastern China, exposing formulators to logistics volatility and tariff exposure.
- Clinical validation costs:FDA 510(k) pathway requirements for otic devices impose six-figure testing burdens on mid-tier entrants.
- Mechanical extraction preference:Audiologist-administered microsuction retains reimbursement advantages in professional channels, limiting retail product penetration.
Strategic Opportunities
- Direct-to-consumer pharmacy integration:Telehealth platforms are creating subscription-based ear care bundles that bypass traditional retail markup structures.
- Travel-format wipe expansion:TSA-compliant single-use sachets address unmet demand among business travelers and gym users.
- IRA preventive care alignment:Medicare Advantage plan incentives for at-home health monitoring are expanding eligible HSA/FSA spending categories.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity assessments for new otic formulations face 12-18 month queue times at accredited laboratories.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in dermatological safety and otic physiology command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Removal Aids Market |
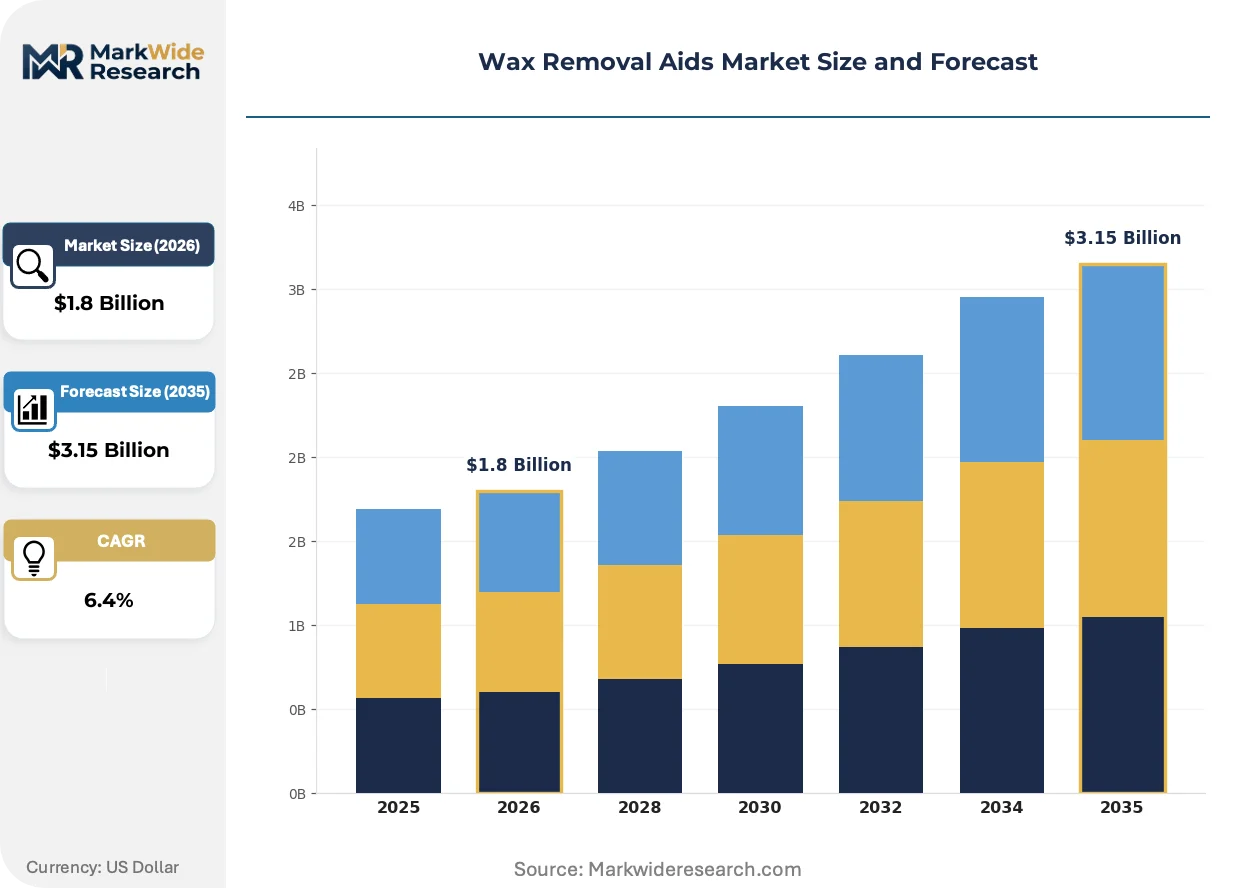
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Wipes, Gels, Creams Application: Household, Automotive, Industrial, Personal Care End User: Consumers, Automotive Professionals, Cleaning Services, Wax Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Medline Industries Inc., Prestige Consumer Healthcare Inc., Eosera Inc., Henry Schein Inc., Clearwax Ltd., PC Werth, The Hearing Lab Ltd., Cipla Limited, GlaxoSmithKline PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Removal Aids Market Evolving Landscape
Digital health integration and formulation biotechnology are converging to transform how consumers diagnose, treat, and monitor ear hygiene conditions outside clinical settings.
Connected otoscopy devices with smartphone-linked cameras are digitizing the diagnostic layer of ear care, allowing users to visualize canal conditions before selecting appropriate wax removal aids. Millennial and Gen Z adopters are driving 40% annual volume expansion in this hardware-software ecosystem. The data streams generated are compressing the feedback loop between symptom recognition and product selection, reducing trial-and-error purchasing.
EPA's 2024 volatile organic compound emission standards for consumer products are forcing solvent-based formulation reformulation across the entire personal care sector. Manufacturers are accelerating water-based and enzymatic cerumenolytic development to maintain shelf placement in California and northeastern states. The regulatory pressure is most acute for spray formats, which face the strictest per-unit emission limits.
Subscription-based replenishment models are displacing episodic pharmacy purchasing among chronic wax buildup sufferers. Amazon Subscribe & Save and specialized DTC platforms are capturing loyalty through algorithmic reorder timing based on usage patterns. This behavioral shift is most pronounced in the United States, where convenience-oriented consumers prioritize automated delivery over in-stock availability verification.
Wax Removal Aids Market Segmentation
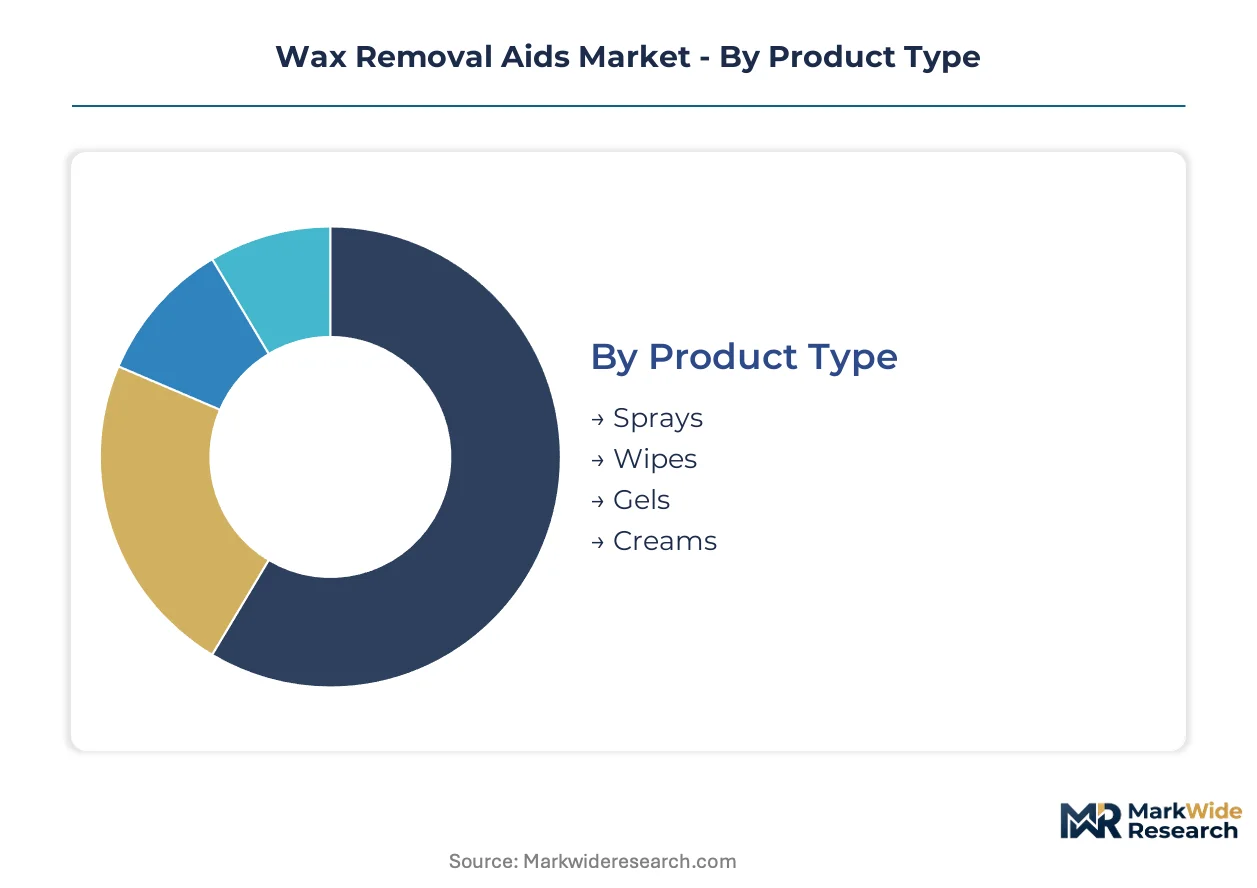
Wax removal aids exhibit distinct consumption patterns across product formats and use environments. Purchase frequency and replenishment cycles vary dramatically between institutional buyers and individual consumers. Understanding these velocity differentials enables targeted inventory positioning and margin optimization.
Product Type:
Sprays and gels turn inventory fastest in pharmacy and mass retail channels, while creams and wipes operate on extended replenishment horizons in specialty and professional settings.
- Sprays:Aerosol and pump-dispersed formulations deploy emulsifying agents and cerumenolytics through fine mist application. Repeat purchases concentrate among U.S. consumers embedding ear hygiene into weekly personal care routines, with FDA 510(k) pathway considerations shaping professional-grade variants.
- Gels:Viscous aqueous formulations deliver sustained contact time for stubborn cerumen deposits. Demand clusters in direct-to-consumer subscription models where algorithmic reorder timing captures chronic sufferers, particularly among aging demographics in Medicare Advantage plans.
- Wipes:Pre-saturated nonwoven substrates packaged in single-use sachets for travel and gym applications. TSA-compliant formats address unmet demand among business travelers in the United States.
- Creams:Thicker emulsion-based products requiring manual application and removal. Automotive and industrial maintenance cycles drive procurement through specialty distributors.
Sprays dominate installed base. Wipes are where expansion concentrates.
Application:
Personal care commands premium pricing and repeat purchase velocity, while automotive and industrial applications tether to scheduled maintenance intervals with predictable but slower turnover.
- Personal Care:At-home ear hygiene products formulated with biocompatible surfactants and gentle solvents. Millennial and Gen Z adopters in the United States are compressing feedback loops between symptom recognition and product selection through connected otoscopy integration.
- Household:Multi-surface wax removal for furniture, flooring, and decorative items. Water-based formulations are displacing volatile organic compound alternatives ahead of EPA emission limits in California and northeastern states.
- Automotive:Protective coating removal and surface preparation for refinishing. Demand concentrates in professional detailing shops and collision repair facilities with established supplier relationships.
- Industrial:Heavy-duty wax and resin removal from manufacturing equipment and production lines. Procurement runs through maintenance, repair, and operations distributors with contract-based pricing.
Personal care captures the dominant margin pool. Household is climbing the fastest as wellness positioning expands category boundaries.
End User:
Consumer self-directed purchasing outpaces institutional procurement in transaction frequency, while automotive professionals and cleaning services consolidate volume through negotiated supply agreements.
- Consumers:Individual purchasers selecting over-the-counter ear care and household wax removal products. Amazon Subscribe & Save and specialized DTC platforms are displacing episodic pharmacy purchasing through algorithmic replenishment.
- Automotive Professionals:Collision repair technicians and detailing specialists requiring consistent formulation performance for warranty compliance. Vendor consolidation is reducing supplier counts to secure volume discounts.
- Cleaning Services:Commercial and residential service providers procuring bulk formats for operational efficiency. Contract terms emphasize total cost of ownership over per-unit pricing.
- Wax Manufacturers:Industrial processors requiring raw material-grade solvents and surfactants for formulation input. Specifications prioritize purity certificates and batch consistency documentation.
Consumers represent the deepest volume base. Cleaning services are where procurement consolidation is concentrating.
Distribution Channel:
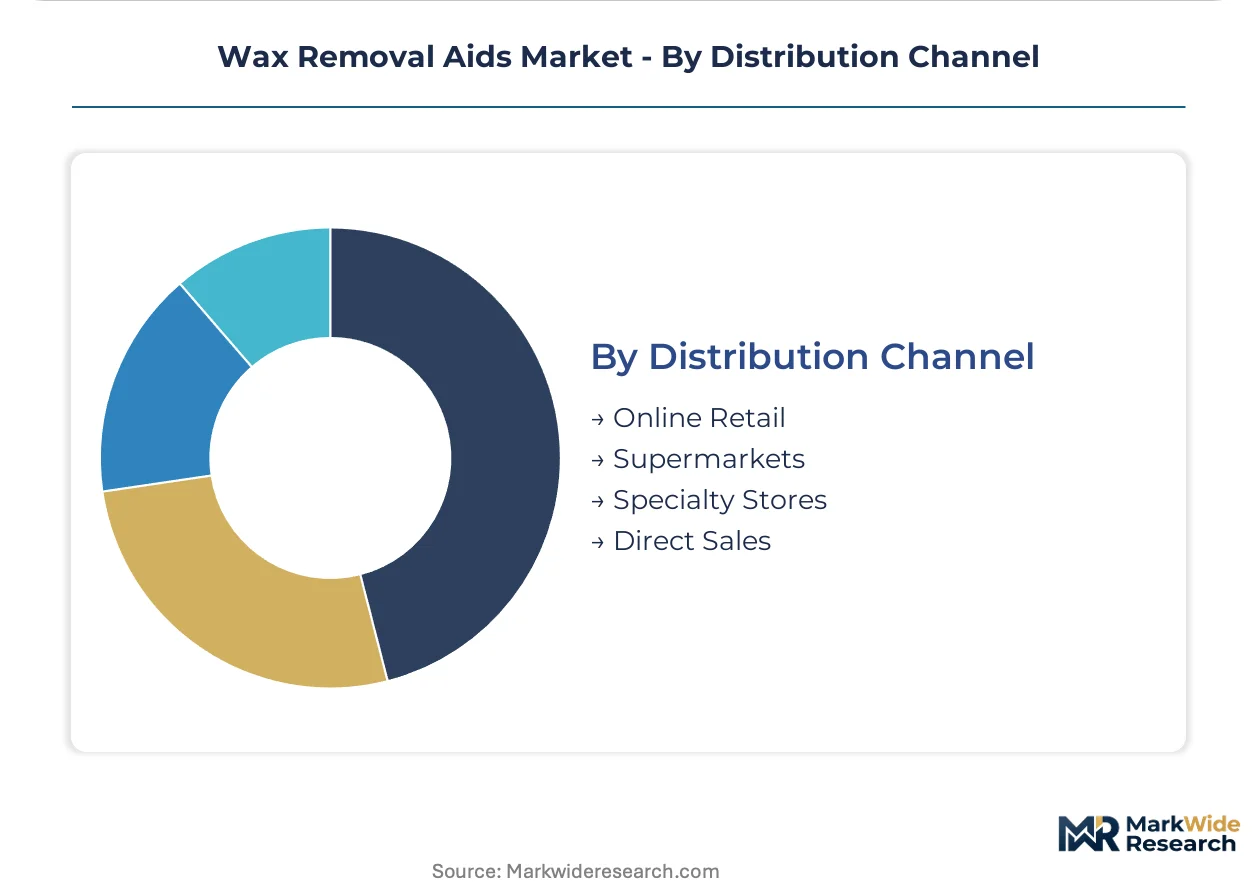
Online retail compresses replenishment cycles through subscription mechanics, while supermarkets and specialty stores rely on in-stock availability and impulse placement.
- Online Retail:E-commerce platforms and direct-to-consumer websites offering subscription replenishment and telehealth bundle integration. Telehealth platforms in the United States are creating ear care bundles that bypass traditional retail markup structures.
- Supermarkets:Mass merchandisers and grocery chains with pharmacy adjacencies. Shelf placement competes for visibility among personal care aisles with established foot traffic patterns.
- Specialty Stores:Hearing aid retailers, audiologist offices, and professional supply houses. FDA oversight of otic drug-device combinations elevates compliance requirements for channel entry.
- Direct Sales:Manufacturer-to-institutional contracts for automotive and industrial volume accounts. Relationship-based selling emphasizes technical service and formulation customization.
Supermarkets anchor current throughput. Online retail is gaining share fastest as subscription models lock in loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of otic drug-device combinations anchors the United States as the dominant geography, while REACH compliance migration and EPA emission standards reshape formulation requirements across manufacturing clusters worldwide.
United States
Aging demographics and Medicare Advantage preventive care incentives drive at-home ear hygiene adoption among chronic wax buildup sufferers. The FDA 510(k) pathway imposes six-figure testing burdens that favor established pharmaceutical heritage players over mid-tier entrants. New Jersey and Pennsylvania pharmaceutical corridors concentrate formulation R&D for prescription-adjacent positioning.
China
Expanded chemical manufacturing capacity for surfactant-based formulations supplies global formulators with cost-competitive inputs. The National Medical Products Administration monitors drug-device classification thresholds that could reclassify cerumenolytic products. Yangtze River Delta chemical clusters dominate bulk surfactant production, exposing supply chains to logistics volatility and tariff exposure.
Germany
EU REACH framework and RoHS directives constrain chemical composition for products entering European markets, compelling biodegradable surfactant reformulation. The European Chemicals Agency enforces stringent cytotoxicity assessment protocols. North Rhine-Westphalia industrial chemistry hubs lead water-based cerumenolytic development to maintain California and northeastern U.S. shelf placement.
United Kingdom
Telehealth platform integration creates subscription-based ear care bundles that bypass traditional retail markup structures. The Medicines and Healthcare products Regulatory Agency aligns with evolving FDA classification criteria for cross-border product registration. London and Southeast England hearing aid retail networks anchor professional channel distribution.
India
Contract manufacturing capabilities attract multinational formulators seeking cost-optimized production for export markets. The Central Drugs Standard Control Organization regulates otic preparations under pharmaceutical rather than cosmetic frameworks. Gujarat and Maharashtra chemical manufacturing zones supply emulsifying agents to global wax removal aid producers.
Wax Removal Aids Market Competitive Landscape
Capability concentration sits with biotechnology-derived specialists; scale advantage sits with broad retail distributors. The market structure tiers between pharmaceutical heritage players with professional channel access and direct-to-consumer platforms with subscription mechanics. Strategic archetypes include clinically tested ingredient developers, mass retail pharmacy networks, and telehealth-integrated service bundles. Dominant competitive moves encompass formulation reformulation for EPA compliance and algorithmic replenishment timing to capture chronic sufferer loyalty.
Within the pharmaceutical heritage tier, GlaxoSmithKline PLC occupies a position exemplifying prescription-adjacent channel anchoring. Prestige Consumer Healthcare Inc. and Eosera Inc. represent contrasting archetypes—broad North American pharmacy distribution versus biotechnology-derived ear care specialization with clinically tested active ingredients. These three entities collectively illustrate how FDA regulatory positioning and ingredient sourcing strategy differentiate competitive stance in a market where classification thresholds remain fluid.
| Leading Market Players |
|---|
| Medline Industries Inc. |
| Prestige Consumer Healthcare Inc. |
| Eosera Inc. |
| Henry Schein Inc. |
| Clearwax Ltd. |
| PC Werth |
| The Hearing Lab Ltd. |
| Cipla Limited |
| GlaxoSmithKline PLC |
| Others |
Value Network & Pricing Analysis
Overcapacity in Yangtze River Delta surfactant production clusters is compressing input costs for formulators while simultaneously eroding supplier pricing power in contract negotiations. This utilization dynamic feeds directly into margin structures across spray and gel formats, where raw material pass-through mechanisms remain the dominant pricing transmission channel.
Pricing Analysis
Geographic price spreads between California-compliant water-based formulations and legacy solvent alternatives now exceed fifty percent at wholesale tier. Three-tier pricing structure across premium biotechnology-derived, standard surfactant-based, and economy private-label levels stratifies the consumer segment. Cost compression in standard-tier sprays is intensifying because EPA volatile organic compound limits are forcing simultaneous reformulation investment and competitive positioning. Cleaning services exhibit highest price sensitivity due to contract-based total cost of ownership procurement, while direct-to-consumer subscription purchasers show lowest sensitivity due to convenience premium anchoring.
Supply Chain Analysis
Export-control regime friction around dual-use chemical manufacturing equipment is constraining capacity expansion in certain Asian manufacturing jurisdictions. Bulk surfactant production draws from China, India, and Germany, with emulsifying agents and cerumenolytic actives as critical formulation inputs. Single-source vulnerability concentrates in Yangtze River Delta logistics corridors exposed to tariff volatility and shipping disruption. Distribution runs through pharmacy wholesale networks for retail placement, direct-to-consumer platforms for subscription fulfillment, and maintenance-repair-operations distributors for industrial volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where telehealth-integrated diagnostic hardware and algorithmic replenishment software are converging into unified ear care ecosystems. Interoperability between connected otoscopy devices and subscription fulfillment platforms is rewiring customer acquisition economics and lifetime value calculations.
For Market Incumbents: Entrench pharmacy channel control through exclusive formulation partnerships with hearing aid retail networks, while accelerating FDA 510(k) certification investment to raise regulatory barriers against mid-tier entrants. Backward integration into biotechnology-derived active ingredient production secures supply continuity and margin protection against API price volatility.
For New Entrants and Emerging Players: Build out travel-format wipe portfolios targeting TSA-compliant single-use sachets for business traveler and gym user segments, where incumbent coverage remains thin. Direct-to-consumer telehealth bundle integration offers the most penetrable go-to-market angle, bypassing traditional retail markup structures through algorithmic reorder timing and symptom-recognition software integration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotechnology-derived formulation segments due to ISO 10993 cytotoxicity assessment bottlenecks and extended laboratory queue times. Five-to-ten year viability favors acquisition targets with clinically tested ingredient portfolios and established professional channel relationships. The signal to watch is FDA classification threshold evolution that could reclassify cosmetic formulations as regulated medical devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology-Derived Formulation Development | Clinically tested active ingredients command premium positioning in pharmacy channels. |
| Telehealth Platform Integration | Connected otoscopy devices compress diagnostic-to-treatment feedback loops for subscribers. |
| EPA Compliance Reformulation | Water-based cerumenolytic technologies secure shelf placement in California and northeastern states. |
| Subscription Replenishment Infrastructure | Algorithmic reorder timing captures chronic sufferer loyalty and reduces customer acquisition costs. |
| Professional Channel Certification Investment | FDA 510(k) pathway completion anchors prescription-adjacent positioning in audiologist offices. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with formulation chemists, pharmacy category buyers, telehealth platform operators, and biomedical testing laboratory directors combined with FDA 510(k) submission databases, EPA emission standard registers, and EU REACH compliance documentation. Bottom-up volume modeling across product formats and top-down value reconciliation against pharmaceutical and personal care sector benchmarks ensured methodological rigor.
Calibration against historical adoption curves for diagnostic-consumer product pairings shaped the projection framework. Segmentation dimensions modeled include product format, application environment, end-user archetype, and distribution channel across the analysis window. CAGRs derived from regression analysis of pricing velocity, replenishment frequency, and channel shift parameters, with specific inputs from connected device adoption rates and subscription commerce penetration benchmarks.
Sensitivities concentrate around FDA classification threshold revisions, REACH compliance migration timelines, and tariff exposure in surfactant supply corridors. Forecasts reflect documented assumptions regarding regulatory stability and logistics cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Hand Dryer Market
Household Items
US Air Fresheners Market
Household Items
MENA POU Water Purifiers Market
Household Items
Silicone Soap Mold Market
Household Items
Industrial Floor Mats Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Dishwasher Tablets Market
Household Items
Commercial Locker Market
Household Items
Kuwait Gas Hobs Market
Household Items
Electric Blankets Market
Household Items
Luxury Massage Chair Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Porcelain Tableware Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Electric Soap Dispenser Market
Household Items
Cookware Market