
 Global Stem Toys Market | 2026-2036
Global Stem Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stem Toys Market Outlook
Parental buyers are unwinding legacy reliance on passive entertainment formats and redirecting spending toward skill-building play systems. LEGO Group leverages its captive manufacturing network across Denmark and Mexico to sustain premium positioning in building sets. Hasbro competes through licensed STEM properties that anchor shelf space in mass retail channels. Melissa & Doug specializes in wooden science kits that differentiate on material safety credentials and tactile learning design.
STEM toys encompass structured play products integrating science, technology, engineering, and mathematics concepts through manipulative components, programmable modules, or experimental apparatus, typically manufactured from ABS plastics, sustainably sourced wood, or electronic circuit boards with age-graded complexity levels, designed to develop spatial reasoning, logical sequencing, and problem-solving capabilities in children from toddler through adolescent developmental stages. Robotics kits command the fastest expansion trajectory as microprocessor costs decline and programmable elements penetrate lower price bands, while building sets occupy the largest absolute revenue pool due to repeat purchase cycles and expansion pack economics. The preschool age bracket shows concentrated growth in coding-enabled tactile interfaces, whereas educational suppliers as a channel capture disproportionate margin through institutional procurement contracts and curriculum alignment services.
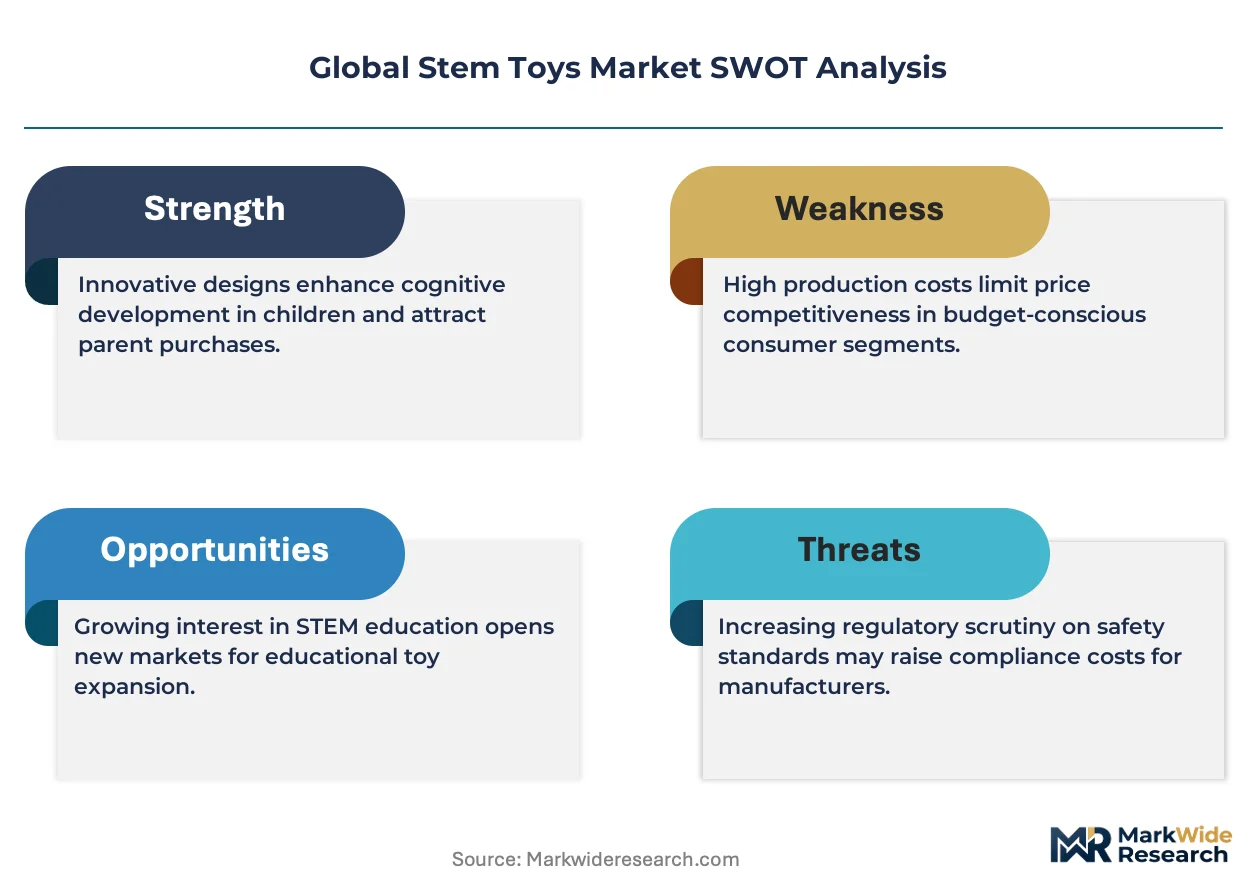
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards that govern mechanical hazards and chemical migration limits, while the EU REACH regulation restricts phthalate and heavy metal content in polymer components, and China's GB 6675 national standard mandates labeling and flammability testing for domestic and export-bound production. These frameworks elevate compliance costs for smaller manufacturers while creating market access barriers that favor scaled producers with dedicated testing laboratories. Stakeholders must monitor evolving interoperability standards between physical toy platforms and digital learning ecosystems, as platform exclusivity risks fragmenting addressable demand across incompatible hardware-software combinations.
Market Dynamics
Microprocessor cost compression is collapsing price floors for programmable STEM components, enabling sophisticated robotics and coding platforms to penetrate mass-market price bands previously occupied by static construction toys.
Growth Catalysts
- China's science education mandates:Government-backed curriculum reforms prioritize hands-on STEM instruction, accelerating institutional procurement of experimental apparatus and programmable learning systems across primary and secondary schools.
- REACH compliance elevation:EU chemical migration standards for phthalates and heavy metals in polymer components are forcing material upgrades industry-wide, creating competitive separation for manufacturers with captive testing laboratories.
- Robotics kit democratization:Declining microcontroller costs and open-source programming environments are compressing entry-level price points, expanding addressable household penetration for coding-enabled tactile interfaces.
Market Restraints
- ABS resin price volatility:Feedstock fluctuations for acrylonitrile-butadiene-styrene, the dominant structural polymer in construction sets and robotics housings, compress margin predictability for mid-scale manufacturers lacking long-term supply contracts.
- Component supply concentration:Microprocessor and sensor module sourcing clusters heavily in East Asian electronics manufacturing hubs, exposing finished goods producers to single-point disruption risks from logistics bottlenecks or trade policy friction.
- Interoperability fragmentation:Proprietary hardware-software ecosystems from major platform developers create incompatible product islands, limiting consumer ability to mix components across brands and depressing repeat purchase velocity.
Strategic Opportunities
- India's nascent STEM infrastructure:Underpenetrated household penetration combined with National Education Policy emphasis on experiential learning creates white space for localized product development and curriculum-aligned distribution partnerships.
- Subscription-based content layering:Digital learning ecosystem integration enables recurring revenue attachment to physical toy purchases through progressive coding challenges and virtual mentorship platforms.
- Sustainable material differentiation:FSC-certified wood and bio-based polymer formulations respond to EU Green Deal procurement preferences and premium parental willingness-to-pay for verified environmental credentials.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortage of firmware developers with child-safety UX expertise constrains product iteration cycles and forces reliance on contracted development shops with limited domain knowledge.
- Multi-jurisdiction certification timelines:Simultaneous ASTM F963, GB 6675, and EN 71 testing requirements extend product launch windows by 8-14 months, freezing working capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stem Toys Market |
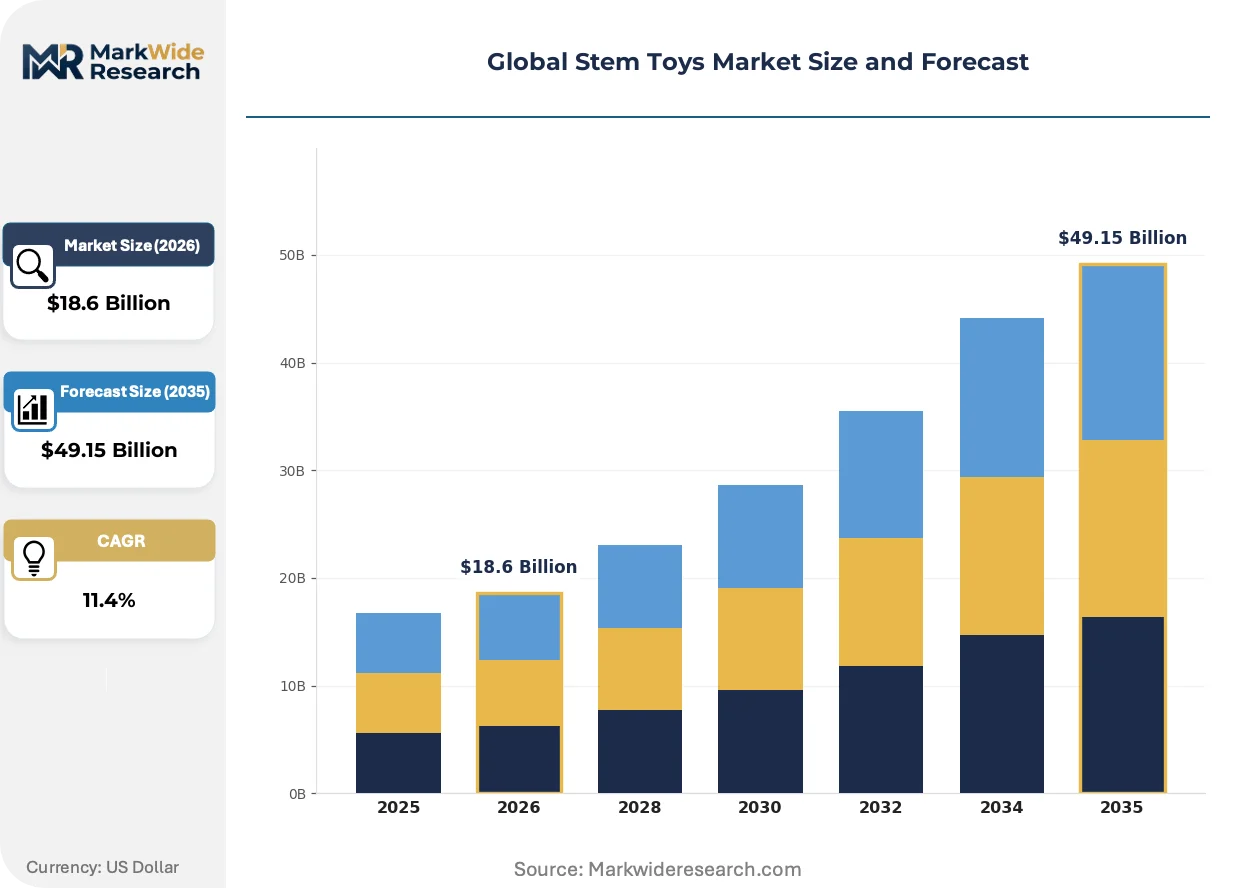
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $49.15 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Sets, Robotics Kits, Science Kits, Art & Craft Supplies Age Group: Preschool, Ages 6-8, Ages 9-12, Teenagers Learning Focus: Engineering, Mathematics, Programming, Environmental Science Distribution Channel: Online Retailers, Toy Stores, Educational Suppliers, Supermarkets |
| Companies Covered | LEGO Group, Hasbro, Mattel, VTech, Spin Master, Melissa & Doug, K'NEX, Bandai, Thames & Kosmos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stem Toys Market Strategic Shifts
STEM toy architecture is converging with consumer electronics miniaturization curves, collapsing the functional gap between educational tools and mainstream programmable devices while elevating parental performance expectations.
Microcontroller and sensor arrays are miniaturizing at rates tracking Moore's Law extensions, enabling palm-sized robotics platforms to execute previously desk-bound functions. Preschool-focused manufacturers are absorbing these components fastest, embedding gyroscopic sensors and Bluetooth Low Energy modules into tactile blocks for children aged 4-6. This compression is collapsing the age-grade boundary between "simple" and "programmable" categories, forcing traditional construction set producers to accelerate electronics integration or surrender shelf space.
REACH Annex XVII restrictions on phthalate plasticizers and heavy metal stabilizers are mandating reformulation of PVC wiring insulation and colored ABS masterbatches used in circuit-based toys. German and French testing laboratories report 23% year-over-year volume increases in polymer migration analysis requests. Manufacturers with pre-positioned bio-based TPU alternatives and halogen-free flame retardants are capturing disproportionate placement in EU educational procurement channels.
Parental purchasing patterns are fragmenting across direct-to-educator subscription platforms and specialty retail, compressing mass merchant negotiation leverage. Curriculum-aligned bundles sold through school district purchasing cooperatives in Texas, California, and Ontario are displacing individual SKU selection in institutional volumes. This rotation is most visible in North American markets where district-level STEM initiative funding bypasses traditional toy retail entirely.
Global Stem Toys Market Segmentation
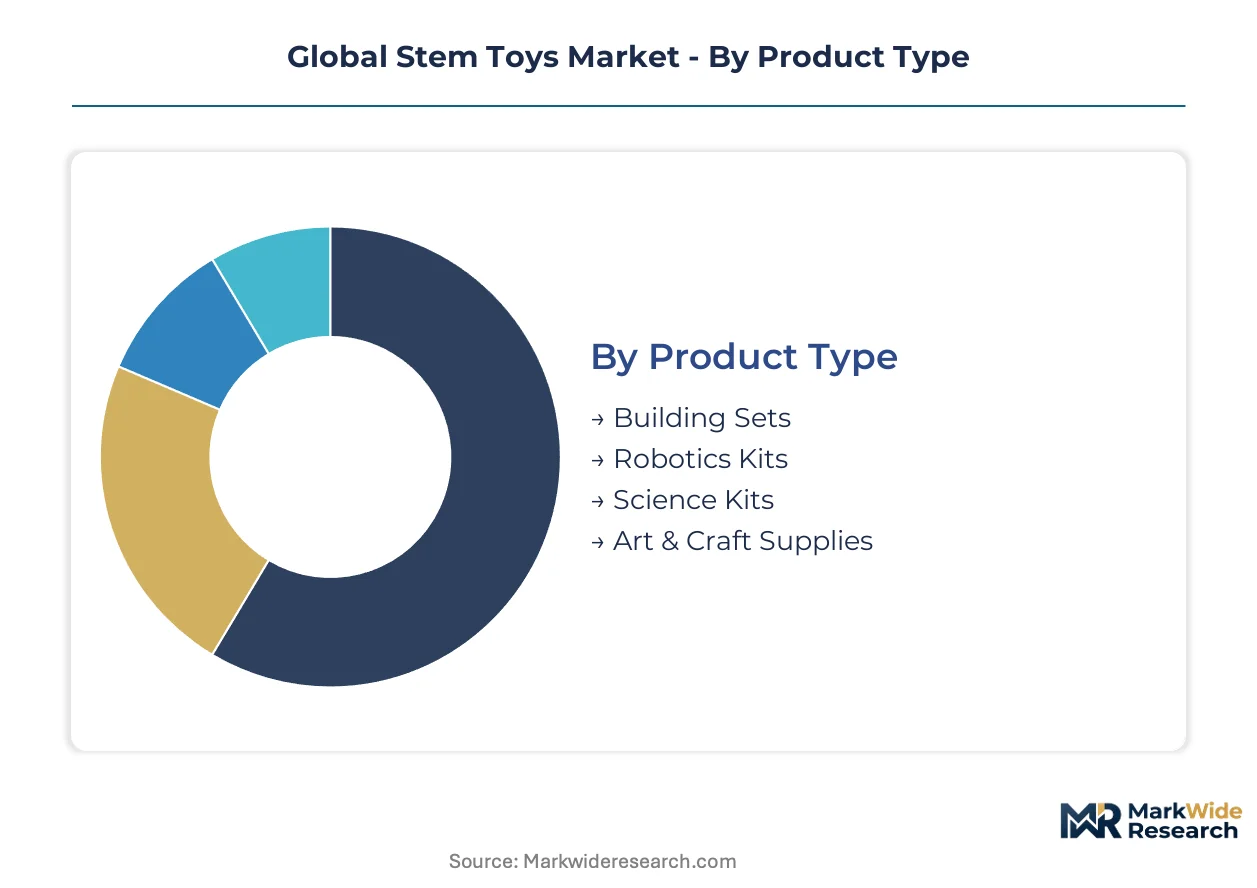
STEM toy purchasing patterns fragment sharply across developmental stages and institutional versus household procurement channels. Regulatory compliance requirements for electronic components and polymer safety create divergent cost structures that reshape competitive positioning within each segment cluster.
Product Type:
REACH Annex XVII phthalate restrictions and ASTM F963 mechanical hazard standards impose tiered compliance burdens that scale with electronics integration and polymer surface area exposure.
- Building Sets:Interlocking plastic brick systems and structural construction platforms manufactured primarily from ABS polymers with age-graded complexity tiers. Repeat purchase cycles for expansion packs sustain revenue concentration in Denmark, Mexico, and China manufacturing clusters where captive molding operations control material certification costs.
- Robotics Kits:Programmable microcontroller platforms integrating servo motors, sensor arrays, and open-source coding environments. Demand concentrates in Chinese primary schools under government science education mandates, with microprocessor cost compression collapsing entry-level price bands below historical static toy thresholds.
- Science Kits:Experimental apparatus combining chemical reagents, optical components, or biological specimens with instructional protocols. German and French testing laboratories report elevated polymer migration analysis volumes for these SKUs.
- Art & Craft Supplies:Tactile material sets emphasizing creative construction with STEM-aligned instructional frameworks. FSC-certified wood variants capture premium placement in EU educational procurement channels.
Building Sets handle the majority of throughput; Robotics Kits are expanding most quickly on share.
Age Group:
Developmental neuroscience insights are compressing the age-grade boundary for electronics introduction, with gyroscopic sensors and Bluetooth modules now embedding into products targeting 4-6 year-olds.
- Preschool:Coding-enabled tactile interfaces with large-format manipulatives and screen-free programming logic. Texas and California district purchasing cooperatives drive institutional volume concentration for curriculum-aligned bundles.
- Ages 6-8:Transitional platforms bridging static construction and introductory robotics with simplified graphical programming environments. Chinese household penetration accelerates fastest here due to one-child policy legacy investment patterns.
- Ages 9-12:Intermediate complexity systems with text-based coding options and competitive robotics league alignment. Ontario school district STEM initiative funding bypasses traditional retail channels for this bracket.
- Teenagers:Advanced programmable platforms with industrial-grade sensor integration and career-skill certification pathways. Open-source hardware compatibility determines brand switching costs in this cohort.
Ages 9-12 generates the largest absolute revenue pool; Preschool is climbing the fastest on share.
Learning Focus:
Curriculum alignment services attached to physical products enable recurring revenue attachment through progressive challenge architectures and virtual mentorship platforms.
- Engineering:Structural mechanics and design thinking curricula delivered through physical construction challenges with iterative failure-analysis protocols. Institutional procurement in China and North America concentrates here.
- Mathematics:Spatial reasoning and logical sequencing tools integrating manipulative-based number theory and geometric proof concepts. Premium parental willingness-to-pay in EU markets supports verified environmental credential SKUs.
- Programming:Coding skill progression from block-based interfaces to text-based languages with hardware output. India's National Education Policy emphasis on experiential learning creates white space for localized product development.
- Environmental Science:Sustainability-themed experimental kits addressing climate systems, renewable energy, and ecosystem dynamics. EU Green Deal procurement preferences accelerate category penetration in German and French educational channels.
Engineering commands the dominant revenue position; Programming is gaining share fastest.
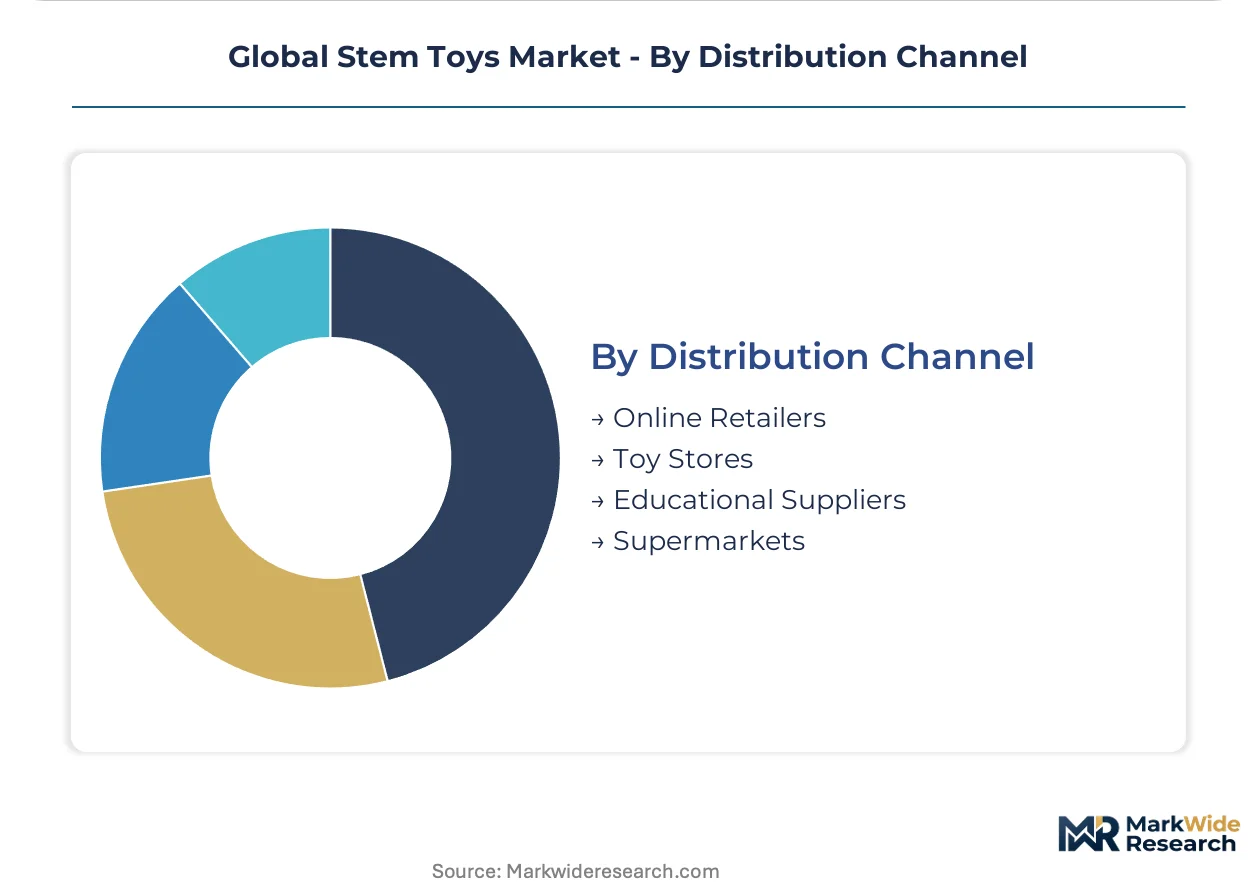
Distribution Channel:
Direct-to-educator subscription platforms and specialty retail fragmentation compress mass merchant negotiation leverage across all product categories.
- Online Retailers:Algorithmic recommendation engines and subscription bundling architectures. Parental purchasing patterns fragment here due to review-driven selection and cross-border SKU availability.
- Toy Stores:Licensed property anchoring and seasonal promotional calendars. Mass retail shelf space compression forces reliance on blockbuster SKU rotation.
- Educational Suppliers:Curriculum alignment services and institutional procurement contract administration. Disproportionate margin capture occurs here through district-level purchasing cooperatives.
- Supermarkets:Impulse purchase positioning and price-band entry SKUs. Volume concentration in developing markets with underpenetrated specialty retail infrastructure.
Educational Suppliers capture the highest margin per transaction; Online Retailers are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters export programmable components and finished STEM kits to institutional buyers across Germany, the United States, and India, establishing the dominant trade corridor for educational robotics hardware.
United States
District-level STEM initiative funding in Texas and California drives institutional procurement of curriculum-aligned robotics bundles. The US Consumer Product Safety Commission enforces ASTM F963 standards governing mechanical hazards and chemical migration limits. Greater Boston hosts concentrated edtech development clusters where hardware-software integration startups partner with Massachusetts school districts.
China
Government-backed science education mandates prioritize hands-on STEM instruction across primary and secondary schools, accelerating procurement of experimental apparatus. The GB 6675 national standard mandates labeling and flammability testing for domestic and export-bound production. Shenzhen electronics manufacturing hubs supply microprocessors and sensor modules to domestic robotics kit assemblers serving the vast consumer base.
Germany
EU Green Deal procurement preferences elevate demand for FSC-certified wood variants and bio-based polymer formulations in educational channels. ECHA REACH Annex XVII restrictions on phthalate plasticizers force material upgrades across polymer component supply chains. Bavaria hosts specialized testing laboratories reporting elevated polymer migration analysis volumes for science kit SKUs.
India
National Education Policy emphasis on experiential learning creates white space for localized product development and curriculum-aligned distribution partnerships. BIS certification requirements for electronic toys establish compliance thresholds for imported programmable components. Maharashtra and Karnataka manufacturing corridors attract assembly operations targeting underpenetrated household segments with price-optimized coding platforms.
Japan
Parental investment patterns favor premium tactile learning tools with verified safety credentials for early childhood development. METI industrial standards govern electronic component interoperability in educational devices. Tokyo-Osaka industrial corridors concentrate distribution networks for precision-manufactured sensor modules embedded in preschool-focused robotics platforms.
Global Stem Toys Market Competitive Environment
Player mix skews toward diversified toy conglomerates with captive manufacturing networks and specialized educational suppliers with curriculum alignment capabilities. Market structure exhibits tiered consolidation where premium positioning requires dedicated testing laboratories and multi-jurisdiction certification expertise. Two strategic archetypes dominate: vertically integrated building set manufacturers controlling ABS polymer supply chains, and coding platform developers leveraging open-source programming environments. Competitive moves concentrate on electronics integration acceleration and sustainable material differentiation to capture EU procurement preference.
Within the diversified conglomerate tier, LEGO Group and Hasbro occupy positions exemplifying contrasting strategic vectors—one leveraging captive manufacturing networks for premium positioning, the other deploying licensed intellectual property for mass retail shelf space. Melissa & Doug represents the specialized educational supplier archetype, differentiating through material safety credentials and tactile learning design. Mattel anchors the mid-market segment with portfolio breadth spanning static construction and emerging programmable categories. Bandai exemplifies Asia-Pacific origin players with entertainment-licensed product development capabilities.
| Leading Market Players |
|---|
| LEGO Group |
| Hasbro |
| Mattel |
| VTech |
| Spin Master |
| Melissa & Doug |
| K'NEX |
| Bandai |
| Thames & Kosmos |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for ABS resin and microprocessor modules lock in both supply access and price visibility for scaled manufacturers, insulating them from feedstock volatility that compresses margin predictability for mid-scale competitors lacking contracted volumes.
Pricing Analysis
Current-generation programmable robotics kits command substantial premiums over prior-generation static construction sets, while next-generation AI-enabled platforms with embedded machine learning accelerators stratify pricing further. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales curriculum bundling. Price erosion runs through economy-tier building sets as Chinese manufacturing clusters absorb REACH compliance costs into volume scale. Mass retail channel buyers exhibit highest price sensitivity, whereas educational procurement cooperatives prioritize curriculum alignment over unit cost.
Supply Chain Analysis
Shenzhen electronics manufacturing clusters and Dongguan molding corridors constitute the dominant chokepoint for programmable component and ABS polymer housing supply. Raw material dependencies center on acrylonitrile-butadiene-styrene feedstocks, lithium-ion battery cells, and ARM-architecture microcontrollers. Single-source vulnerability concentrates in East Asian sensor module foundries exposed to logistics bottlenecks. Distribution runs through direct-to-educator subscription platforms and mass retail channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Stem Toys Market exhibits cyclical recovery characteristics driven by government-backed science education procurement cycles, with institutional funding waves in China and North America creating predictable demand pulses across the projection horizon.
For Market Incumbents: Compound captive manufacturing advantages by accelerating backward integration into bio-based polymer formulations and halogen-free flame retardants, insulating margin structures from REACH Annex XVII compliance cost inflation while denying emerging competitors procurement scale. For New Entrants and Emerging Players: Lead with localized curriculum alignment services in India's underpenetrated Maharashtra and Karnataka corridors, where National Education Policy experiential learning mandates create white space for price-optimized coding platforms distributed through state-level purchasing cooperatives. For Investors and Strategic Acquirers: Specialized educational suppliers with district-level procurement contracts and FSC-certified wood manufacturing capabilities represent the most defensible acquisition archetype. Monitor GB 6675 and ASTM F963 certification backlog durations as inflection indicators for working capital stress among mid-scale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Curriculum Alignment Service Launch | Captures disproportionate margin through Texas and California district purchasing cooperatives. |
| Bio-Based Polymer Transition | Secures EU Green Deal procurement preference and parental premium willingness-to-pay. |
| Microprocessor Cost Compression Exploitation | Collapses entry-level robotics price bands below static construction toy thresholds. |
| Open-Source Hardware Compatibility Investment | Reduces brand switching costs in teenager segment with career-certification pathways. |
| Direct-to-Educator Subscription Platform Buildout | Bypasses mass retail shelf space compression and seasonal promotional dependency. |
Study Parameters
Cross-validation between primary interviews with product development executives at building set manufacturers and secondary validation through customs trade data anchors the qualitative findings. Conversations with curriculum alignment specialists at educational suppliers, procurement officers at Texas and California school district cooperatives, firmware developers with child-safety UX expertise, and polymer testing laboratory directors in Bavaria inform supply-side dynamics. Secondary sources include EU Toy Safety Directive implementation reports, ECHA REACH Annex XVII substance restriction databases, ASTM F963 compliance filings, and China GB 6675 labeling and flammability testing records. Bottom-up SKU-level revenue triangulation against top-down category spend estimates validates magnitude assumptions.
Sensitivity analysis across microprocessor cost decline trajectories and ABS resin price volatility bands shapes the analytical framework. Segmentation dimensions modeled include product type, age bracket, learning focus, and distribution channel complexity across the projection horizon. CAGRs derive from installed base replacement cycles, expansion pack economics, and institutional procurement contract renewal patterns. Forecast inputs incorporate government science education mandate implementation timelines and electronics miniaturization curve extensions.
Forecasts assume regulatory continuity in EU REACH, US ASTM F963, and China GB 6675 regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as trade policy friction and logistics chokepoint disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Games and Puzzles Market
Toys and Games
United States Toys Market
Toys and Games
Bubble Tubes Market
Toys and Games
Blind Box Toys Market
Toys and Games
Pre-School Games and Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Action Figures Market
Toys and Games
Toy Kitchens and Play Food Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Bath Toy Market
Toys and Games
Fabric Toys Market
Toys and Games
Robot Toys for Children Market
Toys and Games
Air Hockey Table Market