
 Fabric Toys Market | 2026-2036
Fabric Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Toys Market Analysis
Preschool educational demand is hardening as a dominant vertical, shifting volume away from pure entertainment plush toward developmental fabric toys. Jellycat leverages its British design heritage to dominate premium gifting channels in North America and Europe. Mattel sustains broad retail shelf presence through backward integration into character licensing and mass-market distribution networks. Spin Master competes aggressively on price in the mid-tier stuffed animal segment while extending its toy-to-content ecosystem strategy.
Fabric toys are textile-based play products constructed from woven or knitted materials such as cotton, polyester fleece, or velvet, typically incorporating stitched seams, embroidered features, and hypoallergenic fiberfill stuffing; they serve developmental, comfort, and educational functions for children from infancy through early school age. Stuffed animals occupy the largest revenue pool due to universal appeal across age groups, though fabric puzzles are recording the fastest growth trajectory among product types as STEM-oriented parents prioritize cognitive development toys. Cotton-based fabric toys command premium positioning among eco-conscious buyers, while polyester variants anchor mass-market volume through lower unit costs and easier care requirements.
The US Consumer Product Safety Commission enforces flammability and small-parts standards that directly shape material selection and design tolerances for fabric toys sold in American retail channels. The EU REACH regulation restricts chemical substances in textile dyes and finishes, compelling manufacturers to reformulate colorants or source certified organic fabrics for European market access. China's GB standards for toy safety add a third compliance layer for production concentrated in Guangdong and Zhejiang provinces. Stakeholders must monitor evolving chemical restriction lists across these three jurisdictions to anticipate reformulation costs and sourcing shifts.
Market Dynamics
Preschool enrollment expansion across OECD member states is hardening demand for developmental fabric toys, while REACH and CPSIA compliance requirements are forcing supply chain restructuring around certified organic materials and reformulated dyes.
Growth Catalysts
- REACH chemical restrictions:The EU regulation is accelerating certified organic cotton sourcing as manufacturers reformulate textile dyes to maintain European market access.
- STEM-oriented parenting:Cognitive development priorities among millennial parents are elevating fabric puzzles and educational plush over pure entertainment products.
- Guangdong manufacturing cluster:Concentrated production infrastructure in China's Pearl River Delta is compressing lead times for global brand fulfillment.
Market Restraints
- Organic cotton price volatility:Weather-dependent harvests and competing textile demand are destabilizing input costs for premium positioning strategies.
- Zhejiang supplier concentration:Heavy reliance on a single Chinese province for polyester fleece production creates geographic risk exposure.
- Flammability testing bottlenecks:CPSC certification timelines extend product development cycles by four to six months for US-bound shipments.
Strategic Opportunities
- India's preschool infrastructure:Government-funded early childhood education expansion is opening volume demand for mid-tier developmental fabric toys.
- Subscription toy services:Direct-to-consumer rental and rotation models are bypassing traditional retail margin structures for urban households.
- Waste-to-textile conversion:Post-consumer polyester recycling technologies are enabling circular economy claims for eco-conscious positioning.
Industry Challenges
- Certified toy safety engineering:Shortage of professionals fluent in GB standards, REACH annexes, and CPSIA small-parts protocols complicates multi-market launches.
- Legacy ERP integration:Batch-level traceability requirements for chemical compliance are forcing expensive supply chain software upgrades among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Toys Market |
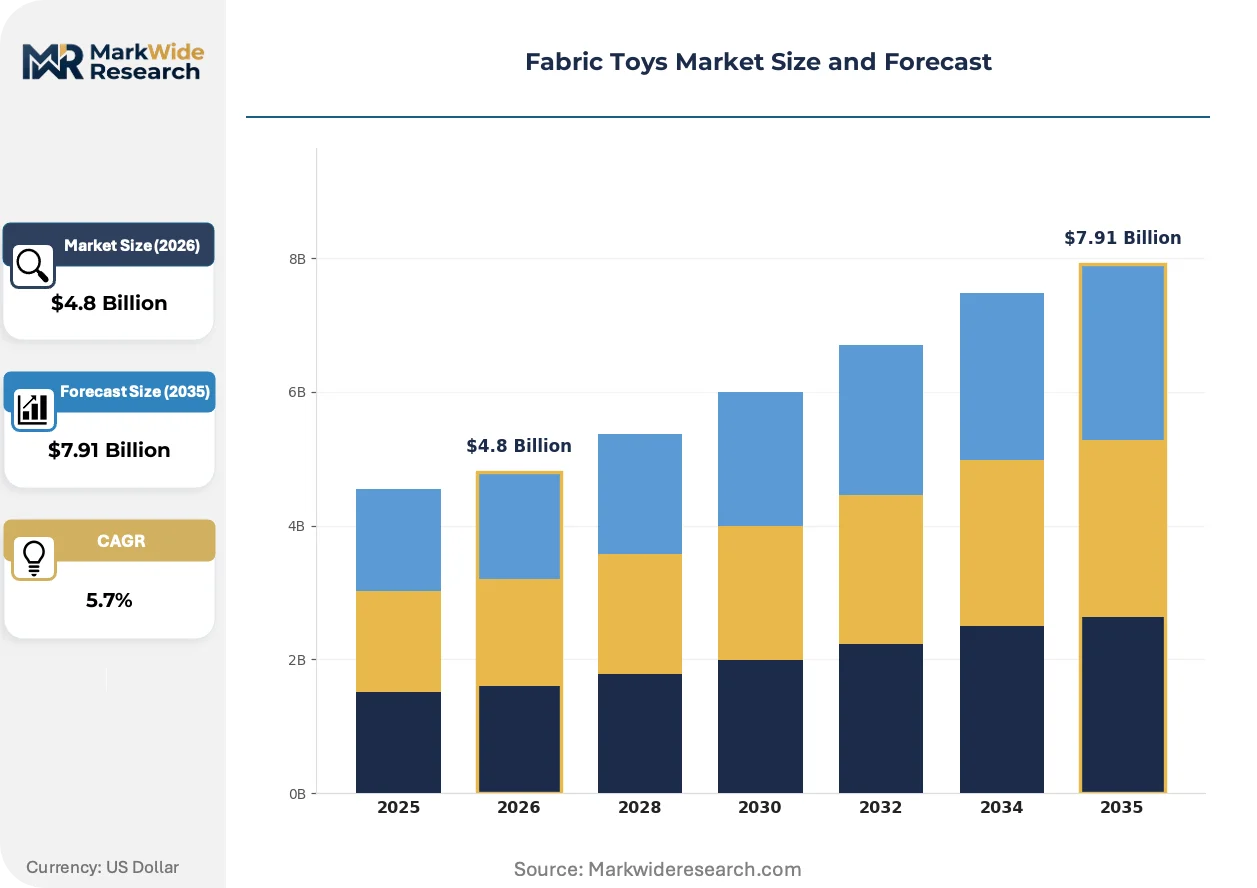
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stuffed Animals, Plush Dolls, Fabric Puzzles, Soft Blocks Age Group: Infants, Toddlers, Preschoolers, School Age End User: Parents, Educational Institutions, Retailers, Gift Shops Fabric Type: Cotton, Polyester, Fleece, Velvet |
| Companies Covered | Ty Inc., Mattel, Jellycat, Spin Master, Hasbro, Gund, Steiff, Melissa & Doug, Aurora World, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Toys Market Emerging Trajectories
Digital-physical hybridization is reshaping fabric toy value propositions, with embedded sensors and connected content layers transforming passive plush into interactive developmental tools.
Smart textile integration is unifying haptic feedback mechanisms with machine-washable construction. Premium infant product lines from Nordic design houses are embedding pressure-sensitive conductive yarns at scale. This convergence is compressing the feature gap between electronic learning toys and traditional fabric play products.
REACH Annex XVII updates are restricting azo dyes and heavy metal finishes in textile applications. Manufacturers serving European retail channels are pivoting to GOTS-certified organic colorants or undyed natural fiber palettes. The preschool segment bears the highest reformulation burden due to mouthing-age safety scrutiny.
Direct-to-institution procurement is consolidating volume for licensed childcare centers and Montessori networks. Traditional toy wholesale distributors are losing shelf influence as procurement teams at regional preschool chains negotiate annual contracts directly with manufacturers. This pattern is most pronounced in Germany's fragmented but quality-sensitive early education market.
Fabric Toys Market Segmentation
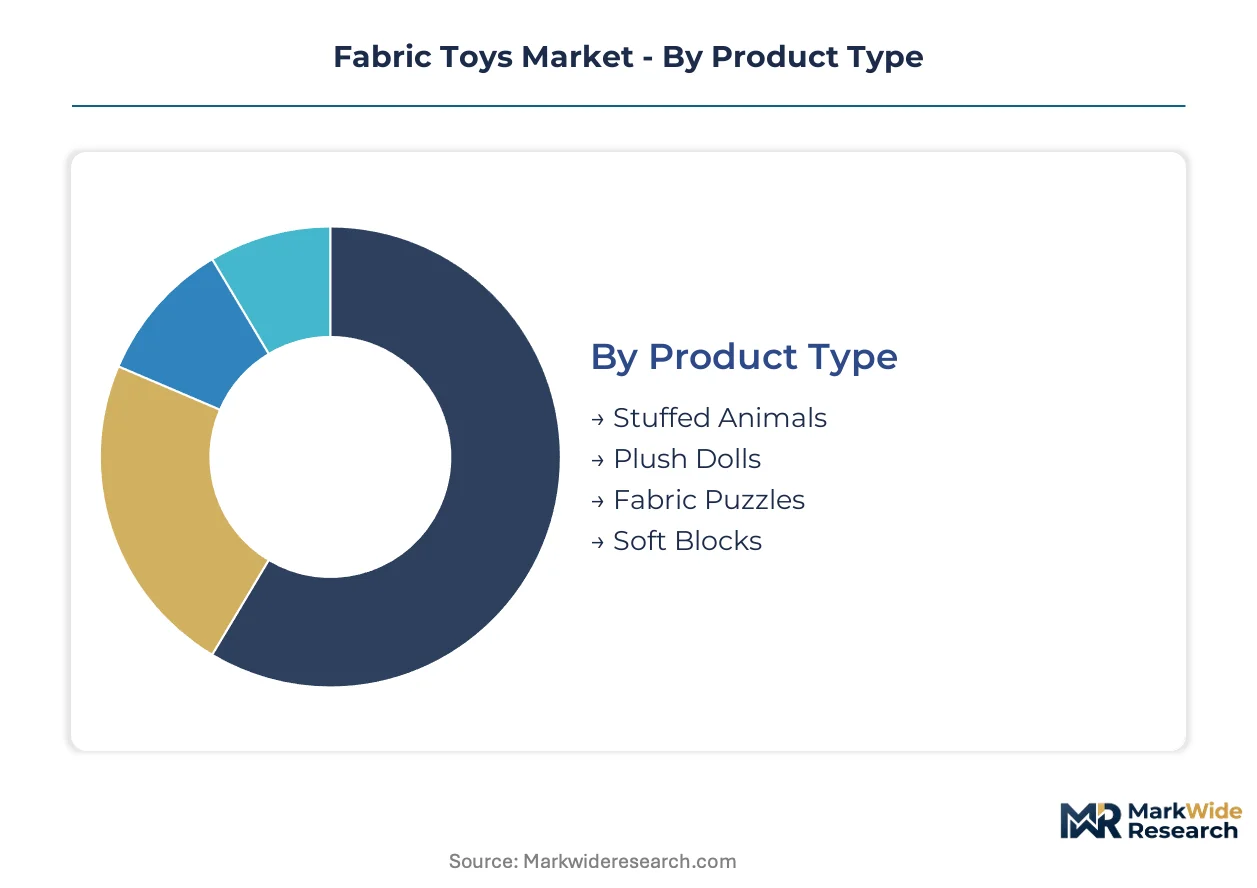
Segmentation in fabric toys reveals how material choices, age-targeted design, and channel strategies create distinct competitive arenas. Manufacturers optimize formulation and certification investments differently across these divides.
Product Type:
Replacement cycles vary dramatically—stuffed animals endure years of attachment while fabric puzzles face obsolescence as children master cognitive milestones.
- Stuffed Animals:Constructed from woven or knitted textiles with embroidered facial features and hypoallergenic fiberfill. Demand concentrates in North American and European gifting channels where British design heritage commands premium positioning.
- Plush Dolls:Character-licensed or original-design soft figures with articulated limbs and synthetic hair elements. Volume flows through mass-market retail networks backed by backward integration into entertainment IP.
- Fabric Puzzles:Textile-based cognitive toys with interlocking soft pieces. STEM-oriented parenting in OECD markets is elevating this category over pure entertainment alternatives.
- Soft Blocks:Stuffed geometric shapes with crinkle fabrics and sensory tags. Procurement teams at regional preschool chains are negotiating annual contracts directly for this developmental staple.
Stuffed animals sit at the top of the volume ranking, with fabric puzzles climbing the fastest.
Age Group:
Margin structures align with safety scrutiny intensity—mouthing-age products bear the heaviest compliance burden and certification costs.
- Infants:Products for birth to 12 months featuring undyed natural fibers and minimal detachable components. Nordic design houses are embedding pressure-sensitive conductive yarns at scale for smart textile integration.
- Toddlers:Items for 1-3 years emphasizing sensory exploration and motor skill development. India's government-funded early childhood education expansion is opening volume demand here.
- Preschoolers:Toys for 3-5 years bridging comfort objects and educational tools. Enrollment expansion across OECD member states is hardening demand for developmental fabric toys in this bracket.
- School Age:Products for 5+ years including collectible plush and craft-oriented fabric kits. Direct-to-consumer subscription services are bypassing traditional retail margins for urban households with children in this segment.
Preschoolers anchor revenue concentration given institutional procurement scale, while toddlers represent the steepest expansion trajectory.
End User:
Channel economics diverge sharply—institutional buyers consolidate volume through annual contracts while gift shops absorb premium markups for occasion-based purchases.
- Parents:Individual consumers prioritizing safety certifications and developmental claims. Millennial buyers are prioritizing cognitive development features over pure entertainment value.
- Educational Institutions:Licensed childcare centers and Montessori networks negotiating direct manufacturer relationships. Germany's fragmented early education market exhibits the most pronounced shift away from traditional wholesale distributors.
- Retailers:Mass-market chains and specialty toy stores managing seasonal inventory cycles. Guangdong's concentrated production infrastructure compresses lead times for global brand fulfillment to this channel.
- Gift Shops:Premium boutiques and museum stores emphasizing design heritage and packaging presentation. British design credentials unlock shelf access in North American and European gifting corridors.
Educational institutions are consolidating procurement fastest, though parents remain the largest absolute volume pool.
Fabric Type:
Input cost volatility separates positioning tiers—organic variants face weather-dependent harvest risk while synthetics track petrochemical indices.
- Cotton:Natural cellulosic fiber commanding premium positioning among eco-conscious buyers. GOTS-certified organic colorants are displacing conventional dyes under REACH Annex XVII pressure.
- Polyester:Synthetic polymer anchoring mass-market volume through lower unit costs and easier care requirements. Post-consumer recycling technologies are enabling circular economy claims for eco-conscious positioning.
- Fleece:Brushed synthetic knit valued for warmth and tactile softness. Heavy reliance on Zhejiang province suppliers creates geographic concentration risk for this material stream.
- Velvet:Woven pile fabric with dense cut or looped surface, historically premium but now accessible in synthetic variants. Reformulation requirements for azo dye restrictions are elevating sourcing complexity for European-bound production.
Polyester dominates absolute volume, with cotton gaining share fastest on sustainability credentialing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing fabric toy production toward jurisdictions with lower cost-of-compliance structures, while consumer markets fragment across divergent safety standards and purchasing power tiers.
United States
CPSC flammability testing and small-parts protocols extend product development cycles for US-bound shipments. The Consumer Product Safety Commission maintains strict enforcement of ASTM F963 toy safety standards. California's Los Angeles Basin hosts design studios and import distributors coordinating Guangdong-sourced finished goods.
China
Domestic preschool enrollment expansion and rising middle-class discretionary spending are hardening local demand alongside export manufacturing. GB standards for toy safety administered by SAMR impose parallel compliance layers on Pearl River Delta factories. Guangdong province concentrates polyester fleece finishing and cut-and-sew assembly for global brand fulfillment.
Germany
REACH Annex XVII chemical restrictions and eco-conscious parenting preferences elevate certified organic cotton positioning. ECHA enforcement of azo dye and heavy metal limitations compels reformulation of textile colorants. Bavaria's early education procurement networks negotiate direct manufacturer contracts, bypassing traditional wholesale channels.
India
Government-funded early childhood education expansion under the Integrated Child Development Services program is opening institutional volume demand. BIS toy safety standards create domestic certification requirements distinct from export-market protocols. Tamil Nadu's textile belt is developing cut-and-sew capacity for mid-tier developmental fabric toy production.
United Kingdom
Design heritage credentials unlock premium shelf access in North American and European gifting corridors. Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance tracking for UK-bound shipments. London-based brand houses coordinate Nordic-inspired smart textile development with Far East manufacturing partners.
Fabric Toys Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium gifting channels consolidating around design-heritage positioning while mass-market retail fragments across price-competitive portfolios. Three archetypes dominate: heritage European houses leveraging craftsmanship narratives, North American entertainment licensors exploiting character IP backward integration, and Asian contract manufacturers scaling certified organic production for private-label programs. Capacity expansion and direct-to-institution procurement consolidation represent the two dominant competitive vectors reshaping channel economics.
Within the heritage-design tier, Jellycat and Steiff exemplify British and German craftsmanship positioning that commands premium markups in museum stores and boutique gifting corridors. Mattel anchors the mass-market entertainment-licensor archetype through in-house production of character-driven plush portfolios. These three entities occupy distinct competitive spaces—heritage craftsmanship, mass-market IP exploitation, and mid-tier price positioning—without direct segment overlap.
| Leading Market Players |
|---|
| Ty Inc. |
| Mattel |
| Jellycat |
| Spin Master |
| Hasbro |
| Gund |
| Steiff |
| Melissa & Doug |
| Aurora World |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in the Pearl River Delta anchor polyester fleece production, translating concentrated ownership into pricing discipline that resists margin erosion despite REACH-driven reformulation costs. Their captive dyeing facilities absorb organic cotton price volatility while passing certification premiums to European buyers.
Pricing Analysis
Distributor margin compression in mass-market retail channels is forcing manufacturers toward direct-to-institution contracts that eliminate wholesale markups. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic lines from conventional polyester and undyed natural fiber variants. Pricing pressure stems from Zhejiang supplier concentration exposing buyers to input cost spikes. Gift shops exhibit lowest price sensitivity, absorbing British design heritage premiums, while mid-tier mass-market retailers face acute margin squeeze.
Supply Chain Analysis
Certification gating through REACH Annex XVII, CPSIA small-parts protocols, and GB standards fragments supplier eligibility across export markets. Production concentrates in China's Guangdong and Zhejiang provinces, with Tamil Nadu's textile belt emerging as alternative cut-and-sew capacity. Raw material flows draw from Xinjiang cotton (premium tier), Zhejiang polyester fiber (mass-market), and Nordic conductive yarn suppliers (smart textile tier). Single-source vulnerability in Zhejiang fleece finishing creates geographic risk exposure. Distribution runs through Los Angeles Basin import distributors coordinating Guangdong-sourced finished goods for North American retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where REACH compliance costs in Germany diverge from India's BIS certification burden, creating margin capture opportunities for dual-certified producers.
For Market Incumbents: To counter direct-to-institution procurement consolidation, Mattel and heritage European houses should deepen backward integration into GOTS-certified organic cotton sourcing while securing annual volume contracts with Germany's fragmented preschool chains. Channel control through captive distribution in Bavaria's early education networks offers defensive positioning.
For New Entrants and Emerging Players: India's government-funded ICDS procurement teams represent an underserved buyer archetype with volume scale and lower certification barriers than OECD markets. Mid-tier developmental fabric toys for toddlers offer the most penetrable segment. A go-to-market angle through Tamil Nadu textile belt partnerships bypasses established Guangdong supplier relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with dual REACH-GB certification capabilities and underutilized smart textile R&D pipelines. Long-term viability hinges on waste-to-textile conversion technology maturation. The signal to watch is post-consumer polyester recycling yield rates achieving commercial scale.
| Strategic Initiative | Industry Significance |
|---|---|
| GOTS-Certified Organic Sourcing | REACH Annex XVII compliance secures European retail shelf access against azo dye restrictions. |
| Direct-to-Institution Contracts | Bavaria's preschool procurement networks bypass traditional wholesale margin structures entirely. |
| Smart Textile Integration | Nordic design houses embed pressure-sensitive conductive yarns for interactive developmental tools. |
| Waste-to-Textile Conversion | Post-consumer polyester recycling enables circular economy claims for eco-conscious positioning. |
| Tamil Nadu Capacity Expansion | India's ICDS program opens institutional volume demand with lower compliance cost structures. |
Methodological Framework
Multiple input streams — structured interviews with preschool procurement directors and Montessori network administrators, trade data from Guangdong and Zhejiang customs authorities, and REACH regulatory filings — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from CPSC enforcement records, ECHA restriction updates, and OECD preschool enrollment statistics. Primary fieldwork encompassed brand managers at heritage European houses, category buyers at North American mass-market retailers, and plant managers at Tamil Nadu textile facilities.
Historical shipment volumes from Pearl River Delta export zones were cross-referenced against panel input from procurement teams at German early education networks. The analytical framework segmented across product type, age bracket, fabric certification tier, and channel structure throughout the forecast period. CAGRs were derived from enrollment-driven demand elasticity modeling and substitution effects between polyester and organic cotton variants. Forecast inputs incorporated REACH Annex XVII amendment timelines and India's ICDS infrastructure buildout pace.
Underlying measurement precision varies by segment; institutional procurement volumes carry tighter precision than gift channel estimates due to contract transparency. Forecasts reflect documented assumptions about compliance cost pass-through rates and raw material substitution elasticities. A model refresh is warranted upon material change in REACH chemical restriction lists or India's BIS toy safety standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Dartboard Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Table Top Games Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Sustainable Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
US Sex Toys Market
Toys and Games
Toys and Games Market
Toys and Games
Claw Crane Machine Market
Toys and Games
United States Toys Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
Bubble Blower Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Bath Toy Market
Toys and Games
Children Entertainment Centers Market