
 Blind Box Toys Market | 2026-2036
Blind Box Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Box Toys Market Insights
Asset-light licensing and royalty-based manufacturing is reshaping competitive entry in blind box toys, lowering capital barriers for new IP holders. POP MART leverages its designer-artist ecosystem to sustain premium pricing power across Greater China. Funko anchors North American distribution through mass retail partnerships and entertainment licensing. Bandai dominates Japan's character-goods segment with decades-long anime and tokusatsu IP control.
Blind box toys are sealed, randomized-package collectibles containing undisclosed figures from a defined series, typically manufactured through injection-molded PVC or rotocast vinyl processes with proprietary IP licensing. Their commercial purpose centers on repeat-purchase behavior driven by scarcity mechanics, social sharing, and secondary-market trading value. Collectible figures occupy the dominant margin pool due to higher per-unit ASPs and stronger resale premiums, while plush toys represent the fastest-growing material category as softness appeals broaden the addressable base beyond traditional figure collectors. Distribution through online retail channels captures accelerating volume as live-stream commerce and social-platform storefronts displace conventional toy store foot traffic.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards that govern small-part choking hazards and phthalate limits in vinyl blind box production. China's State Administration for Market Regulation implements GB 6675 national toy safety standards alongside enhanced IP protection rules that affect licensed character merchandise. The EU's REACH regulation and ECHA chemical restrictions constrain certain plasticizer formulations used in European-bound vinyl collectibles. Stakeholders must monitor evolving chemical compliance thresholds and platform-specific resale regulations that could alter both manufacturing cost structures and secondary-market liquidity.
Market Dynamics
Social commerce platforms and live-streaming unboxing culture are compressing traditional retail cycles, converting entertainment consumption directly into purchase behavior without intermediary discovery phases.
Growth Catalysts
- REACH chemical standards:The EU's tightening material compliance requirements are accelerating R&D investment in bio-based vinyl alternatives, creating first-mover advantages for compliant manufacturers.
- Injection-molded PVC process innovation:Advanced rotocasting techniques are reducing per-unit production waste and enabling smaller batch runs for limited-edition releases.
- Urban China cluster density:Tier-one city retail ecosystems in Shanghai, Beijing, and Shenzhen concentrate IP licensing negotiations and collector community formation.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer feedstock costs fluctuate with crude oil benchmarks, compressing margin predictability for vinyl figure production.
- Single-source mold fabrication:Precision steel tooling for injection-molded figures concentrates with specialized Guangdong and Zhejiang suppliers, creating geographic supply risk.
- Phthalate substitution complexity:REACH and GB 6675 divergent chemical restrictions force dual-formulation inventory holding for cross-border shipments.
Strategic Opportunities
- Southeast Asia platform expansion:Indonesia, Vietnam, and Thailand present underpenetrated social commerce infrastructure for blind box distribution beyond established China networks.
- Plush material segment crossover:Soft-goods manufacturing expertise from apparel supply chains is hybridizing with collectible IP licensing to capture non-figure collectors.
- Secondary-market authentication services:Blockchain-verified provenance systems are emerging to reduce counterfeit friction in peer-to-peer trading.
Industry Challenges
- Designer-artist contract negotiation:IP holder exclusivity terms and royalty rate disputes complicate multi-year collaboration planning.
- GB 6675 certification timelines:China's national toy safety testing backlog delays product launch windows during peak seasonal demand.
- Live-stream inventory forecasting:Real-time unboxing momentum creates demand spikes that outpace rotocast production lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Box Toys Market |
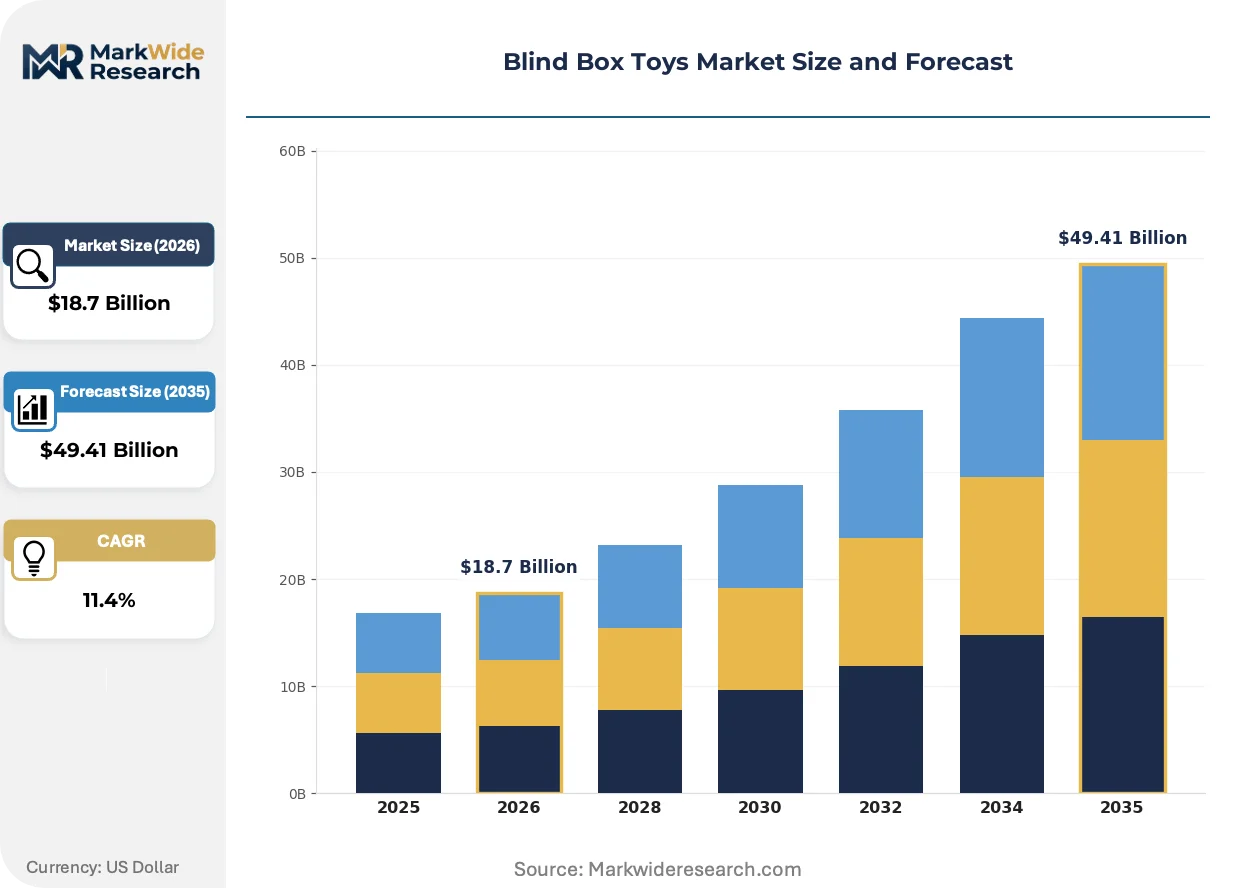
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collectible Figures, Plush Toys, Action Figures, Figurines Material: Plastic, Vinyl, Fabric, Cardboard Target Age Group: Toddlers, Preschool, Children, Teens Distribution Channel: Online Retail, Toy Stores, Department Stores, Specialty Shops |
| Companies Covered | POP MART, Funko, 52Toys, MINISO, LEGO, Kidrobot, Bandai, Sonny Angel, Medicom Toy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Box Toys Market Trends and Innovations
Digital-physical convergence is dissolving boundaries between virtual collecting and tangible ownership, with augmented reality and NFT-linked figures creating hybrid consumption experiences.
Near-field communication (NFC) chip embedding is hybridizing physical blind box figures with digital verification layers. Premium collectors in Shanghai and Shenzhen are adopting NFC-enabled authentication for high-value secondary trades. This technology is hybridizing traditional manufacturing with software-defined ownership records, compressing trust establishment costs.
China's SAMR enhanced IP protection rules are tightening enforcement against unauthorized character merchandise. Manufacturers now face accelerated takedown procedures and statutory damage calculations for unlicensed production. Vinyl figure exporters targeting European markets are responding with parallel trademark registration strategies.
Collector communities are fragmenting into micro-segmented affinity groups organized around specific artists rather than broad IP franchises. Social platform algorithms on Xiaohongshu and Douyin are replacing conventional toy retail discovery. This behavioral shift concentrates most visibly in Beijing's designer toy subcultures where artist-direct drops bypass distributor markups entirely.
Blind Box Toys Market Segmentation
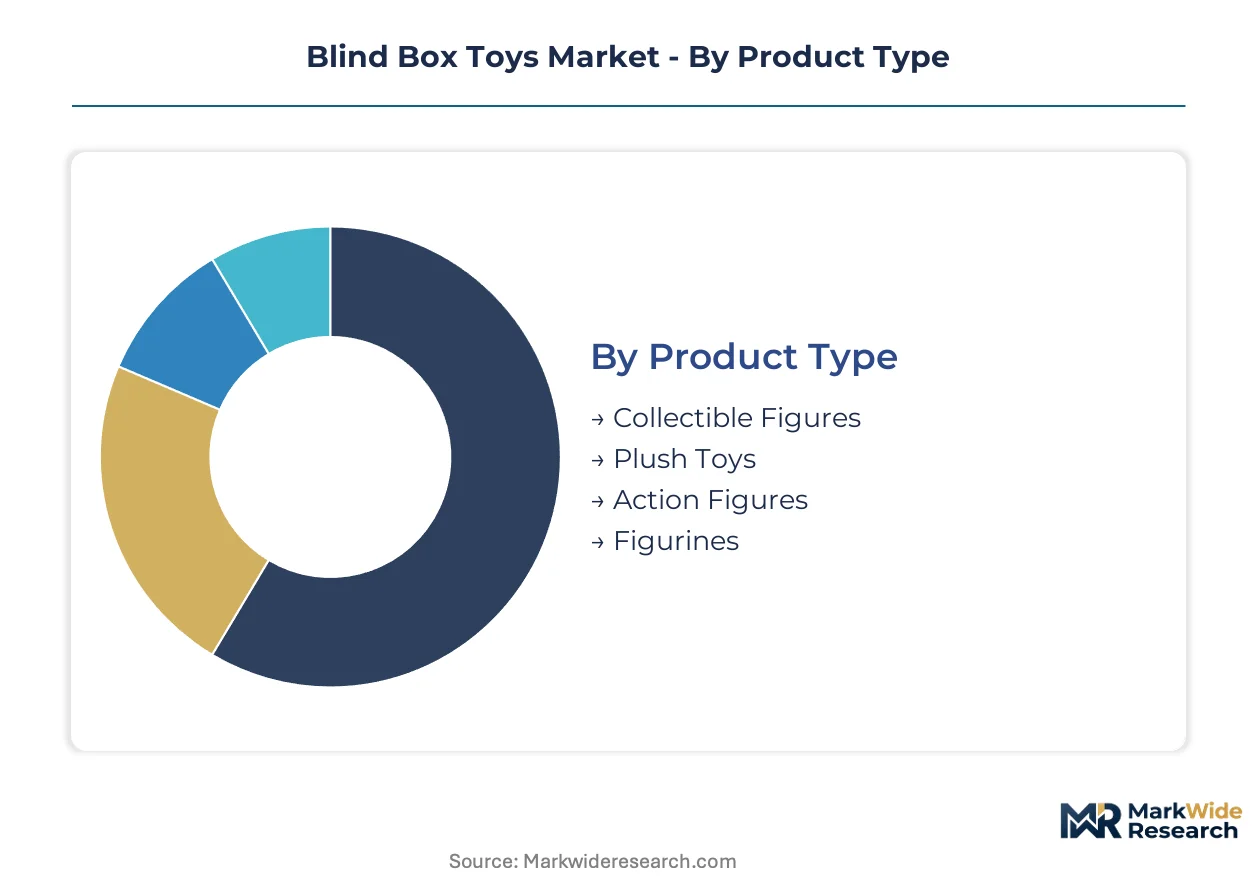
Segmentation in blind box toys determines inventory velocity, margin architecture, and platform selection. Cycle times vary dramatically across product types and channels, with some segments turning weekly while others anchor seasonal collections. Understanding these rhythms separates operational leaders from inventory-trapped competitors.
Product Type:
Collectible figures compress restock cycles to under fourteen days in Shanghai and Shenzhen, while plush toys stretch toward seasonal replenishment patterns. Action figures and figurines occupy intermediate turnover bands tied to entertainment release calendars.
- Collectible Figures:Injection-molded PVC or rotocast vinyl constructions with proprietary IP licensing drive the dominant margin pool. Demand concentrates in Beijing's designer-artist subcultures where live-stream unboxing converts entertainment consumption directly into purchase behavior without intermediary discovery phases.
- Plush Toys:Soft-goods manufacturing hybridizes with collectible IP licensing to capture non-figure collectors. Fabric-based construction appeals broaden the addressable base beyond traditional figure collectors, with demand accelerating fastest in tier-one Chinese cities where softness preferences diverge from vinyl aesthetics.
- Action Figures:Articulated joints and poseable limbs target entertainment franchise collectors with longer development cycles tied to theatrical and streaming release windows.
- Figurines:Static display pieces emphasize sculptural detail over play functionality, serving premium shelf-space collectors with extended pre-order horizons.
Collectible figures anchors the volume base while plush toys gains share at the steepest rate.
Material:
Cost tier stratification separates premium vinyl formulations from commodity plastic and cardboard, with compliance chemistry driving effective margin compression at each tier.
- Vinyl:Rotocast vinyl processes enable complex surface textures and color layering that command premium ASPs. REACH chemical standards and GB 6675 divergent phthalate restrictions force dual-formulation inventory holding for cross-border shipments, compressing margin predictability for European-bound production.
- Plastic:Injection-molded PVC dominates unit economics through Guangdong and Zhejiang supplier concentration. Petrochemical input volatility with crude oil benchmarks creates margin unpredictability that specialized mold fabricators partially hedge through long-term resin contracts.
- Fabric:Textile-based construction leverages apparel supply chain expertise for plush crossover expansion.
- Cardboard:Lowest material tier serves promotional and entry-price positioning with minimal compliance burden.
Vinyl commands premium positioning while plastic delivers volume scale through manufacturing concentration.
Target Age Group:
Customer type determines safety certification intensity, with toddler and preschool segments triggering GB 6675 and ASTM F963 small-part testing backlogs that delay launch windows.
- Teens:Young adult collectors in urban China drive adoption through social commerce platforms and live-streaming unboxing culture. This demographic concentrates in Shanghai, Beijing, and Shenzhen where IP-driven retail ecosystems thrive and secondary-market trading value sustains repeat-purchase behavior.
- Children:School-age collectors balance parental purchase approval with peer social currency, creating dual-influencer decision structures.
- Preschool:Safety certification intensity peaks here with GB 6675 testing timelines compressing seasonal launch flexibility.
- Toddlers:ASTM F963 small-part choking hazard governance and phthalate limits impose the strictest material compliance requirements.
Teens generate the highest per-capita spend velocity while toddlers impose the steepest compliance cost burden.
Distribution Channel:
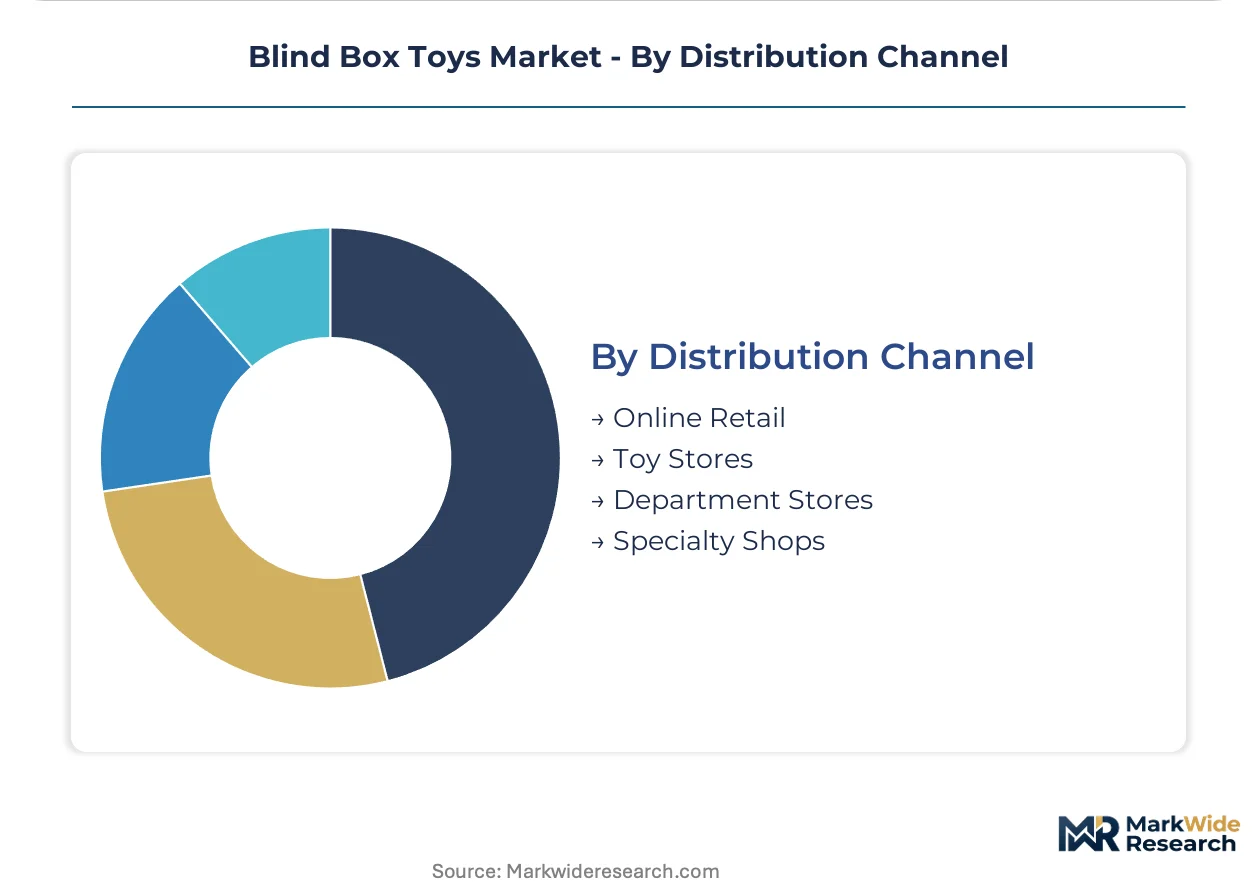
Channel selection determines working capital intensity and demand forecasting precision, with online retail compressing inventory cycles while specialty shops extend curation horizons.
- Online Retail:Social-platform storefronts and live-stream commerce displace conventional toy store foot traffic. Real-time unboxing momentum creates demand spikes that outpace rotocast production lead times, forcing buffer inventory strategies that strain working capital.
- Specialty Shops:Curated physical discovery environments sustain premium positioning for limited-edition drops. Beijing's designer toy subcultures leverage artist-direct relationships that bypass distributor markups entirely.
- Toy Stores:Mass retail partnerships anchor North American volume distribution through entertainment licensing tie-ins.
- Department Stores:Intermediate positioning between specialty curation and mass velocity, with seasonal display allocation determining SKU survival.
Online retail captures accelerating volume share while specialty shops defend margin through curation authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished blind box collectibles while importing specialized mold steel and phthalate-free plasticizers from Germany and Japan. The trade flow concentrates manufacturing value-add in Guangdong while sourcing compliance-grade materials from precision chemical suppliers in advanced economies.
China
Shanghai and Beijing collector communities drive live-stream commerce adoption through Xiaohongshu and Douyin platforms. SAMR enforces GB 6675 toy safety standards alongside enhanced IP protection rules that accelerate takedown procedures for unauthorized merchandise. Shenzhen anchors the designer-artist ecosystem where POP MART cultivates exclusive creator relationships.
United States
Mass retail partnerships and entertainment licensing sustain volume distribution through big-box toy channels. The CPSC enforces ASTM F963 standards governing small-part choking hazards and phthalate limits in vinyl production. Los Angeles and New York City concentrate specialty shop curation and secondary-market trading infrastructure.
Japan
Decades-long anime and tokusatsu IP control sustains character-goods demand across generational collector bases. METI oversees product safety through Consumer Product Safety Act enforcement aligned with international toy standards. Tokyo's Akihabara and Nakano Broadway districts anchor physical retail discovery for limited-edition drops.
Germany
ECHA REACH chemical restrictions constrain plasticizer formulations used in European-bound vinyl collectibles, forcing formulation adaptation. The EU Toy Safety Directive mandates CE marking and material traceability for all imported play products. Berlin and Munich host curated designer toy boutiques that bridge Asian IP imports with continental collector access.
South Korea
MFDS cosmetic-grade material standards are hybridizing with toy safety protocols as character goods cross into lifestyle merchandise categories. Seoul's Hongdae district concentrates independent artist studios and pop-up retail experiments. Busan-Ulsan manufacturing corridors supply rotocast vinyl capacity for regional brand production.
Blind Box Toys Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mold fabrication and chemical formulation. The vendor base separates into IP licensors, manufacturing contractors, and distribution platforms with minimal overlap between functions. Three archetypes dominate: artist-ecosystem curators, mass-retail licensors, and specialty fabricators. Competitive moves concentrate on exclusive IP lockups and direct-to-consumer channel construction.
Within the artist-ecosystem tier, POP MART exemplifies platform-integrated curation through designer exclusivity structures. Funko occupies the mass-licensing position anchored in entertainment property partnerships. Bandai represents the heritage fabricator archetype with decades-long character IP control. These three sit at different coordinates of the value chain without direct overlap in core competencies.
| Leading Market Players |
|---|
| POP MART |
| Funko |
| 52Toys |
| MINISO |
| LEGO |
| Kidrobot |
| Bandai |
| Sonny Angel |
| Medicom Toy |
| Others |
Pricing and Supply Chain Analysis
REACH chemical chokepoints in European-bound vinyl formulations compress margin architecture across premium and mass-market tiers while forcing dual-inventory holding patterns that reshape supplier geography. Guangdong mold fabricators exploit this regulatory fragmentation to capture pricing power through compliant-batch certification premiums.
Pricing Analysis
Young adult collectors in Shanghai and Shenzhen anchor three-tier pricing structure across premium artist editions, standard IP releases, and economy blind-box entry points. Price differentiation rests on NFC authentication inclusion and GB 6675 certification grade. Cost compression in the economy tier intensifies because petrochemical resin volatility outpaces rotocast production efficiency gains. Mass-market channel buyers exhibit highest price sensitivity; limited-edition drop participants show lowest.
Supply Chain Analysis
PVC resin and phthalate-free plasticizer feedstock dependency draws from German and Japanese specialty chemical suppliers, with rotocast vinyl production anchored in Guangdong and Zhejiang provinces. Steel tooling fabrication sources from Shenzhen precision mold houses. Single-source vulnerability concentrates in REACH-compliant formulation batches. Distribution runs through Xiaohongshu and Douyin social commerce platforms displacing conventional toy retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NFC-enabled authentication hybridization signals high-growth disruption as physical-digital convergence redefines collector ownership verification. SAMR enhanced IP protection rules accelerate enforcement velocity against unauthorized production.
For Market Incumbents: Build designer-artist exclusivity moats through multi-year royalty contracts locking emerging creators before rival platform recruitment. Secure backward integration into rotocast vinyl capacity in Busan-Ulsan corridors to hedge Guangdong supply concentration. Counter Funko's mass-licensing threat with limited-batch scarcity mechanics that sustain secondary-market premium capture. For New Entrants and Emerging Players: Southeast Asian social commerce white-space in Jakarta, Bangkok, and Ho Chi Minh City represents the most penetrable entry point where live-stream infrastructure lags Chinese platform maturity. Plush-material crossover segments attract non-vinyl collectors with lower mold-fabrication capital barriers. Pursue artist-direct drop models bypassing distributor markups entirely. For Investors and Strategic Acquirers: ECHA REACH chemical restriction evolution reshapes the acquisition landscape toward compliant-formulation specialists with European market access. Five-to-ten-year viability favors platform-integrated curators over pure manufacturing contractors. Signal to watch: blockchain-authentication patent filings indicating secondary-market infrastructure buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Designer-Artist Exclusivity Lockups | POP MART's creator ecosystem model secures premium pricing power through scarcity-controlled IP drops. |
| REACH-Compliant Formulation R&D | Bio-based vinyl alternatives create first-mover manufacturing advantages for European market entry. |
| Southeast Asia Platform Expansion | Indonesia and Thailand social commerce infrastructure gaps offer distribution channel preemption. |
| NFC Authentication Integration | Shanghai collector adoption of chip-enabled provenance reduces counterfeit friction in high-value trades. |
| Plush Material Segment Entry | Fabric-based construction leverages apparel supply chains to capture softness-preference collectors. |
Research Methodology
Operator-level perspectives from blind box brand managers, rotocast vinyl plant engineers, Xiaohongshu live-stream hosts, and specialty toy shop curators anchored the qualitative base. Secondary validation drew from SAMR enforcement bulletins, ECHA REACH restriction updates, customs trade data for vinyl figure exports, and platform commerce transaction disclosures. Bottom-up SKU velocity modeling triangulated against top-down market sizing across the analysis window.
Scenario-bracketing framed volume projections across product type, material chemistry tier, distribution channel, and target age group dimensions. CAGRs derived from segment-level growth rate reconciliation with macro consumption indicators. Forecast inputs incorporated live-stream commerce penetration curves and GB 6675 certification timeline backlogs affecting seasonal launch windows.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks and yuan-euro exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding social platform algorithm stability and collector community fragmentation velocity. Cross-checking against customs export volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Smart/AI Toys Market
Toys and Games
Cat Toys Market
Toys and Games
Inflatable Toys Market
Toys and Games
US Sex Toys Market
Toys and Games
Coaster Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Wooden Toys Market
Toys and Games
Smart Toys Market
Toys and Games
Construction Toys Market
Toys and Games
Animation Toys Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Ferret Toys Market
Toys and Games
Plush Toy Market
Toys and Games
Orbital Action Jigsaw Market