
 Children Entertainment Centers Market | 2026-2036
Children Entertainment Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Children Entertainment Centers Market Analysis
Aftermarket service revenue from birthday packages and membership renewals is narrowing the margin gap against one-time entry fees. Dave & Buster's leverages its hybrid adult-family positioning to sustain higher per-capita spending across arcade-dining formats. CEC Entertainment anchors the traditional children's birthday segment through Chuck E. Cheese's brand strength in suburban markets. KidZania competes on immersive educational role-play, differentiating its offering from conventional ride-and-game facilities.
Children entertainment centers comprise purpose-built facilities combining physical play structures, electronic games, live entertainment, and food service designed for supervised family recreation. ASTM F1487 governs playground equipment safety, while ASTM F2291 addresses ride system design, establishing baseline engineering parameters for facility construction and operation. Family Entertainment Centers occupy the largest revenue pool by facility type, integrating multi-generational appeal that extends dwell time and ancillary spending. Educational Activities within the Entertainment Offering dimension represent the fastest-growing segment as parents prioritize developmental value alongside entertainment.
ASTM International sets voluntary consensus standards for amusement device safety across US-based operations, while the Consumer Product Safety Commission monitors incident reporting and recall enforcement for equipment-related injuries. China's Standardization Administration issues GB standards for large amusement facility safety, creating compliance thresholds for imported ride systems and domestic manufacturing. Facility operators must monitor evolving accessibility mandates from the Department of Justice ADA requirements and local fire marshal capacity regulations that directly impact layout design and throughput economics.
Market Dynamics
Family Entertainment Centers face intensifying pressure from ASTM F24 safety standard revisions that extend certification timelines and inflate capital deployment requirements for ride system operators. The shift toward educational-entertainment hybrid formats is compressing traditional arcade-dining economics while opening adjacent revenue pools.
Growth Catalysts
- Educational-Entertainment Convergence:Parental preference for developmental value alongside play is expanding facility programming into STEM-based role-play and interactive learning modules.
- Suburban Retail Corridor Revitalization:Mall operators in the United States and United Kingdom are offering favorable lease terms to anchor tenants that drive multi-hour family dwell time.
- ASTM F1487 Compliance Infrastructure:Standardized playground equipment safety protocols reduce liability exposure and enable insurer-backed financing for facility expansions.
Market Restraints
- Steel and Electronics Input Volatility:Ride system manufacturing depends on specialized steel alloys and semiconductor components subject to supply concentration in East Asian foundries.
- Regulatory Friction from ADA Title III:Department of Justice accessibility mandates require costly facility retrofits that extend project timelines by 8-14 months.
- Home Entertainment Substitution:Immersive gaming consoles and streaming platforms capture discretionary family spending previously allocated to out-of-home recreation.
Strategic Opportunities
- India Tier-II City Penetration:Underdeveloped organized play infrastructure in cities like Pune and Jaipur offers first-mover positioning for branded facility formats.
- Membership-Subscription Models:Monthly recurring revenue structures reduce seasonality exposure and improve lifetime value metrics against one-time admission economics.
- GB Standard Alignment in China:Domestic manufacturing certification under Standardization Administration protocols opens procurement cost advantages for locally sourced ride systems.
Industry Challenges
- Certified Ride Technician Scarcity:ASTM F2291 inspection protocols require specialized mechanical engineering expertise that outpaces vocational training program output.
- Legacy POS Integration Complexity:Ticketing and food service systems from the 2010s resist API connectivity with modern membership management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Entertainment Centers Market |
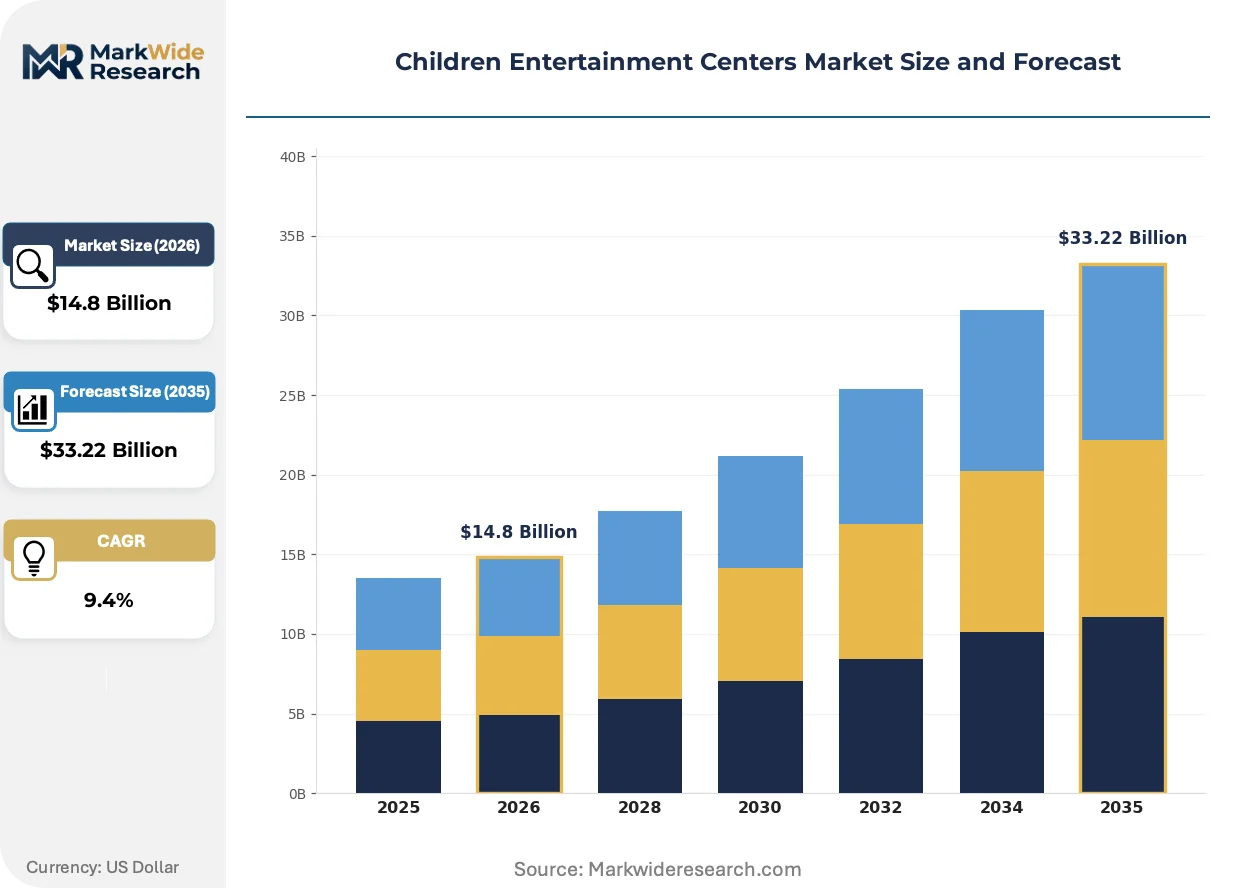
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Playgrounds, Outdoor Parks, Family Entertainment Centers, Arcade Venues Target Age Group: Toddlers, Preschoolers, School-Age Children, Preteens Entertainment Offering: Games, Rides, Educational Activities, Themed Events Revenue Model: Entry Fees, Memberships, Snack Sales, Birthday Packages |
| Companies Covered | The Walt Disney Company, Dave & Buster's, CEC Entertainment, Cinergy Entertainment Group, KidZania, Scene75 Entertainment Centers, LEGOLAND Discovery Center, Chuck E. Cheese, Lucky Strike Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Entertainment Centers Market Emerging Trajectories
Digital augmentation of physical play environments is compressing the gap between passive entertainment and active participation, forcing facility operators to reconfigure floor plans around immersive technology rather than traditional mechanical rides.
RFID-enabled wristband systems are migrating from simple access control to full-stack behavioral tracking platforms. Family Entertainment Center operators in the United States deploy these devices to capture dwell-time patterns and trigger dynamic pricing for food service. The data infrastructure is migrating from siloed arcade management systems to unified cloud architectures that enable predictive maintenance scheduling.
ASTM International's accelerated revision cycle for F24 amusement ride standards is compressing equipment depreciation schedules. Facility operators must now budget for mid-life safety retrofits that previously fell outside capital planning horizons. The United Kingdom's Health and Safety Executive has adopted analogous inspection frequencies, extending compliance cost pressure across Atlantic operations.
Parents now prioritize booking flexibility over package bundling when selecting birthday event venues. This behavioral pivot is fragmenting the traditional Saturday-morning reservation concentration that anchored facility staffing models. China's first-tier cities exhibit the most pronounced shift, with mobile-native parents demanding real-time availability transparency through mini-program interfaces rather than telephone bookings.
Children Entertainment Centers Market Segmentation
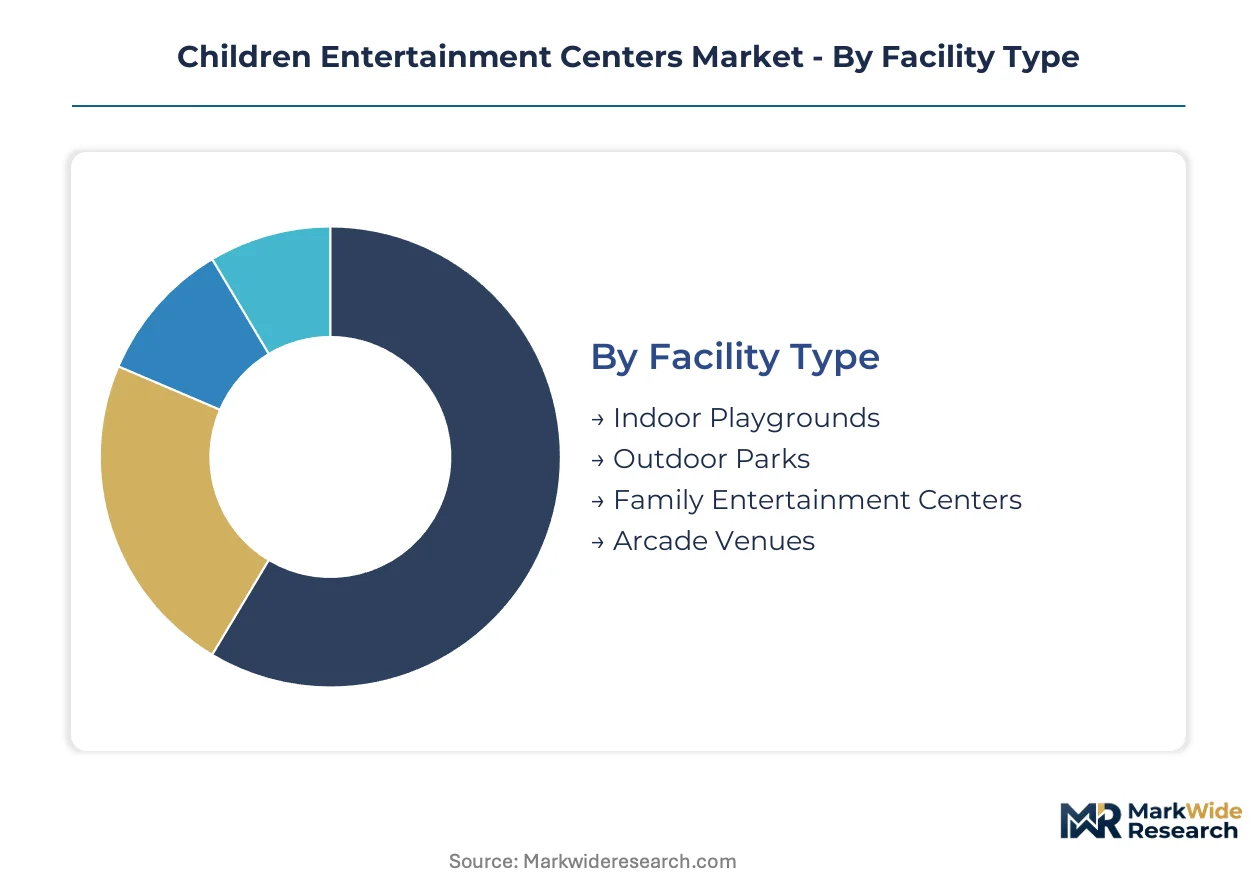
Segmentation in children entertainment centers reveals how facility economics diverge across operational models and customer life stages. Operators must align capital intensity, safety protocols, and programming depth with distinct revenue per visitor profiles.
Facility Type:
Mature formats anchor suburban retail corridors while emerging concepts compress development timelines through modular construction.
- Indoor Playgrounds:Climate-controlled structures featuring soft-play equipment, ball pits, and climbing frames engineered to ASTM F1487 specifications. Demand clusters in United Kingdom retail parks where mall operators prioritize year-round foot traffic generators over seasonal tenants.
- Outdoor Parks:Weather-dependent facilities incorporating splash pads, adventure courses, and nature-based play landscapes. United States municipal park districts in Texas and Florida drive procurement through public-private partnership structures that transfer operational risk to concessionaires.
- Family Entertainment Centers:Hybrid venues integrating arcade systems, dining service, and multi-generational attractions. These facilities command the highest per-capita spend through extended dwell times.
- Arcade Venues:Electronics-focused formats emphasizing ticket-redemption games and prize merchandising. Capital requirements run lower than full-service competitors but face acute pressure from home gaming substitution.
Family Entertainment Centers handle the majority of throughput; Educational-Entertainment hybrid formats are gaining share fastest.
Target Age Group:
Programming depth and supervision ratios vary sharply across developmental stages, dictating staffing models and liability exposure.
- Toddlers:Sensory-motor play zones requiring 1:4 staff-to-child ratios and padded surfacing throughout. United States franchise operators in this segment face elevated insurance premiums that compress unit economics.
- Preschoolers:Imaginative play structures and simple mechanical rides designed for 3-5 year old physical capabilities. China's first-tier cities exhibit concentrated demand as dual-income households outsource supervised recreation.
- School-Age Children:Competitive gaming formats and skill-based attractions targeting 6-12 year olds with independent mobility. This cohort generates the highest birthday package attachment rates.
- Preteens:Social-oriented environments emphasizing group activities and limited-adult supervision. Operators struggle to retain this demographic against mobile gaming and streaming platform competition.
School-Age Children drive the volume base; Preteens show the steepest churn risk requiring format innovation.
Entertainment Offering:
Content mix determines capital turnover velocity and repeat visit frequency across facility portfolios.
- Games:Electronic and redemption-based systems requiring continuous hardware refresh cycles. Semiconductor supply constraints from East Asian foundries extend equipment lead times.
- Rides:Mechanical attractions governed by ASTM F24 inspection protocols and GB standards in China. Certified technician scarcity inflates maintenance costs beyond depreciation schedules.
- Educational Activities:STEM-based role-play and interactive learning modules. Parental preference for developmental value is expanding this category most quickly.
- Themed Events:Character appearances, seasonal programming, and private celebration hosting. These offerings command premium pricing but require volatile intellectual property licensing.
Games absorb the largest fixed capital deployment; Educational Activities are climbing the fastest on revenue contribution.
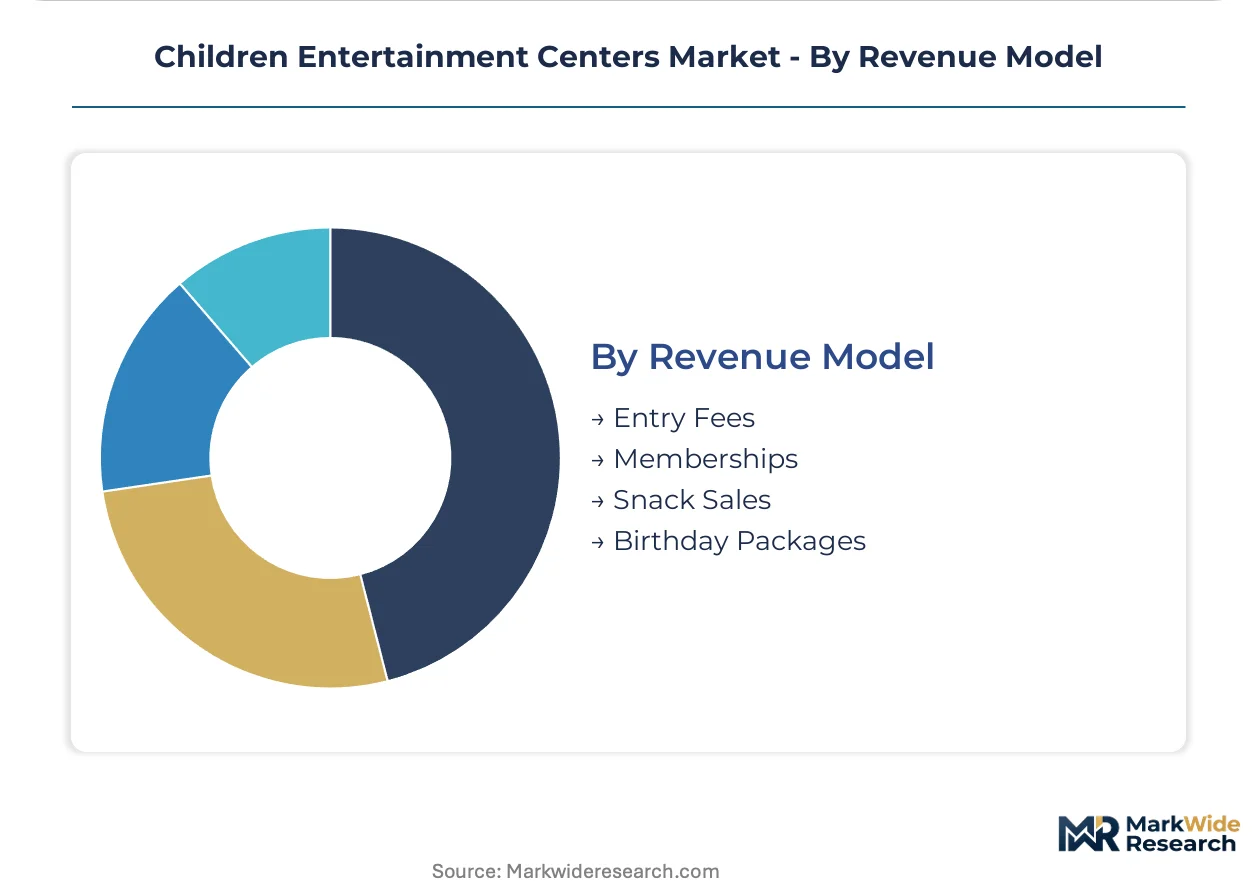
Revenue Model:
Recurring revenue structures are displacing transactional economics as operators seek predictable cash flow.
- Entry Fees:Single-visit admission pricing vulnerable to weather and discretionary spending cyclicality. United Kingdom operators have compressed this share through dynamic pricing algorithms.
- Memberships:Monthly subscription models reducing seasonality exposure and improving lifetime value metrics. China's mobile-native parents demonstrate highest enrollment velocity through mini-program interfaces.
- Snack Sales:Food service margins subsidizing attraction economics. Health-conscious menu requirements from municipal regulators in California and New York constrain traditional concession profiles.
- Birthday Packages:Bundled event hosting with tiered service levels. Booking fragmentation toward flexible scheduling is eroding the Saturday-morning concentration that anchored staffing models.
Entry Fees still process the highest transaction count; Memberships are expanding most quickly as share of recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Parents in China and the United Kingdom demonstrate highest willingness-to-pay for educational-entertainment hybrids, while Indian and Brazilian markets remain highly elastic on entry fees.
United States
Suburban retail corridor revitalization drives facility expansion, with mall operators offering favorable lease terms to anchor tenants. ASTM F24 and F1487 standards govern ride system and playground safety, extending certification timelines. Texas and Florida municipal park districts lead procurement through public-private partnerships that transfer operational risk to concessionaires.
China
First-tier city dual-income households outsource supervised recreation at premium rates, while Tier-II cities present first-mover opportunities. Standardization Administration GB standards for large amusement facilities create compliance thresholds for imported ride systems. Shanghai and Beijing clusters concentrate immersive educational role-play concepts targeting mobile-native parents demanding real-time booking transparency.
United Kingdom
Retail park operators prioritize year-round foot traffic generators over seasonal tenants, concentrating demand in climate-controlled indoor formats. Health and Safety Executive inspection frequencies match ASTM International's accelerated revision cycle, compressing equipment depreciation schedules. Greater London and Midlands retail corridors anchor Family Entertainment Center penetration.
India
Underdeveloped organized play infrastructure in Pune and Jaipur offers branded facility format opportunities, though price elasticity constrains premium positioning. Central Electricity Authority regulations intersect with state-level entertainment tax structures. Maharashtra and Gujarat industrial clusters support domestic ride system component fabrication, reducing import dependency.
Germany
Engineering-intensive ride system manufacturing concentrates in Bavaria and Baden-Württemberg, supplying equipment globally. CE marking and machinery directives establish safety baselines for facility imports. Munich and Stuttgart metropolitan areas demonstrate stable demand for educational-entertainment hybrids as parental prioritization of developmental value aligns with cultural preferences.
Children Entertainment Centers Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player tiers: global entertainment conglomerates with intellectual property portfolios, regional facility operators optimizing suburban retail economics, and specialized educational-entertainment hybrids. Strategic moves center on membership-subscription model adoption and modular facility format replication to compress development timelines.
Within the hybrid adult-family positioning tier, Dave & Buster's exemplifies arcade-dining format economics, while CEC Entertainment anchors traditional children's birthday segments through franchise density. KidZania occupies the immersive educational role-play archetype, differentiating against conventional ride-and-game facilities. These three represent distinct strategic postures rather than direct competitive overlap.
| Leading Market Players |
|---|
| The Walt Disney Company |
| Dave & Buster's |
| CEC Entertainment |
| Cinergy Entertainment Group |
| KidZania |
| Scene75 Entertainment Centers |
| LEGOLAND Discovery Center |
| Chuck E. Cheese |
| Lucky Strike Entertainment |
| Others |
Supply Flow & Price Mechanics
Undercapacity in certified ride technician training programs across the United States and United Kingdom simultaneously inflates maintenance labor costs and extends ASTM F2291 inspection backlogs, forcing facility operators to absorb premium pricing for scarce technical services while suppliers command stronger terms on service contracts.
Pricing Analysis
Project-based service contracts dominate capital expenditure planning, with ride system manufacturers bundling installation, certification, and multi-year maintenance into single negotiated packages. Price differentiation hinges on ASTM F24 compliance tier and geographic proximity to certified technician pools, with coastal United States facilities facing steeper premiums than Midwestern counterparts. Cost compression in entry-fee revenue streams is intensifying because home entertainment substitution erodes discretionary out-of-home spending. Birthday package buyers demonstrate lowest price sensitivity, while walk-in admission purchasers exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced motion-control semiconductors from United States and allied jurisdictions limit ride system automation upgrades for Chinese facility operators, compressing equipment refresh cycles in that market. Manufacturing concentrates in Germany, China, and the United States, with specialized steel alloys and precision electronics drawing from East Asian foundries and Bavarian engineering clusters. Single-source vulnerability in semiconductor components creates procurement risk. Distribution runs through direct OEM relationships for large-format attractions and regional distributors for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in cyclical recovery as suburban retail corridor revitalization drives anchor tenant demand for family dwell-time generators, reversing pandemic-era foot traffic declines.
For Market Incumbents: Entrench membership-subscription models to reduce seasonality exposure and improve lifetime value metrics against transactional admission economics. Deepen backward integration into certified technician training programs to alleviate ASTM F2291 inspection scarcity. Prioritize modular facility formats that compress development timelines and enable rapid format pivots as educational-entertainment hybrids gain share. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-II cities such as Pune and Jaipur where organized play infrastructure remains underdeveloped and first-mover positioning is achievable. Target educational-entertainment hybrid formats that command parental willingness-to-pay premiums. Deploy mobile-native booking interfaces to capture China's demand for real-time availability transparency. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because membership-subscription economics transform cyclical admission volatility into predictable cash flows. Acquisition targets should emphasize facilities with established recurring revenue bases and compliant safety certification infrastructure. The signal to watch is ASTM F24 revision frequency acceleration, which compresses equipment depreciation schedules and favors operators with capital flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Membership-Subscription Model Deployment | Transforms transactional admission economics into predictable recurring revenue streams across suburban United States markets. |
| GB Standard Alignment in China | Opens procurement cost advantages for domestically sourced ride systems under Standardization Administration certification protocols. |
| Certified Technician Training Program Investment | Alleviates ASTM F2291 inspection scarcity that currently inflates maintenance costs beyond depreciation schedules. |
| Modular Facility Format Replication | Compresses development timelines and enables rapid pivots toward educational-entertainment hybrid concepts. |
| RFID Behavioral Tracking Infrastructure | Captures dwell-time patterns to trigger dynamic food service pricing and optimize staffing models. |
Methodological Framework
A spread of perspectives from facility operations directors, ASTM compliance officers, mall leasing managers, ride system procurement leads, and family entertainment center franchisees converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings of publicly traded operators, municipal procurement records from Texas and Florida park districts, and Standardization Administration GB standard documentation. Customs data on ride system imports and ASTM incident reporting databases provided additional triangulation. Bottom-up facility economics modeling and top-down market sizing approaches were reconciled to produce integrated estimates.
Demand-supply-balance dynamics across facility type, target age cohort, entertainment offering mix, and revenue model segmentation anchored the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle assumptions, and pricing elasticity parameters specific to birthday package and membership revenue streams. Modeled inputs included suburban retail vacancy rates, dual-income household formation trends in China's first-tier cities, and ASTM F24 revision implementation timelines.
Stress conditions across steel and electronics input volatility, ADA Title III compliance timeline extensions, and home entertainment substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory revision cycles and parental preference shifts toward developmental value. Material shifts in ASTM International's standard-setting velocity or China's GB standard harmonization trajectory would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Collectibles Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Drone for Kids Market
Toys and Games
Ride-Ons Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Cat Toys Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Global Toys Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Fabric Toys Market
Toys and Games
Bubble Tubes Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Robot Toys for Children Market
Toys and Games
Global Blind Boxes Market