
 Kids Recreational Services Market | 2026-2036
Kids Recreational Services Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Recreational Services Market Outlook
After-school programming is broadening its pull on family budgets as parents prioritize structured developmental activities outside traditional schooling. The Walt Disney Company leverages its theme park and cruise ecosystems to anchor premium experiential offerings for families. SeaWorld Entertainment Inc. competes through marine-education positioning that differentiates its park portfolio from generic entertainment alternatives. Merlin Entertainment Group sustains geographic diversification across Legoland and Madame Tussauds properties to control regional demand cycles.
Kids recreational services encompass organized non-academic activities delivered through staffed facilities or instructed sessions, typically requiring child-safety certifications, age-appropriate equipment protocols, and liability coverage frameworks. These services functionally substitute informal childcare with developmental outcomes spanning physical literacy, creative expression, and social coordination. Sports coaching and arts & crafts represent mature revenue pools where pricing power has consolidated around branded franchise networks. Online and hybrid delivery models within the delivery model dimension are capturing fastest-growing enrollment as platform infrastructure reduces geographic constraints on instructor reach.
FDA guidelines on surface sanitization and food service safety directly shape operational compliance costs for camp-based and community center providers across the United States. OSHA workplace standards and state-level childcare licensing boards jointly determine staffing ratios and facility inspection schedules that gate market access. Stakeholders must monitor how subsidy policy revisions and digital platform regulations recalibrate the competitive boundary between physical and virtual service delivery.
Market Dynamics
Hybrid delivery infrastructure is compressing geographic barriers between instructors and enrolled families, forcing physical facility operators to reconfigure their value proposition around experiential differentiation rather than proximity convenience.
Growth Catalysts
- OSHA workplace standards:Unified federal safety protocols reduce compliance fragmentation across state lines, lowering operational complexity for multi-location providers.
- Suburban metropolitan zones:Dual-income household density in United States, India, and Brazil corridors generates concentrated demand for structured after-school alternatives.
- Platform infrastructure:Instructor-to-family matching algorithms reduce customer acquisition costs and extend service radius beyond traditional catchment areas.
Market Restraints
- Child-safety certification scarcity:Qualified instructor pipelines lag enrollment demand, inflating wage premiums and constraining program scale-up velocity.
- Liability coverage concentration:Specialized insurance underwriters dominate the segment, exposing operators to premium volatility and coverage term tightening.
- Facility capital intensity:Age-appropriate equipment protocols and ADA compliance requirements demand substantial upfront investment with extended payback periods.
Strategic Opportunities
- Low-income subsidy expansion:The U.S. Child Care and Development Block Grant Act revisions are widening eligibility pools for fee-assisted enrollment.
- Marine-education positioning:Biome-focused programming differentiates against generic entertainment alternatives in coastal metropolitan markets.
- AI-powered personalization:Adaptive learning engines converging with live instruction are enabling customized developmental pathways at previously unattainable scale.
Industry Challenges
- Instructor retention pipelines:Competitive wage pressure from adjacent education sectors accelerates turnover and degrades program continuity.
- Digital-physical integration:Legacy booking and payment systems resist seamless connection with emerging hybrid delivery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Recreational Services Market |
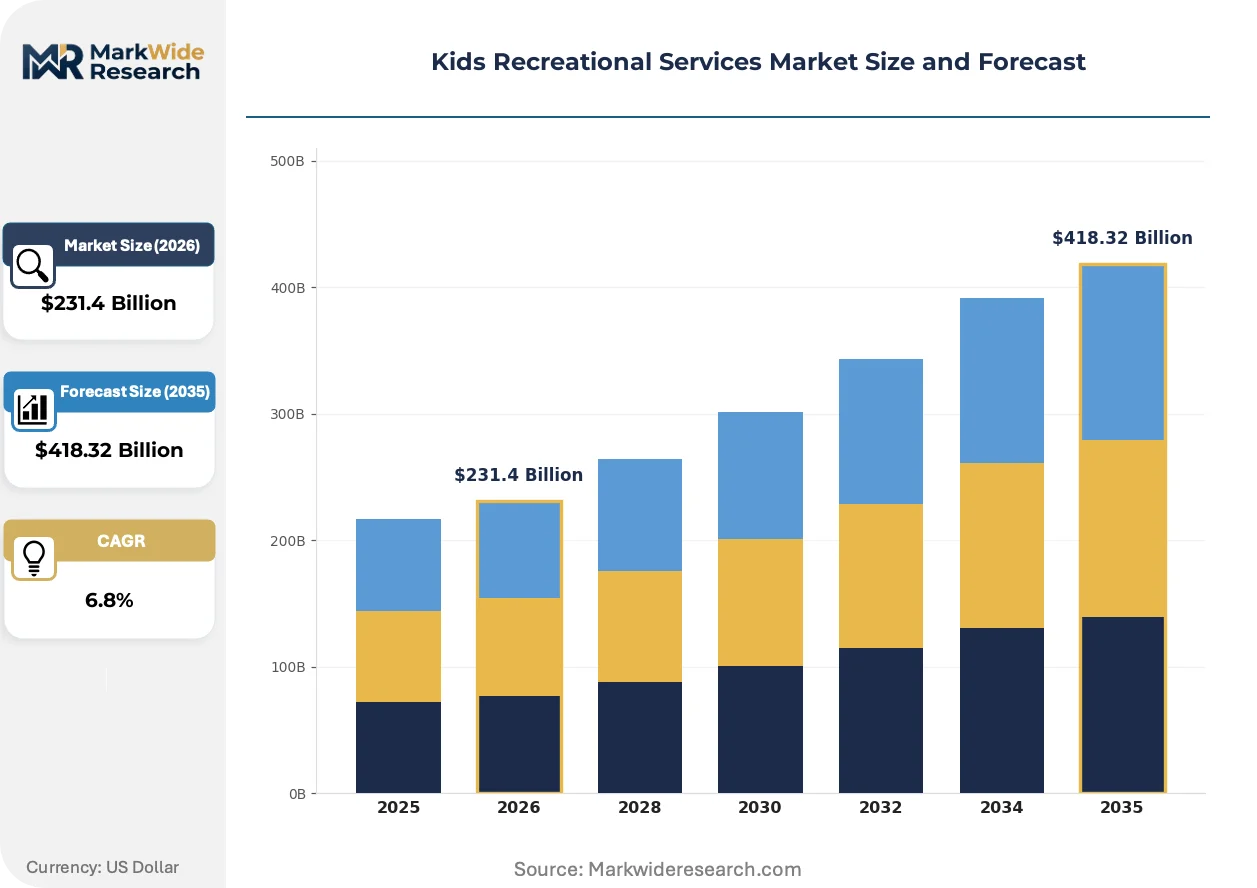
| Market Size in 2026 | $231.4 Billion |
| Market Size in 2035 | $418.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sports Coaching, Arts & Crafts, Music Lessons, Dance Classes Age Group: Toddlers, Preschoolers, School Age, Teens Delivery Model: In-Person, Online, Hybrid, On-Site Facility Type: Community Centers, Private Studios, Schools, Camps |
| Companies Covered | Chuck E. Cheese, SeaWorld Entertainment Inc., The Walt Disney Company, The Little Gym International, LEGO Group, Universal Studios, Merlin Entertainment Group, Urban Air Adventure Park, KidZania, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Recreational Services Market Strategic Shifts
Platform-mediated service delivery is restructuring competitive boundaries between physical and virtual provision, while regulatory attention to child welfare intensifies operational scrutiny across all delivery modes.
Live-streamed instruction with asynchronous practice modules is expanding into suburban households previously constrained by instructor availability and commute logistics. Families in United States secondary metros adopt these formats fastest, compressing the addressable market for traditional brick-and-mortar providers while opening enrollment to rural and exurban geographies previously deemed uneconomical.
The U.S. FDA guidelines on surface sanitization and food service safety are elevating baseline operational costs for camp-based and community center operators. Compliance documentation requirements now demand dedicated administrative capacity, disproportionately burdening smaller independent providers while creating scale advantages for networked franchise systems with centralized quality assurance infrastructure.
Subscription-based enrollment models are displacing session-by-session purchasing across after-school programming categories. United States dual-income households lead this shift, trading flexibility for predictable budgeting and guaranteed placement in high-demand instructor schedules. This compresses customer switching and intensifies retention investment by competing platforms.
Kids Recreational Services Market Segmentation
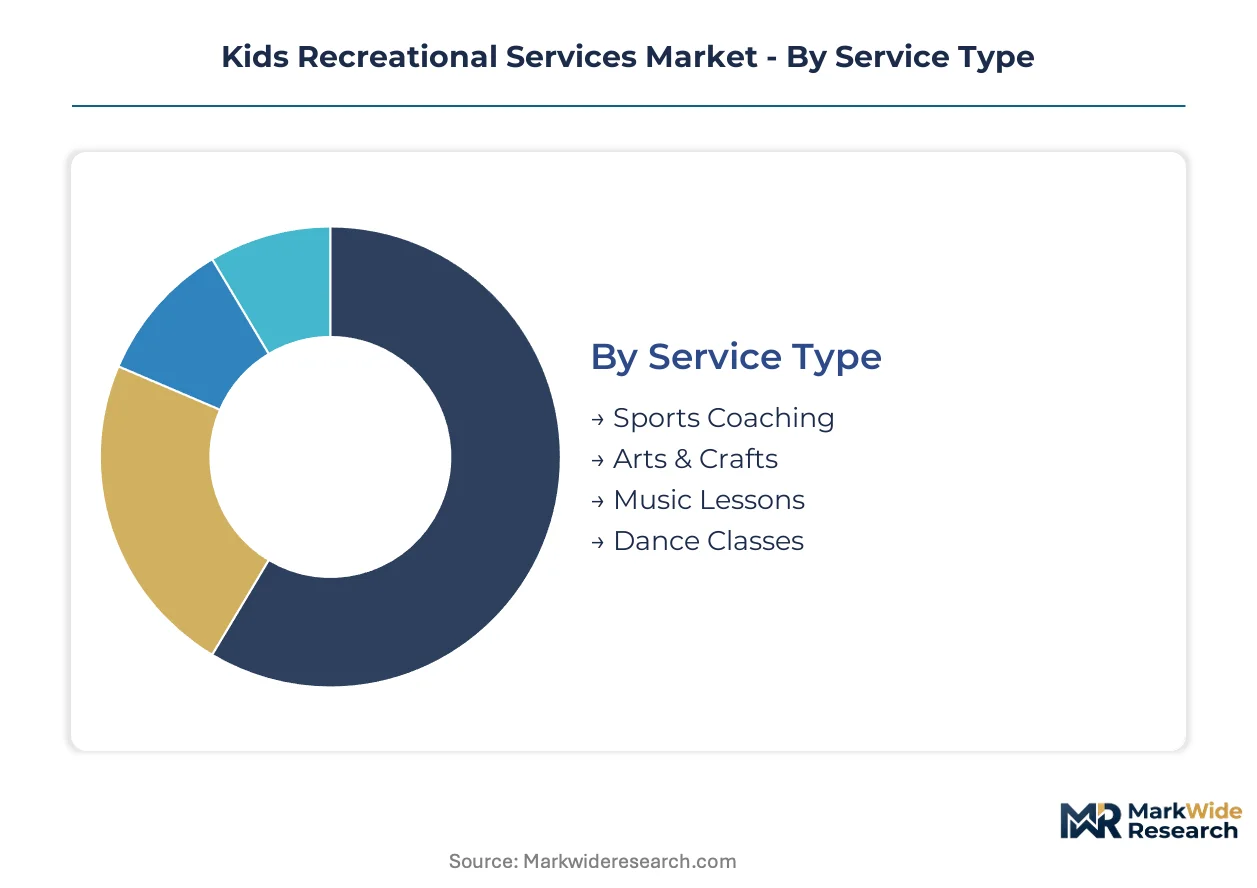
Segmentation in kids recreational services reveals how family preferences, infrastructure constraints, and developmental priorities split demand across distinct service configurations. Operators configure staffing, certification requirements, and pricing architectures differently for each segment cluster.
Service Type:
Upgrade cycles in recreational programming follow shifting parental priorities for measurable developmental outcomes rather than entertainment value alone.
- Sports Coaching:Structured athletic instruction spanning team sports and individual skill development, requiring certified coaches and liability protocols. Demand concentrates in suburban United States corridors where dual-income households prioritize physical literacy alongside academic performance. Franchise networks dominate pricing power through branded curriculum standardization.
- Arts & Crafts:Hands-on creative expression programming emphasizing fine motor development and visual-spatial skills. Enrollment clusters in Indian metropolitan zones where middle-class families view artistic competency as competitive differentiator for school admissions. Supply constraints around specialized instructors inflate wage premiums.
- Music Lessons:Instrumental and vocal instruction delivered through individual or small-group formats.
- Dance Classes:Movement-based programming spanning ballet, hip-hop, and cultural dance traditions.
Volume placements concentrate in Sports Coaching; the faster expansion belongs to Arts & Crafts.
Age Group:
Cost tier stratification across age brackets reflects differential staffing ratios, equipment scale, and parental price sensitivity.
- School Age:Programming for children 6-12 years emphasizing skill progression and social coordination. Brazilian suburban households drive concentrated demand for structured after-school alternatives that substitute informal childcare. OSHA workplace standards and state-level licensing boards jointly determine staffing ratios that gate market access.
- Preschoolers:Early developmental programming for ages 3-5 focusing on foundational motor and social skills. United States dual-income households in secondary metros adopt hybrid delivery formats fastest, compressing addressable market for traditional brick-and-mortar providers. FDA surface sanitization guidelines elevate baseline operational costs disproportionately.
- Toddlers:Parent-accompanied or drop-off programming for ages 1-3 emphasizing sensory exploration.
- Teens:Advanced skill development and competitive preparation for adolescents 13-17.
Revenue concentration sits with School Age; Preschoolers are climbing the fastest.
Delivery Model:
Customer type fragmentation across delivery modes reflects divergent convenience priorities and technology access patterns.
- Hybrid:Blended instruction combining live-streamed sessions with asynchronous practice modules and periodic in-person intensives. United States families in exurban geographies previously deemed uneconomical now enroll through platform infrastructure that reduces geographic constraints on instructor reach. Subscription-based models displace session-by-session purchasing.
- In-Person:Traditional facility-based delivery requiring physical presence for all instruction. Demand concentrates where commute logistics and instructor availability previously constrained access. Facility capital intensity and ADA compliance requirements demand substantial upfront investment.
- Online:Fully remote instruction delivered through synchronous video platforms.
- On-Site:Programming delivered at schools, workplaces, or residential complexes eliminating family transport burden.
Enrollment share still favors In-Person; Hybrid is gaining share fastest.
Facility Type:
Supply concentration across facility categories reflects capital access, regulatory burden distribution, and partnership ecosystem depth.
- Community Centers:Municipal or nonprofit-operated facilities offering subsidized access and sliding-scale pricing. The U.S. Child Care and Development Block Grant Act shapes subsidy eligibility for low-income families accessing these services. Compliance documentation requirements disproportionately burden smaller independent providers.
- Private Studios:Commercially operated dedicated spaces emphasizing premium positioning and specialized equipment. Networked franchise systems deploy centralized quality assurance infrastructure to manage FDA food service safety protocols across multiple locations. Scale advantages compound through shared administrative capacity.
- Schools:Programming delivered within K-12 institutional settings during or immediately after instructional hours.
- Camps:Seasonal residential or day-camp programming emphasizing immersive multi-day experiences.
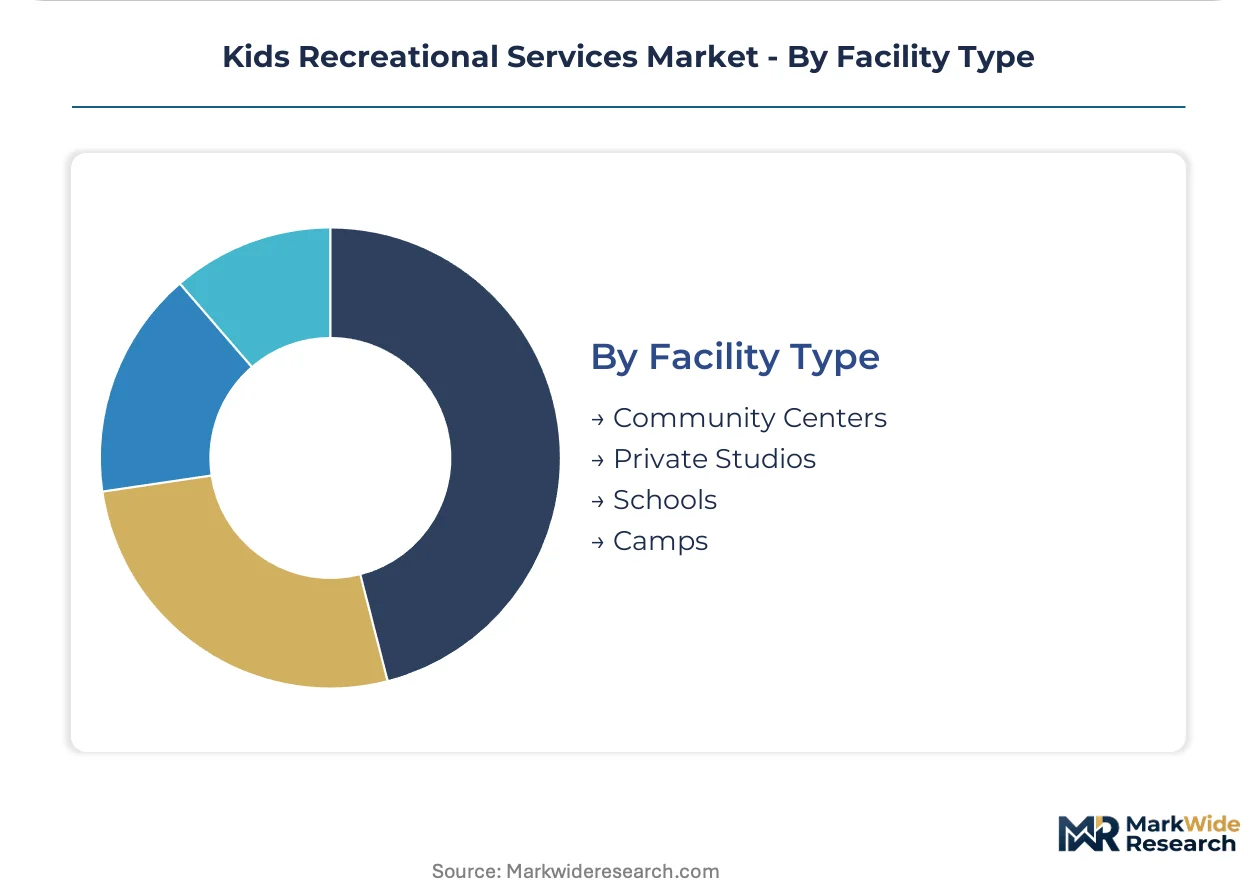
Private Studios capture premium pricing; Community Centers show steepest expansion trajectory through subsidy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and suburban corridor development are concentrating recreational infrastructure investment in dual-income household clusters across four major national markets.
United States
OSHA workplace standards and the Child Care and Development Block Grant Act shape subsidy eligibility for low-income families accessing after-school programming. Demand concentrates in suburban metropolitan zones where dual-income households prioritize structured developmental alternatives. Platform infrastructure reduces geographic constraints on instructor reach in exurban geographies previously deemed uneconomical.
India
Middle-class families in Indian metropolitan zones view artistic competency as competitive differentiator for school admissions. BIS standards govern equipment safety protocols for facility-based providers. Enrollment clusters in suburban corridors where household spending on child development broadens fastest.
Brazil
Brazilian suburban households drive concentrated demand for structured after-school alternatives that substitute informal childcare. ANVISA regulations shape operational compliance for camp-based and community center providers. Dual-income household density in São Paulo and Rio de Janeiro corridors generates sustained enrollment velocity.
United Kingdom
CE marking requirements and GDPR compliance elevate baseline operational costs for digital-physical hybrid delivery platforms. Subscription-based enrollment models displace session-by-session purchasing across after-school programming categories. London and Southeast England anchor premium experiential positioning for branded franchise networks.
Germany
REACH regulations and EU Green Deal sustainability criteria reshape facility capital intensity for age-appropriate equipment protocols. Baden-Württemberg and Bavaria host concentrated private studio development. Networked franchise systems deploy centralized quality assurance infrastructure to manage compliance documentation requirements.
Kids Recreational Services Market Competitive Environment
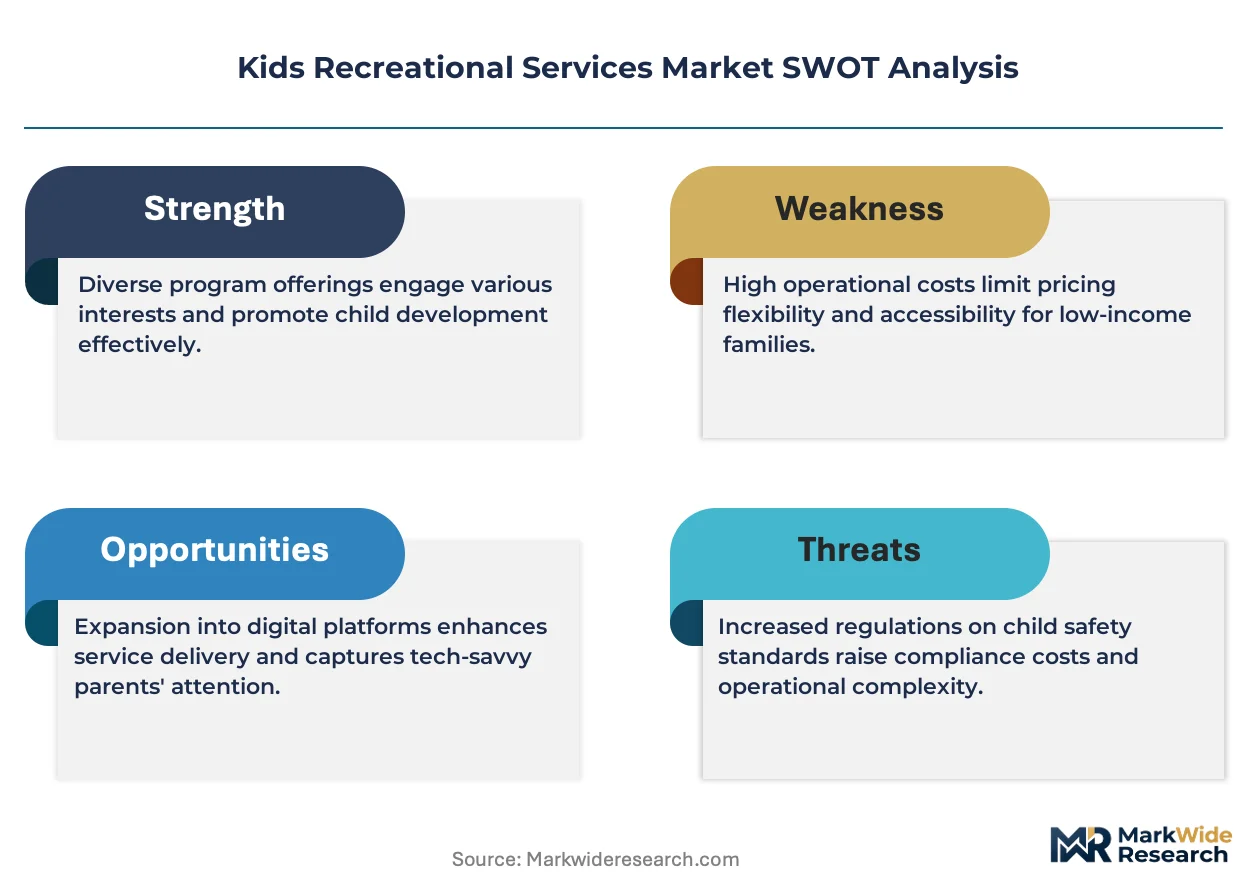
Branded specialists and contract manufacturers split share differently across segments, with franchise networks dominating pricing power through curriculum standardization while independent operators retain localized flexibility. The vendor base organizes around three strategic archetypes: ecosystem-anchored entertainment conglomerates, biome-focused education specialists, and geographic diversification platforms. Competitive moves concentrate on experiential differentiation through marine-education positioning and subscription-based enrollment models that compress customer switching.
Within the ecosystem-anchored tier, The Walt Disney Company and SeaWorld Entertainment Inc. represent contrasting approaches to premium experiential capture. Merlin Entertainment Group occupies a position exemplifying geographic diversification across branded properties. The Little Gym International and Urban Air Adventure Park sit within the facility-based franchise archetype, while KidZania anchors the immersive role-play education segment.
| Leading Market Players |
|---|
| Chuck E. Cheese |
| SeaWorld Entertainment Inc. |
| The Walt Disney Company |
| The Little Gym International |
| LEGO Group |
| Universal Studios |
| Merlin Entertainment Group |
| Urban Air Adventure Park |
| KidZania |
| Others |
Value Chain & Pricing Dynamics
Certified instructor wages cascade through three distinct pricing tiers as facilities pass labor premiums to enrolled families. Brazilian community centers absorb the steepest cost compression, while United States private studios leverage subscription lock-in to stabilize revenue against wage volatility.
Pricing Analysis
Short lead-time placement commands premium positioning in United States suburban corridors where dual-income households trade flexibility for guaranteed instructor schedules. Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and facility amenity density. Pricing pressure stems from qualified instructor scarcity inflating wage premiums faster than enrollment growth. Community center operators exhibit highest price sensitivity; ecosystem-anchored entertainment conglomerates retain lowest sensitivity through bundled experiential value.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme reshape equipment sourcing for facility-based providers, favoring local manufacturers of age-appropriate apparatus. Specialized instructional equipment concentrates in China, Germany, and South Korea; liability insurance underwriting anchors in United States and London markets. Supply chain risk centers on single-source vulnerability for marine-education biome installations in coastal metropolitan zones. Distribution runs through franchise network hubs that centralize procurement and quality assurance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where platform infrastructure and captive instructor pipelines determine competitive durability. Players pursue downstream control over subscription enrollment and hybrid delivery matching algorithms to compress customer acquisition costs.
For Market Incumbents: Anticipate hybrid platform entrants eroding geographic catchment advantages by accelerating experiential differentiation investments. Secure marine-education positioning in coastal corridors before biome-focused specialists consolidate. Backward integration into instructor certification pipelines defends against wage inflation and turnover degradation.
For New Entrants and Emerging Players: Rural and exurban United States families previously deemed uneconomical represent the most penetrable buyer archetype. Platform-mediated delivery eliminates facility capital intensity barriers while subscription models generate predictable recurring revenue. Partner with municipal community centers for subsidized placement under Child Care and Development Block Grant Act eligibility expansion.
For Investors and Strategic Acquirers: Subsidy policy revision announcements are the leading indicator that community center expansion trajectories will accelerate. Long-term viability favors networked franchise systems with centralized compliance infrastructure over independent operators facing administrative burden concentration. Watch for AI-powered personalization engine deployments as signal of scalable customization capability maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Instructor Certification Pipeline Development | Captive supply of OSHA-compliant staff reduces wage volatility exposure for multi-location operators. |
| Hybrid Platform Infrastructure Deployment | Live-streamed instruction with asynchronous modules extends service radius beyond traditional catchment areas. |
| Marine-Education Biome Installation | Coastal metropolitan differentiation against generic entertainment alternatives commands premium positioning. |
| Subscription Enrollment Model Conversion | Predictable recurring revenue compresses customer switching and stabilizes cash flow against seasonality. |
| Municipal Subsidy Partnership Expansion | Child Care and Development Block Grant Act eligibility access opens low-income household enrollment pools. |
Study Parameters
SEC filings of publicly traded entertainment conglomerates, OSHA regulatory guidance documents, and municipal community center procurement databases formed the secondary backbone of this analysis. Primary interviews with after-school program directors, child-safety certification board officials, franchise operations executives, and liability insurance underwriters validated demand patterns and operational constraints. Bottom-up enrollment data triangulated against top-down household spending estimates across United States, India, and Brazil corridors.
Historical trendline analysis of enrollment velocity and pricing evolution informed projection modeling across service type, age group, delivery model, and facility type dimensions. CAGRs derived from segment-specific growth trajectories weighted by dual-income household density and subsidy policy exposure. Instructor wage inflation curves and platform technology adoption rates served as industry-specific forecast inputs throughout the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to subsidy policy revisions, digital platform regulations, and child-safety certification pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Pre-School Games and Toys Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Bounce House Market
Toys and Games
Toy Collectibles Market
Toys and Games
China Toys Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Drone for Kids Market
Toys and Games
Glow Sticks Market
Toys and Games
Bubble Tubes Market
Toys and Games
US Sex Toys Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Fabric Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Kid's Microphone Market