
 Robot Toys for Children Market | 2026-2036
Robot Toys for Children Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Toys for Children Market Insights
Parental buyers is rotating toward educator-influenced purchasing, displacing impulse-driven gift buying as the dominant transaction mode. Lego leverages its brick-robot hybrid ecosystem to anchor premium positioning in coding-enabled construction sets. WowWee competes through animatronic character licensing, while Sphero specializes in app-integrated spherical robots for classroom deployment.
Robot toys for children encompass electromechanical play devices incorporating sensors, microcontrollers, and wireless connectivity to enable autonomous or user-directed behavior, typically constructed from ABS plastic housings with lithium-polymer power cells and servo-actuated limb mechanisms. Educational robots lead structural segment value generation as schools embed coding literacy into core curricula, while interactive robots occupy the fastest-expansion tier driven by voice-recognition and emotional-response AI integration. Programmable robots concentrate margin pools in subscription-based software ecosystems, whereas remote control robots represent a mature hardware-centric category with thinning differentiation.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards including small-part choke hazards and chemical migration limits, while the FCC regulates radio-frequency emissions from Bluetooth-enabled robot toys. The EU's CE marking and RoHS substance restrictions shape market access for Asian exporters. China's SAMR administers compulsory CCC certification for domestic electronic toy circulation. Stakeholders must monitor whether emerging AI governance frameworks classify learning-enabled robot toys as educational technology subject to additional privacy compliance beyond traditional toy regulation.
Market Dynamics
The market's competitive logic is pivoting around Shenzhen's component-to-assembly corridor density, where lithium-polymer cell suppliers and servo motor fabricators operate within single-day logistics reach of finished goods assemblers.
Growth Catalysts
- STEAM curriculum mandates:North American childcare centers now embed programmable robotics into preschool accreditation requirements, creating institutional procurement pipelines for sensor-equipped kits.
- China's GB 6675 updates:Stricter electromagnetic emissions testing standards for electronic playthings are filtering out low-grade competitors and elevating certified manufacturers.
- Bluetooth Low Energy modules:Falling component costs are enabling voice-recognition and emotional-response AI integration at sub-premium price tiers.
Market Restraints
- Lithium-polymer cell volatility:Raw material concentration in cobalt refining operations creates input cost instability for power cell dependent manufacturers.
- Shenzhen corridor dependency:Over 70 percent of global servo-actuated limb mechanism assembly concentrates in a single manufacturing cluster, exposing supply chains to localized disruption.
- ASTM F963 small-part testing:Choke hazard certification timelines extend product development cycles by four to six months for new form factors.
Strategic Opportunities
- India's toy manufacturing PLI scheme:Production-linked incentives for electronic toy assembly are drawing component sourcing away from single-origin dependence.
- Subscription software ecosystems:Recurring revenue attachment to programmable robot kits creates margin pools beyond hardware sale economics.
- Voice-recognition plus emotional AI convergence:Interactive robots capable of adaptive response behavior are opening household segments beyond educational institutional buyers.
Industry Challenges
- Firmware security certification:Learning-enabled robots storing child interaction data face emerging privacy compliance complexity beyond traditional toy safety frameworks.
- Cross-border electromagnetic compatibility testing:Divergent FCC, CE marking, and CCC radio-frequency emission standards force redundant certification expenditures for multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Toys for Children Market |
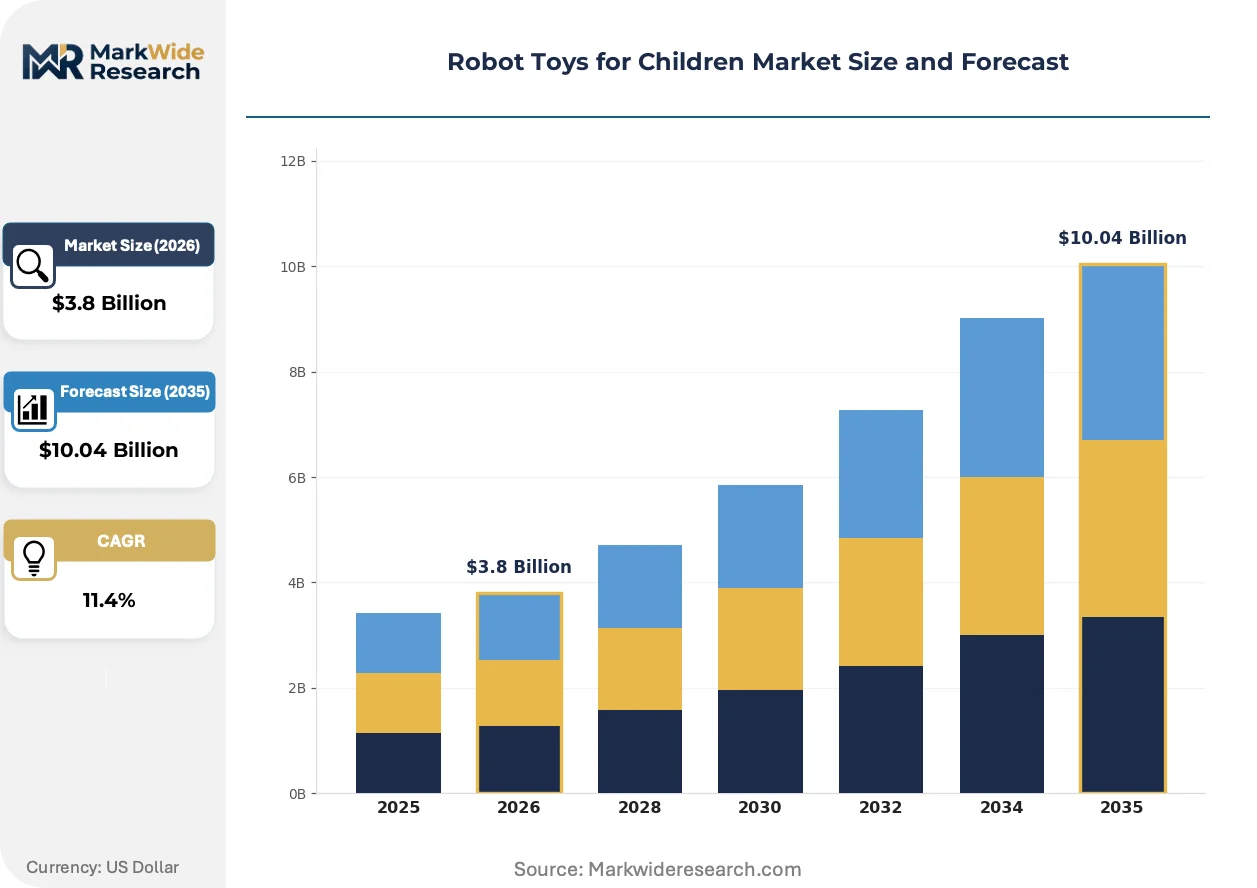
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Robots, Educational Robots, Remote Control Robots, Programmable Robots Age Group: Toddlers, Preschoolers, Early School Age, Tweens Material: Plastic, Metal, Rubber, Electronic Components Sales Channel: Online Retail, Toy Stores, Specialty Stores, Supermarkets |
| Companies Covered | Lego, Hasbro, Mattel, Bandai, WowWee, Spin Master, Sphero, Ubtech Robotics, Wonder Workshop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Toys for Children Market Trends and Innovations
Hardware-software integration depth is becoming the primary axis of differentiation, with coding literacy platforms and animatronic character ecosystems competing for household attention and institutional procurement budgets.
Modular brick-robot hybrid construction systems are decomposing the traditional separation between physical play and digital programming interfaces. Elementary school technology coordinators are adopting these platforms at accelerating rates for classroom deployment. The technology is decomposing standalone coding tablet apps by embedding computational thinking directly into tactile manipulation experiences.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on learning-enabled toys marketed in member states. Manufacturers must now document decision-making logic for voice-recognition and emotional-response systems. Educational robot segments targeting European institutional buyers are restructuring firmware architectures to accommodate explainability mandates before product launch.
Parental purchasing is rotating toward educator-validated selection criteria, displacing retail impulse and seasonal gift patterns. Specialty toy retailers and direct-to-school distributors are capturing transaction flow from big-box seasonal aisles. This behavioral shift concentrates most visibly in North American suburban districts with high childcare center density and active parent-teacher organization networks.
Robot Toys for Children Market Segmentation
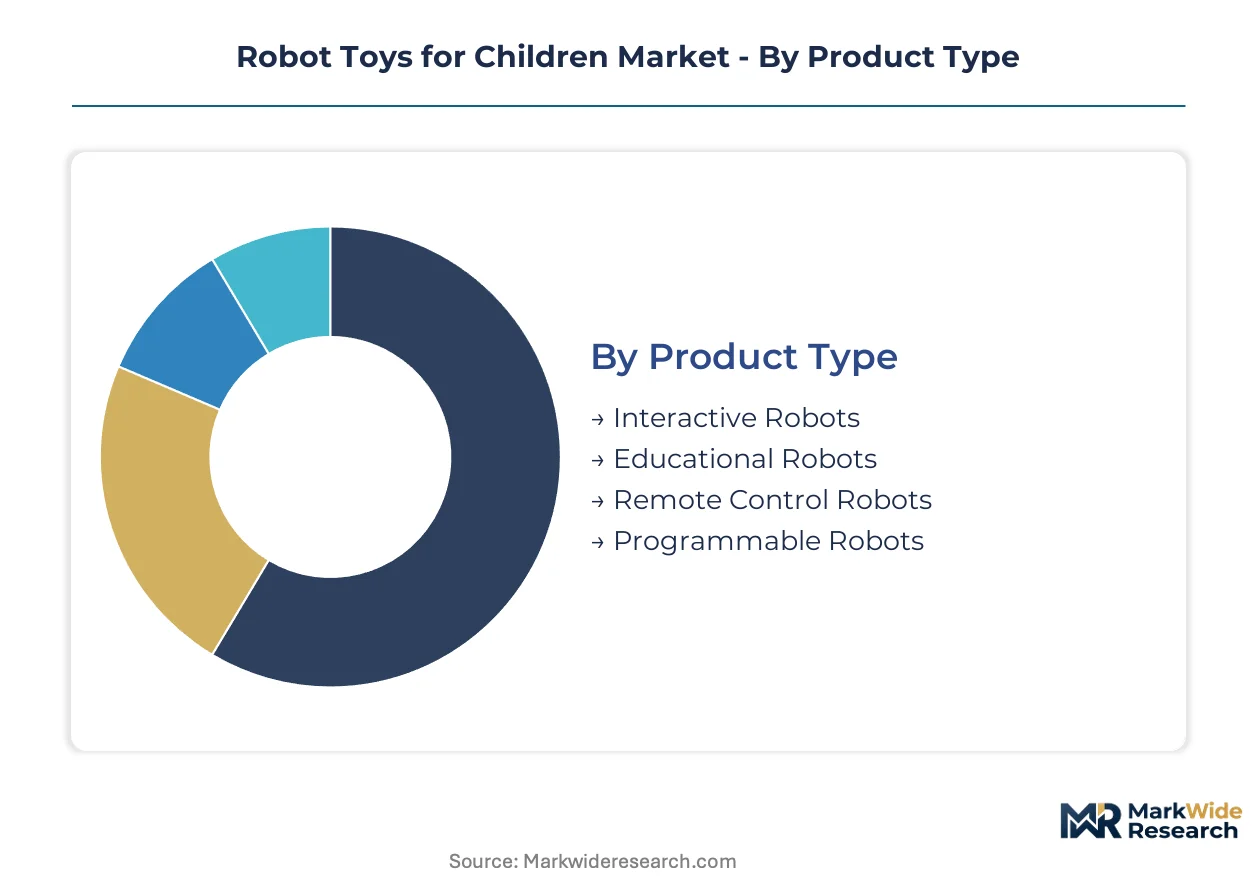
Robot toys fragment across four distinct category axes, each governing different margin structures and procurement channels. Product type determines firmware complexity and subscription attach rates. Age targeting shapes safety certification requirements and price elasticity. Material composition drives electromagnetic compliance exposure. Channel selection separates institutional buyers from household purchasers.
Product Type:
Educational robots dominate North American institutional procurement, while interactive robots concentrate in Asian household retail. Programmable and remote control variants split between export manufacturing and domestic consumption patterns.
- Interactive Robots:Voice-recognition modules and emotional-response AI processors enable adaptive behavior patterns. Shenzhen assembly lines ship these predominantly to Japanese and South Korean retail channels where household penetration runs deepest. Bluetooth Low Energy integration costs are compressing price thresholds.
- Educational Robots:Sensor-equipped kits with drag-drop coding interfaces target preschool STEAM accreditation requirements. US childcare centers and Canadian early learning facilities constitute the core demand concentration. Curriculum alignment with CSTA K-12 standards drives repeat procurement cycles.
- Remote Control Robots:Radio-frequency transmitter pairs with servo-actuated locomotion systems.
- Programmable Robots:Microcontroller-based platforms with block-based or text-based coding environments.
Educational robots command the established base. The steepest expansion runs through interactive robots.
Age Group:
Preschoolers and early school age segments absorb premium pricing for coding-enabled platforms. Toddler and tween categories concentrate volume in simpler electromechanical formats with lower firmware overhead.
- Preschoolers:Large-form ABS housings with rounded edges accommodate ASTM F963 small-part restrictions. North American parent-teacher organization networks validate purchasing decisions for this cohort. Durability specifications exceed 10,000 actuation cycles.
- Early School Age:Brick-robot hybrid construction systems embed computational thinking into tactile manipulation. Elementary technology coordinators in US suburban districts deploy these at accelerating rates. Curriculum integration with Common Core math standards strengthens institutional attachment.
- Toddlers:Simplified locomotion with obstacle-avoidance sensors and limited input interfaces.
- Tweens:Advanced programmable kits with Python or JavaScript compatibility and competitive robotics league alignment.
Early school age captures the volume center. Preschoolers are climbing the fastest on institutional procurement acceleration.
Material:
Electronic components concentrate margin pools through firmware-dependent differentiation. Plastic, metal, and rubber inputs compete on cost efficiency and safety certification speed.
- Electronic Components:Lithium-polymer power cells, microcontrollers, and Bluetooth modules constitute 40-60 percent of bill-of-materials value. Shenzhen component suppliers cluster within single-day logistics reach of assembly facilities. GB 6675 electromagnetic emissions testing filters uncertified suppliers from Chinese domestic circulation.
- Plastic:ABS and polycarbonate housings dominate structural enclosures for impact resistance and chemical migration compliance.
- Metal:Aluminum and steel servo brackets provide torque stability in programmable limb mechanisms.
- Rubber:Traction surfaces and shock-absorbing bumpers in remote control and interactive form factors.
Plastic maintains the volume base. Electronic components deliver the steepest margin expansion trajectory.
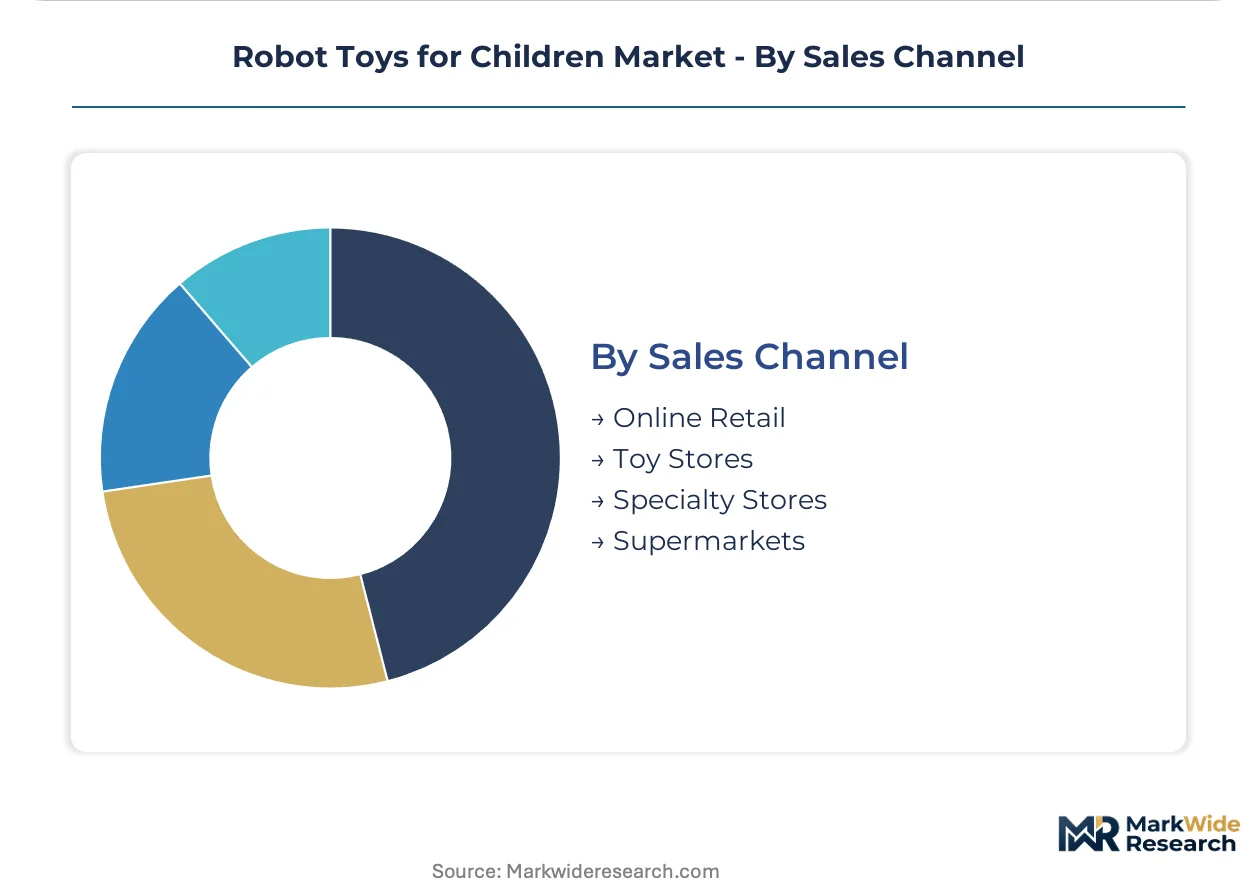
Sales Channel:
Online retail and specialty stores fragment along educator-influenced versus impulse-driven purchasing patterns. Toy stores and supermarkets retain seasonal gift concentration.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture educator-validated research-heavy purchases. Parental buyers compare CSTA alignment and curriculum integration specifications before committing. Subscription software attach rates run highest through this channel.
- Specialty Stores:Curated assortments with staff technical expertise serve homeschooling and supplemental education segments. US and Canadian independent retailers maintain relationships with district technology coordinators.
- Toy Stores:Seasonal aisle placement drives impulse purchasing for gift occasions.
- Supermarkets:Mass-market price points with limited technical differentiation.
Online retail is gaining share fastest. Specialty stores hold the educator-validated core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's manufacturing corridor ships the majority of finished robot toys to North American childcare procurement networks and Japanese household retail channels. Component suppliers cluster within single-day logistics reach of assembly facilities. The trade flow concentrates value capture in China's Pearl River Delta while end-market monetization tilts toward OECD education systems.
United States
US childcare centers now embed programmable robotics into preschool STEAM accreditation requirements. The Consumer Product Safety Commission enforces ASTM F963 toy safety standards including small-part choke hazards and chemical migration limits. Greater Boston and Silicon Valley suburbs concentrate parent-teacher organization networks that validate educator-influenced purchasing decisions.
China
Domestic demand for interactive robots with voice-recognition modules is accelerating in tier-one cities. The State Administration for Market Regulation administers compulsory CCC certification for electronic toy circulation under updated GB 6675 electromagnetic emissions standards. Shenzhen's component-to-assembly corridor anchors global supply, with lithium-polymer cell suppliers and servo motor fabricators operating within tight logistics proximity.
Japan
Household penetration of emotional-response AI robots runs deepest in Japanese retail channels. The Ministry of Economy, Trade and Industry oversees JIS standards compliance for Bluetooth-enabled play devices. Tokyo-Osaka metropolitan corridors concentrate specialty toy retailers capturing educator-validated transaction flow.
Germany
European institutional procurement for coding-enabled construction sets concentrates in German early learning facilities. The EU AI Act's risk classification framework imposes algorithmic transparency requirements on learning-enabled toys marketed in member states. Bavaria's industrial districts host distributors restructuring firmware architectures to accommodate explainability mandates.
India
Production-linked incentives for electronic toy assembly are drawing component sourcing away from single-origin dependence. The Bureau of Indian Standards shapes domestic market access requirements for imported play devices. Maharashtra and Gujarat manufacturing zones are attracting assembly facility investments from multinational brands seeking supply chain diversification.
Robot Toys for Children Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration depth. The vendor base splits between consolidated brick-robot hybrid platforms and fragmented animatronic character licensors. Three archetypes dominate: construction ecosystem anchors, classroom deployment specialists, and licensed character animatronics. Competitive moves concentrate on curriculum alignment partnerships and subscription software ecosystem attachment.
Within the construction ecosystem tier, Lego exemplifies brick-robot hybrid platform dominance through its coding-enabled sets. Sphero and Wonder Workshop occupy positions as classroom deployment specialists with app-integrated spherical and character-form robots. WowWee represents the licensed character animatronics archetype through its entertainment property integrations. Each anchors distinct procurement channels—retail gift, institutional education, and household entertainment respectively.
| Leading Market Players |
|---|
| Lego |
| Hasbro |
| Mattel |
| Bandai |
| WowWee |
| Spin Master |
| Sphero |
| Ubtech Robotics |
| Wonder Workshop |
| Others |
Pricing and Supply Chain Analysis
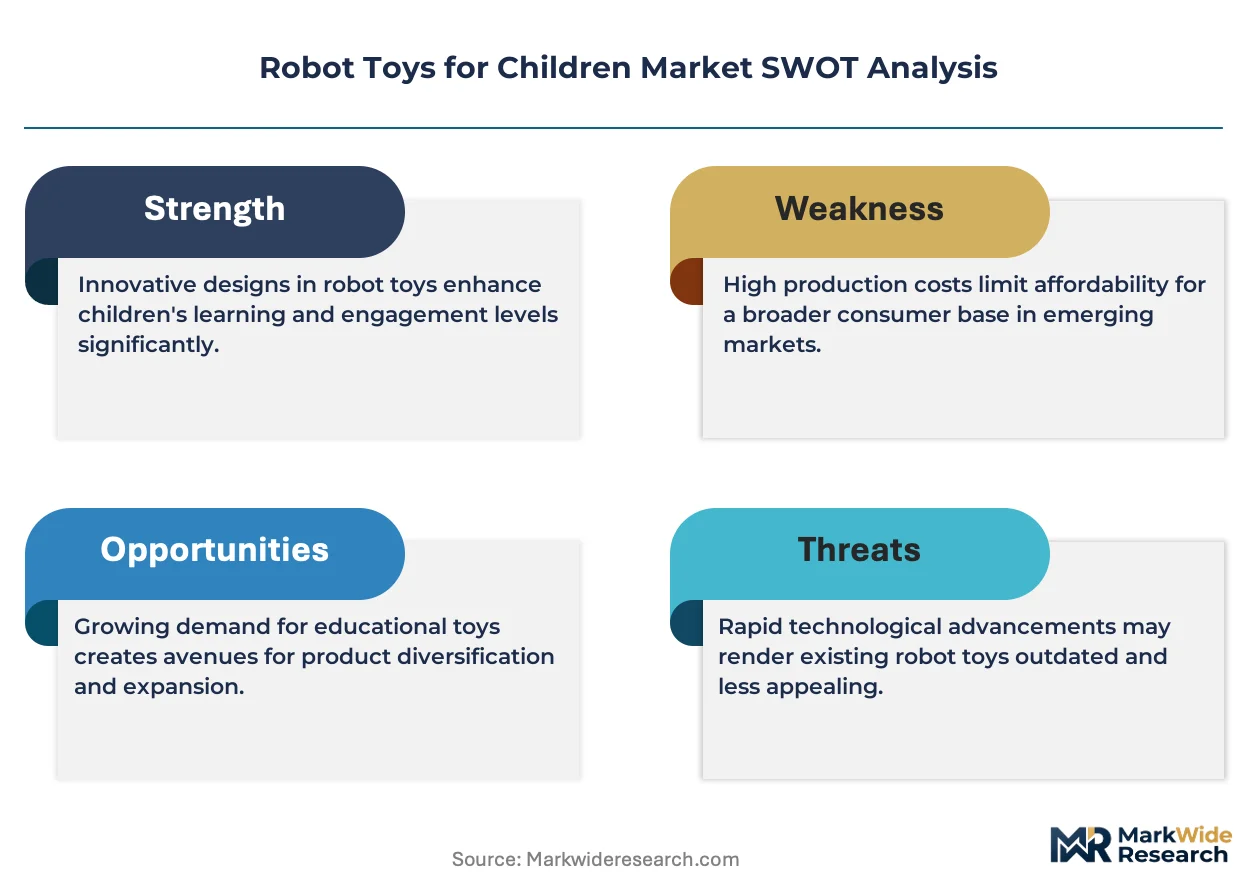
Four-to-six month ASTM F963 certification timelines compress pricing power for new form factors while Shenzhen's same-day component logistics anchor margin structures for established SKUs. This lead-time asymmetry rewards incumbents with certified product lines while forcing new entrants into aggressive introductory pricing to offset extended cash conversion cycles.
Pricing Analysis
Current-generation voice-recognition modules with emotional-response AI processors command three-tier pricing structure across premium, standard, and economy levels, while prior-generation Bluetooth-only variants face cost compression in retail channels. Price differentiation rests on firmware complexity and CSTA curriculum alignment certification. Margins are tightening due to lithium-polymer cell raw material volatility. Institutional buyers in North American childcare networks demonstrate lowest price sensitivity, while mass-market household purchasers in Asian retail concentrate volume in economy tiers.
Supply Chain Analysis
China anchors global servo-actuated limb mechanism assembly, with South Korea and Japan feeding specialized microcontroller and sensor inputs. The supply chain draws from cobalt refining operations for lithium-polymer cells, ABS resin complexes for housings, and rare-earth magnet flows for motor assemblies. Single-source vulnerability concentrates in Shenzhen's Pearl River Delta corridor where over seventy percent of global assembly capacity clusters. Distribution runs through direct-to-school institutional procurement networks in North America and specialty toy retail channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through North American childcare center procurement consolidation, with district-level technology coordinators displacing fragmented parental gift purchasing as the dominant transaction archetype.
For Market Incumbents: Fortify curriculum alignment partnerships with CSTA and Common Core standard-setters to lock institutional procurement pipelines. Deepen backward integration into lithium-polymer cell supply through captive sourcing agreements with certified cobalt refiners. Defensive priority rests on firmware security certification ahead of emerging AI governance frameworks that may reclassify learning-enabled toys as educational technology subject to additional privacy compliance. For New Entrants and Emerging Players: Anchor in India's Production-Linked Incentive manufacturing zones to escape Shenzhen corridor dependency and capture supply chain diversification budgets from multinational brands. Target homeschooling segments through specialty retail channels where staff technical expertise validates educator-influenced purchasing. Go-to-market angle should emphasize subscription software ecosystem attach rates that generate recurring revenue beyond hardware sale economics. For Investors and Strategic Acquirers: Carve-out targets emerge from entertainment conglomerates' toy divisions where animatronic character licensing portfolios have underperformed against brick-robot hybrid platforms. Long-term viability over the coming decade hinges on voice-recognition plus emotional AI convergence capabilities. Signal to monitor: EU AI Act explainability mandate compliance timelines, as firmware architecture restructuring costs will separate acquirable distressed assets from sustainable growth platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Curriculum Alignment Partnership | CSTA K-12 standard integration locks North American institutional procurement pipelines against competitors. |
| Subscription Software Ecosystem Launch | Recurring revenue attachment to programmable kits escapes hardware margin compression from Shenzhen assembly cost volatility. |
| India PLI Zone Manufacturing Footprint | Maharashtra and Gujarat assembly investments diversify supply chain concentration risk from single-origin Pearl River Delta dependency. |
| Firmware Security Certification Investment | GDPR and emerging AI governance compliance preempts reclassification of learning-enabled toys as educational technology. |
| Emotional-Response AI Platform Integration | Voice-recognition convergence with adaptive behavior algorithms opens Japanese household segments beyond institutional buyers. |
Research Methodology
The analysis maps interactive robots, educational robots, programmable robots, and remote control variants, each validated through elementary technology coordinators, preschool accreditation officers, specialty toy retail buyers, and lithium-polymer procurement managers at assembly facilities. Primary interview intelligence triangulates against customs trade records, FCC equipment authorization filings, EU CE marking databases, and childcare center procurement contract aggregators. Bottom-up bill-of-materials costing and top-down retail channel revenue estimation cross-validate segment-level outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, age targeting, material composition, and sales channel dimensions alongside firmware complexity tiers and curriculum integration depth. CAGRs derive from segment-level growth driver weighting and constraint penalty functions. Forecast inputs incorporate GB 6675 electromagnetic emissions testing adoption curves and Bluetooth Low Energy module cost compression trajectories.
Underlying assumptions cover STEAM curriculum mandate persistence, cobalt price band stability, and Shenzhen logistics continuity, with deviation risk concentrated in lithium-polymer raw material shocks and AI governance framework reclassification events. Recalibration cycles align with material shifts in regulatory compliance timelines and institutional procurement budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Global Stem Toys Market
Toys and Games
Claw Machine Market
Toys and Games
Action Figures Market
Toys and Games
Bubble Blower Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Toys and Games Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Bounce House Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Animation Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Traditional Toys and Games Market
Toys and Games
Plush Toy Market
Toys and Games
Indoor Bumper Cars Market