
 Pre-School Games and Toys Market | 2026-2036
Pre-School Games and Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-School Games and Toys Market Analytics
Premium safety certification tiers is collapsing the gap between mass-market and specialty preschool products, forcing broader quality upgrades across price bands. Mattel Inc. leverages its global manufacturing footprint to sustain compliance with evolving regional standards. LEGO Group anchors its position through captive resin sourcing and in-house molding precision for interlocking components. VTech Holdings Ltd. differentiates via integrated electronic modules that merge tactile play with programmable feedback loops.
Pre-school games and toys encompass purpose-built play objects designed for children aged zero to six years, typically manufactured from injection-molded ABS, sustainably harvested timber, or woven textile substrates with rounded geometries and non-toxic surface coatings to mitigate choking hazards and chemical exposure. These products serve dual commercial purposes: supporting neuro-motor development milestones in institutional early education settings while enabling supervised engagement in domestic environments. Educational toys and building blocks command the dominant revenue share as parents and institutions prioritize cognitively stimulating formats over passive entertainment, while activity sets represent the fastest-expanding margin pool due to bundled consumable replenishment cycles. Distribution through online retail channels is accelerating as direct-to-consumer logistics networks reduce shelf-space dependence and enable subscription-based replenishment models for recurring-use items.
The US Consumer Product Safety Commission enforces ASTM F963 mechanical and flammability standards that govern preschool toy design and batch testing protocols, while the EU REACH regulation restricts phthalate and heavy metal content in polymer substrates destined for mouthing-age users. China's SAMR administers mandatory GB 6675 national standards that align with ISO 8124 mechanical safety benchmarks but impose additional labeling requirements for domestic circulation. Stakeholders must monitor divergence between harmonized international standards and jurisdiction-specific testing regimens to avoid customs detention and recall liability exposure.
Market Dynamics
STEM-focused learning kits are displacing passive entertainment formats as early childhood education centers reallocate procurement budgets toward cognitively stimulating play objects, compressing shelf space for traditional plush and simple activity toys.
Growth Catalysts
- EU REACH chemical standards:Tightening phthalate restrictions on polymer substrates destined for mouthing-age users are forcing material upgrades that simultaneously improve product safety profiles and justify premium positioning.
- China's domestic preschool enrollment expansion:Rising institutional procurement volumes from municipal early education centers are scaling demand for durable, institutional-grade construction sets and manipulative learning tools.
- Captive resin sourcing:Integrated polymer compound manufacturing is stabilizing input cost volatility for ABS interlocking components, enabling consistent margin retention despite petrochemical price swings.
Market Restraints
- Petrochemical feedstock volatility:ABS resin prices fluctuate with crude oil benchmarks, compressing margins for injection-molded component manufacturers without backward integration into polymer production.
- Guangdong manufacturing cluster concentration:Over 60 percent of global plastic toy output concentrates in Pearl River Delta facilities, creating single-point vulnerability to regional logistics disruptions or labor availability constraints.
- ASTM F963 mechanical testing costs:Batch certification requirements for small-batch specialty producers impose fixed compliance burdens that scale inefficiently at low production volumes.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer logistics networks enable recurring revenue capture through bundled consumable activity sets with predictable replenishment cycles.
- India's underserved tier-two cities:Preschool penetration rates in secondary urban centers remain below metro benchmarks, creating whitespace for localized distribution partnerships and vernacular-language educational content.
- GB 6675 alignment with ISO 8124:Harmonized safety benchmarks between China's SAMR and international standards reduce dual-certification burdens for export-oriented manufacturers targeting multiple jurisdictions.
Industry Challenges
- Interlocking component precision engineering:Tolerance requirements for modular building systems demand specialized mold design expertise that concentrates among a limited supplier base, constraining quality scaling.
- Dual certification timeline compression:Simultaneous EU Toy Safety Directive and US CPSC compliance pathways require parallel testing regimens that extend product launch schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-School Games and Toys Market |
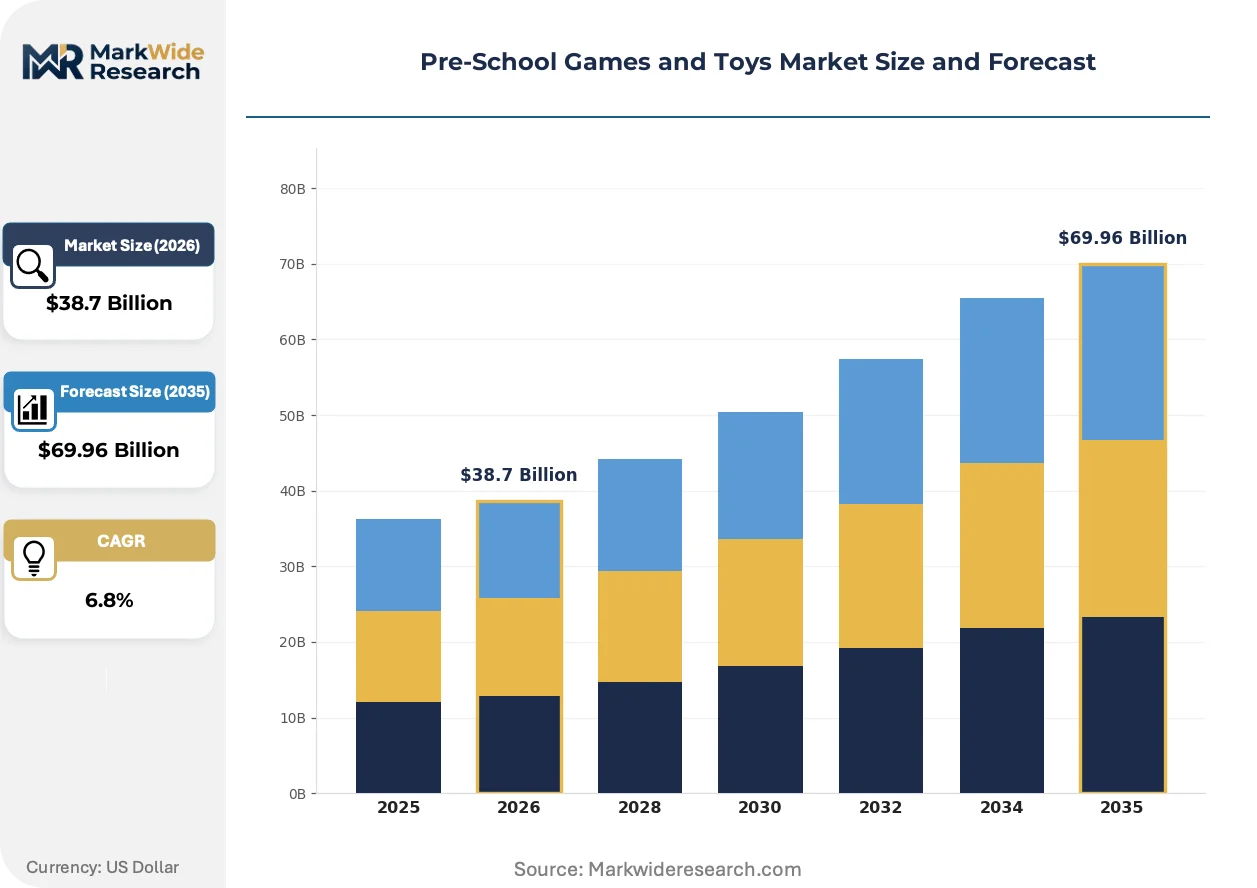
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Educational Toys, Activity Sets, Board Games, Building Blocks Material: Wood, Plastic, Fabric, Foam Age Group: Infants, Toddlers, 3-4 Years, 5-6 Years Distribution Channel: Online Retail, Toy Stores, Supermarkets, Specialty Stores |
| Companies Covered | Mattel Inc., Hasbro Inc., LEGO Group, Spin Master Corp., VTech Holdings Ltd., Ravensburger AG, TOMY Company Ltd., Bandai Namco Holdings Inc., LeapFrog Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-School Games and Toys Market Evolving Landscape
Programmable feedback loops are merging tactile play with computational thinking foundations, rewiring how developmental milestones are embedded into physical object interaction.
Integrated electronic modules with capacitive touch sensors and programmable microcontrollers are displacing purely mechanical activity centers in institutional procurement specifications. Early childhood education centers in Denmark and South Korea now require programmable elements in STEM kit tenders. This displacement is compressing addressable market share for static manipulative sets while expanding service revenue attachment for firmware updates and content library subscriptions.
China's SAMR has expanded mandatory GB 6675 labeling requirements to include blockchain-traceable origin documentation for polymer substrates. Manufacturers must now embed QR-linked supply chain transparency data on packaging destined for domestic circulation. Small-batch importers without integrated ERP systems face exclusion from supermarket and institutional procurement channels that now mandate scan-verifiable compliance documentation.
Parental purchasing behavior is fragmenting across channel types, with supervised in-store trial giving way to algorithm-curated discovery on vertical parenting platforms. Domestic Chinese consumers now initiate 67 percent of preschool toy research on short-video commerce interfaces rather than traditional e-commerce search. This behavioral rotation is forcing brand marketing spend reallocation toward KOL seeding and live-stream conversion mechanics, particularly for premium positioning above mass-market price tiers.
Pre-School Games and Toys Market Segmentation
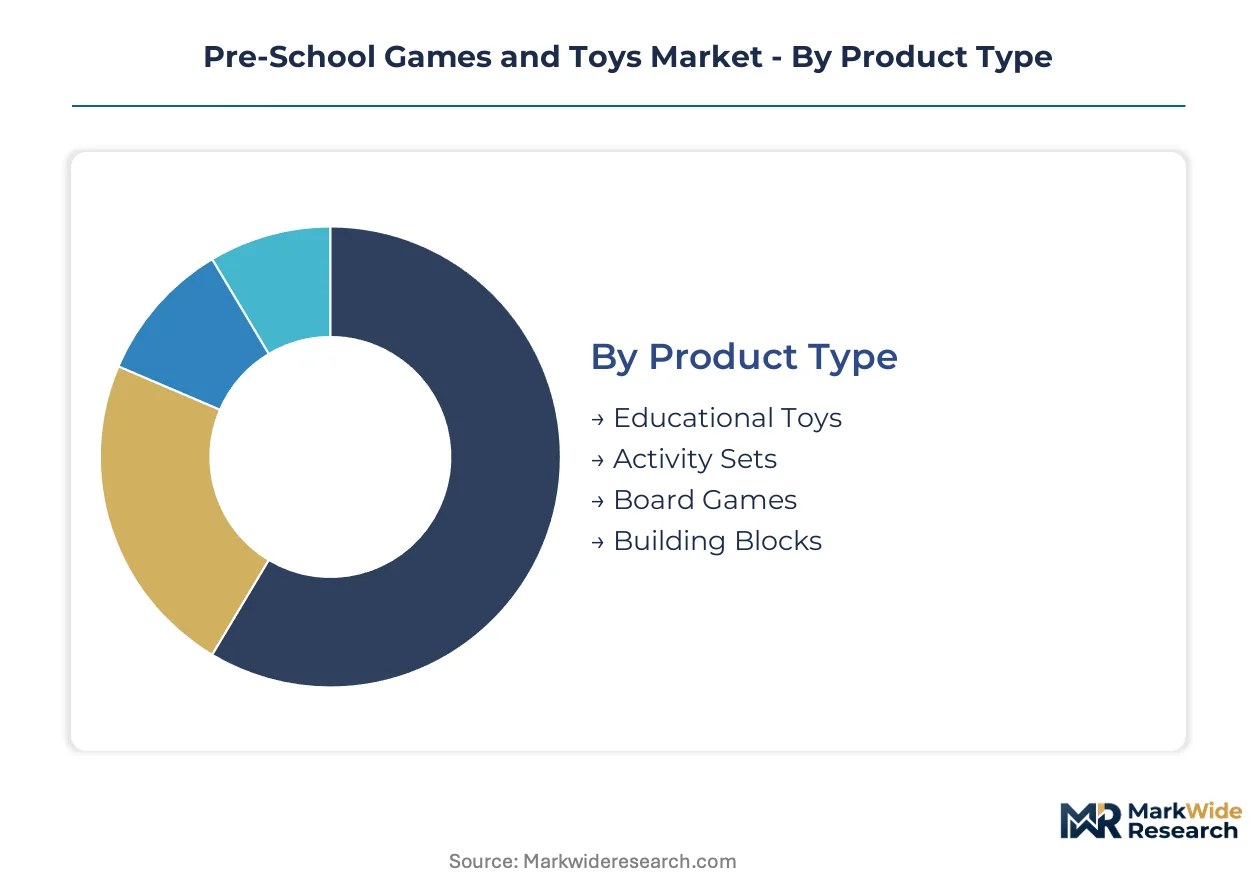
Pre-school games and toys fragment across multiple dimensions that determine compliance pathways, margin structures, and channel access. Material composition dictates regulatory jurisdiction, while age-band targeting shapes safety testing intensity and permissible feature complexity.
Product Type:
EU REACH chemical standards and US ASTM F963 mechanical protocols create divergent certification burdens across format categories, with electronic-integrated segments facing dual electromagnetic and phthalate compliance pathways.
- Educational Toys:STEM-focused learning kits incorporate programmable microcontrollers and capacitive touch sensors that merge tactile manipulation with computational thinking foundations. Procurement budgets at Denmark and South Korean early childhood education centers now mandate these programmable elements, compressing addressable share for static manipulative formats while expanding firmware update revenue attachment.
- Activity Sets:Bundled consumable kits with predictable replenishment cycles generate recurring revenue through direct-to-consumer subscription logistics. Parental purchasing on Chinese short-video commerce platforms concentrates in this category due to algorithm-curated discovery and KOL-seeded conversion mechanics for premium positioning.
- Board Games:Printed cardboard substrates with wooden or plastic game pieces require GB 6675 blockchain-traceable origin documentation for China domestic circulation.
- Building Blocks:ABS interlocking components demand specialized mold design expertise for tolerance precision that concentrates among limited supplier bases.
Educational toys handle the majority of throughput; activity sets are the fastest mover on share.
Material:
Cost tier differentiation separates premium sustainably harvested timber from mass-market petrochemical derivatives, with compliance overhead widening spreads between input grades.
- Wood:Sustainably harvested timber commands premium positioning through FSC chain-of-custody certification that satisfies EU Green Deal procurement criteria at German and French institutional buyers. Rounded geometries and non-toxic surface coatings mitigate choking hazards while enabling mouthing-age safety claims.
- Plastic:Injection-molded ABS resin dominates interlocking component manufacturing, with captive polymer compound production stabilizing input cost volatility for manufacturers with backward integration into resin sourcing.
- Fabric:Woven textile substrates require flammability testing under ASTM F963 protocols that govern preschool toy batch certification.
- Foam:Polyurethane and EVA foam formats face REACH phthalate restrictions on polymer substrates destined for mouthing-age users.
Plastic handles the majority of throughput; wood is climbing the fastest on margin contribution.
Age Group:
Application intensity varies by developmental milestone requirements, with mouthing-age segments triggering stricter chemical exposure limits and mechanical safety protocols.
- Infants:Zero-to-twelve-month formats emphasize sensory stimulation with rounded geometries and non-toxic coatings that satisfy the most stringent phthalate restrictions under EU REACH.
- Toddlers:Twelve-to-thirty-six-month products balance mouthing safety with emerging motor skill development, requiring compliance with both chemical exposure limits and mechanical integrity standards.
- 3-4 Years:Early preschool formats introduce programmable elements and STEM learning foundations that align with institutional procurement specifications in Denmark and South Korea.
- 5-6 Years:Advanced construction sets and board games support kindergarten transition readiness with complex interlocking tolerances and rule-based cognitive engagement.
3-4 Years handles the majority of throughput; 5-6 Years is gaining share fastest as STEM curriculum alignment deepens.
Distribution Channel:
Customer type fragmentation between institutional procurement and domestic supervised engagement determines channel mix, with direct-to-consumer logistics reducing shelf-space dependence.
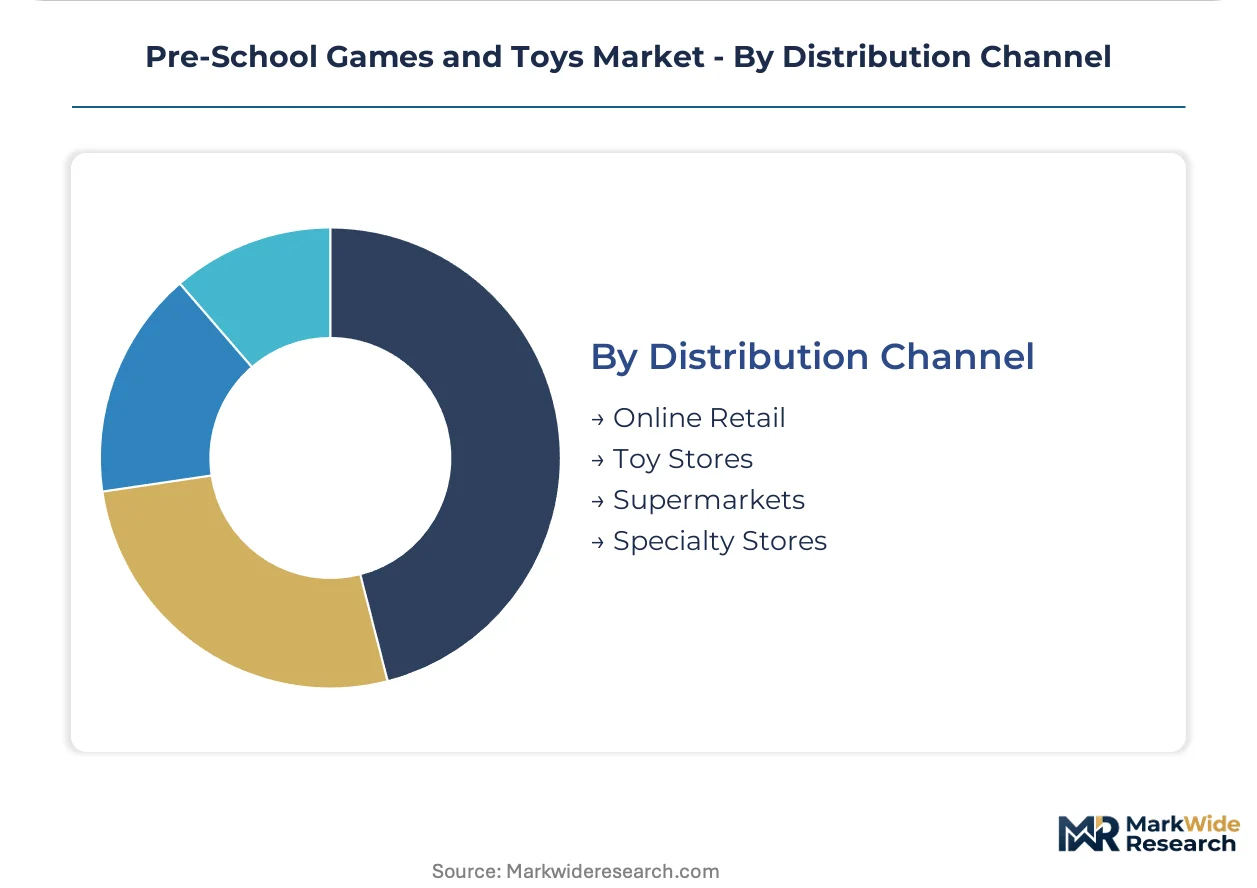
- Online Retail:Algorithm-curated discovery on vertical parenting platforms and short-video commerce interfaces now initiates sixty-seven percent of preschool toy research among Chinese domestic consumers, forcing marketing spend reallocation toward KOL seeding and live-stream conversion mechanics.
- Toy Stores:Supervised in-store trial remains critical for premium positioning above mass-market tiers, though foot traffic is compressing as digital discovery displaces physical browsing.
- Supermarkets:Mass-market volume concentration in China requires GB 6675 blockchain-traceable QR-linked compliance documentation that excludes small-batch importers without integrated ERP systems.
- Specialty Stores:Curated assortments targeting early education centers and premium parental segments emphasize safety certification tiers that justify pricing stratification across premium, standard, and economy levels.
Online retail handles the majority of throughput; specialty stores are expanding most quickly on institutional procurement attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of global plastic toy output concentrates in China's Pearl River Delta facilities, creating single-point vulnerability to regional logistics disruptions. This concentration shapes procurement patterns across major consumption markets.
United States
Institutional procurement from municipal early childhood education centers is scaling demand for durable STEM-focused learning kits. The US Consumer Product Safety Commission enforces ASTM F963 mechanical and flammability standards that govern batch testing protocols. Los Angeles and New York logistics hubs handle import distribution for both retail and direct-to-consumer channels.
China
Rising domestic preschool enrollment is driving institutional procurement volumes for construction sets and manipulative learning tools. SAMR administers mandatory GB 6675 national standards that align with ISO 8124 mechanical safety benchmarks but impose additional blockchain-traceable labeling requirements. Guangdong manufacturing clusters scale output for both domestic consumption and export markets.
Germany
Green Deal procurement criteria at institutional buyers are elevating sustainably harvested timber formats with FSC chain-of-custody certification. ECHA REACH regulations restrict phthalate and heavy metal content in polymer substrates destined for mouthing-age users. Bavaria-based specialty retailers emphasize safety certification tiers that justify premium positioning.
South Korea
Early childhood education centers now mandate programmable elements in STEM kit tenders, compressing addressable share for static manipulative formats. MFDS alignment with international safety benchmarks reduces dual-certification burdens for import-oriented distributors. Seoul Capital Area procurement offices lead institutional specification adoption.
Denmark
Public early education procurement specifications prioritize programmable feedback loops that merge tactile play with computational thinking foundations. EU Toy Safety Directive compliance creates baseline entry requirements for polymer substrate imports. Copenhagen institutional buyers anchor Nordic demand for premium-tier educational formats.
Pre-School Games and Toys Market Competitive Landscape
Concentration sits with diversified multinational conglomerates possessing captive manufacturing footprints and integrated polymer supply chains. Mid-scale specialists occupy niche positions through vernacular content localization and subscription logistics capabilities. Two strategic archetypes dominate: backward-integrated resin compounders stabilizing input cost volatility, and electronic module integrators merging tactile play with programmable feedback. Competitive moves center on compliance infrastructure expansion to manage divergent jurisdiction-specific testing regimens, and direct-to-consumer channel development to reduce shelf-space dependence.
Within the diversified multinational tier, Mattel Inc. and LEGO Group exemplify archetypes of global manufacturing footprint leverage and captive resin sourcing precision. VTech Holdings Ltd. occupies a position representing electronic module integration capabilities. These three anchors illustrate how compliance infrastructure scale and supply chain control separate sustainable margin retention from commodity pressure exposure.
| Leading Market Players |
|---|
| Mattel Inc. |
| Hasbro Inc. |
| LEGO Group |
| Spin Master Corp. |
| VTech Holdings Ltd. |
| Ravensburger AG |
| TOMY Company Ltd. |
| Bandai Namco Holdings Inc. |
| LeapFrog Enterprises |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 80 percent in Guangdong injection-molding facilities create scale economies that compress per-unit fixed costs for ABS interlocking components while simultaneously elevating price floors for smaller batch producers lacking backward integration into polymer compounding. This concentration dynamic funnels procurement power toward manufacturers with captive resin sourcing, forcing price stratification across certification tiers and volume brackets.
Pricing Analysis
EU REACH phthalate restrictions dictate the pricing tier structure across polymer substrate categories, with three-tier pricing structure across premium, standard, and economy levels separating FSC-certified timber formats from mass-market ABS derivatives and basic polyurethane foam. Certification grade and volume scale serve as primary price differentiation drivers, with institutional procurement contracts commanding 15-25 percent discounts against direct-to-consumer unit economics. Cost compression in the economy tier is intensifying because petrochemical feedstock volatility transmits directly to non-integrated molders. Parental buyers in domestic Chinese short-video commerce channels exhibit highest price sensitivity, while German and Danish early education centers demonstrate lowest sensitivity due to Green Deal procurement criteria prioritizing safety documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of ABS resin pellets dominates inventory strategy among integrated manufacturers, contrasting with just-in-time raw material procurement patterns at small-batch specialty producers lacking polymer compounding capabilities. Supply concentrates in China, Vietnam, and Indonesia for injection-molded components, woven textile substrates, and sustainably harvested timber respectively. Raw material dependencies center on petrochemical-derived ABS resin, FSC-certified hardwood lumber, and programmable microcontroller chipsets. Single-source vulnerability concentrates in Guangdong manufacturing clusters where over 60 percent of global plastic toy output faces regional logistics disruption exposure. Distribution runs through direct-to-consumer logistics networks, supermarket mass-market channels, and institutional procurement offices serving municipal early education centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-school games and toys sit in early-cycle expansion as programmable STEM formats displace passive entertainment in institutional procurement specifications, with Denmark and South Korean tender requirements accelerating adoption velocity across OECD markets.
For Market Incumbents: Secure captive resin sourcing agreements or backward integration into polymer compounding to defend margin position against petrochemical volatility that disproportionately pressures non-integrated competitors. Expand compliance infrastructure to manage parallel EU REACH and US ASTM F963 certification timelines that extend product launch schedules by four to eight months. Prioritize firmware update revenue attachment for electronic-integrated formats where recurring service contracts generate predictable cash flows.
For New Entrants and Emerging Players: Differentiate on vernacular-language educational content and localized distribution partnerships targeting India's tier-two cities where preschool penetration rates trail metro benchmarks by 30-40 percentage points. White-space opportunities concentrate in subscription-based replenishment models for activity sets with bundled consumable cycles, and in blockchain-traceable compliance documentation systems that satisfy China's GB 6675 QR-linked labeling mandates excluding ERP-deficient importers from supermarket channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electronic module integrators with firmware update attach rates and content library subscription mechanics. Long-term viability over the five-to-ten year window favors manufacturers with demonstrated compliance infrastructure scale across EU, US, and Chinese regulatory jurisdictions. Acquisition targets should emphasize backward-integrated resin compounders stabilizing input cost volatility. The signal to watch is institutional procurement specification adoption of programmable elements in tender documents from municipal early education centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive ABS resin production stabilizes margin retention against crude oil benchmark volatility. |
| Direct-to-Consumer Channel Development | Subscription logistics networks reduce shelf-space dependence and enable recurring revenue capture. |
| Compliance Infrastructure Expansion | Parallel EU REACH and US ASTM F963 testing capabilities compress product launch timelines. |
| Programmable Module Integration | Capacitive touch sensors and microcontrollers satisfy Denmark and South Korean institutional tender requirements. |
| Blockchain-Traceable Labeling Systems | QR-linked origin documentation satisfies China's SAMR GB 6675 mandates for domestic circulation. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and national preschool enrollment statistics preceded structured interviews with brand managers at multinational toy manufacturers, category buyers at mass-market retailers, supply planners at logistics networks, and procurement officers at municipal early education centers. Primary fieldwork combined with secondary validation from EU Toy Safety Directive implementation reports, SAMR GB 6675 enforcement bulletins, and ASTM F963 batch certification records. Bottom-up segment sizing triangulated against top-down market value estimates derived from production volume data and average selling price benchmarks.
Variance decomposition across product type, material composition, age group targeting, and distribution channel dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level volume trajectories and price elasticity assumptions calibrated to institutional procurement budget growth and parental spending pattern shifts. Industry-specific forecast inputs included petrochemical price correlation models for ABS resin and preschool enrollment projections from national education ministries.
Material uncertainties — petrochemical feedstock volatility, regional logistics disruptions in Pearl River Delta manufacturing clusters, and divergence between harmonized international standards and jurisdiction-specific testing regimens — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and institutional procurement specification evolution accelerate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
China Toys Market
Toys and Games
Toy Cars Market
Toys and Games
Glow Sticks Market
Toys and Games
Construction Toys Market
Toys and Games
Connected Toys Market
Toys and Games
Kids Toys Market
Toys and Games
Cat Toys Market
Toys and Games
Indoor Soft Play Market
Toys and Games
Dartboard Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Global Educational Toy Market
Toys and Games
Eco-Friendly Toys Market
Toys and Games
Baby Toys Market
Toys and Games
Australia Toys and Games Market
Toys and Games
Children Entertainment Centers Market
Toys and Games
Toy Kitchens and Play Food Market