
 Cocamide Monoethanolamine Market | 2026-2036
Cocamide Monoethanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Cocamide Monoethanolamine Market Outlook
China is reshaping supply dynamics for cocamide monoethanolamine through aggressive fatty acid derivative capacity additions. Colonial Chemical leverages vertical integration into coconut oil feedstocks to sustain margin stability. BASF SE anchors European demand with specialized grades for mild surfactant systems. Yeser Chemicals competes on cost-optimized liquid formulations for Asian detergent producers.
Cocamide monoethanolamine functions as a non-ionic surfactant produced via amidation of coconut fatty acids with monoethanolamine, typically containing 78-82% amide content with low free amine specifications for cosmetic-grade applications. It serves primarily as a foam booster, viscosity builder, and emulsifier across rinse-off personal care and hard-surface cleaning formulations. Liquid grades dominate volume throughput due to easier handling in continuous detergent manufacturing, while powder formats command premium positioning in solid shampoo bars and travel-size personal care where water-free processing matters. Personal care applications lead value capture given formulation complexity and certification requirements, whereas industrial cleaning represents a mature, price-sensitive volume channel.
REACH registration requirements and EU Green Deal bio-based content mandates in Europe constrain petrochemical-derived supply while creating preferential market access for RSPO-certified feedstock chains. China's GB standards for cosmetic raw materials and SAMR surfactant safety evaluations impose parallel compliance burdens on exporters targeting domestic formulators. India's BIS quality certification for detergent-grade amides adds another layer of market entry conditioning. Stakeholders must monitor regulatory divergence between bio-based content thresholds and traditional performance benchmarks to align R&D portfolios with shifting compliance landscapes.
Market Dynamics
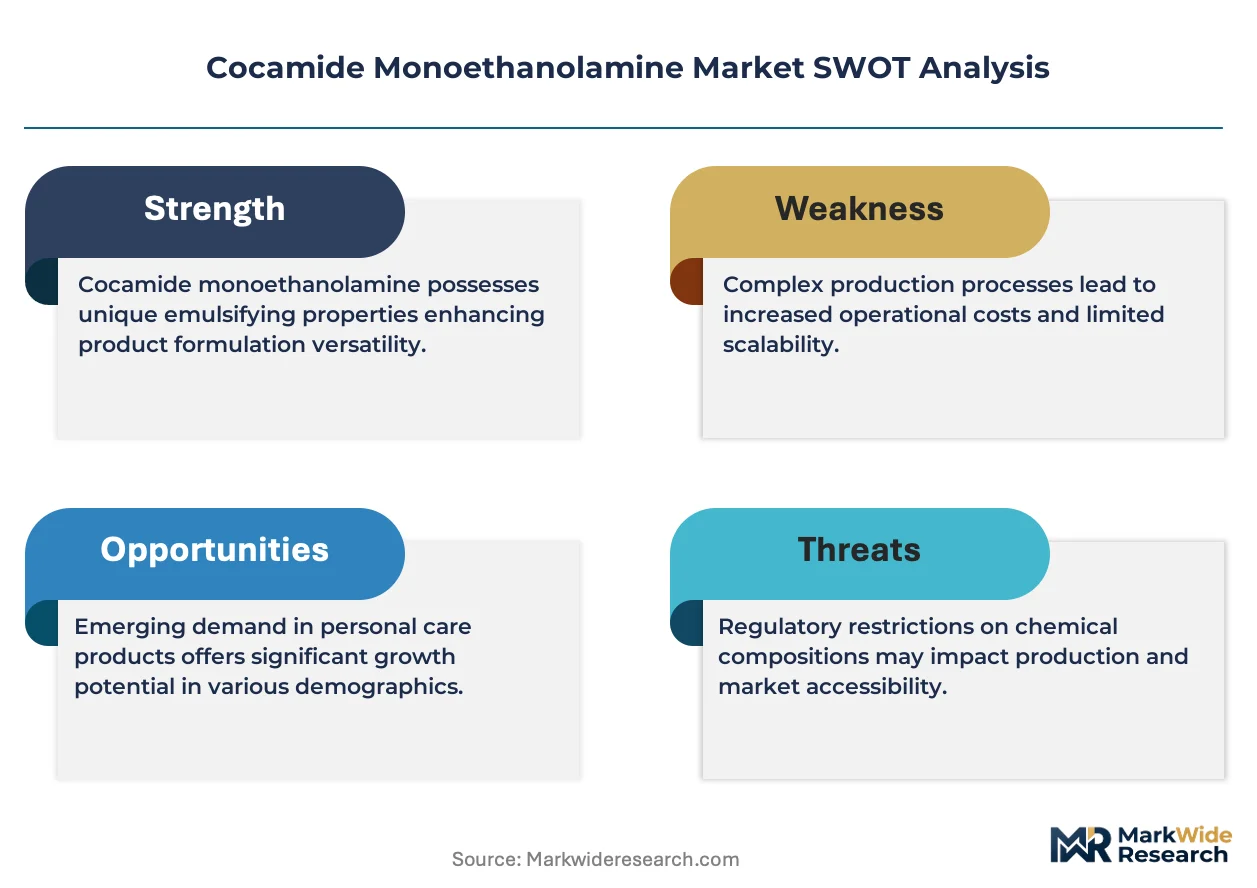
Sulfate-free surfactant reformulation is compressing formulation windows for cocamide monoethanolamine suppliers, forcing simultaneous performance maintenance and feedstock certification upgrades across personal care supply chains.
Growth Catalysts
- REACH bio-based mandates:EU Green Deal content thresholds create preferential procurement lanes for RSPO-certified amide producers serving European personal care formulators.
- Hard-surface cleaning automation:Continuous detergent manufacturing lines in industrial laundries demand liquid-grade foam boosters with consistent viscosity profiles.
- China's fatty acid ethoxylate expansion:Domestic capacity additions in Shandong and Jiangsu provinces reduce import dependency for coconut-derived feedstocks.
Market Restraints
- Coconut oil price volatility:Weather-driven supply fluctuations in Southeast Asian plantation zones transmit directly to amide production economics.
- Monoethanolamine supply concentration:Petrochemical-derived MEA availability tightens when ethylene oxide crackers undergo maintenance cycles.
- Alkyl polyglucoside substitution:Starch-based surfactants capture mild-cleansing positioning in premium shampoo segments previously dominated by cocamides.
Strategic Opportunities
- Solid shampoo bar penetration:Water-free personal care formats in Germany and France require powder-grade amides with low moisture specifications.
- India BIS certification pathways:Detergent-grade amide standardization opens formal market access for exporters targeting domestic laundry compounders.
- SAMR cosmetic raw material registration:Pre-approval of amide specifications for Chinese domestic formulators reduces technical barrier friction for qualified suppliers.
Industry Challenges
- Amidation process optimization:Maintaining 78-82% amide content while suppressing free amine levels below cosmetic-grade thresholds demands precise temperature-pressure control.
- Dual certification timelines:Simultaneous pursuit of RSPO supply chain and REACH full registration stretches compliance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocamide Monoethanolamine Market |
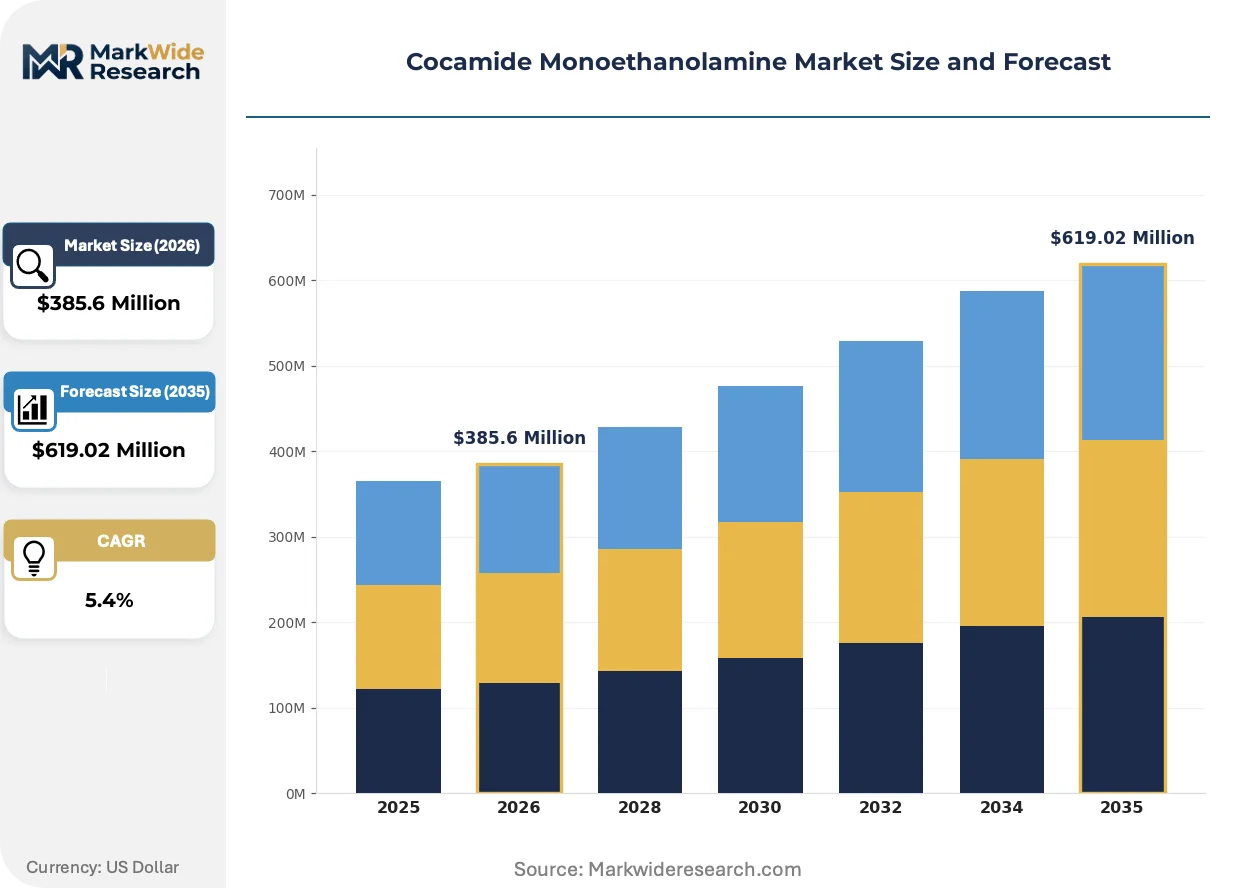
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Paste Application: Personal Care, Household Cleaners, Industrial Cleaning, Textile End User: Cosmetics Manufacturers, Detergent Producers, Textile Industry, Food Processing Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Colonial Chemical, Yeser Chemicals, BASF SE, Zanyu Technology Group, Lubrizol, Croda International, Kao, Ele Corporation, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocamide Monoethanolamine Market Strategic Shifts
Enzymatic amidation pathways and bio-based feedstock traceability systems are restructuring competitive differentiation in cocamide monoethanolamine manufacturing.
Enzymatic catalyst systems for coconut fatty acid amidation are migrating from pilot-scale demonstration to commercial production. Specialty chemical producers in the Netherlands and Germany adopt lipase-mediated processes to reduce energy intensity. This technology is migrating from niche pharmaceutical applications toward commodity surfactant manufacturing, compressing the cost premium between bio-based and conventional routes.
EU Green Deal bio-based content verification frameworks now require mass-balance documentation across fatty acid derivative supply chains. Cosmetic formulators in France and Germany demand blockchain-traceable coconut oil sourcing to satisfy CSRD disclosure requirements. Personal care brands with premium positioning are responding by locking multi-year supply agreements with RSPO-certified plantation operators.
Direct procurement relationships between personal care brands and amide producers are displacing traditional distributor intermediaries in European supply chains. Large formulators in Germany consolidate purchase volumes to secure dedicated production slots and custom specification development. This channel restructuring is most visible in rinse-off cosmetic segments where formulation complexity justifies technical collaboration between supplier and end-user R&D functions.
Cocamide Monoethanolamine Market Segmentation
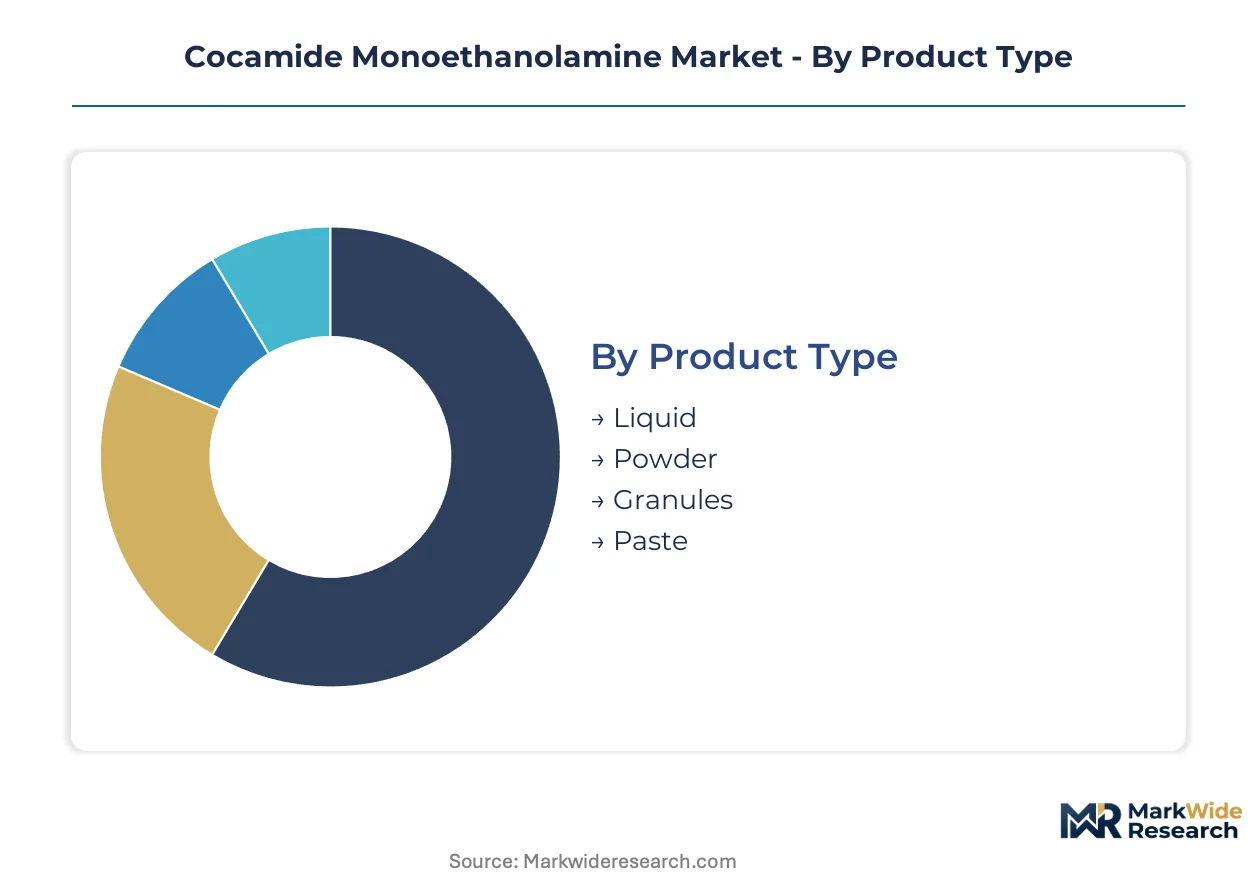
Cocamide monoethanolamine manufacturers configure production assets around physical form factors that dictate handling economics and end-use compatibility. Segment boundaries reflect tension between continuous-process detergent manufacturing and batch cosmetic compounding requirements.
Product Type:
Use-case spectrum spans automated liquid dosing systems through water-free solid processing formats.
- Liquid:Standard 78-82% amide content solutions dominate continuous manufacturing lines in industrial laundries and large-scale detergent plants. German and Chinese formulators specify consistent viscosity profiles for automated dosing equipment.
- Powder:Spray-dried grades with sub-2% moisture content enable solid shampoo bar production in France and Germany where water-free cosmetic processing commands premium positioning. RSPO-certified feedstock chains add compliance layer for EU Green Deal disclosure requirements.
- Granules:Free-flowing agglomerated formats suit automated powder blending in Indian detergent compounders seeking BIS-certified inputs.
- Paste:High-concentration semisolid grades serve small-batch cosmetic manufacturers in Japan requiring precise metering without solvent handling.
The dominant share belongs to Liquid, while Powder is closing the gap fastest.
Application:
Cost tier stratification separates certification-intensive cosmetic segments from price-sensitive industrial channels.
- Personal Care:Rinse-off formulations in Germany and France demand REACH-registered grades with suppressed free amine levels below 0.5%. Enzymatic amidation processes from Dutch specialty producers reduce energy intensity for premium positioning.
- Household Cleaners:Hard-surface spray and liquid laundry applications in China absorb volume throughput from Shandong and Jiangsu fatty acid derivative capacity. SAMR cosmetic raw material registration adds compliance friction for exporters.
- Industrial Cleaning:Automated CIP systems in food processing plants specify foam-controlled liquid grades with predictable viscosity temperature coefficients.
- Textile:Scouring and wetting agent applications in Indian textile clusters prioritize cost-optimized liquid formulations over certification requirements.
Personal Care commands the value premium, though Household Cleaners generates the steepest volume expansion.
End User:
Customer type diversity stretches from multinational cosmetic brands through regional detergent compounders.
- Cosmetics Manufacturers:German and French formulators consolidate procurement volumes to secure dedicated production slots and custom specification development with RSPO-certified suppliers.
- Detergent Producers:Indian laundry compounders drive BIS certification adoption for domestic market access, while Chinese producers leverage local fatty acid ethoxylate capacity.
- Textile Industry:Processing mills in India and Bangladesh specify cost-optimized liquid grades for scouring and dye leveling without cosmetic-grade purity premiums.
- Food Processing:Equipment cleaning operations in regulated markets specify amide grades meeting national food contact material standards.
Cosmetics Manufacturers anchor value capture, with Detergent Producers expanding most quickly.
Distribution Channel:
Supply concentration patterns favor direct technical relationships over intermediated trade.
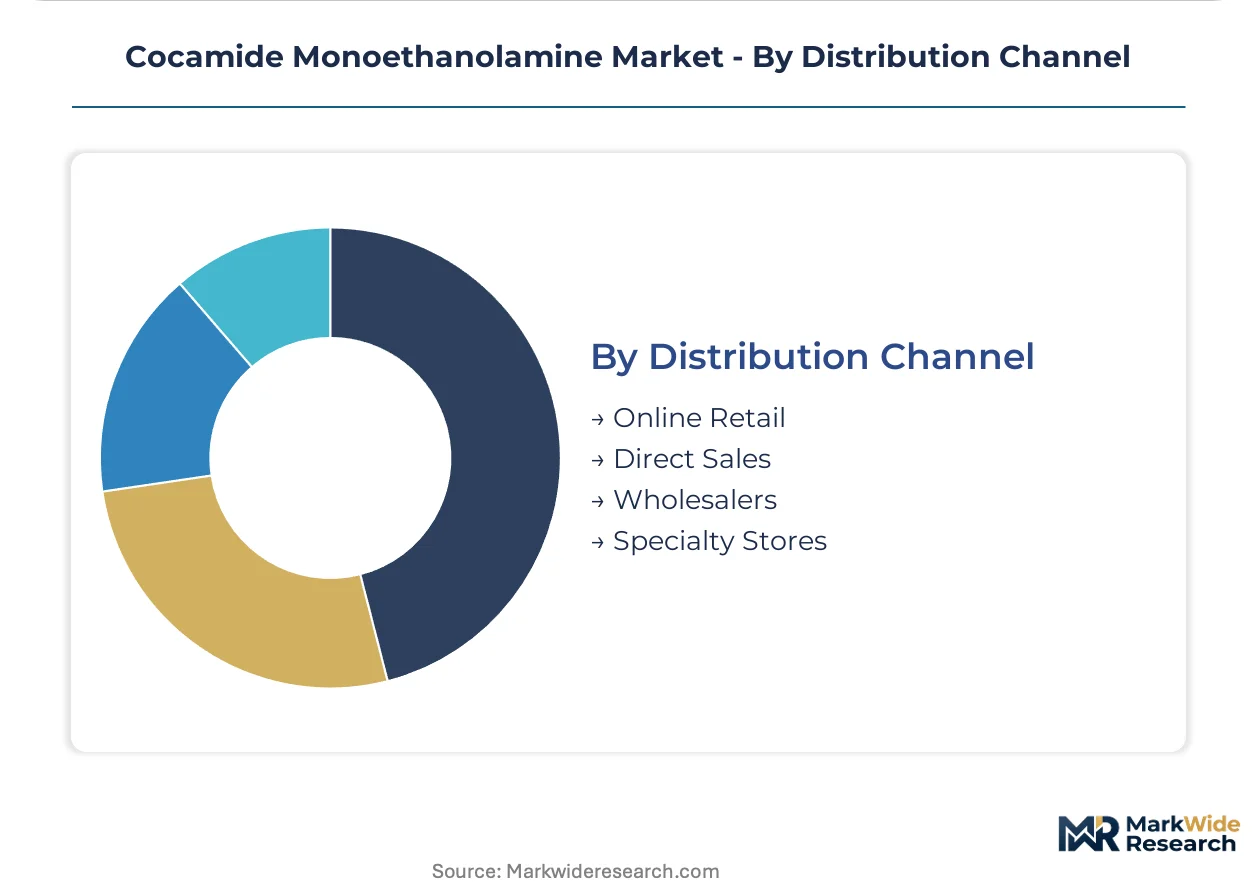
- Direct Sales:Large German personal care formulators bypass distributors to lock multi-year supply agreements with plantation-integrated producers, securing blockchain-traceable RSPO certification for CSRD compliance.
- Wholesalers:Regional chemical distributors in India and Southeast Asia aggregate fragmented detergent producer demand, carrying inventory for BIS-certified and standard grades.
- Online Retail:Specialty chemical marketplaces serve small-batch cosmetic manufacturers in Japan and South Korea requiring kilogram-scale powder grades with rapid specification verification.
- Specialty Stores:Technical service-oriented distributors in the Netherlands provide formulation support alongside amide supply for enzymatic amidation adopters.
Direct Sales holds the dominant procurement share, while Online Retail is gaining traction fastest among small-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut fatty acid derivative capacity clusters in coastal manufacturing zones across four major economies. Each regional formation responds to distinct regulatory pressures and end-use demand patterns.
China
Shandong and Jiangsu provinces host expanding fatty acid ethoxylate operations that reduce import dependency for coconut-derived feedstocks. GB standards for cosmetic raw materials and SAMR surfactant safety evaluations impose compliance burdens on exporters targeting domestic formulators. Local producers in these coastal clusters scale amidation capacity to serve both household cleaner compounders and personal care manufacturers.
Germany
REACH registration requirements and EU Green Deal bio-based content mandates constrain petrochemical-derived supply while creating preferential access for RSPO-certified feedstock chains. German formulators consolidate procurement volumes to secure dedicated production slots and custom specification development. The Rhine-Ruhr industrial corridor anchors enzymatic amidation technology adoption among specialty chemical producers.
United States
Personal care brands with sulfate-free positioning drive reformulation demand across rinse-off cosmetic segments. EPA oversight of industrial surfactant applications intersects with state-level chemical disclosure requirements in California and New York. Colonial Chemical maintains operations in Tennessee with backward integration into coconut oil feedstocks.
India
BIS quality certification for detergent-grade amides adds market entry conditioning for exporters targeting domestic laundry compounders. Textile processing mills in Gujarat and Tamil Nadu specify cost-optimized liquid grades for scouring applications without cosmetic-grade purity premiums. Mumbai-Pune chemical clusters absorb volume throughput from regional fatty acid derivative producers.
France
CSRD disclosure requirements push cosmetic formulators toward blockchain-traceable coconut oil sourcing for premium positioning. The EU Green Deal verification frameworks demand mass-balance documentation across fatty acid derivative supply chains. Lyon and Paris basin formulators lock multi-year supply agreements with RSPO-certified plantation operators.
Cocamide Monoethanolamine Market Competitive Environment
Plantation-integrated specialists and petrochemical-backed diversified producers split the market between feedstock security and formulation science capabilities. The structure tilts toward consolidation at the top tier with fragmented regional specialists serving price-sensitive detergent channels. Three archetypes dominate: vertically integrated coconut processors, enzymatic technology adopters, and cost-optimized Asian commodity producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure RSPO certification and REACH registration simultaneously.
Among plantation-integrated fabricators, Colonial Chemical exemplifies backward integration into coconut oil supply chains. BASF SE anchors European demand with specialized grades for mild surfactant systems. Yeser Chemicals occupies a position within the cost-optimized liquid formulation tier serving Asian detergent producers. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| Colonial Chemical |
| Yeser Chemicals |
| BASF SE |
| Zanyu Technology Group |
| Lubrizol |
| Croda International |
| Kao |
| Ele Corporation |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu province capacity clusters in China anchor raw material availability for coconut fatty acid derivatives, concentrating margin capture with plantation-integrated suppliers while spot-market buyers absorb volatility from Southeast Asian weather disruptions.
Pricing Analysis
REACH registration dictates the pricing tier structure across European personal care channels, separating RSPO-certified premium grades from standard detergent-tier offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with cosmetic-grade amide content thresholds and free amine specifications commanding substantial premiums. Cost compression in standard liquid grades is intensifying because Shandong producers scale ethoxylate capacity. Detergent compounders in India exhibit highest price sensitivity, while German rinse-off formulators prioritize specification compliance over unit cost.
Supply Chain Analysis
Coconut oil feedstock availability hinges on plantation output across Indonesia, Philippines, and Malaysia, with weather-driven supply fluctuations transmitting directly to amide production economics. Monoethanolamine supply draws from petrochemical crackers concentrated in China, Germany, and the United States. Single-source vulnerability in ethylene oxide derivative channels tightens when crackers undergo maintenance cycles. Distribution runs through direct technical relationships between large formulators and plantation-integrated producers, displacing traditional distributor intermediaries in European supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification development services and formulation partnership agreements represent a faster-expanding revenue layer than commodity amide sales, as personal care brands consolidate procurement volumes to secure dedicated technical collaboration.
For Market Incumbents: Insulate margin stability through captive coconut oil sourcing and multi-year RSPO certification lock-ins with plantation operators. Alkyl polyglucoside substitution in premium shampoo segments threatens cocamide positioning, demanding accelerated enzymatic amidation R&D to reduce energy intensity and defend specification premium.
For New Entrants and Emerging Players: Establish a beachhead in Indian BIS-certified detergent-grade supply, where domestic laundry compounders seek qualified import alternatives. Solid shampoo bar penetration in France and Germany offers white-space positioning for powder-grade specialists with sub-2% moisture capabilities and blockchain-traceable feedstock documentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical platforms that acquired regional surfactant producers during prior consolidation waves. Five-to-ten year viability favors plantation-integrated mid-caps with simultaneous REACH full registration and RSPO supply chain certification. The signal to watch is SAMR cosmetic raw material pre-approval velocity, which indicates technical barrier friction reduction for qualified suppliers targeting Chinese domestic formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Oil Feedstocks | Colonial Chemical's Tennessee operations demonstrate margin insulation against Southeast Asian weather volatility. |
| Enzymatic Amidation Scale-Up | Dutch and German specialty producers reduce energy intensity to compress bio-based cost premiums. |
| RSPO Certification Investment | EU Green Deal mass-balance documentation requirements create preferential procurement lanes for certified chains. |
| Direct Technical Partnership Agreements | German formulators bypass distributors to secure dedicated production slots and custom specification development. |
| SAMR Pre-Approval Registration | Qualified suppliers reduce technical barrier friction for Chinese domestic cosmetic formulators. |
Study Parameters
The analysis maps liquid-grade detergent channels, powder-grade cosmetic applications, and enzymatic technology adoption tiers, each validated through procurement leads at downstream formulators, technical directors at specialty chemical producers, and regulatory affairs specialists managing REACH and SAMR submissions. Primary interviews with plant managers in Shandong and Jiangsu capacity clusters, distribution channel partners in Indian chemical wholesale networks, and R&D heads at enzymatic technology adopters combined with secondary validation from customs trade data, ACC surfactant industry reports, and ECHA registration databases. Bottom-up capacity utilization estimates and top-down demand segmentation triangulate volume outputs.
Assumptions held fixed include REACH bio-based content thresholds and EU Green Deal verification frameworks, while coconut oil price volatility and monoethanolamine cracker maintenance cycles were varied across stress scenarios. Segmentation dimensions modeled span physical form factor, application end-use, and regional production hub clusters. CAGRs were derived from normalized production capacity trajectories and end-use demand elasticity coefficients across personal care reformulation cycles and industrial cleaning automation trends. Feedstock certification adoption curves and enzymatic process cost compression rates informed industry-specific forecast inputs.
Stress conditions across coconut oil supply disruption severity, ethylene oxide derivative availability, and regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sulfate-free surfactant reformulation velocity and RSPO supply chain maturation. Cross-checking against ECHA registration progression and SAMR cosmetic raw material approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Specialty Surfactants Market
Surfactants
North America Surfactants Market
Surfactants
Amino Silicone Oil Market
Surfactants
Soap Salts Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Lauramide DEA Market
Surfactants
Cetyl Chloride Market
Surfactants
Powder Defoamers Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Zeolite for Detergents Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Selenium Sulphide Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market