
 Global Shooting Games Market | 2026-2036
Global Shooting Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shooting Games Market Foresight
South Korea's esports infrastructure build-out is tilting competitive shooter development eastward, with dedicated arenas and training facilities multiplying around Seoul and Busan. Tencent Holdings leverages its WeGame distribution platform to anchor shooter releases across Greater China. Electronic Arts sustains premium sports-shooter hybrid franchises through annualized development cycles. Valve Corporation dominates PC-based competitive ecosystems with Steam Workshop modding tools that extend title longevity beyond standard release windows.
Shooting games constitute interactive entertainment software where players engage simulated firearms combat through real-time input mechanics, typically employing hit-scan or projectile physics engines rendering ballistic trajectories at frame rates exceeding sixty per second for competitive integrity. These products serve commercial purposes spanning entertainment consumption, professional esports competition, and social platform engagement. First-Person Shooter titles occupy the largest installed base among game type segments, while Tactical Shooter subcategories command the highest per-user monetization through seasonal battle pass structures. Mobile platform deployment represents the fastest-expanding distribution channel, though Console retains the densest concentration of premium purchase revenue.
China's NMPA maintains stringent content approval queues for shooter titles, directly constraining release velocity for publishers targeting the country's substantial player base. The EU's GDPR and proposed Digital Services Act impose escalating data governance obligations on live-service shooter operators processing youth player information across European markets. ESRB age-rating protocols in the United States shape marketing channel access and retail placement for mature-rated shooter franchises. Stakeholders must weigh regulatory compliance investment against platform expansion timelines, particularly where cross-border data flows intersect with divergent regional content standards.
Market Dynamics
Live-service monetization architectures are restructuring publisher revenue models, with battle pass systems and seasonal content cadences displacing traditional boxed retail economics across mobile, console, and PC deployment channels simultaneously.
Growth Catalysts
- Esports tournament infrastructure:Dedicated competitive venues in South Korea and Southeast Asia are accelerating professional shooter league formation. Broadcast rights and sponsorship pools expand as viewership scales.
- GDPR youth data frameworks:The EU's escalating governance obligations are forcing platform operators to build compliant architecture. This creates competitive moats for operators with established compliance investment.
- Cloud gaming distribution:Low-latency streaming protocols are eliminating hardware barriers for premium shooter experiences. Emerging market player bases access console-grade fidelity without dedicated device ownership.
Market Restraints
- Content approval queue congestion:China's NMPA maintains stringent shooter title review timelines. Publisher release velocity compresses against bureaucratic throughput constraints.
- Input cost volatility:Live-service infrastructure demands continuous server and bandwidth expenditure. Energy pricing fluctuations in European data center clusters squeeze operational margins.
- Platform concentration risk:Mobile shooter distribution depends heavily on Apple App Store and Google Play Store terms. Commission structures and policy enforcement create dependency fragility.
Strategic Opportunities
- India's underpenetrated mobile base:Relatively low shooter genre saturation against massive smartphone install base presents first-mover positioning. Localized content and payment integration unlock access.
- Cross-reality convergence:VR headset penetration and AR mobile capabilities are converging with traditional shooter mechanics. Hybrid physical-digital competitive formats emerge as experimental categories.
- Brazil's regulatory tailwind:ANVISA and telecommunications frameworks show openness to imported interactive entertainment. Regional server deployment and Portuguese localization capture Latin American growth.
Industry Challenges
- Anti-cheat engineering talent scarcity:Kernel-level detection system development requires specialized cybersecurity expertise. Competitive integrity demands outpace qualified personnel supply.
- Cross-platform certification complexity:Simultaneous release across PlayStation, Xbox, Nintendo, and PC ecosystems multiplies compliance testing timelines. Version parity maintenance strains QA resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shooting Games Market |
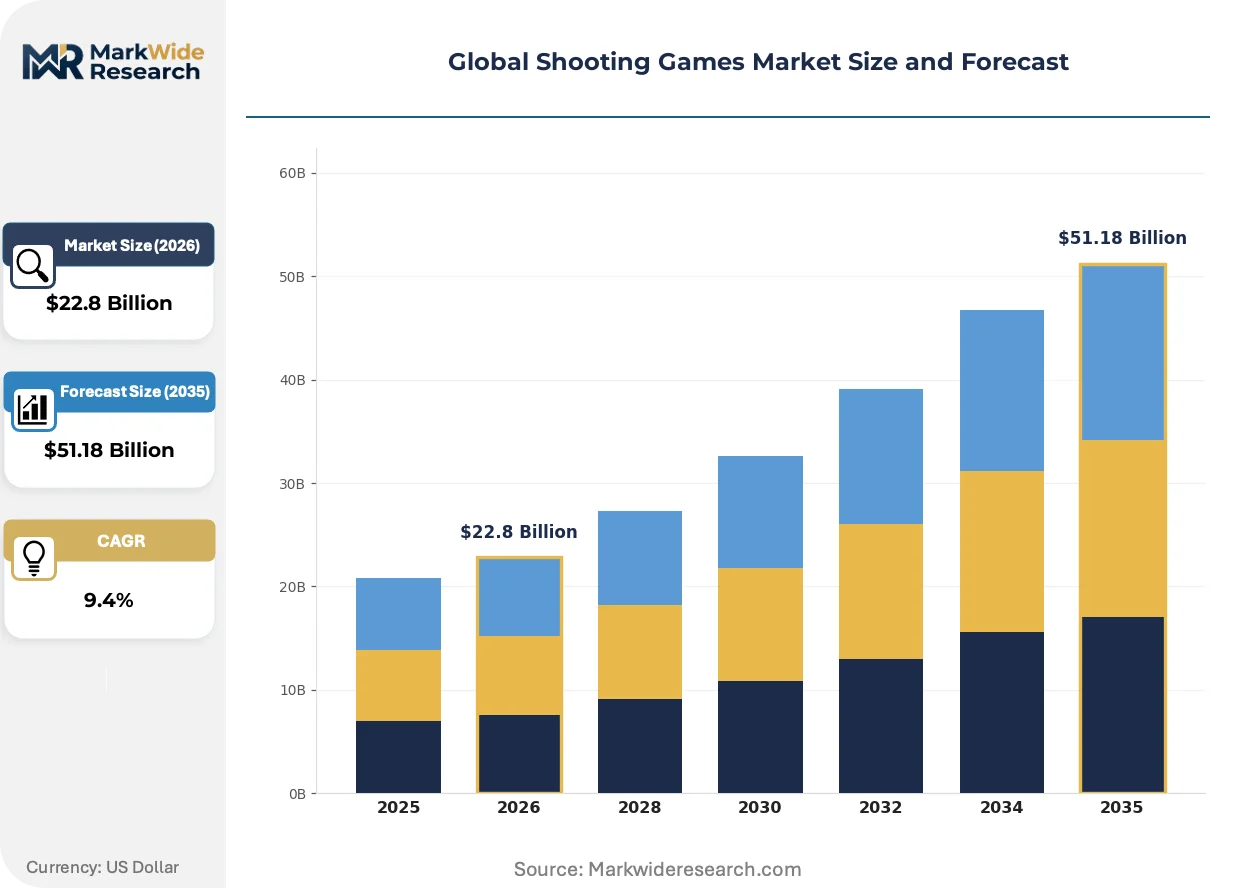
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: First-Person Shooter, Third-Person Shooter, Tactical Shooter, Light Gun Shooter, Rail Shooter Platform: Console, PC, Mobile, VR Devices, Cloud Gaming Monetization Model: Free-to-Play, Premium Purchase, Subscription, In-Game Purchases, Ad-Supported Player Mode: Single-Player, Multiplayer, Co-Op, Battle Royale, Online Competitive |
| Companies Covered | Activision Blizzard, Electronic Arts, Tencent Holdings, Ubisoft, Epic Games, Valve Corporation, Rockstar Games, Nexon, NetEase Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shooting Games Market Shifts & Advancements
Generative systems and procedural content pipelines are compressing development timelines for live-service shooter environments, while regulatory scrutiny of youth engagement mechanics intensifies across multiple jurisdictions.
AI-assisted content generation is digitizing asset production workflows for weapon skins, character cosmetics, and environmental geometry. Mid-size studios adopt these tools to match the content velocity of major publishers. The technology is digitizing the economics of seasonal update delivery, collapsing production costs that previously required hundred-person art teams.
The EU's proposed Digital Services Act imposes algorithmic transparency obligations on recommendation systems driving player engagement. Live-service operators must document and disclose how matchmaking and reward scheduling function. Mobile shooter platforms targeting European youth demographics face the steepest compliance adaptation requirements.
Subscription bundling is displacing individual title purchases as the dominant access model. Xbox Game Pass and PlayStation Plus aggregate shooter libraries into flat-fee consumption. Southeast Asian markets exhibit the fastest behavioral transition, with mobile-first players demonstrating lower attachment to perpetual ownership.
Global Shooting Games Market Segmentation
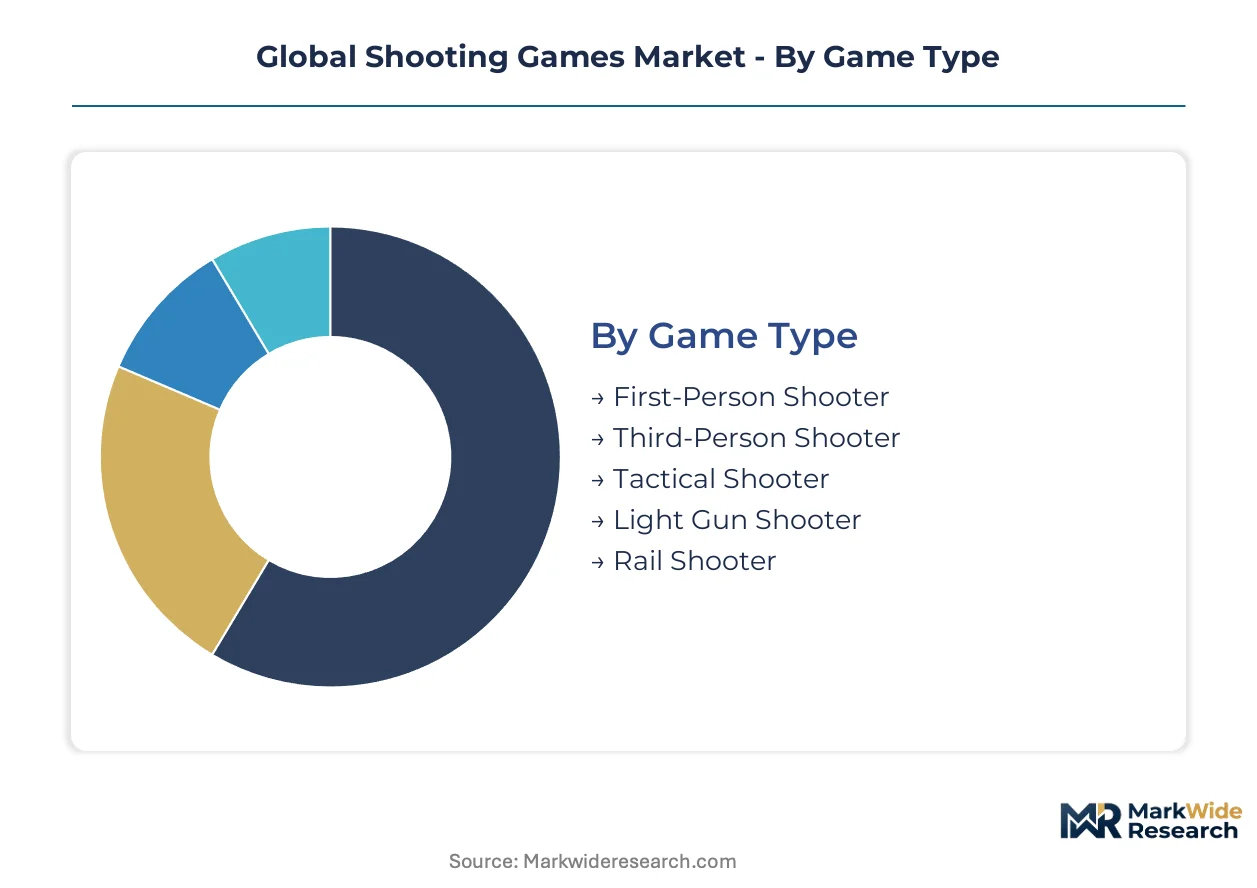
Shooter market segmentation reveals divergent monetization physics across platform ecosystems and competitive formats. Publishers calibrate development investment against distinct player engagement patterns and regional hardware penetration curves.
Game Type:
Cost tier differentiation separates mass-market accessibility from specialized competitive depth in shooter design philosophy.
- First-Person Shooter:Camera positioning at eye-level creates immersive spatial awareness through narrow field-of-view constraints. Console and PC ecosystems in the United States and Germany concentrate demand here, driven by esports broadcast infrastructure and peripheral ecosystem maturity.
- Tactical Shooter:Methodical pacing and realistic ballistic modeling emphasize team coordination over reflex speed. Per-user monetization peaks in this category through seasonal battle pass architectures and limited cosmetic drops.
- Third-Person Shooter:Over-the-shoulder camera angles enable character customization visibility and cover-based movement systems.
- Light Gun Shooter:Arcade-originated peripheral dependency limits addressable market to specialized hardware installations and retro gaming segments.
- Rail Shooter:On-rails movement automation reduces input complexity, concentrating demand in casual mobile deployments and VR onboarding experiences.
First-Person Shooter commands the established base. The steepest expansion runs through Tactical Shooter.
Platform:
Application context determines hardware requirements and revenue recognition timing across shooter deployment channels.
- Mobile:Touch-based input schemes and asynchronous session design accommodate fragmented attention patterns. Southeast Asian markets—particularly Indonesia, Vietnam, and the Philippines—drive volume concentration through smartphone-first internet access.
- Console:Standardized hardware configurations enable optimized rendering pipelines and guaranteed performance baselines. Premium purchase revenue concentrates most densely here, supported by controller ecosystem lock-in and physical retail channel persistence in Japan and the United Kingdom.
- PC:Modular upgrade paths and peripheral customization sustain competitive integrity demands through high refresh rate displays and precision input devices.
- VR Devices:Immersive spatial tracking introduces physical movement requirements that constrain session duration and addressable demographic.
- Cloud Gaming:Low-latency streaming protocols eliminate upfront hardware investment, expanding access in Brazil and India where console penetration remains limited.
Console retains the revenue density advantage. Mobile gains share fastest through emerging market smartphone diffusion.
Monetization Model:
Customer type stratification separates engagement-driven from transaction-driven revenue recognition patterns.
- Free-to-Play:Zero entry price maximizes audience acquisition velocity, with revenue extraction through optional cosmetic and convenience purchases. This model dominates mobile shooter deployment and PC competitive titles, particularly in markets with price-sensitive player bases.
- In-Game Purchases:Microtransaction architectures enable continuous revenue recognition beyond initial acquisition, spanning battle passes, loot boxes, and direct cosmetic sales. Regulatory scrutiny from the FTC and EU consumer protection frameworks intensifies around youth-targeted mechanics.
- Premium Purchase:Upfront transaction model persists in narrative-driven single-player campaigns and annualized sports-shooter hybrids.
- Subscription:Flat-fee access bundling through Xbox Game Pass and PlayStation Plus displaces individual title ownership, especially in urban Australian and Canadian markets.
- Ad-Supported:Rewarded video integration sustains revenue in price-elastic mobile segments without direct player expenditure.
Free-to-Play commands the installed base. In-Game Purchases climb the fastest as live-service architectures mature.
Player Mode:
Volume concentration patterns reflect social engagement preferences and competitive intensity thresholds across shooter audiences.
- Battle Royale:Last-player-standing elimination mechanics scale concurrent user counts through single-match population density. South Korean PC bang culture and Brazilian streaming communities amplify demand concentration here.
- Multiplayer:Persistent server architectures enable matchmaking-based competition across skill tiers, forming the backbone of franchise retention and seasonal content cycles.
- Online Competitive:Ranked progression systems and tournament integration serve esports aspirants and professional pipeline development.
- Co-Op:Cooperative AI opposition reduces competitive pressure, attracting players prioritizing social coordination over adversarial skill expression.
- Single-Player:Narrative-driven campaigns and bot-match options accommodate players with limited connectivity or preference for scripted challenge.
Multiplayer retains the core engagement base. Battle Royale expands most quickly through streaming platform amplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Southeast Asian players gravitate toward mobile-first battle royale formats with compressed session design. German and US markets sustain premium console and PC ecosystems with hardware peripheral integration. Chinese demand flows through state-approved domestic titles with modified monetization architectures.
United States
Esports broadcast infrastructure and peripheral ecosystem maturity drive First-Person Shooter demand. The FTC intensifies scrutiny of youth-targeted microtransaction mechanics. Los Angeles and Seattle anchor competitive league headquarters and streaming platform operations.
China
Smartphone-first internet access and social platform integration sustain massive concurrent user bases. The NMPA maintains stringent content approval queues that compress publisher release velocity. Shenzhen and Beijing host the dominant domestic publishers adapting titles for regulatory compliance.
Germany
PC peripheral customization and high-refresh-rate display adoption support competitive integrity demands. The GDPR imposes escalating data governance obligations on live-service operators processing youth player information. Cologne anchors major trade exhibition infrastructure for publisher announcements.
South Korea
PC bang culture and dedicated esports venue build-out accelerate professional league formation. The MFDS framework intersects with telecommunications policy on youth engagement duration. Seoul and Busan multiply training facilities and broadcast production clusters.
Brazil
Streaming community amplification and mobile shooter adoption outpace console penetration. ANVISA and telecommunications frameworks demonstrate openness to imported interactive entertainment. São Paulo anchors regional server deployment and Portuguese localization operations.
Global Shooting Games Market Competitive Landscape
Capability concentration sits with specialized engine developers and anti-cheat architects; scale advantage sits with platform-integrated publishers with distribution infrastructure. The competitive set stratifies into three tiers: multinational publishers with annualized franchise cycles, Asian platform operators with regulatory adaptation expertise, and independent studios with modding ecosystem leverage. Dominant competitive moves include exclusive platform partnerships and live-service infrastructure acquisition.
Within the multinational publisher tier, Activision Blizzard and Electronic Arts exemplify annualized development cycles and esports league ownership. Tencent Holdings occupies a position bridging platform distribution dominance with regulatory navigation capabilities in Greater China. Valve Corporation anchors PC-based competitive ecosystems through workshop modding tools that extend title longevity beyond standard release windows.
| Leading Market Players |
|---|
| Activision Blizzard |
| Electronic Arts |
| Tencent Holdings |
| Ubisoft |
| Epic Games |
| Valve Corporation |
| Rockstar Games |
| Nexon |
| NetEase Games |
| Others |
Supply & Pricing Matrix
Shanghai-Singapore maritime freight corridors transmit server hardware cost volatility directly into live-service shooter infrastructure economics, compressing margins for publishers dependent on Asian data center clusters while amplifying price differentiation between premium console experiences and mobile-first deployments.
Pricing Analysis
Long-term offtake contracts for cloud infrastructure anchor live-service shooter economics, with spot-market bandwidth procurement creating margin fragility during peak concurrent user events. Three-tier pricing structure across premium battle passes, standard seasonal content, and economy cosmetic tiers separates committed esports competitors from casual mobile players. Cost compression in mobile advertising-supported tiers intensifies because platform commission structures consume forty percent of gross revenue. Emerging market smartphone users exhibit highest price sensitivity; console ecosystem veterans demonstrate lowest sensitivity due to hardware sunk costs and peripheral ecosystem lock-in.
Supply Chain Analysis
Extended payment terms from Taiwanese semiconductor foundries and supply-chain finance facilities from Singaporean logistics providers sustain hardware procurement cycles for console manufacturers. China, Taiwan, and South Korea concentrate graphics processing unit fabrication and memory module production. Raw material dependencies span rare earth elements for magnet assemblies, high-purity silicon for chip fabrication, and cobalt for battery chemistry in mobile devices. Single-source vulnerability in advanced node semiconductor manufacturing creates systemic exposure. Distribution runs through platform-holder digital storefronts with physical retail channel persistence in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shooting games market enters a cyclical recovery phase as live-service monetization architectures mature and esports broadcast infrastructure investment accelerates through dedicated venue construction in Seoul and Busan.
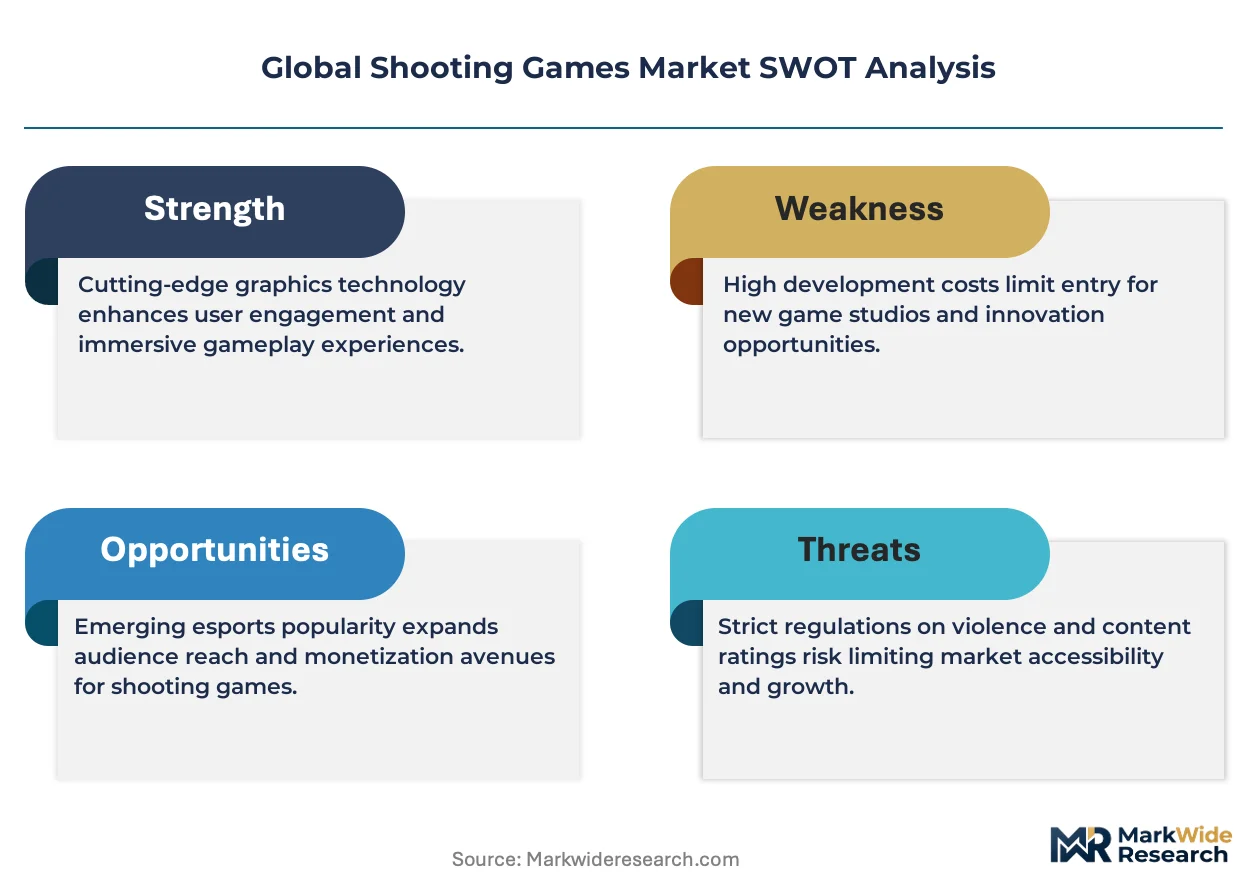
For Market Incumbents: Insulate competitive positioning through exclusive platform partnerships and anti-cheat technology acquisition, addressing the talent scarcity threatening competitive integrity. Kernel-level detection system development represents the critical defensive lever against emerging cybersecurity boutiques. For New Entrants and Emerging Players: India's underpenetrated mobile shooter base against massive smartphone install volume represents the most penetrable entry point for first-mover positioning. Localized payment integration and Hindi-language content production unlock access before domestic publishers consolidate control. For Investors and Strategic Acquirers: Specialized anti-cheat engineering studios with kernel-level detection expertise offer the highest acquisition value within the five-to-ten-year viability window. Regulatory approval velocity for Chinese content releases serves as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Service Infrastructure Acquisition | Anti-cheat technology from kernel-level specialists secures competitive integrity for tournament organizers. |
| Exclusive Platform Partnership | WeGame distribution anchoring accelerates regulatory-compliant release velocity across Greater China. |
| Esports Venue Construction | Seoul and Busan training facilities multiply broadcast production capacity for professional league formation. |
| Localized Content Production | Hindi-language deployment and UPI payment integration unlock India's smartphone-first player base. |
| Cloud Gaming Distribution | Low-latency streaming protocols eliminate hardware barriers for Brazilian and Indian market penetration. |
Research Methodology
Cross-validation between publisher financial disclosures and platform-holder revenue reporting anchors the qualitative findings. Primary interviews with esports tournament organizers, live-service operations directors, anti-cheat engineering leads, and Southeast Asian distribution partners combine with secondary validation against SEC 10-K filings, NMPA approval databases, Steam concurrent user metrics, and mobile platform analytics. Bottom-up title-level revenue estimation and top-down platform revenue triangulation establish analytical coherence.
Calibration against historical release velocity and concurrent user trajectories shapes the projection framework across the analysis window. Segmentation dimensions span game type, platform ecosystem, monetization architecture, and player competitive mode. CAGRs derive from installed base diffusion curves and per-user monetization maturation patterns. Cloud gaming latency benchmarks and mobile data pricing elasticity serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency volatility and energy pricing for European data center operations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and platform commission structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Europe Spectator Sports Market
Sports & Fitness
Global Inflatable Outdoor Leisure Product Market
Sports & Fitness
Wellness Services Market
Sports & Fitness
Surfing Boards Market
Sports & Fitness
Smart Insole Market
Sports & Fitness
Hydration Supplement Market
Sports & Fitness
Skiing Equipment Market
Sports & Fitness
China Sports Optic Market
Sports & Fitness
Slam Ball Market
Sports & Fitness
Trekking Poles Market
Sports & Fitness
United States Archery Equipment Market
Sports & Fitness
Sports Team and Clubs Market
Sports & Fitness
Tennis Equipment Market
Sports & Fitness
Padel Court Operator Market
Sports & Fitness
Smart Fitness Market
Sports & Fitness
GCC Weight Management Market