
 Wellness Services Market | 2026-2036
Wellness Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wellness Services Market Outlook
Subscription-based leasing of wellness platforms is rewriting competitive dynamics, lowering capital barriers for mid-sized providers. Personify Health leverages employer channel control to sustain recurring revenue streams. EXOS anchors performance-focused coaching for military and athletic clients. Headspace Health differentiates through digital mental health integration with insurance networks.
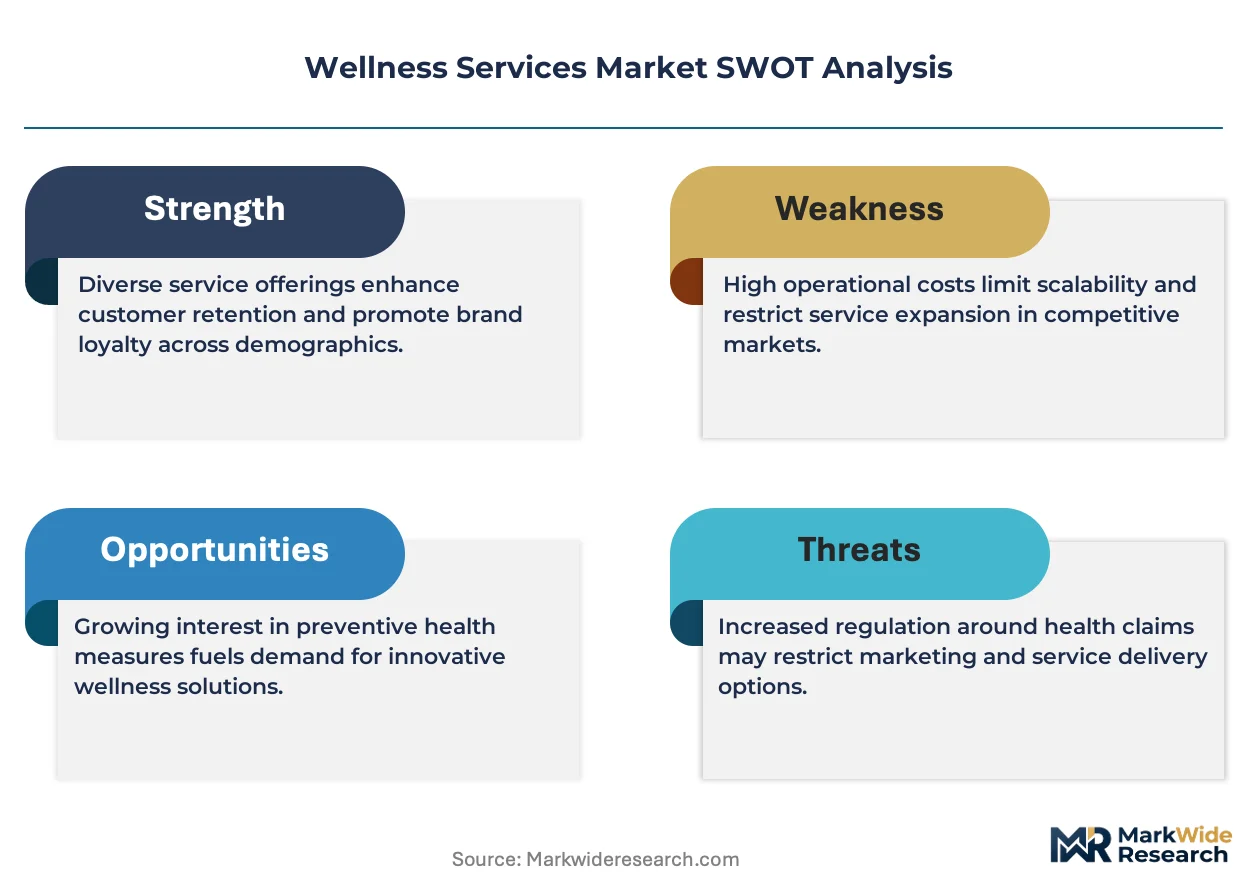
Wellness services encompass structured interventions promoting physical, mental, and behavioral health through personalized coaching, therapeutic touch, nutritional guidance, and movement-based programming delivered across physical and virtual channels. Service providers combine biometric assessment, behavioral psychology, and habit-formation protocols to reduce chronic disease risk and improve functional capacity. Fitness coaching and mental health services command premium pricing due to measurable ROI in employer settings, while massage therapy represents a mature segment with stable margins. Online classes and mobile services are expanding fastest as asynchronous delivery reduces per-session labor intensity and extends geographic reach.
FDA oversight of digital therapeutics and HIPAA privacy mandates constrain how wellness platforms collect and share health data, creating compliance costs that favor scaled operators. The EU AI Act and GDPR impose additional algorithmic transparency requirements on European-deployed mental health apps, fragmenting product development paths. Stakeholders must monitor evolving telehealth licensure rules that determine whether practitioners can serve clients across state or national borders without physical presence.
Market Dynamics
Employer-sponsored wellness programs are consolidating purchasing power around platforms demonstrating measurable productivity ROI, compressing vendor margins while elevating compliance requirements for data handling.
Growth Catalysts
- HIPAA Privacy Mandates:United States employers demand certified platforms, filtering out undercapitalized competitors and concentrating contract flows toward scaled operators with dedicated compliance infrastructure.
- Biometric Assessment Integration:Wearable-derived physiological data streams enable personalized intervention protocols that demonstrably reduce employer insurance premiums.
- Corporate HR Budget Reallocation:Fortune 500 wellness spending now exceeds traditional occupational health line items, redirecting procurement toward integrated mental-physical service bundles.
Market Restraints
- Telehealth Licensure Fragmentation:Practitioners face state-by-state credentialing requirements that prevent cross-border service delivery without physical presence, constraining platform scalability.
- Algorithmic Transparency Costs:EU AI Act compliance forces dual product development tracks for European-deployed mental health applications, elevating R&D overhead.
- Clinical Validation Thresholds:FDA digital therapeutic pathways require randomized controlled trial evidence that asynchronous coaching platforms struggle to generate cost-effectively.
Strategic Opportunities
- Medicaid Expansion Pathways:United States state-level behavioral health carve-outs create reimbursement channels for digital mental health services previously confined to commercial payers.
- Asynchronous Delivery Models:On-demand video libraries and AI-guided protocols reduce per-session labor intensity, extending geographic reach into rural and international markets.
- Performance Coaching Convergence:Military and athletic training methodologies are migrating into corporate wellness contracts, opening premium pricing tiers for specialized providers.
Industry Challenges
- Behavioral Health Practitioner Shortage:Licensed therapist supply constraints limit platform scaling regardless of technology investment, forcing reliance on paraprofessional coaches with narrower scope-of-practice authority.
- Interoperability with Legacy HR Systems:Enterprise wellness platforms must integrate with fragmented benefits administration software, extending implementation timelines and elevating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellness Services Market |
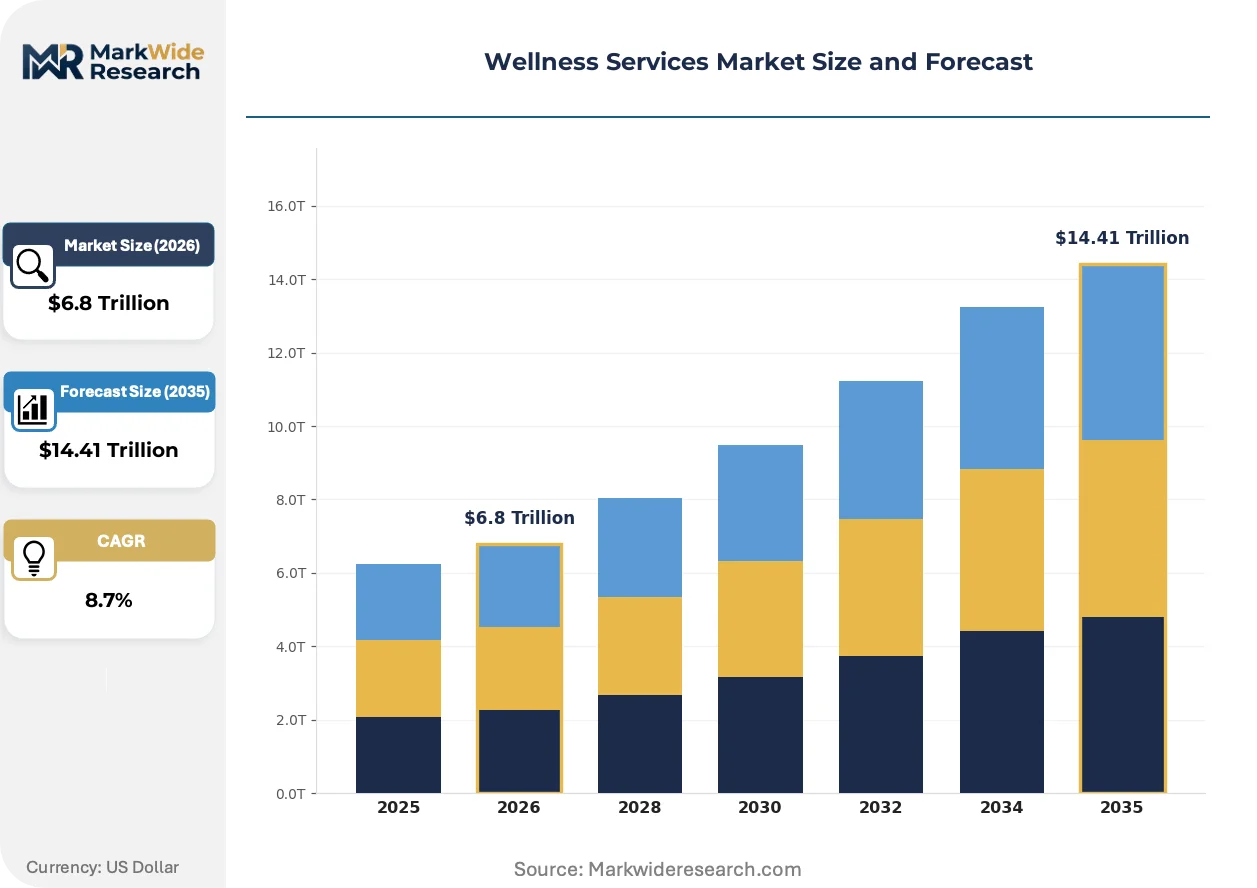
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $14.41 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Massage Therapy, Nutritional Counseling, Yoga Instruction, Fitness Coaching Client Type: Corporate Wellness, Individual Consumers, Group Sessions, Seniors Delivery Mode: In-Person Sessions, Online Classes, Mobile Services, Retreats Wellness Focus: Mental Health, Physical Fitness, Holistic Healing, Preventive Care |
| Companies Covered | Nestlé S.A., Unilever PLC, Procter & Gamble, Bayer AG, Herbalife Nutrition Ltd., ComPsych, Personify Health, EXOS, Headspace Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellness Services Market Strategic Shifts
Digital biomarker capture and AI-guided intervention protocols are compressing the labor component of wellness service delivery while elevating regulatory scrutiny over algorithmic decision-making in health contexts.
Continuous glucose monitoring and heart-rate variability tracking are rendering obsolete episodic biometric screening events that previously anchored corporate wellness program design. Self-insured employers in the United States are adopting these sensor streams for metabolic health cohort management. The shift is rendering obsolete annual health risk assessment contracts that dominated employer procurement through 2020.
GDPR algorithmic transparency requirements and the EU AI Act risk-classification framework impose documentation burdens on European-deployed mental health applications. Vendors must maintain technical files demonstrating human oversight of automated diagnostic suggestions. France and Germany are enforcing these provisions most stringently, with ANSM and BfArM issuing guidance specific to wellness app claims.
Subscription-based platform licensing is displacing per-employee-per-month pricing in mid-market employer segments. Benefits consultants are bundling wellness access with broader health navigation services, compressing standalone vendor margins. This pattern is most visible in United States metropolitan markets where brokerage consolidation has concentrated purchasing influence among three national firms.
Wellness Services Market Segmentation
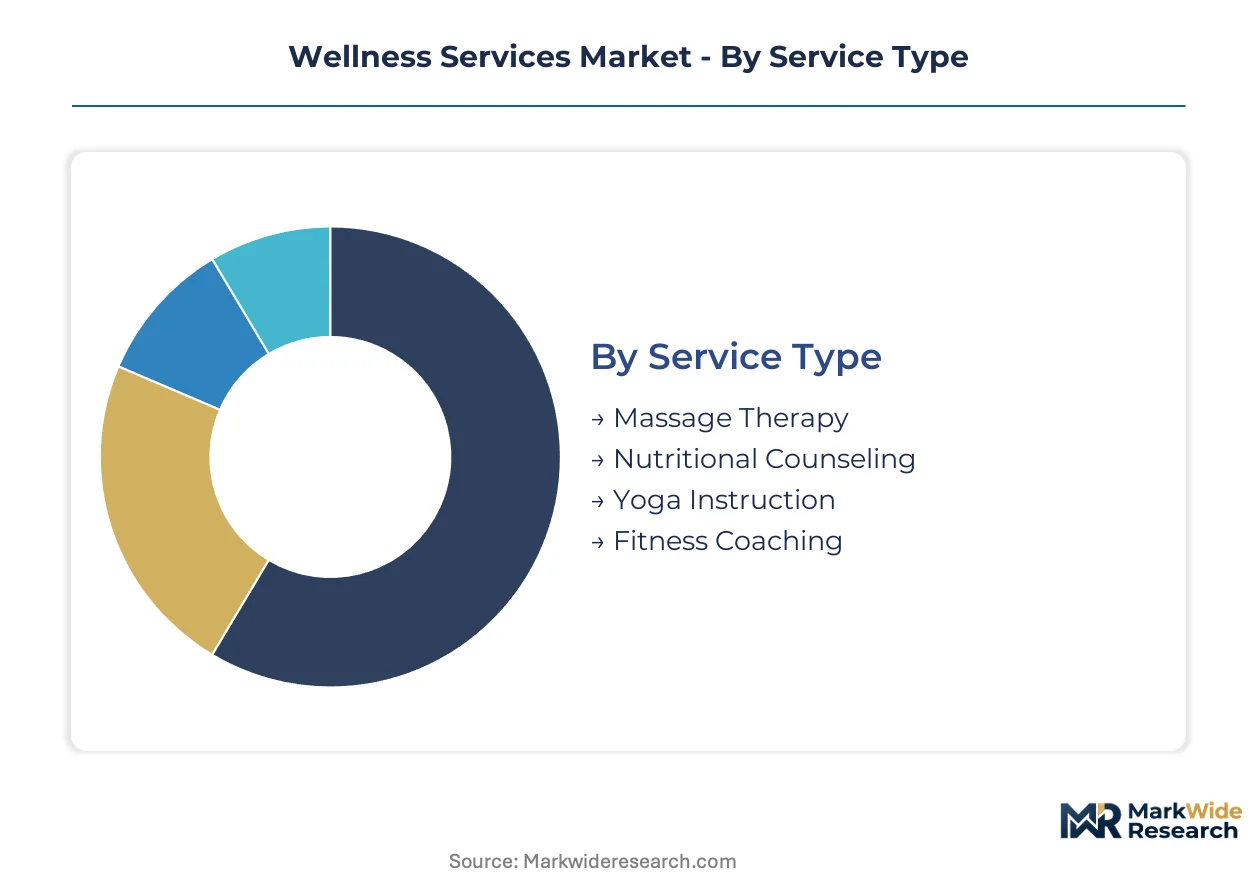
Service differentiation in wellness markets follows distinct procurement logics across employer, consumer, and institutional channels. Each segmentation dimension reveals divergent margin structures, compliance burdens, and scalability constraints that reshape competitive positioning.
Service Type:
Employer procurement concentrates on modalities demonstrating measurable productivity outcomes and insurance premium reductions.
- Fitness Coaching:Structured exercise programming combines biometric assessment with personalized progression protocols. United States Fortune 500 employers drive contract concentration here, prioritizing vendors with validated ROI metrics for reduced absenteeism.
- Mental Health Services:Licensed therapeutic interventions and digital behavioral health platforms address stress, anxiety, and depression. HIPAA-compliant data handling requirements filter vendor eligibility, concentrating purchasing among scaled operators with dedicated compliance infrastructure.
- Massage Therapy:Manual manipulation techniques for musculoskeletal relief represent a mature segment with stable margins and established licensure frameworks across state jurisdictions.
- Nutritional Counseling:Registered dietitian services targeting metabolic health and chronic disease prevention through personalized meal planning and dietary intervention.
- Yoga Instruction:Movement-based mindfulness practices delivered across corporate, studio, and digital formats with lower regulatory barriers than clinical service categories.
The dominant share belongs to Fitness Coaching, while Mental Health Services is closing the gap fastest.
Client Type:
Purchasing power and contract value vary sharply across channel structures, from self-funded employer programs to individual discretionary spending.
- Corporate Wellness:Employer-sponsored programs bundle multiple service modalities under single procurement contracts. These engagements command premium pricing due to demonstrated insurance cost reductions and productivity metrics.
- Individual Consumers:Direct-pay clients purchasing services through subscription models or per-session arrangements. Price sensitivity here exceeds employer channels, compressing margins for standalone providers.
- Group Sessions:Reduced per-participant pricing structures for cohort-based delivery in corporate, community, or educational settings.
- Seniors:Medicare Advantage supplemental benefit carve-outs and age-specific programming targeting mobility maintenance and fall prevention.
Corporate Wellness captures the largest contract value, with Seniors expanding most quickly via Medicare reimbursement pathway expansion.
Delivery Mode:
Channel economics shift dramatically with labor intensity and geographic reach, favoring asynchronous formats for scale.
- Online Classes:Pre-recorded and live-streamed instruction delivered through subscription platforms. Reduced per-session labor intensity enables margin expansion and rural market penetration.
- Mobile Services:Practitioner travel to client locations for in-home or on-site delivery. Premium pricing offsets logistical overhead in metropolitan United States markets.
- In-Person Sessions:Facility-based service delivery requiring physical infrastructure investment and local market density.
- Retreats:Intensive multi-day immersive experiences commanding highest per-client revenue with limited scalability.
Online Classes now lead volume expansion, while Mobile Services sustain premium pricing tiers in dense urban corridors.
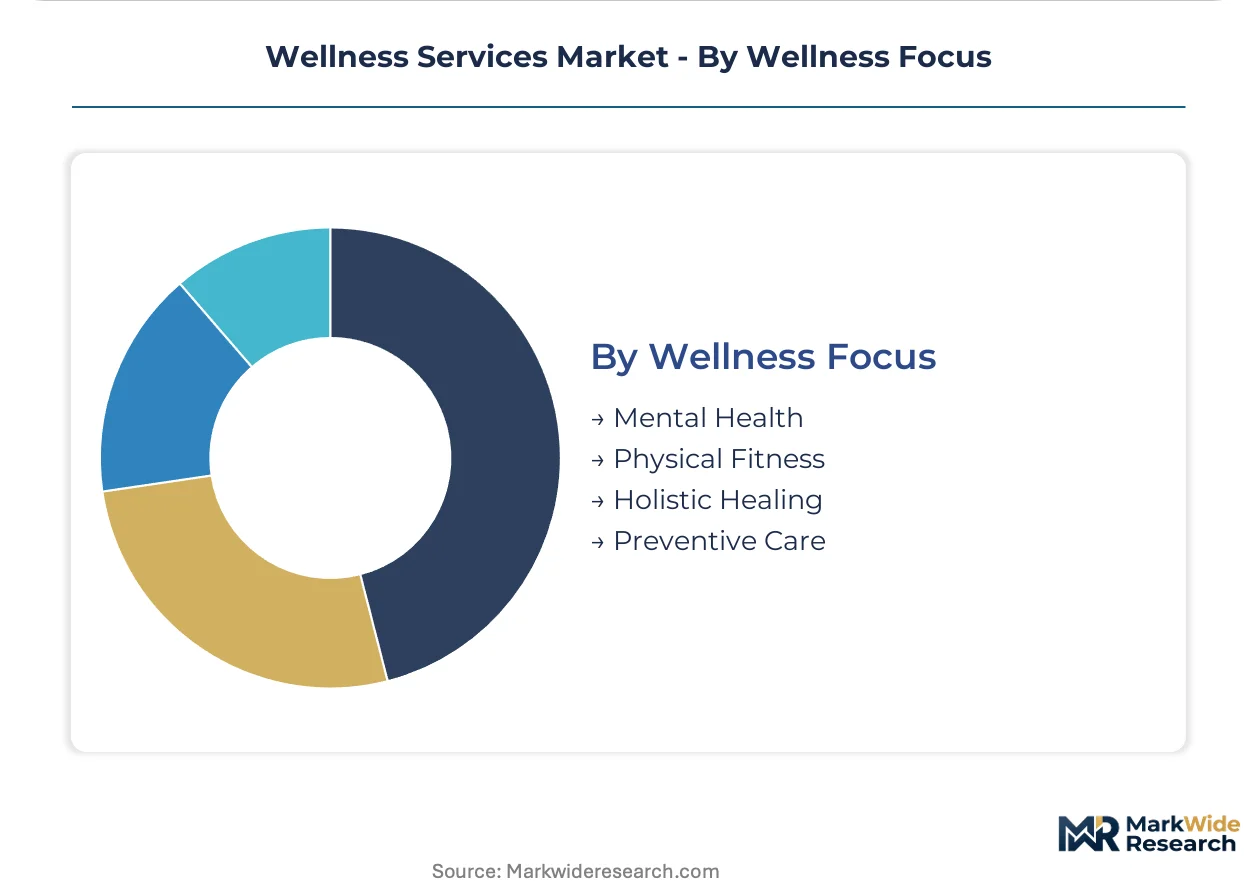
Wellness Focus:
Regulatory classification determines reimbursement eligibility and clinical validation requirements across focus areas.
- Physical Fitness:Exercise and movement protocols with established efficacy evidence for cardiovascular and metabolic health outcomes. Employer procurement favors this category for insurance premium reduction documentation.
- Preventive Care:Risk assessment and early intervention services targeting chronic disease avoidance. FDA digital therapeutic pathways apply to certain biometric monitoring applications in this segment.
- Mental Health:Behavioral and psychological services requiring licensed practitioner oversight. HIPAA and state telehealth licensure rules constrain cross-border service delivery.
- Holistic Healing:Integrative approaches combining multiple modalities with variable regulatory classification across jurisdictions.
Physical Fitness maintains the broadest reimbursement access, though Preventive Care is gaining share fastest through employer biometric screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored purchasing concentrates wellness services demand in economies with mature corporate benefits infrastructure and regulatory frameworks governing health data handling.
United States
Fortune 500 self-insured employers drive contract concentration through productivity-linked procurement. HIPAA mandates filter vendor eligibility toward scaled operators with dedicated compliance infrastructure. The San Francisco Bay Area and New York Metro anchor platform development clusters where benefits technology startups intersect with venture capital.
Germany
Works council co-determination structures shape corporate wellness program design through mandatory employee consultation. BfArM guidance on wellness app claims enforcement creates documentation burdens for algorithmic health tools. Berlin and Munich host concentrated digital health incubator activity alongside established occupational health service providers.
United Kingdom
NHS Long Term Plan integration with employer wellness platforms opens reimbursement pathways for digital mental health services. MHRA oversight of software as medical device classification determines which biometric monitoring tools enter clinical workflows. London's Square Mile and Canary Wharf financial districts generate concentrated demand for executive performance coaching contracts.
Japan
Metabo Check legislation mandating employer waistline screening sustains demand for fitness and nutritional intervention services. METI promotion of Health Management Stock Selection incentivizes listed companies to disclose wellness investment metrics. Tokyo and Osaka metropolitan areas concentrate corporate headquarters procurement authority for national wellness program rollouts.
Australia
Private health insurance premium incentives for wellness program participation drive consumer-facing platform adoption. TGA regulation of medical device software constrains how wearable-integrated coaching platforms position health claims. Sydney and Melbourne corporate park developments anchor on-site wellness facility deployments for professional services employers.
Wellness Services Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments where employer consolidation favors scaled compliance infrastructure. The vendor base organizes into three tiers: multinational consumer goods conglomerates with wellness-adjacent portfolios, dedicated workplace wellness platforms with employer channel dominance, and digital-native mental health applications with insurance network integration. Competitive moves concentrate on strategic partnerships with benefits consultants and asynchronous delivery capability expansion.
Within the employer-platform specialist tier, Personify Health, EXOS, and Headspace Health exemplify divergent positioning archetypes. Personify Health occupies a channel-control position through benefits consultant relationships. EXOS represents performance methodology specialization migrating from athletic and military contexts into corporate contracts. Headspace Health anchors digital mental health integration with payer networks, exemplifying the insurance-coverage-dependent archetype.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever PLC |
| Procter & Gamble |
| Bayer AG |
| Herbalife Nutrition Ltd. |
| ComPsych |
| Personify Health |
| EXOS |
| Headspace Health |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in HIPAA-certified platform engineering across the United States Midwest is compressing implementation timelines and elevating professional services premiums for mid-market employers seeking compliant wellness deployments. This utilization squeeze simultaneously rewards scaled operators with dedicated compliance infrastructure while forcing smaller vendors toward subscription-based licensing models that reduce upfront capital requirements.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with HIPAA-compliant platforms commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by biometric integration depth, practitioner credential tier, and after-sales implementation support. Pricing pressure stems from benefits consultant bundling that compresses standalone vendor margins in metropolitan United States markets. Individual consumers exhibit highest price sensitivity, while Fortune 500 self-insured employers prioritize ROI documentation over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for wearable biometric sensors centers on Taiwan, South Korea, and China, with Foxconn and Pegatron holding dominant assembly capacity for continuous glucose monitoring and heart-rate variability devices. Component sourcing draws from specialized semiconductor foundries in Taiwan for sensor microcontrollers and from Japanese manufacturers for precision optical components. Single-source vulnerability in advanced biosensor chip fabrication creates exposure to geopolitical trade restrictions. Distribution runs through enterprise benefits technology platforms and direct-to-employer sales channels rather than traditional retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level telehealth licensure regimes and Medicaid reimbursement pathways creates protected niches for regionally specialized operators. Employer procurement consolidation around integrated mental-physical bundles simultaneously opens white-space for asynchronous delivery specialists.
For Market Incumbents: Pre-empt platform commoditization by deepening practitioner network exclusivity in underserved United States states where telehealth licensure barriers deter national competitors. Invest in backward integration into biometric sensor data pipelines to reduce dependency on third-party wearable APIs. Consolidate benefits consultant relationships before brokerage concentration completes in remaining metropolitan markets. For New Entrants and Emerging Players: Build out asynchronous coaching infrastructure targeting rural United States counties where synchronous practitioner delivery remains economically unviable. Medicare Advantage supplemental benefit carve-outs for seniors represent the most penetrable reimbursement channel. Position through direct employer contracting bypassing benefits consultant gatekeepers to preserve margin. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among employer-platform specialists with multi-year contracts and integrated data handling infrastructure. Five-to-ten year viability hinges on regulatory compliance scalability rather than technology differentiation alone. Monitor state Medicaid behavioral health carve-out expansion rates as the primary inflection signal for digital mental health reimbursement runway.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Compliance Infrastructure Investment | Dedicated compliance teams filter vendor eligibility toward scaled operators with Fortune 500 access. |
| Asynchronous Delivery Platform Development | On-demand video libraries reduce per-session labor intensity and extend rural geographic reach. |
| Benefits Consultant Partnership Consolidation | Brokerage concentration in United States metros elevates channel control for preferred platform vendors. |
| Biometric Sensor Data Pipeline Integration | Wearable-derived physiological streams enable personalized protocols that reduce employer insurance premiums. |
| Medicaid Reimbursement Pathway Expansion | State-level behavioral health carve-outs open public payer channels previously confined to commercial markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with corporate wellness directors, benefits consultants at national brokerage firms, licensed behavioral health practitioners, and platform product managers. Secondary validation drew from HIPAA enforcement action databases, FDA digital therapeutic guidance documents, state telehealth licensure rule filings, and employer benefits expenditure surveys. Bottom-up service volume estimates triangulated against top-down employer spending aggregates across the analysis window.
Calibration against historical contract values and disclosed platform pricing anchored the projection framework. Segmentation dimensions modeled encompass service type, client archetype, delivery mode, and wellness focus area, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from trend extrapolation of employer procurement patterns and reimbursement pathway expansion rates, incorporating biometric technology adoption curves and practitioner supply constraints as wellness-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by multinational consumer goods conglomerates or accelerated FDA digital therapeutic reclassification would shift outcomes materially. Quarterly review of state Medicaid behavioral health carve-out announcements and benefits consultant M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Trekking Poles Market
Sports & Fitness
Smart Breathing Trainer Market
Sports & Fitness
Surfboard Market
Sports & Fitness
Golf Club Market
Sports & Fitness
Personal Exercise Mats Market
Sports & Fitness
Australia and New Zealand Corporate Wellness Market
Sports & Fitness
Inflatable Sleds Market
Sports & Fitness
UAE Horse Riding Equipment Market
Sports & Fitness
Bicycle Drivetrain Cassette Market
Sports & Fitness
Gym Mats Market
Sports & Fitness
Winter Sports Equipment Market
Sports & Fitness
Global Water Bikes Market
Sports & Fitness
Snorkeling Market
Sports & Fitness
Global Personal Watercraft Market
Sports & Fitness
Stadium Seating Market
Sports & Fitness
North America Sports Drink Market